
 Clothes Fastener Market | 2026-2036
Clothes Fastener Market Size, Share, and Industry Trends Forecast 2026-2036
Clothes Fastener Market Analysis
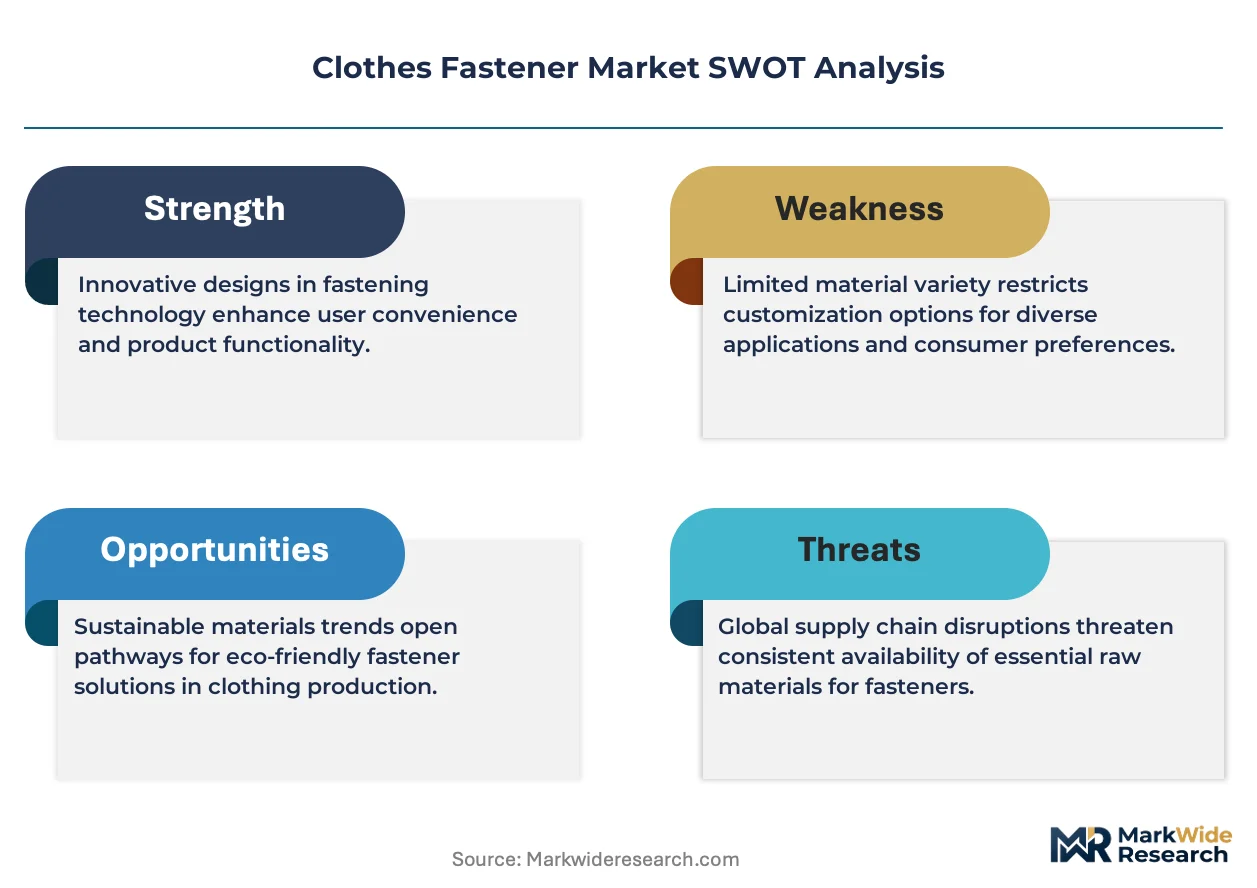
Recycled polyethylene terephthalate is decoupling clothes fastener economics from virgin resin price volatility. Velcro leverages its hook-and-loop patent portfolio to sustain premium positioning in technical apparel. YKK anchors global zipper supply through captive smelting and dyeing operations across Asia.
Clothes fasteners are mechanical or adhesive joining devices engineered to 5–50N shear strength, manufactured through injection molding, die-casting, or weaving processes, serving to enable garment closure, adjustment, and structural integrity in textile products. The zipper segment dominates value pools due to precision metal and coil engineering requirements, while plastic snaps lead volume growth in disposable and children's wear where cost minimization overrides durability specifications. Nylon coil zippers are displacing metal in lightweight outerwear as brands prioritize gram reduction and corrosion resistance.
REACH chemical restrictions in Europe and California's Proposition 65 enforcement in the United States are forcing reformulation of plating chemistries and phthalate-based plasticizers across the supply chain. China's GB standards for child-resistant fasteners and Japan's JIS quality certifications create layered compliance thresholds for export-oriented manufacturers. Stakeholders must monitor biomaterial certification schemes and chemical disclosure platforms as downstream brands harden Scope 3 reporting requirements.
Market Dynamics
Recycled polymer feedstock availability is restructuring procurement economics for garment fasteners, decoupling converter margins from virgin resin price cycles while forcing capital redeployment toward chemical recycling infrastructure.
Growth Catalysts
- EU Green Deal chemical restrictions:Substitution mandates for virgin plastics are accelerating demand for post-consumer recycled content in sportswear fasteners, creating pull-through for certified recycled polyester and polyamide grades.
- Technical apparel expansion:Precision-engineered hook-and-loop systems are penetrating medical and military uniform specifications where wash durability and rapid donning outweigh cost considerations.
- Vietnam's garment export corridor:Concentrated cut-make-trim capacity in Ho Chi Minh City and Dong Nai Province is generating localized demand for just-in-time fastener supply with shorter logistics loops.
Market Restraints
- Metal price volatility:Copper and zinc cost swings in Yiwu and Dongguan smelting clusters compress margin predictability for zipper coil and slider manufacturers locked into annual brand contracts.
- REACH compliance costs:ECHA substance restrictions on nickel release and chromium VI plating chemistries force reformulation investments that smaller electroplaters cannot absorb, consolidating surface treatment capacity.
- Bioplastic performance gaps:Polylactic acid and starch-based alternatives exhibit insufficient creep resistance and moisture stability for load-bearing applications, limiting substitution in outerwear and luggage segments.
Strategic Opportunities
- India's technical textiles push:PLI scheme incentives for man-made fiber and technical textile production are creating domestic fastener demand previously served by Chinese imports, opening regional manufacturing slots.
- Digital product passport mandates:EU CSRD and forthcoming textile EPR requirements will reward converters with blockchain-traceable supply chains, favoring early adopters in chemical disclosure and recycled content verification.
- Automated sewing integration:Vision-guided robotic workstations are converging with ultrasonic welding equipment, enabling direct-to-garment fastener attachment that bypasses traditional sewing subcontractor networks.
Industry Challenges
- Color-matching precision:Dye lot consistency across metal, nylon, and recycled polymer substrates requires spectrophotometric calibration capabilities that mid-tier converters lack, causing rejection rates in brand quality audits.
- GB standard compliance timelines:China's child-resistant fastener testing protocols and Japan's JIS durability certifications impose sequential validation periods that delay new product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothes Fastener Market |
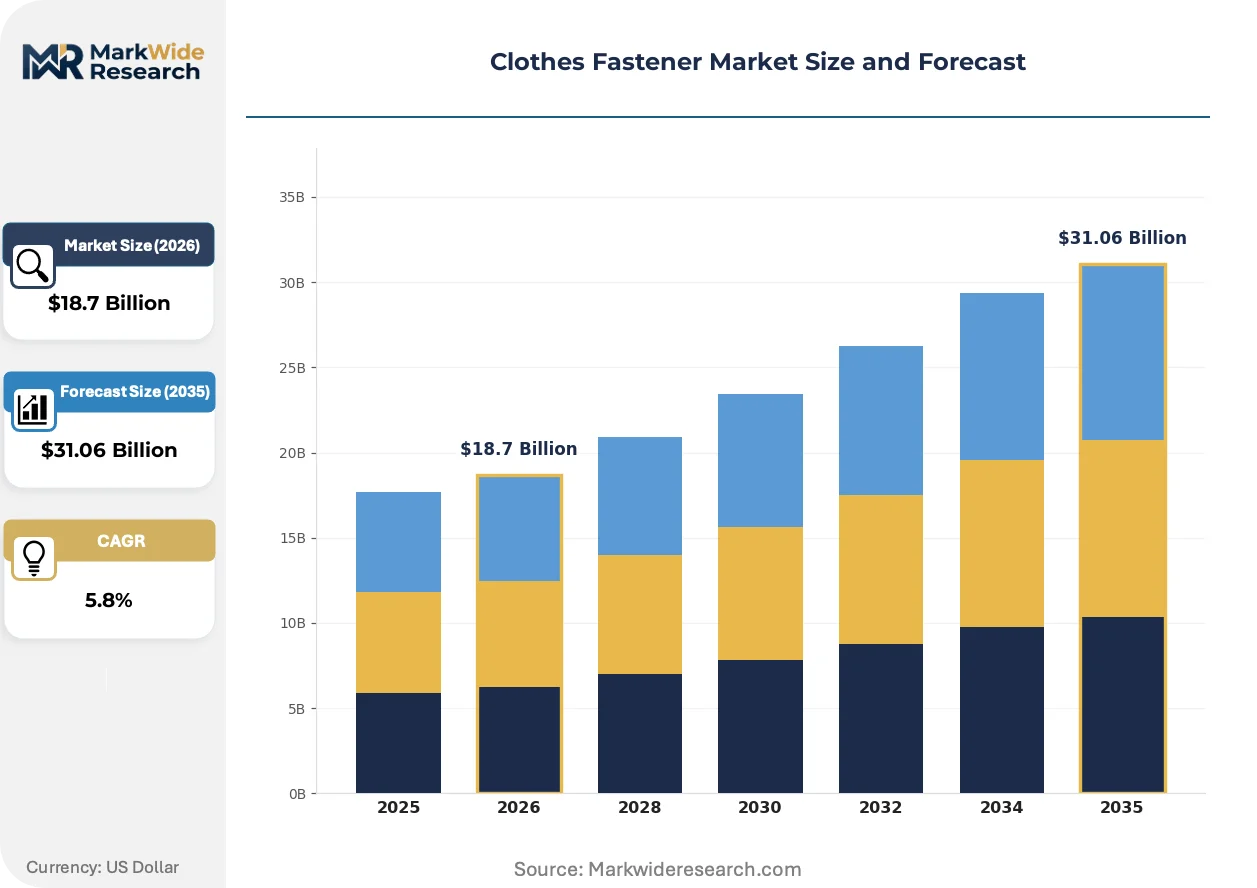
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zippers, Buttons, Snaps, Hooks Material: Plastic, Metal, Nylon, Fabric End User: Apparel Manufacturers, Retailers, DIY Consumers, Textile Industries Application: Clothing, Accessories, Footwear, Bags |
| Companies Covered | APLIX, Binder, Velcro, Morito, Coats Group, 3M, Kuraray Group, Riri SA, YKK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothes Fastener Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure requirements are compressing product development cycles while fragmenting the specification landscape across end-use verticals. Converters must now engineer for multiple compliance regimes simultaneously.
Biobased polyamide 11 derived from castor oil is converging with conventional petroleum-based nylon 6,6 in zipper tape and slider applications. Outdoor brands in Germany and Switzerland are specifying the material for alpine and ski apparel where cold-weather impact resistance matters. This convergence is compressing the premium pricing window for fossil-based technical grades as scale economies emerge.
California's Proposition 65 enforcement against phthalate-containing plasticizers is forcing reformulation of PVC-coated zipper tapes and snap sockets. Manufacturers serving the US market are migrating to citrate and adipate ester alternatives, with compliance costs concentrated in children's wear and intimate apparel categories where skin contact duration is longest.
Direct sourcing from fastener converters is displacing traditional trading company intermediaries among mid-sized European apparel brands. These buyers are building supplier portals for real-time order tracking and carbon footprint verification. The shift is most visible in Denmark and the Netherlands, where B Corp certification requirements mandate Scope 3 supply chain transparency.
Clothes Fastener Market Segmentation
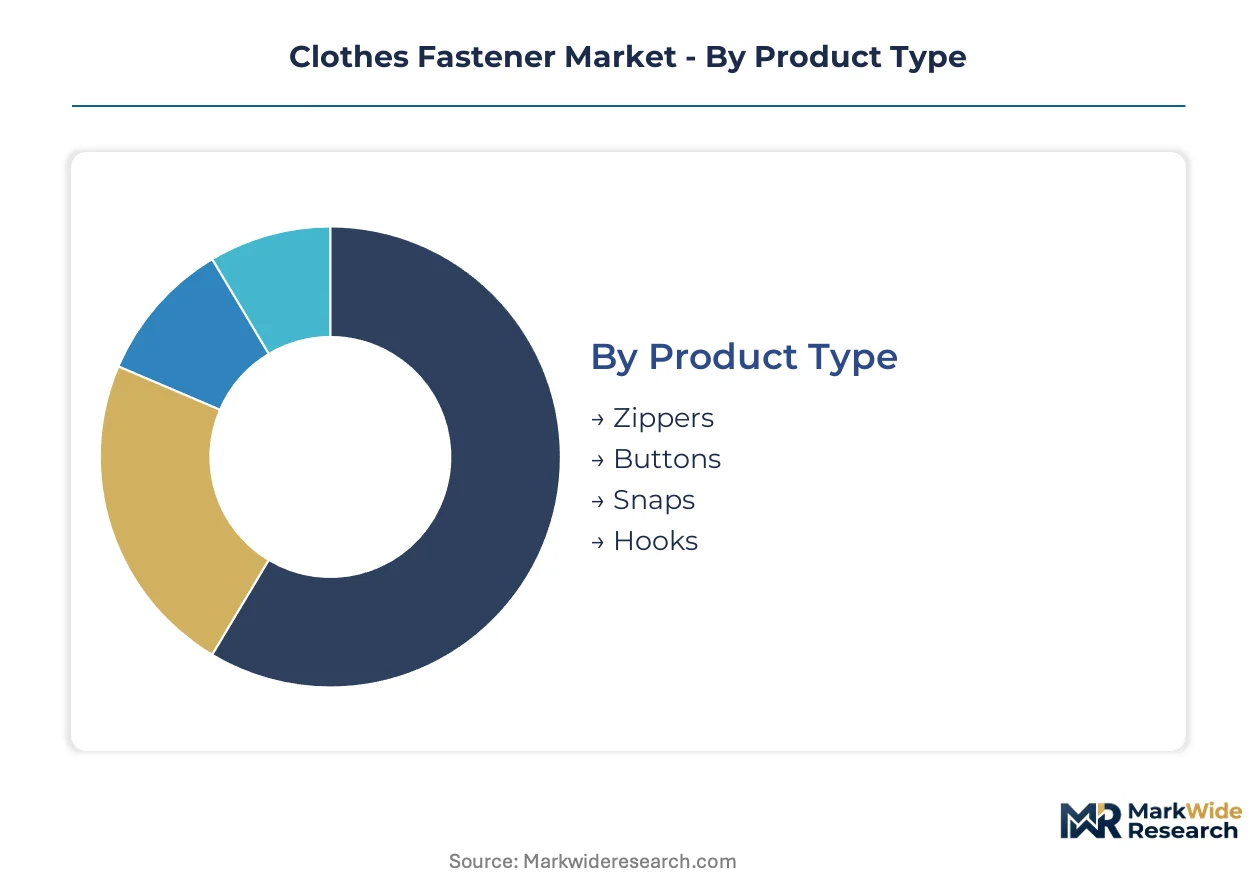
Fastener selection in garment production follows upgrade cycles tied to durability specifications and regulatory compliance. Manufacturers must match material performance to end-use stress loads while navigating chemical disclosure mandates across export markets.
Product Type:
Replacement cycles vary dramatically across fastener categories, with industrial laundries and technical apparel driving shorter refresh intervals than fashion outerwear.
- Zippers:Precision-engineered coil and metal-tooth systems deliver 5–50N shear strength for load-bearing closures. Demand clusters in Vietnam's cut-make-trim corridor where sportswear brands specify corrosion-resistant nylon coil for alpine and marine applications.
- Buttons:Injection-molded polymer and die-cast metal discs attach through sew-through or shank configurations. Fast fashion retailers in Ho Chi Minh City prioritize ultrasonic-compatible designs for automated attachment workflows.
- Snaps:Spring-ring and prong-ring mechanisms enable rapid donning in children's wear and medical uniforms.
- Hooks:Hook-and-loop systems penetrate military and emergency responder specifications where wash durability exceeds 100 cycles.
Volume placements concentrate in Buttons; the faster expansion belongs to Zippers.
Material:
Cost tier differentiation separates commodity feedstocks from certified recycled grades commanding supply chain transparency premiums.
- Plastic:Acetal and polyamide resins dominate disposable apparel through injection molding economies. EU Green Deal restrictions on virgin polymers are accelerating post-consumer recycled PET sourcing for sportswear brands.
- Metal:Brass, zinc, and aluminum alloys provide structural integrity for luggage and outerwear. Copper price volatility in Yiwu smelting clusters compresses margin predictability for annual contract manufacturers.
- Nylon:Polyamide 6,6 and bio-based PA11 from castor oil converge in technical zipper tapes. German and Swiss outdoor brands specify cold-impact grades for ski apparel.
- Fabric:Woven tapes and hook-and-loop substrates enable lightweight adjustment systems in performance wear.
Plastic captures the highest shipment volumes; bio-based alternatives are climbing the fastest.
End User:
Customer type determines specification rigor, with multinational apparel brands imposing chemical disclosure requirements that exclude smaller trading company intermediaries.
- Apparel Manufacturers:Cut-make-trim contractors in Vietnam's Dong Nai Province drive just-in-time procurement for export-bound production.
- Retailers:Mid-sized European brands in Denmark and the Netherlands build direct supplier portals for real-time carbon footprint verification.
- DIY Consumers:Home sewing and repair segments favor retail-packaged assortments through e-commerce channels.
- Textile Industries:Technical textile producers under India's PLI scheme generate domestic fastener demand previously served by Chinese imports.
Apparel Manufacturers absorb the bulk of volume; Retailers are gaining share fastest through direct converter relationships.
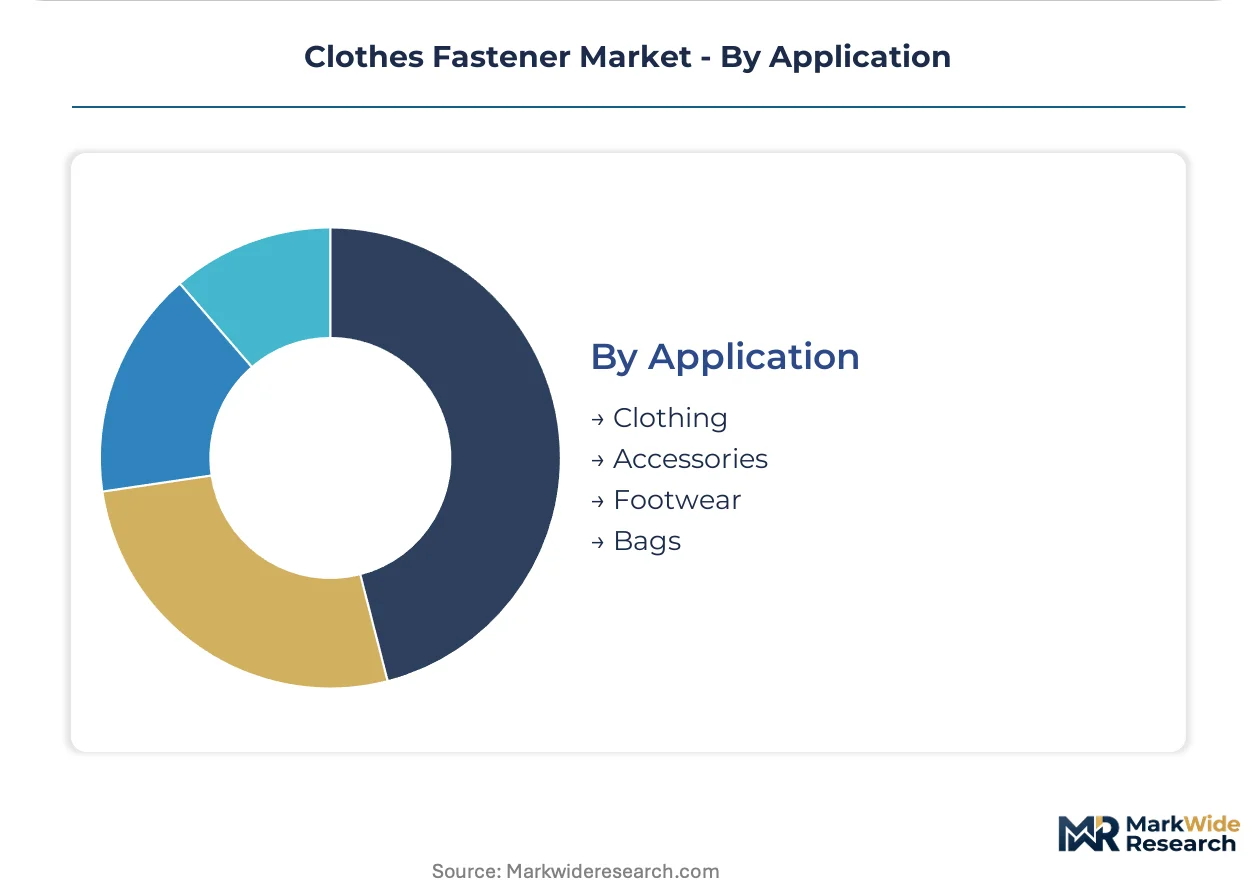
Application:
Maturity gradients separate established clothing applications from emerging specifications in technical accessories.
- Clothing:Shirts, trousers, and outerwear represent the installed base, with REACH nickel release restrictions forcing plating chemistry reformulation across EU-bound production.
- Accessories:Belts, gloves, and headwear require color-matched metal and polymer components. Spectrophotometric calibration capabilities differentiate tier-one converters from mid-tier competitors facing brand audit rejections.
- Footwear:Boot and sneaker closures demand flex-fatigue resistance beyond standard garment specifications.
- Bags:Luggage and backpack segments prioritize load-bearing zipper durability for travel and outdoor use.
Clothing maintains volume dominance; Accessories follow the steepest expansion trajectory as technical specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's garment export corridor concentrates procurement demand for just-in-time fastener supply, while regulatory divergence across major consumer markets forces multi-jurisdictional compliance strategies.
United States
California's Proposition 65 enforcement against phthalate-containing plasticizers drives reformulation of PVC-coated zipper tapes. EPA oversight of electroplating effluents affects metal fastener imports from Asian suppliers. Los Angeles and New York City house technical apparel brands specifying hook-and-loop systems for military and emergency responder contracts.
Germany
ECHA REACH restrictions on nickel release and chromium VI plating chemistries force surface treatment investments. The EU Green Deal accelerates post-consumer recycled polymer sourcing for sportswear fasteners. Outdoor brands in Munich and Hamburg specify bio-based polyamide 11 from castor oil for alpine apparel applications.
China
GB standards for child-resistant fasteners impose sequential validation periods delaying product launches. MIIT dual carbon goals pressure converters toward chemical recycling infrastructure. Yiwu and Dongguan smelting clusters supply brass and zinc alloys for zipper coils, though copper price volatility compresses margin predictability.
Japan
METI and JIS quality certifications create layered compliance thresholds for export-oriented manufacturers. Technical apparel brands in Osaka and Nagoya prioritize wash durability exceeding 100 cycles for medical and military uniform specifications. Domestic converters maintain captive dyeing operations for color-matching precision.
India
PLI scheme incentives for man-made fiber production generate domestic fastener demand previously served by Chinese imports. BIS quality mandates and DGFT trade procedures affect import substitution strategies. Tamil Nadu and Gujarat textile clusters drive regional manufacturing expansion for cut-make-trim operations.
Clothes Fastener Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision-engineered zippers consolidating around vertically integrated metal processors while commodity snaps fragment across injection molding job shops. Three archetypes dominate: patent-protected hook-and-loop specialists, captive smelting zipper manufacturers, and recycled polymer converters. Competitive moves center on backward integration into chemical recycling infrastructure and direct-to-brand supplier portal development.
Among Japanese fabricators, YKK and Morito exemplify scale-driven vertical integration strategies, with YKK representing the captive smelting archetype and Morito occupying a position in diversified fastening systems. Velcro anchors the patent-protected specialty tier among US-based players, its hook-and-loop portfolio sustaining premium positioning in technical apparel specifications. APLIX and Riri SA sit within the European precision-manufacturing cluster, with Riri exemplifying Swiss-Italian metal engineering heritage in luxury zipper applications.
| Leading Market Players |
|---|
| APLIX |
| Binder |
| Velcro |
| Morito |
| Coats Group |
| 3M |
| Kuraray Group |
| Riri SA |
| YKK |
| Others |
Supply Flow & Price Mechanics
EU Green Deal chemical restrictions gate qualified supply for premium-tier fastener converters while excluding uncertified competitors from brand procurement portals. REACH-compliant electroplaters and recycled polymer-certified manufacturers command pricing premiums as sportswear brands harden Scope 3 disclosure requirements.
Pricing Analysis
Volume placements in plastic snaps run on thin margins while precision-engineered zippers sustain premium returns. Three-tier pricing structure across certified recycled, conventional technical, and commodity grades separates converters by chemical disclosure depth and dye-lot precision capabilities. Pricing pressure stems from copper and zinc volatility in Yiwu smelting clusters compressing annual contract predictability. Fast fashion retailers in Vietnam exhibit highest price sensitivity; German outdoor brands show lowest sensitivity due to performance specifications.
Supply Chain Analysis
Workforce availability constraints in Dongguan and Ho Chi Minh City are redirecting automated fastener attachment investments toward robotic sewing integration. Supply concentrates in China, Vietnam, and India, with Yiwu and Dongguan anchoring metal coil production and Dong Nai Province hosting cut-make-trim demand clusters. Raw material dependencies center on brass and zinc alloys, polyamide 6,6 resin, and post-consumer recycled PET flake. Single-source vulnerability in electroplating chemistry supply creates consolidation pressure. Distribution runs through direct supplier portals displacing traditional trading company intermediaries among European B Corp-certified brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clothes fastener economics function as a cost-of-compliance story where ECHA REACH nickel release restrictions erect barrier-to-entry moats favoring electroplaters with captive surface treatment investments.
For Market Incumbents: Extend backward integration into chemical recycling infrastructure to secure post-consumer polymer feedstock and decouple from virgin resin cycles. Lock in multi-year plating chemistry reformulation contracts before ECHA expands restricted substance lists. Bioplastic performance gaps in load-bearing applications present temporary defensive positioning against starch-based substitutes. For New Entrants and Emerging Players: Direct-to-brand supplier portals offer the lowest-friction entry path around entrenched trading company networks. Target India's technical textile clusters under PLI scheme incentives where domestic fastener demand outpaces local converter capacity. Lead with blockchain-traceable recycled content verification to satisfy Denmark and Netherlands B Corp procurement mandates. For Investors and Strategic Acquirers: Consolidation among electroplaters unable to absorb REACH reformulation costs is the leading indicator that surface treatment capacity will concentrate among compliant mid-caps. Long-term viability favors converters with captive dyeing operations and spectrophotometric calibration capabilities. Watch for sequential validation delays under China's GB standards as a signal of launch-timeline risk in Asian supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Recycling | Secures post-consumer PET supply for EU Green Deal-compliant sportswear procurement. |
| Automated Sewing Integration | Vision-guided robotic workstations bypass traditional subcontractor networks in Vietnam. |
| Digital Product Passport Deployment | Blockchain traceability satisfies CSRD and forthcoming textile EPR disclosure mandates. |
| Captive Dyeing Operation Expansion | Spectrophotometric calibration reduces rejection rates in brand quality audits. |
| Direct Supplier Portal Development | Real-time carbon footprint verification displaces trading company intermediaries in Europe. |
Methodological Framework
Independent corroboration across fastener converter executives, garment brand procurement leads, and chemical recycling plant managers underwrites the qualitative findings. Primary interviews with cut-make-trim contractors in Vietnam's Dong Nai Province, electroplating facility operators in Yiwu, and technical textile producers under India's PLI scheme combined with secondary validation from customs trade data, SEC filings of listed apparel brands, and ECHA substance restriction announcements. Bottom-up shipment estimates triangulate against top-down brand procurement spend analysis.
Rate-of-change decomposition across product type, material grade, end-user archetype, and application stress-load specifications structures the analytical framework. Segmentation modeling incorporates zipper coil engineering precision, recycled content certification tiers, and regional regulatory compliance clusters. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Forecast inputs include copper price volatility indices and sequential validation timelines for GB and JIS certifications.
The model holds under stable regulatory enforcement intensity; deviation in ECHA substance restriction expansion pace or MIIT dual carbon acceleration would shift supply-side concentration assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Quilt Market
Textile Innovations
Smart Textile Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Global Textile Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Textile Felt Market
Textile Innovations
GCC Textile Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
Handloom Products Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Smart and Interactive Textiles Market