
 Asia-Pacific Textile Market | 2026-2036
Asia-Pacific Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Textile Market Outlook
A capital-intensity divergence between integrated chemical-fiber producers and garment-assemblers is unwinding legacy competitive hierarchies across the Asia-Pacific textile landscape. Toray Industries leverages its upstream polymerization capabilities to capture margin pools in technical textiles. Shenzhou International anchors its position through vertical control over knitting and dyeing operations for global sportswear brands. Shandong Weiqiao Pioneering Group dominates raw cotton and viscose spinning at scale that few downstream rivals can replicate.
Asia-Pacific textiles encompass woven, knitted, and non-woven structures engineered from natural and synthetic filaments with yarn counts ranging from coarse 10 Ne to ultra-fine 120 Ne for varied end-use performance. Technical textiles and apparel command the most dynamic expansion trajectories, with technical applications in geotextiles and medical filtration drawing premium pricing while cotton-based fashion fabrics face margin compression from polyester substitution. Home textiles remains a mature revenue base concentrated among wholesalers serving mass retail channels across India and China.
China's MEE enforces wastewater discharge limits that shutter non-compliant dye houses, while India's BIS mandates fiber-content labeling standards that reshape import compliance costs for regional traders. Bangladesh's Department of Environment and Vietnam's MONRE apply parallel effluent rules that filter market access for smaller finishing operations. Stakeholders must track which regulatory jurisdiction ultimately sets the binding cost floor for cross-border textile supply chains.
Market Dynamics
China's MEE wastewater discharge mandates are forcing dye house consolidation across Shandong and Jiangsu provinces, redirecting finishing capacity toward Vietnam and Bangladesh while elevating compliance costs for mid-scale operators.
Growth Catalysts
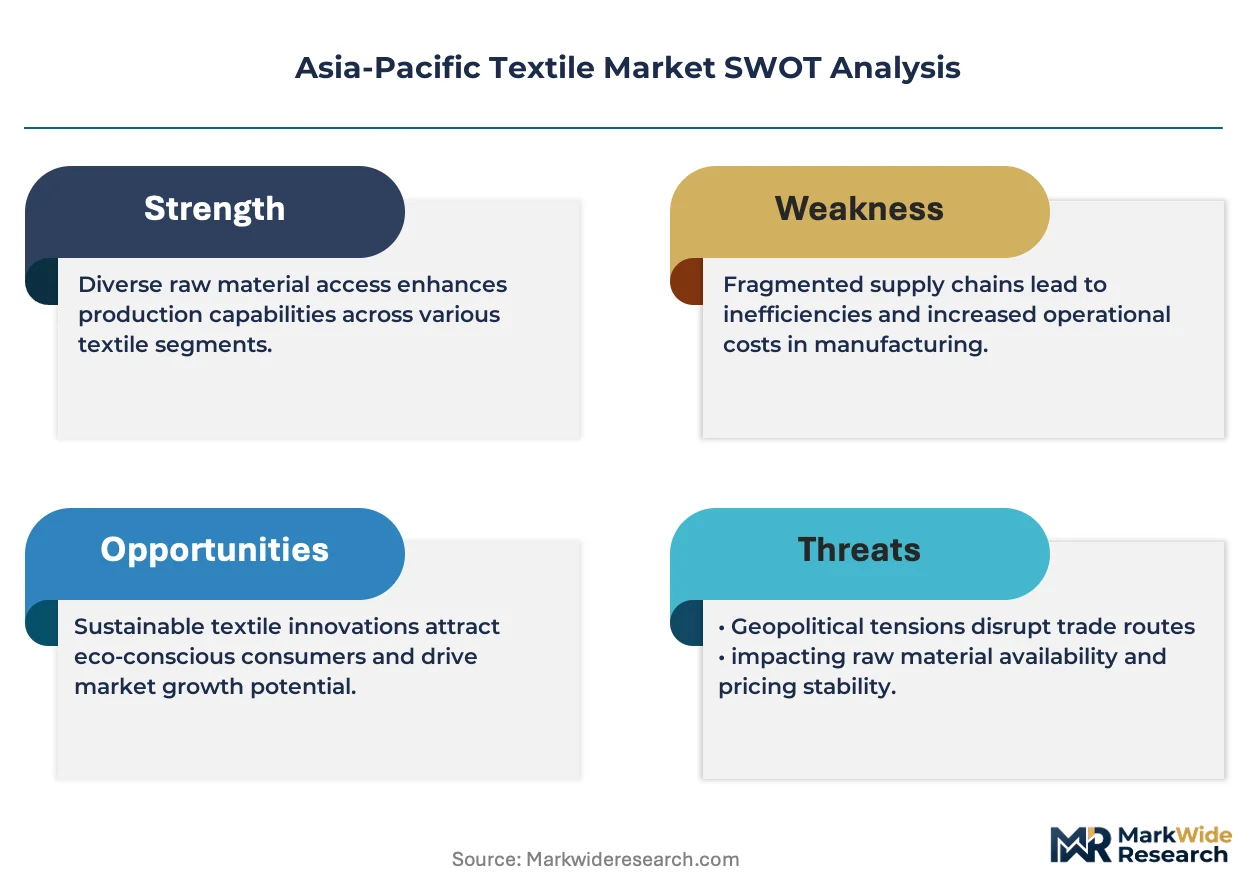
- Technical textile demand:Geotextile and medical filtration applications in Australia and Japan command premium pricing tiers that absorb higher polymer input costs.
- MEE environmental enforcement:China's tightened effluent rules accelerate synthetic fiber sourcing migration to Vietnam, Indonesia, and Bangladesh.
- Polyester substitution:Sportswear brands across Southeast Asia are reformulating cotton-dominant blends toward recycled PET feedstocks.
Market Restraints
- Crude-linked input volatility:PTA and MEG prices oscillate with naphtha spreads, compressing margin visibility for filament producers.
- Single-origin supply risk:Viscose pulp concentration in Indonesian and Indian dissolving-grade facilities creates bottleneck exposure.
- BIS labeling friction:India's fiber-content certification requirements add 6-8 week lead times for cross-border apparel shipments.
Strategic Opportunities
- Vietnam dye house buildout:MONRE-compliant wet-processing parks in Binh Duong and Dong Nai provinces offer greenfield capacity for technical textile finishers.
- PLI scheme alignment:India's production-linked incentive framework for man-made fiber apparel rewards integrated spinning-weaving investments.
- Digital textile printing convergence:Reactive ink chemistry combined with single-pass printer architecture enables micro-batch customization for Australasian fashion e-commerce.
Industry Challenges
- Colorist talent scarcity:Vietnam and Bangladesh face acute shortages of shade-matching technicians capable of meeting sportswear brand color standards.
- Legacy ERP integration:Indonesian weaving cooperatives struggle to connect ISO 9001 quality modules with real-time loom monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Textile Market |
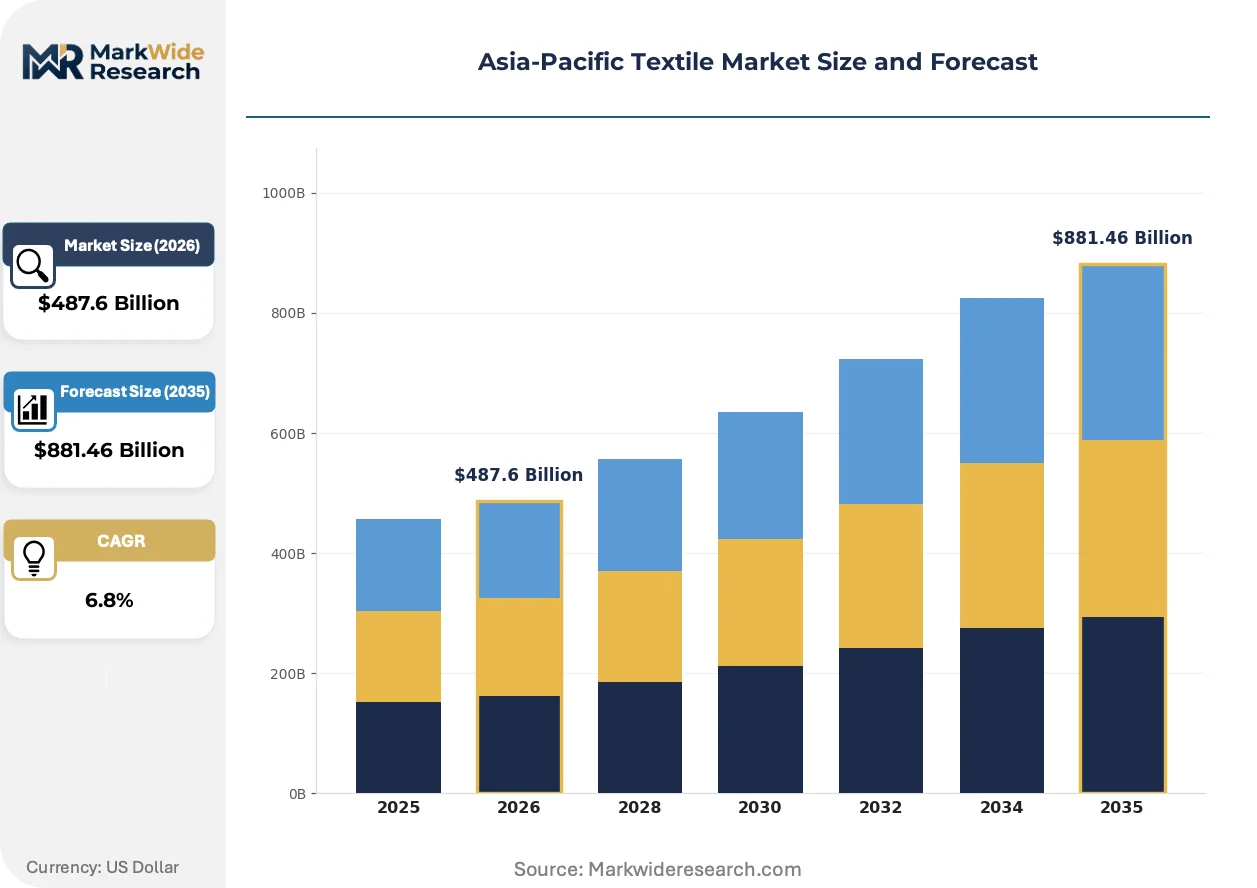
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Home Textiles, Technical Textiles, Fashion Fabrics Material: Cotton, Polyester, Wool, Silk End User: Retailers, Manufacturers, Wholesalers, Exporters Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Toray Industries, Inc., Raymond Group, Shenzhou International Group Holdings Ltd., Shandong Ruyi Technology Group Co., Ltd., Jiangsu Hengli Chemical Fiber Co., Ltd., Shandong Weiqiao Pioneering Group Co., Ltd., Arvind Ltd., HuaFang Group, Texhong Textile Group, Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Textile Market Strategic Shifts
Digital manufacturing architectures and circular feedstock verification systems are restructuring how Asia-Pacific textile producers compete on speed-to-market and sustainability credentials.
Dope-dyed polyester filament is supplanting conventional package-dyed yarn in automotive upholstery and outdoor gear manufacturing. Tier-1 seating suppliers in Thailand and South Korea have converted 60% of their synthetic yarn intake to solution-dyed grades. This shift compresses water and energy footprints while eliminating batch-to-batch shade variation that plagued traditional dye house operations.
China's GB standards for recycled textile content are mandating traceability documentation across filament supply chains. MIIT enforcement of polymer-origin verification creates compliance layering that favors large-scale chemical fiber producers with in-house recycling streams. Apparel exporters targeting the domestic Chinese market now face 15-20% cost premiums for certified recycled inputs versus virgin equivalents.
Direct-to-garment digital printing is eroding rotary screen dominance in Australasian promotional and licensed apparel channels. Sydney and Melbourne-based print-on-demand platforms contract Vietnamese cut-and-sew operators for blank garment supply, compressing traditional wholesaler-distributor hierarchies. This disintermediation is most visible in sub-500 unit runs where colorway flexibility outweighs unit cost minimization.
Asia-Pacific Textile Market Segmentation
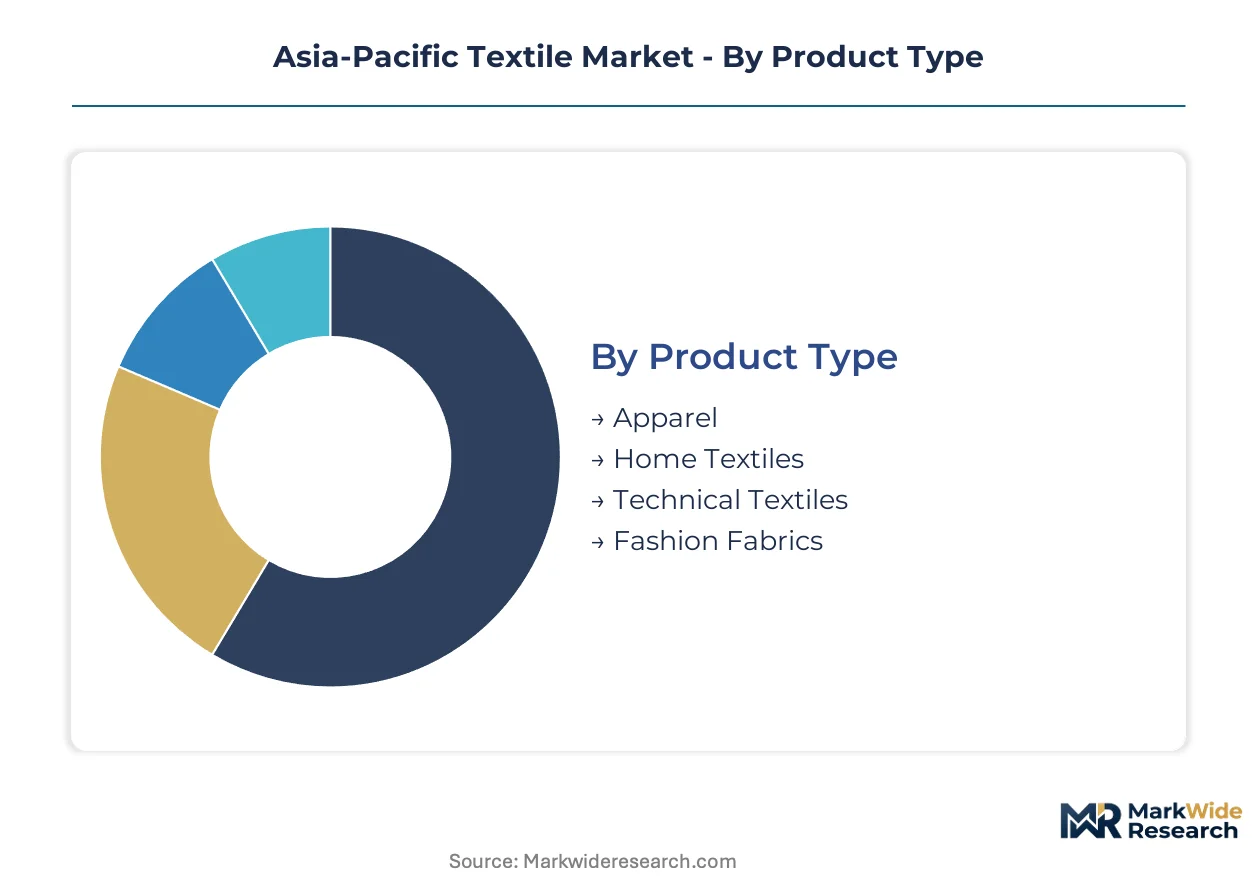
Segmentation reveals how margin pools shift between commodity volume plays and specialty premium positions across Asia-Pacific textile value chains. Material chemistry and end-use application complexity create divergent profitability profiles that reshape competitive investment priorities.
Product Type:
Margin concentration tracks toward technical specifications and compliance intensity rather than pure scale.
- Technical Textiles:Engineered structures incorporating high-tenacity filaments, coated substrates, and composite reinforcements for load-bearing and barrier applications. Australian mining operations and Japanese medical device manufacturers absorb premium pricing for geotextile stabilization fabrics and sterile filtration media, with MEE wastewater mandates elevating compliant supplier scarcity.
- Apparel:Cut-and-sewn garments spanning knit tops, woven bottoms, and outerwear assembled from natural and synthetic inputs. Vietnam and Bangladesh capture the bulk of sportswear brand volume as China's environmental enforcement redirects finishing capacity southward.
- Home Textiles:Bed linens, bath towels, and upholstery fabrics serving mass retail channels across India and China.
- Fashion Fabrics:Seasonal woven and printed materials for designer and fast-fashion collections.
The dominant share belongs to Apparel, while Technical Textiles is closing the gap fastest.
Material:
Cost tier stratification separates virgin polymer feedstocks from recycled and natural alternatives with divergent compliance burdens.
- Polyester:PET and PTT filaments derived from purified terephthalate polymerization, available in virgin, recycled, and dope-dyed grades. Thailand's Tier-1 automotive seating suppliers have converted majority synthetic intake to solution-dyed polyester, eliminating batch shade variation while compressing water footprints under MONRE guidelines.
- Cotton:Staple fiber spun from ginned seed cotton, ranging from coarse 10 Ne carded yarns to fine 60 Ne combed constructions. Shandong Weiqiao Pioneering Group anchors regional supply through captive ginning and spinning scale that downstream rivals cannot replicate.
- Wool:Animal fiber sourced from Australian and New Zealand merino flocks, processed through carbonizing and worsted spinning for suiting and knitwear.
- Silk:Bombyx mori filament reeled from cultivated cocoons, concentrated in Zhejiang and Jiangsu provinces for luxury scarf and lining applications.
Polyester commands volume leadership, though recycled PET grades are expanding most quickly as GB standards enforce polymer-origin verification.
End User:
Procurement sophistication determines supplier qualification depth and contract tenure stability.
- Manufacturers:Integrated spinners, weavers, knitters, and finishers converting fiber to finished fabric. Shenzhou International leverages vertical control over knitting and dyeing to anchor sportswear brand relationships.
- Retailers:Apparel brands and private-label operators sourcing finished garments for direct consumer sale. Australia's digital print-on-demand platforms contract Vietnamese cut-and-sew operators for blank supply, disintermediating traditional wholesale hierarchies.
- Wholesalers:Inventory-holding distributors serving smaller retail accounts across secondary Indian and Indonesian cities.
- Exporters:Trading houses consolidating shipments for cross-border clearance, navigating BIS fiber-content certification delays.
Manufacturers retain the deepest supplier relationships, while Retailers are gaining procurement leverage fastest through direct platform integration.
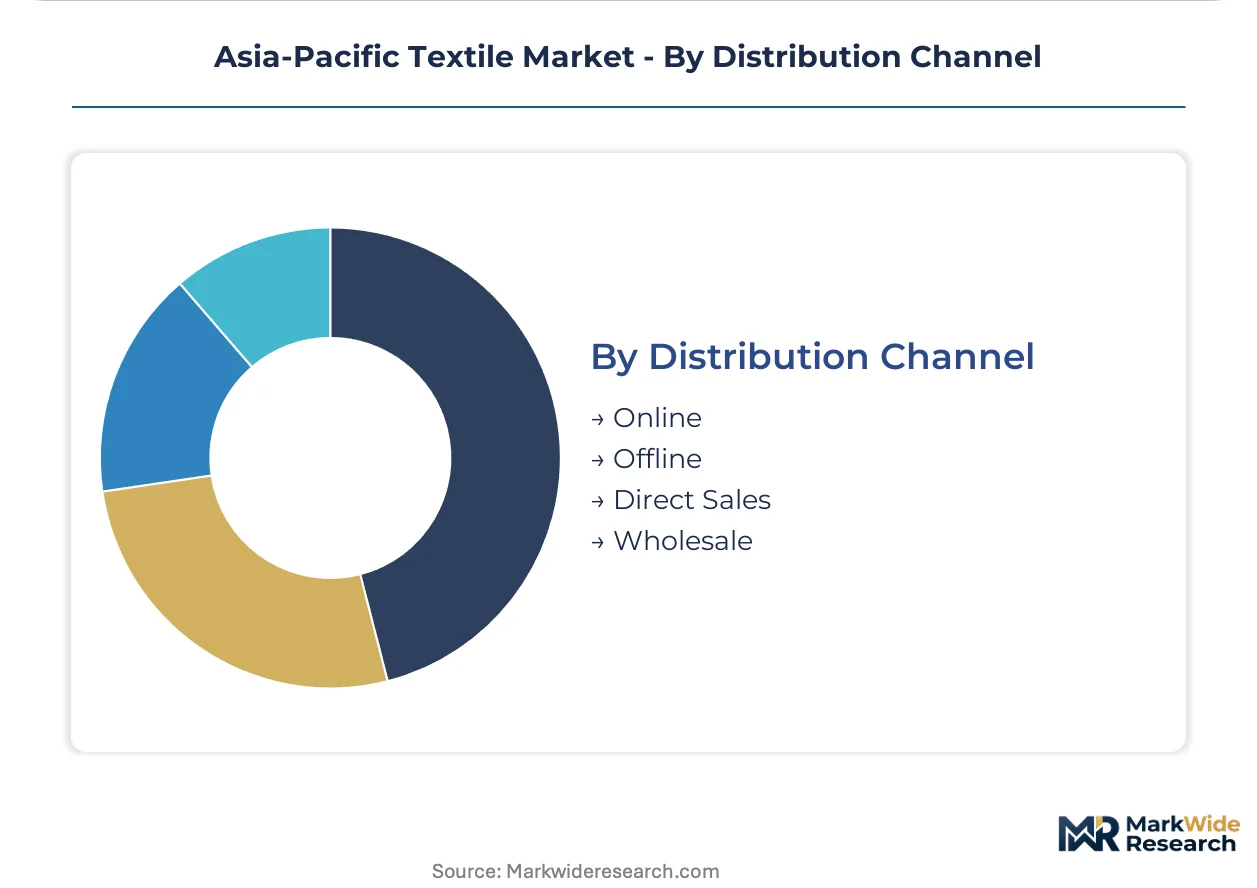
Distribution Channel:
Channel economics hinge on lot size flexibility versus unit cost minimization tradeoffs.
- Wholesale:Volume aggregation through dedicated textile markets and trading companies in Surat, Keqiao, and Jakarta. India's BIS labeling requirements add six-to-eight week lead times that filter smaller trading operations from compliant supply chains.
- Direct Sales:Mill-direct relationships between fiber producers and large apparel manufacturers, bypassing intermediary margins.
- Online:Digital platforms connecting buyers to certified suppliers with traceability documentation for recycled content claims.
- Offline:Physical showroom and exhibition-based sampling for seasonal collection development.
Wholesale still handles majority volume, though Direct Sales is climbing the fastest as brand sustainability audits demand supply chain transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through captive polymerization scale, while Vietnam and Bangladesh compete on wet-processing cost floors reshaped by environmental enforcement migration. This asymmetry drives investment flows toward Southeast Asian dye house infrastructure.
China
Domestic sportswear brands and automotive seating manufacturers absorb the bulk of technical textile output from Zhejiang and Jiangsu provinces. MEE wastewater discharge mandates have shuttered non-compliant dye houses across Shandong, redirecting finishing capacity southward and elevating compliance costs for mid-scale operators still operating within coastal industrial zones.
Vietnam
MONRE-compliant wet-processing parks in Binh Duong and Dong Nai provinces attract synthetic fiber sourcing migration from Chinese coastal provinces. The Department of Natural Resources and Environment enforces effluent standards that filter market access for smaller finishing operations, while Ho Chi Minh City anchors cut-and-sew assembly for global sportswear brands.
Bangladesh
Ready-made garment exporters serving European and North American retail channels drive cotton and polyester blend demand through Dhaka and Chittagong industrial corridors. The Department of Environment applies parallel effluent rules that reshape import compliance costs, with the country's central bank monitoring foreign exchange availability for raw material procurement.
India
BIS fiber-content labeling standards add six-to-eight week lead times for cross-border apparel shipments, filtering smaller trading operations from compliant supply chains. Maharashtra and Gujarat house integrated spinning-weaving investments aligned with PLI scheme incentives for man-made fiber apparel production.
Indonesia
Dissolving-grade viscose pulp concentration in Sumatran and Javanese facilities creates bottleneck exposure for regional rayon supply. The Ministry of Environment and Forestry oversees industrial wastewater parameters that affect textile park licensing in Central Java, while Jakarta-based trading houses coordinate filament distribution across Southeast Asian garment assembly networks.
Asia-Pacific Textile Market Competitive Environment
Concentration sits with integrated chemical-fiber producers possessing captive polymerization and recycling streams. The vendor base stratifies across three tiers: upstream resin and filament specialists, midstream fabric processors with vertical dye house control, and downstream cut-and-sew assemblers competing on lot-size flexibility. Strategic moves center on M&A for polymerization assets and greenfield dye house buildout in Vietnam and Bangladesh to capture compliance-driven capacity migration.
Within the upstream chemical-fiber tier, Toray Industries and Jiangsu Hengli Chemical Fiber exemplify integrated producers leveraging polymerization scale. Shandong Weiqiao Pioneering Group occupies a position among raw material specialists with captive cotton and viscose spinning operations. Shenzhou International represents the midstream fabric processor archetype through vertical control over knitting and finishing for brand relationships.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Raymond Group |
| Shenzhou International Group Holdings Ltd. |
| Shandong Ruyi Technology Group Co., Ltd. |
| Jiangsu Hengli Chemical Fiber Co., Ltd. |
| Shandong Weiqiao Pioneering Group Co., Ltd. |
| Arvind Ltd. |
| HuaFang Group |
| Texhong Textile Group, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Polyester substitution for cotton-dominant blends is redrawing procurement geography across Southeast Asia while compressing margin pools for conventional spinners still wedded to natural fiber processing. China's MEE wastewater enforcement has elevated compliant dye house scarcity premiums, pushing sportswear brands toward Vietnam's MONRE-certified wet-processing parks where solution-dyed filament commands configured-to-order premiums over commodity package-dyed alternatives.
Pricing Analysis
The customization-premium spread separates solution-dyed polyester filament for automotive seating from commodity package-dyed yarn for mass apparel. Three-tier pricing structure across technical certification, standard compliance, and economy grades tracks MEE and MONRE environmental adherence as the primary differentiation driver. Pricing pressure stems from crude-linked PTA and MEG volatility that compresses margin visibility for filament producers. Mid-scale garment assemblers exhibit highest price sensitivity, while Tier-1 automotive seating suppliers absorb premium tiers for shade consistency.
Supply Chain Analysis
Inventory lead times stretch six-to-eight weeks for Indian apparel shipments navigating BIS fiber-content certification requirements. Supply concentrates in China, Vietnam, and Bangladesh, with raw material dependencies on Indonesian and Indian dissolving-grade viscose pulp plus naphtha-derived polymer feedstocks. Single-origin pulp concentration creates bottleneck exposure. Distribution runs through Ho Chi Minh City and Dhaka industrial corridors for cut-and-sew assembly, with Surat and Keqiao trading hubs handling volume aggregation for wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific textiles face high-growth disruption as China's MEE enforcement and GB recycled-content standards simultaneously reshape compliance economics and sourcing geography. Digital textile printing convergence with reactive ink chemistry enables micro-batch customization that threatens traditional rotary screen dominance.
For Market Incumbents: Compound polymerization scale advantages through captive recycling stream investments that satisfy MIIT polymer-origin verification requirements. Defend dye house relationships by acquiring MONRE-compliant wet-processing capacity in Binh Duong province before capacity scarcity elevates lease premiums. Threatened by digital print-on-demand platforms, incumbents must anchor technical textile margins through geotextile and medical filtration specialization.
For New Entrants and Emerging Players: Lead with digital textile printing infrastructure targeting Australasian promotional apparel channels where sub-500 unit runs favor colorway flexibility over unit cost minimization. White-space opportunities sit in recycled PET feedstock verification services and shade-matching technician training programs addressing acute Vietnam and Bangladesh talent scarcity. Go-to-market leverage rests on direct platform integration with Sydney and Melbourne-based print-on-demand operators.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated chemical-fiber producers possessing captive polymerization and in-house recycling streams that absorb GB standard compliance premiums. Long-term viability favors upstream resin specialists over downstream cut-and-sew assemblers facing margin compression from polyester substitution. Signal to monitor: MONRE licensing velocity for greenfield dye house buildout in Dong Nai province as inflection indicator for compliant capacity availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization | Toray Industries and Jiangsu Hengli capture margin pools through captive PTA and MEG supply. |
| Greenfield Dye House Buildout | MONRE-compliant wet-processing parks in Binh Duong attract capacity migration from Shandong province. |
| Recycled Feedstock Certification | MIIT polymer-origin verification creates compliance layering favoring large-scale chemical fiber producers. |
| Digital Printing Platform Integration | Single-pass printer architecture with reactive ink chemistry enables micro-batch Australasian e-commerce fulfillment. |
| Technical Textile Specialization | Geotextile and medical filtration applications command premium pricing from Australian mining and Japanese device manufacturers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, MEE enforcement disclosures, BIS certification records, and SEC filings from listed textile producers. Primary interviews engaged spinning mill operations directors, sportswear brand procurement leads, dye house compliance officers, and trading company logistics managers. Bottom-up capacity assessments across Vietnamese and Bangladeshi industrial parks were triangulated against top-down demand modeling from regional apparel export statistics.
Segmentation dimensions modeled include material chemistry, end-use application complexity, and distribution channel lot-size flexibility across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections incorporating polyester substitution rates and MEE-driven capacity relocation. Industry-specific forecast inputs encompassed dissolving-grade pulp availability from Indonesian facilities and MONRE licensing velocity for wet-processing park development.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement stringency or crude price stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and brand sourcing migration patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Clothes Fastener Market
Textile Innovations
GCC Textile Market
Textile Innovations
Global Textile Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Smart Textile Market
Textile Innovations
Quilt Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Textile Felt Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Digital Textile Printing Market