
 GCC Textile Market | 2026-2036
GCC Textile Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Textile Market Foresight
Multi-source procurement is recalibrating how GCC textile buyers manage supply risk across Egyptian, Indian, and Pakistani mill networks. Aratex Group leverages integrated spinning-to-garment operations across Saudi Arabia to anchor its position in uniform and workwear supply. Saudi German Nonwovens specializes in medical and hygiene nonwoven substrates, competing on polymer-to-fabric control that shields margin from petrochemical volatility. Lomar Collection differentiates through premium modest fashion retail, controlling boutique channels in Jeddah and Riyadh.
Textiles comprise fibrous materials—cotton, polyester, aramid, or their blends—processed through weaving, knitting, or nonwoven bonding to achieve specified tensile strength, abrasion resistance, and flame-retardancy ratings for end-use performance. Technical textiles lead structural growth, absorbing margin from oilfield geotextiles and automotive interior substrates where specification intensity exceeds commodity apparel. Synthetic fibers dominate volume throughput, though blended fabrics gain share in sportswear applications as moisture-wicking cotton-polyester constructions displace pure synthetics in GCC heat-climate athletic wear.
SASO enforces fiber-content labeling and flammability standards that filter non-compliant imports at Saudi ports, while the UAE's Emirates Authority for Standardization and Metrology (ESMA) governs textile safety marking for Dubai re-exports. Gulf Cooperation Council customs union rules harmonize tariff treatment but leave national standards divergence that complicates cross-border inventory planning. Stakeholders must monitor whether Abu Dhabi's industrial free zones or Saudi Arabia's King Abdullah Economic City attract enough spinning and dyeing investment to reduce Asia-dependent lead times.
Market Dynamics
Technical textile specification intensity is compressing commodity margins across GCC states, forcing mills to migrate from volume apparel toward oilfield geotextiles and automotive substrates where polymer-to-fabric control commands pricing power.
Growth Catalysts
- SASO Fiber-Content Mandates:Saudi labeling enforcement is filtering non-compliant imports at Jeddah and Dammam ports, creating captive demand for locally certified spinning operations.
- Automotive Interior Substrates:GCC vehicle assembly growth is absorbing flame-retardant technical fabrics from Saudi German Nonwovens and comparable suppliers with petrochemical backward integration.
- Dubai Re-Export Hub Status:Emirates Authority for Standardization and Metrology (ESMA) marking protocols position UAE as the regional procurement gateway for Egyptian and Pakistani mill networks.
Market Restraints
- Petrochemical Feedstock Volatility:Polymer price swings transmit directly to polyester and polypropylene nonwoven margins, compressing earnings for non-integrated converters.
- Asia-Dependent Lead Times:Dyeing and finishing capacity concentration in India and China exposes GCC garment makers to 90-120 day procurement cycles that conflict with fast-fashion velocity.
- Flammability Standard Divergence:SASO and ESMA maintain non-harmonized testing protocols, forcing dual certification costs on suppliers serving both Saudi Arabia and UAE markets.
Strategic Opportunities
- King Abdullah Economic City:Saudi Arabia's Red Sea industrial zone offers tax-advantaged spinning and dyeing investment to compress Asia-dependent lead times for uniform suppliers.
- Modest Fashion Premiumization:Boutique retail channels in Jeddah and Riyadh are absorbing higher-margin abaya and kaftan constructions with embroidery and beadwork value-addition.
- PLI-Style Manufacturing Incentives:Saudi Industrial Development Fund financing is targeting technical textile capacity for medical hygiene and oilfield applications.
Industry Challenges
- Colorfastness Certification Bottlenecks:SASO laboratory capacity constraints in Riyadh are extending approval timelines for imported fabric lots, freezing working capital.
- Legacy Dyehouse Environmental Compliance:Saudi and UAE effluent discharge rules are forcing capex into water treatment that smaller Pakistani-owned garment workshops cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Textile Market |
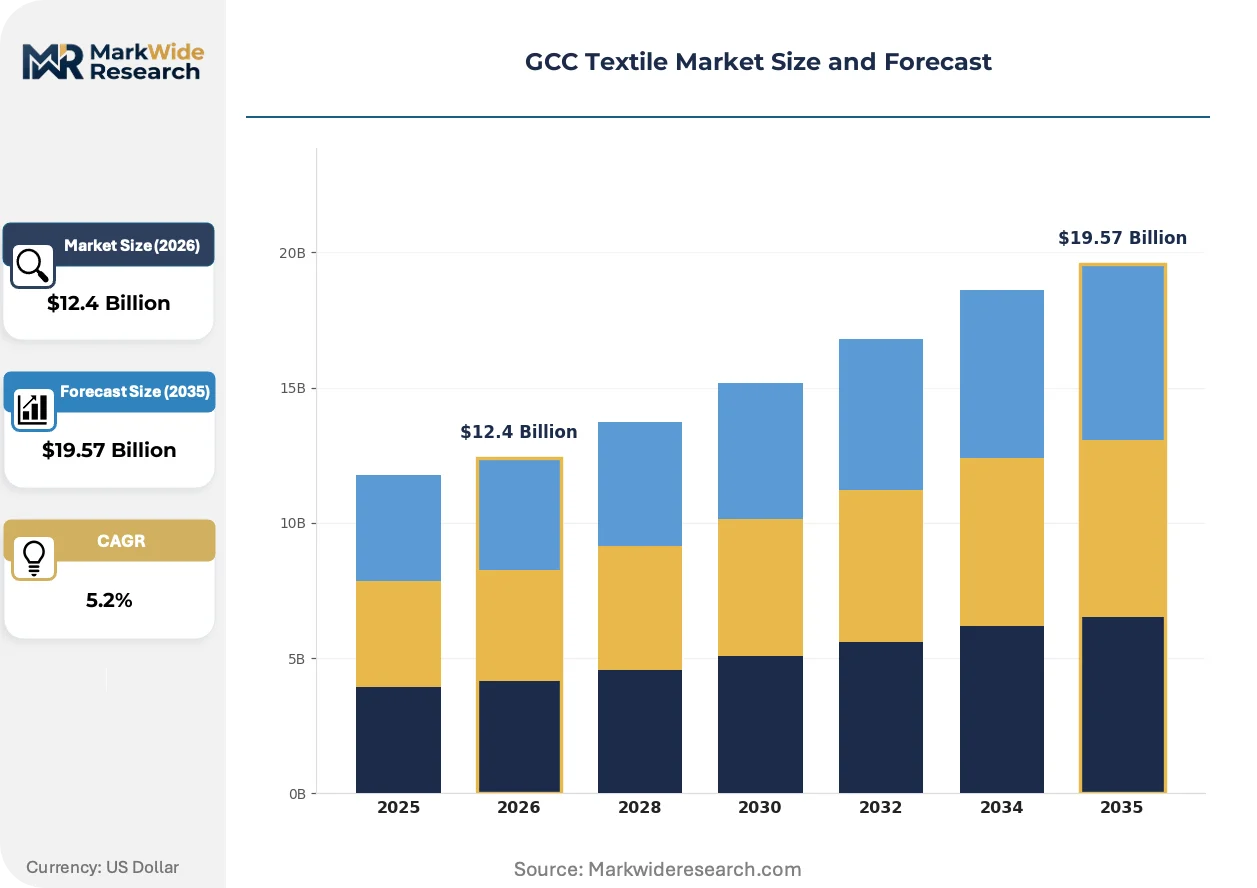
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $19.57 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fibers, Synthetic Fibers, Blended Fabrics, Technical Textiles End Use/Application: Apparel Manufacturing, Home Furnishing, Automotive Interiors, Industrial Fabrics, Sportswear Manufacturing Technology: Weaving, Knitting, Nonwoven, Embroidery, Printing, Dyeing Distribution Channel: Wholesale Distributors, Retail Outlets, Online Platforms, Direct Sales, Dealers |
| Companies Covered | Aratex Group, Saudi German Nonwovens, Alyaf Industrial Co. Ltd., Millennium Fashions Industries, FPC Coated Technical Textiles, SV Pittie Sohar Textiles, Avgol Middle East, Lomar Collection, Takween Advanced Industries, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Textile Market Shifts & Advancements
Digital textile printing and moisture-wicking cotton-polyester blends are displacing conventional wet-processing and pure synthetic constructions across GCC heat-climate applications.
Digital sublimation printing is overtaking rotary screen methods for short-run modest fashion and corporate uniform orders. Saudi boutique brands and UAE hospitality suppliers are adopting on-demand colorways with sub-72-hour turnaround. This compression of minimum order quantities is fragmenting volume concentration among legacy Indian mill relationships.
SASO's 2024 technical textile labeling amendments are tightening fiber-content disclosure and origin documentation for Saudi imports. The industrial consequence is a documentation burden that favors vertically integrated Saudi spinning-to-garment operations over trading-house intermediaries. Medical nonwoven and automotive substrate categories are responding with captive laboratory testing investments to preempt port-of-entry delays.
Regional procurement desks are consolidating supplier panels from fragmented South Asian mill networks toward audited Egyptian and Turkish partnerships with ESMA pre-certification. Dubai-based trading houses are losing share to direct mill relationships as Saudi and UAE retail chains enforce supplier reduction programs. This concentration is most visible in Riyadh-based hypermarket private-label apparel sourcing.
GCC Textile Market Segmentation
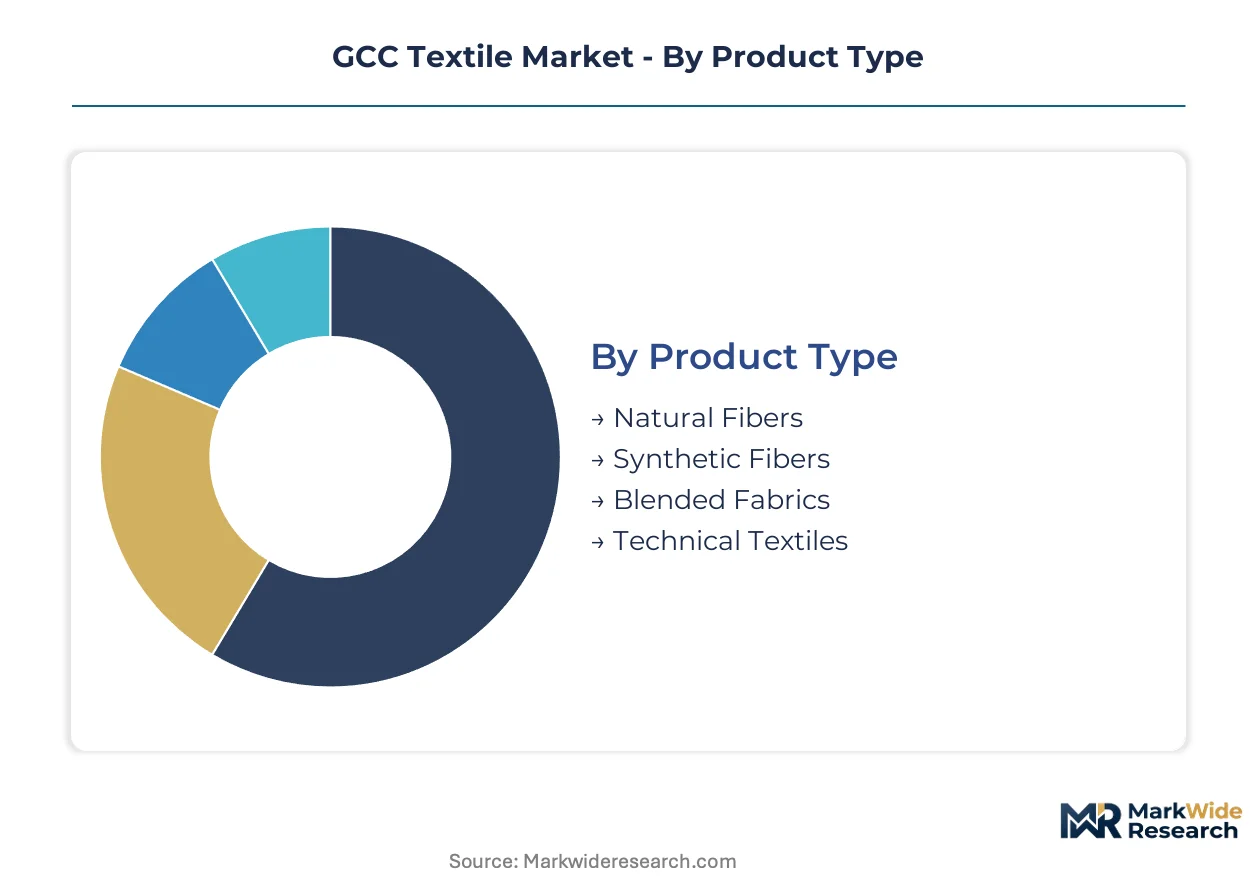
Segmentation in the GCC textile market reveals how fiber selection, end-use specification, and channel access determine margin capture across Saudi Arabia and the UAE. Each dimension exposes different competitive pressures: technical compliance for SASO labeling, petrochemical integration for synthetics, and re-export velocity for Dubai-based distribution.
Product Type:
Natural fibers operate as standalone commodity inputs, while technical textiles embed as performance-critical components within industrial systems.
- Natural Fibers:Cotton and wool constructions dominate Saudi uniform procurement and UAE hospitality linen supply. Egyptian long-staple cotton anchors premium bedding orders from Riyadh hotel operators facing SASO fiber-content audit requirements.
- Synthetic Fibers:Polyester and polypropylene spunbond nonwovens absorb oilfield geotextile demand and automotive interior specifications where flame-retardancy ratings exceed commodity thresholds. Saudi German Nonwovens leverages petrochemical backward integration to shield margin from polymer volatility.
- Blended Fabrics:Cotton-polyester moisture-wicking constructions displace pure synthetics in GCC athletic wear applications.
- Technical Textiles:Aramid and glass-fiber reinforced substrates serve oilfield containment and structural composite applications.
Natural fibers lead volumes today; technical textiles are gaining share fastest.
End Use/Application:
Cost tier stratification separates high-specification industrial applications from price-sensitive commodity apparel procurement.
- Apparel Manufacturing:Garment assembly concentrates in Jeddah industrial zones and Dubai free ports where SASO and ESMA labeling protocols filter import compliance. Modest fashion premiumization in Riyadh boutiques absorbs higher-margin abaya constructions with embroidery value-addition.
- Automotive Interiors:Flame-retardant technical fabrics from Saudi German Nonwovens and comparable suppliers integrate into GCC vehicle assembly lines. Specification intensity here exceeds commodity margins by requiring polymer-to-fabric control and captive laboratory testing.
- Home Furnishing:Curtain and upholstery fabrics serve UAE hospitality and Saudi residential development.
- Industrial Fabrics:Oilfield geotextiles and filtration media absorb technical textile capacity.
- Sportswear:Heat-climate athletic wear drives cotton-polyester blend adoption.
Apparel manufacturing leads volumes today; automotive interiors are climbing the fastest.
Manufacturing Technology:
Volume throughput concentrates in high-speed weaving and knitting, while margin capture shifts toward nonwoven and digital printing where specification intensity defends pricing power.
- Weaving:Air-jet and rapier looms process cotton and polyester warps for uniform and sheeting applications at Saudi Aratex Group facilities. This technology anchors commodity throughput but faces margin compression from Asian import competition.
- Nonwoven:Spunbond and meltblown polymer webs serve medical hygiene and oilfield geotextile specifications where Saudi German Nonwovens competes on petrochemical integration. ESMA pre-certification requirements favor captive production over trading-house intermediation.
- Knitting:Circular and flat-bed machines produce stretch constructions for sportswear and intimate apparel.
- Embroidery:Value-added decoration supports modest fashion premiumization in Jeddah and Riyadh boutiques.
- Printing:Digital sublimation displaces rotary screen for short-run orders.
- Dyeing:Continuous and batch processing faces effluent compliance capex burdens.
Weaving leads volumes today; nonwoven is expanding most quickly.
Distribution Channel:
Customer type segmentation separates institutional procurement desks from fragmented retail and direct-to-consumer velocity.
- Wholesale Distributors:Dubai-based trading houses aggregate Egyptian and Pakistani mill output for re-export across GCC states. ESMA marking protocols position these intermediaries as regional procurement gateways, though supplier reduction programs at Saudi retail chains erode their share.
- Online Platforms:E-commerce channels for modest fashion and corporate uniform orders compress minimum order quantities and accelerate colorway turnaround. Saudi boutique brands adopt sub-72-hour digital fulfillment to fragment legacy Indian mill relationships.
- Retail Outlets:Hypermarket private-label sourcing concentrates toward audited Turkish partnerships.
- Direct Sales:Mill-direct relationships bypass intermediaries for large uniform contracts.
- Dealers:Regional agents serve industrial fabric and technical textile specifications.
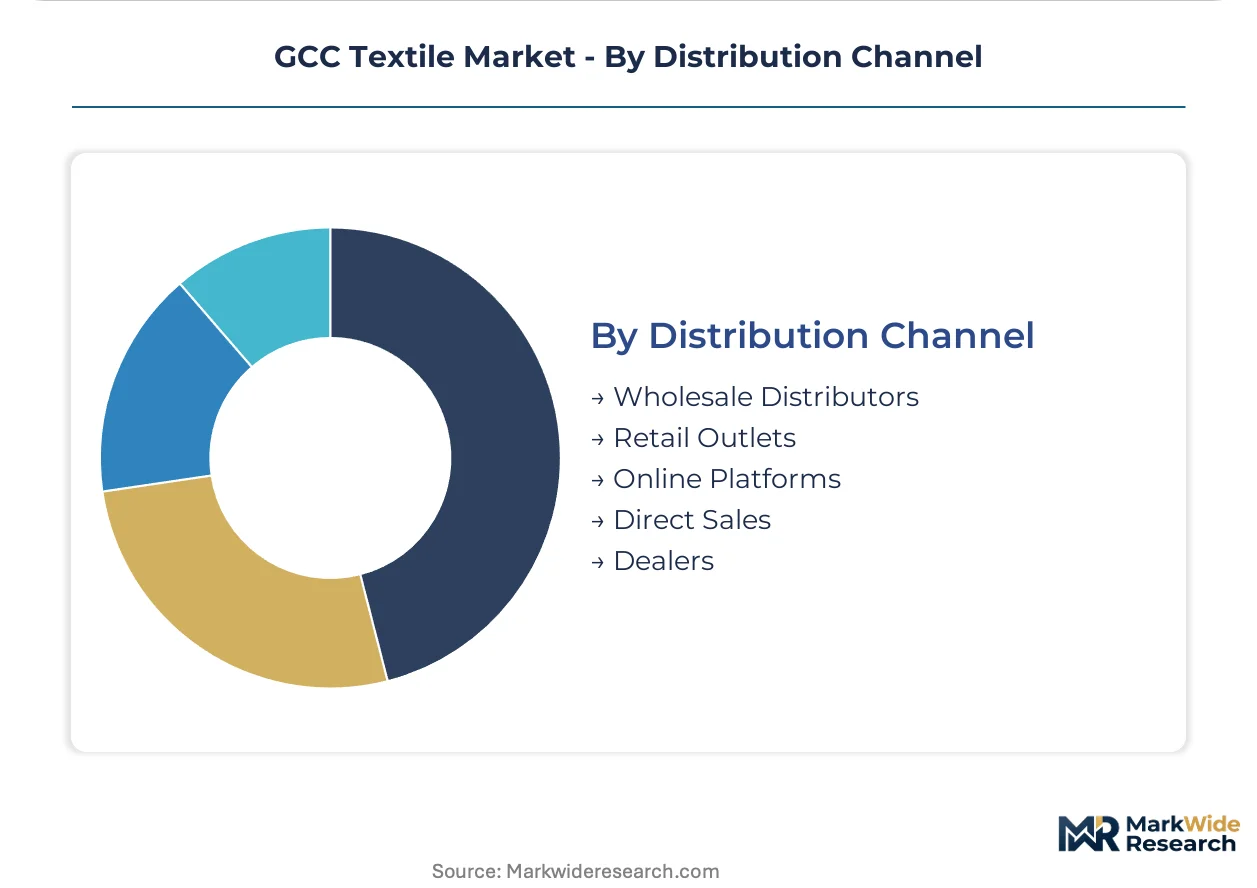
Wholesale distributors lead volumes today; online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's garment re-export hub anchors procurement velocity across Gulf Cooperation Council states, with Saudi Arabia and the United Arab Emirates absorbing the dominant share of technical textile and apparel manufacturing investment.
Saudi Arabia
Uniform procurement and modest fashion premiumization drive Saudi demand, with Riyadh boutiques absorbing higher-margin abaya constructions. SASO fiber-content labeling mandates filter non-compliant imports at Jeddah and Dammam ports, creating captive demand for locally certified spinning operations. King Abdullah Economic City attracts tax-advantaged dyeing investment to compress Asia-dependent lead times.
United Arab Emirates
Dubai's re-export gateway status concentrates Egyptian and Pakistani mill networks serving GCC procurement desks. ESMA marking protocols govern textile safety for re-exports, positioning UAE as the regional compliance checkpoint. Jebel Ali free zones host digital textile printing adoption for hospitality and corporate uniform short-run orders.
Kuwait
Hospitality linen supply and residential furnishing absorption characterize Kuwaiti textile procurement. The country's central standards body enforces import conformity assessment protocols that align with Gulf Cooperation Council customs union frameworks. Shuwaikh industrial areas concentrate garment finishing and embroidery value-addition for regional re-export.
Oman
Oilfield geotextile specifications and industrial fabric demand shape Omani procurement patterns. The Sultanate's special economic zones offer tariff advantages for polymer-to-fabric converters serving regional energy infrastructure. Sohar port logistics corridors connect Indian subcontinent mill networks to GCC distribution channels.
Qatar
Hospitality and healthcare textile specifications dominate Qatari demand following infrastructure expansion cycles. The national quality infrastructure regulator enforces product safety marking that harmonizes with Saudi and UAE protocols. Doha industrial zones concentrate medical nonwoven and technical fabric warehousing for regional project supply.
GCC Textile Market Competitive Landscape
Global majors compete with regional champions across petrochemical integration and technical specification intensity, producing a tiered structure where backward-integrated synthetics producers hold pricing power over commodity apparel converters. The vendor base separates into three archetypes: petrochemical-integrated nonwoven specialists, spinning-to-garment vertical operators, and boutique retail channel controllers. Dominant competitive moves include captive laboratory testing investments to preempt SASO port delays, and direct mill relationships replacing Dubai trading house intermediation.
Within the integrated manufacturing tier, Aratex Group and Saudi German Nonwovens exemplify divergent strategic positions. Aratex Group anchors Saudi Arabia's uniform and workwear supply through captive spinning-to-garment operations that satisfy SASO fiber-content audit requirements. Saudi German Nonwovens occupies a position in medical and hygiene substrates where polymer-to-fabric control shields margin from feedstock volatility. Lomar Collection represents the boutique retail vector, controlling premium modest fashion channels in Jeddah and Riyadh through embroidery and beadwork value-addition that commands pricing power above commodity apparel tiers.
| Leading Market Players |
|---|
| Aratex Group |
| Saudi German Nonwovens |
| Alyaf Industrial Co. Ltd. |
| Millennium Fashions Industries |
| FPC Coated Technical Textiles |
| SV Pittie Sohar Textiles |
| Avgol Middle East |
| Lomar Collection |
| Takween Advanced Industries |
| Others |
Supply & Pricing Matrix
SASO effluent discharge mandates gate qualified supply access and premium-tier pricing power for Saudi dyeing operations, compressing margins for non-compliant Pakistani garment workshops while rewarding certified Egyptian and Turkish mill partnerships with ESMA pre-certification.
Pricing Analysis
Polymer price swings transmit directly to polyester and polypropylene nonwoven margins, forcing contract-based long-term offtake structures among petrochemical-integrated suppliers. Price differentiation hinges on SASO fiber-content certification grade and volume scale, with boutique modest fashion channels absorbing premium embroidery value-addition. Cost compression in commodity apparel tiers intensifies because Asian import competition erodes uniform margins. Hypermarket private-label buyers exhibit highest price sensitivity; oilfield geotextile procurement desks demonstrate lowest sensitivity due to specification-critical applications.
Supply Chain Analysis
Freight cost volatility from India and China dyeing hubs exposes GCC garment makers to working capital strain during 90-120 day procurement cycles. Supply concentrates in Egypt, Pakistan, and Turkey for cotton spinning; Saudi Arabia and UAE for petrochemical-derived synthetics. Raw material dependencies rest on Egyptian long-staple cotton, polymer feedstocks from SABIC and ADNOC, and Indian yarn intermediates. Single-source vulnerability concentrates in Chinese digital printing equipment and specialty dye chemicals. Distribution runs through Dubai-based wholesale trading houses and direct mill relationships for large uniform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in technical textile premiumization and captive laboratory investments that preempt SASO port delays, with digital sublimation adoption compressing minimum order quantities for modest fashion velocity.
For Market Incumbents: Deepen backward integration into polymer-to-fabric control to shield margin from petrochemical volatility, and expand captive testing capacity in Riyadh to bypass SASO laboratory bottlenecks. Aratex Group's spinning-to-garment model demonstrates how vertical integration defends against trading-house disintermediation. Prioritize King Abdullah Economic City dyeing investment to compress Asia-dependent lead times below fast-fashion velocity thresholds.
For New Entrants and Emerging Players: Boutique hospitality linen buyers in Riyadh and Doha represent an underserved archetype with specification intensity above commodity tiers but below oilfield geotextiles. Target medical nonwoven capacity gaps in Qatar's healthcare infrastructure expansion, and pursue ESMA pre-certification partnerships with audited Turkish mills to bypass Dubai trading house intermediation. Lead with sub-72-hour digital fulfillment capabilities to fragment legacy Indian mill relationships.
For Investors and Strategic Acquirers: Roll-up economics work for petrochemical-integrated nonwoven specialists because SASO documentation burdens favor vertically integrated operations over trading-house intermediaries. Five-to-ten year viability hinges on technical textile specification intensity exceeding commodity apparel margin compression. Acquire targets with captive laboratory testing and Red Sea industrial zone tax advantages. Watch for King Abdullah Economic City dyeing capacity announcements as inflection indicators for Asia-dependent lead time compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Saudi German Nonwovens leverages SABIC feedstock access to shield margin from volatility. |
| Captive Laboratory Testing Investment | Preemptive SASO certification in Riyadh eliminates port-of-entry delays and frozen working capital. |
| Digital Sublimation Printing Adoption | UAE hospitality suppliers achieve sub-72-hour turnaround for fragmented short-run orders. |
| ESMA Pre-Certification Partnerships | Audited Turkish mill relationships bypass Dubai trading house intermediation for Saudi retail chains. |
| Red Sea Industrial Zone Expansion | King Abdullah Economic City tax advantages compress Asia-dependent lead times for uniform suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Saudi spinning mill operations directors, UAE hospitality procurement managers, Egyptian cotton export traders, and Dubai-based trading house principals with secondary validation. Customs data from Saudi Ports Authority and UAE Federal Customs Authority anchored volume estimates, while SASO technical textile labeling amendments and ESMA marking protocols informed regulatory scenario modeling. Bottom-up mill capacity assessments triangulated against top-down GCC apparel consumption proxies.
Comparable-period anchoring linked historical fiber price volatility patterns to forward projection assumptions across the analysis window. Segmentation dimensions modeled included fiber type, end-use application, manufacturing technology, and distribution channel, with additional granularity on modest fashion versus industrial fabric specification intensity. CAGRs derived from compound growth trajectory analysis incorporating petrochemical feedstock cost curves and SASO compliance adoption rates.
Inputs from Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology were available through the study window; gaps in real-time Pakistani mill cost structures introduce uncertainty bands around competitive positioning assessments. Forecasts reflect documented assumptions on dyeing capacity migration to King Abdullah Economic City and digital printing adoption velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Textile Felt Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Global Textile Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Handloom Products Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Quilt Market
Textile Innovations
Smart Textile Market
Textile Innovations
Digital Textile Printing Market