
 Pool Speakers Market | 2026-2036
Pool Speakers Market Size, Share, and Industry Trends Forecast 2026-2036
Pool Speakers Market Analytics
Residential hospitality is repositioning the pool speakers category toward permanently installed, architecturally integrated audio solutions. JBL anchors its position through aggressive waterproofing certification and resort-channel partnerships. Ultimate Ears competes on portable durability and direct-to-consumer distribution. Sony differentiates through high-resolution audio codecs and premium pricing tiers in the built-in segment.
Pool speakers are sealed, weather-resistant electroacoustic transducers engineered to reproduce audio in wet, chlorinated, or saline environments, typically carrying IP67 or IP68 ingress protection ratings and corrosion-resistant polymer housings. Their primary purpose is to deliver ambient or directed sound in residential pools, hotel aquatic facilities, and commercial water parks without electrical hazard. Bluetooth speakers now dominate unit volume while built-in installations capture the majority of value, as waterproofing costs and professional labor embed premium pricing into permanently mounted systems. Floating speakers represent a narrowing novelty segment with compressed margins, whereas bass-enhanced configurations command attention in the residential luxury tier.
FCC Part 15 governs wireless transmission protocols for Wi-Fi and Bluetooth pool speakers sold in the United States, while EPA guidelines on lithium-ion battery disposal shape end-of-life obligations for manufacturers. CE marking and REACH compliance govern material safety and electromagnetic compatibility for European market access. Stakeholders must monitor evolving IP rating harmonization between IEC and regional bodies, as stricter submersion-depth testing protocols could reshape competitive barriers and certification costs.
Market Dynamics
Residential pool construction in Florida, California, and Arizona is compressing demand cycles toward permanently installed, architecturally integrated audio systems rather than seasonal portable replacements.
Growth Catalysts
- Bluetooth IP67 certification:Waterproofing standard harmonization is eliminating regional fragmentation in product design. Manufacturers now engineer once for multi-territory deployment.
- Lithium-ion battery density gains:Energy storage improvements are extending playback duration without housing enlargement. Portable units now rival wired installations in runtime.
- Queensland residential hospitality:Australian resort-channel partnerships are normalizing premium built-in specifications. This demand is filtering into adjacent Southeast Asian markets.
Market Restraints
- Corrosion-resistant polymer input costs:Specialized housing materials face petrochemical price volatility. Margin compression hits floating speaker categories hardest.
- Professional labor dependency:Built-in installations require certified electrician engagement. Installation cost often exceeds hardware price in premium segments.
- IEC submersion-depth testing divergence:Regional bodies are proposing conflicting IP rating protocols. Certification multiplication is raising market entry barriers.
Strategic Opportunities
- Saline environment specialization:Saltwater pool conversion trends in coastal United States counties are creating specification gaps. Corrosion engineering for chloride exposure remains underdeveloped.
- Wi-Fi 6E convergence with mesh networking:Low-latency multi-speaker synchronization is enabling whole-pool audio zoning. Residential luxury buyers are piloting these configurations.
- India PLI scheme extension:Electronics manufacturing incentives are attracting contract assembly relocation. Component sourcing from this geography could reshape cost structures.
Industry Challenges
- Acoustic engineering talent scarcity:Waterproof transducer design requires rare crossover expertise in materials science and audio engineering. Compensation inflation is hitting mid-tier manufacturers.
- FCC Part 15 certification timelines:Wireless protocol approval delays are compressing product launch windows. Pre-certification testing costs are rising with protocol complexity.
- Legacy 2.4 GHz interference management:Crowded spectrum in dense residential deployments is degrading Bluetooth reliability. Firmware mitigation is consuming R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pool Speakers Market |
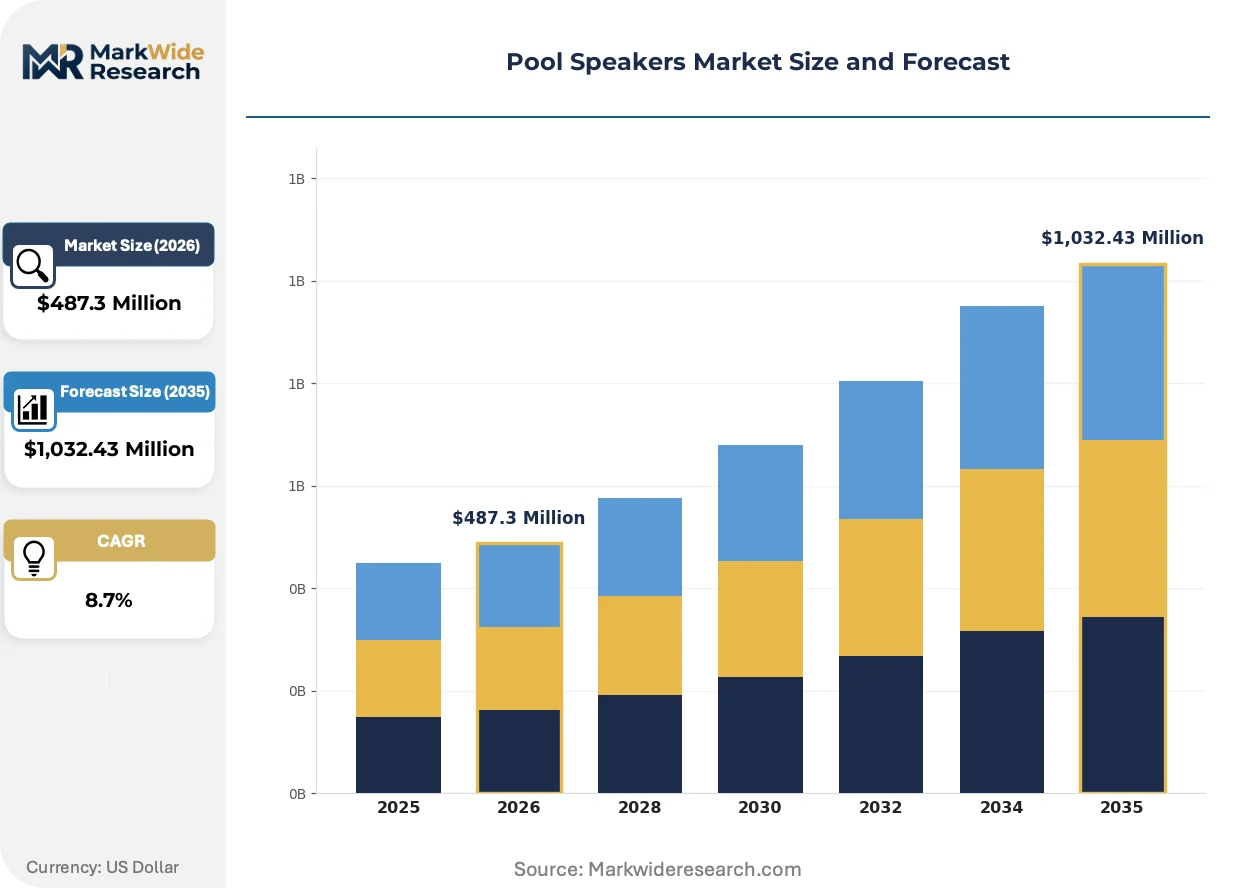
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Speakers, Wired Speakers, Floating Speakers, Wall-Mounted Speakers Form Factor: Portable, Installed, Built-In, In-Ground Connectivity: Wi-Fi, NFC, Auxiliary, USB Sound Quality: High-Fidelity, Waterproof, Bass-Enhanced, Surround Sound |
| Companies Covered | Ultimate Ears, Marshall, JBL, Tribit, Bose, soundcore, EarFun, Anker, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pool Speakers Market Evolving Landscape
Audio hardware is converging with architectural specification processes, permanently installed systems now entering design-phase conversations rather than post-construction retrofit markets.
GaN (gallium nitride) amplification circuitry is electrifying power efficiency in compact waterproof housings. Residential integrators in Scottsdale, Arizona and Naples, Florida are specifying these amplifiers for heat-dissipation-constrained poolside enclosures. The technology is electrifying what was previously a thermal-management ceiling on output wattage.
EPA lithium-ion battery disposal guidelines are reshaping end-of-life obligations for manufacturers selling in the United States. Take-back program mandates are adding operational overhead while creating service-revenue attachment points. The portable segment is responding with modular battery architectures enabling field replacement rather than full unit retirement.
Architects are embedding speaker specifications into construction documentation earlier than previous cycles. Pool builders in Queensland and Orange County are routing conduit during gunite phase rather than post-tile. This behavioral compression is eliminating retrofit margin for aftermarket installers and favoring manufacturer-direct specification relationships.
Pool Speakers Market Segmentation
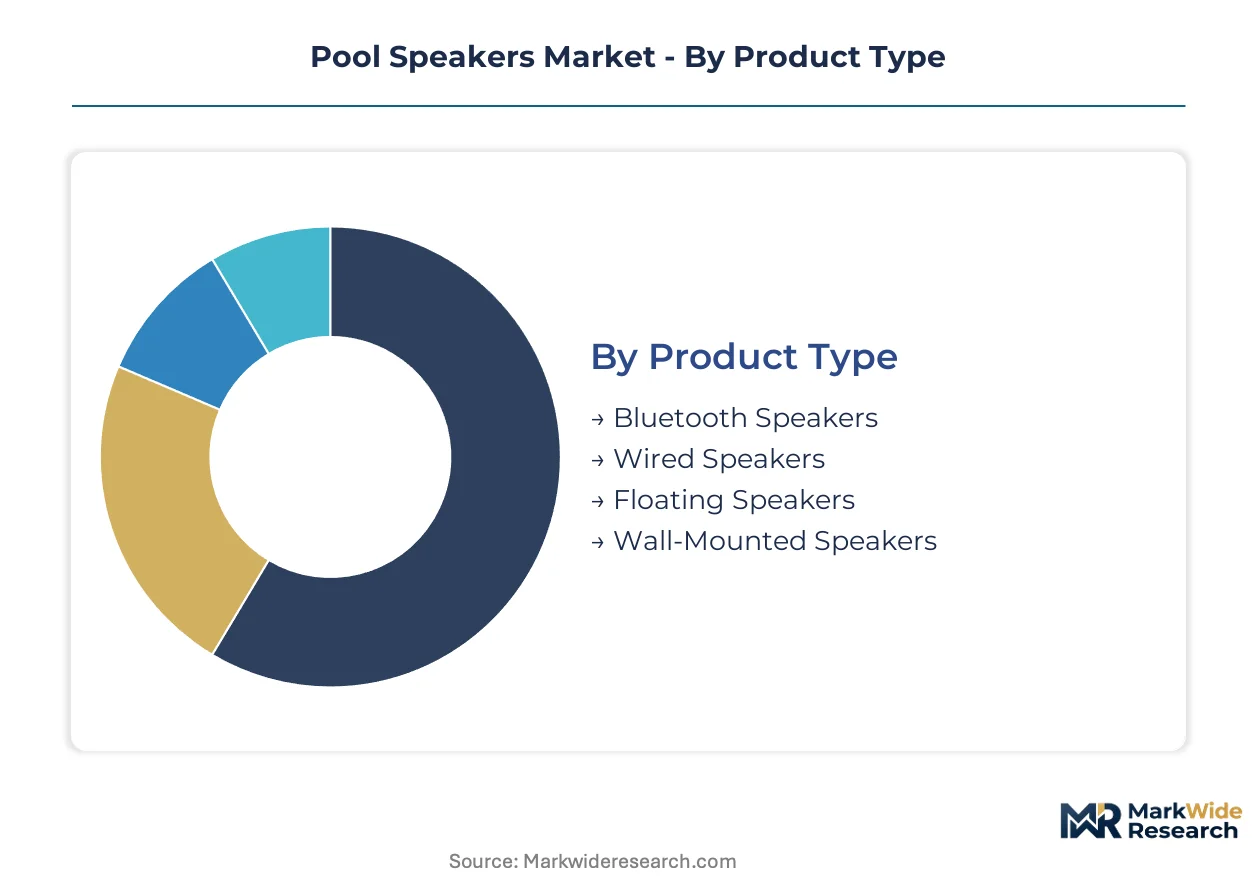
Pool speaker segmentation reveals how waterproof audio hardware splinters across installation permanence, acoustic performance tiers, and network protocols. Buyers trade portability against architectural integration, while saltwater corrosion resistance and mesh synchronization capabilities reshape specification priorities.
Product Type:
Customization intensity varies sharply across this category, from mass-produced portable units to architect-specified permanent installations requiring certified electrician engagement.
- Bluetooth Speakers:Wireless units dominate unit volume through lithium-ion battery density improvements and IP67 certification harmonization. Demand concentrates in Florida, California, and Arizona residential pools where seasonal portability matches replacement cycles.
- Wired Speakers:Permanently cabled systems capture majority value share through professional labor embedding and corrosion-resistant polymer housings. Queensland resort-channel partnerships normalize these specifications for saline environment durability.
- Floating Speakers:Novelty segment with compressed margins faces petrochemical price volatility in housing materials.
- Wall-Mounted Speakers:Architecturally integrated units enter construction documentation during gunite phase rather than post-tile retrofit.
Most installed capacity flows through Wired Speakers. Expansion is steepest in Bluetooth Speakers.
Form Factor:
Cost tier stratification separates disposable portables from capital-intensive built-in systems with decade-long depreciation schedules.
- Portable:Battery-powered units with GaN amplification circuitry address thermal-management constraints in compact housings. Scottsdale and Naples integrators specify these for heat-dissipation-constrained poolside enclosures.
- Installed:Post-construction retrofit systems face margin compression as architects embed specifications earlier in documentation cycles.
- Built-In:Gunite-phase conduit routing eliminates aftermarket installer margin and favors manufacturer-direct specification relationships.
- In-Ground:Subgrade transducer housings require chloride-exposure engineering for saltwater pool conversion trends in coastal United States counties.
Built-In systems anchor revenue concentration. Portable configurations gain share fastest through direct-to-consumer distribution normalization.
Connectivity:
Application context dictates protocol selection, from latency-tolerant ambient audio to synchronized multi-zone residential luxury configurations.
- Wi-Fi:Wi-Fi 6E convergence with mesh networking enables whole-pool audio zoning with low-latency multi-speaker synchronization.
- NFC:Pairing acceleration technology reduces friction in hospitality deployment scenarios with high guest turnover.
- Auxiliary:Legacy 3.5mm connections persist in commercial water parks with established AV infrastructure.
- USB:Power-delivery and data hybrid connections support firmware updates and charging in premium portable segments.
Wi-Fi carries the steepest expansion trajectory. Auxiliary maintains installed base in legacy commercial installations.
Sound Quality:
Customer type differentiation separates audiophile residential buyers from utility-focused commercial operators prioritizing coverage over fidelity.
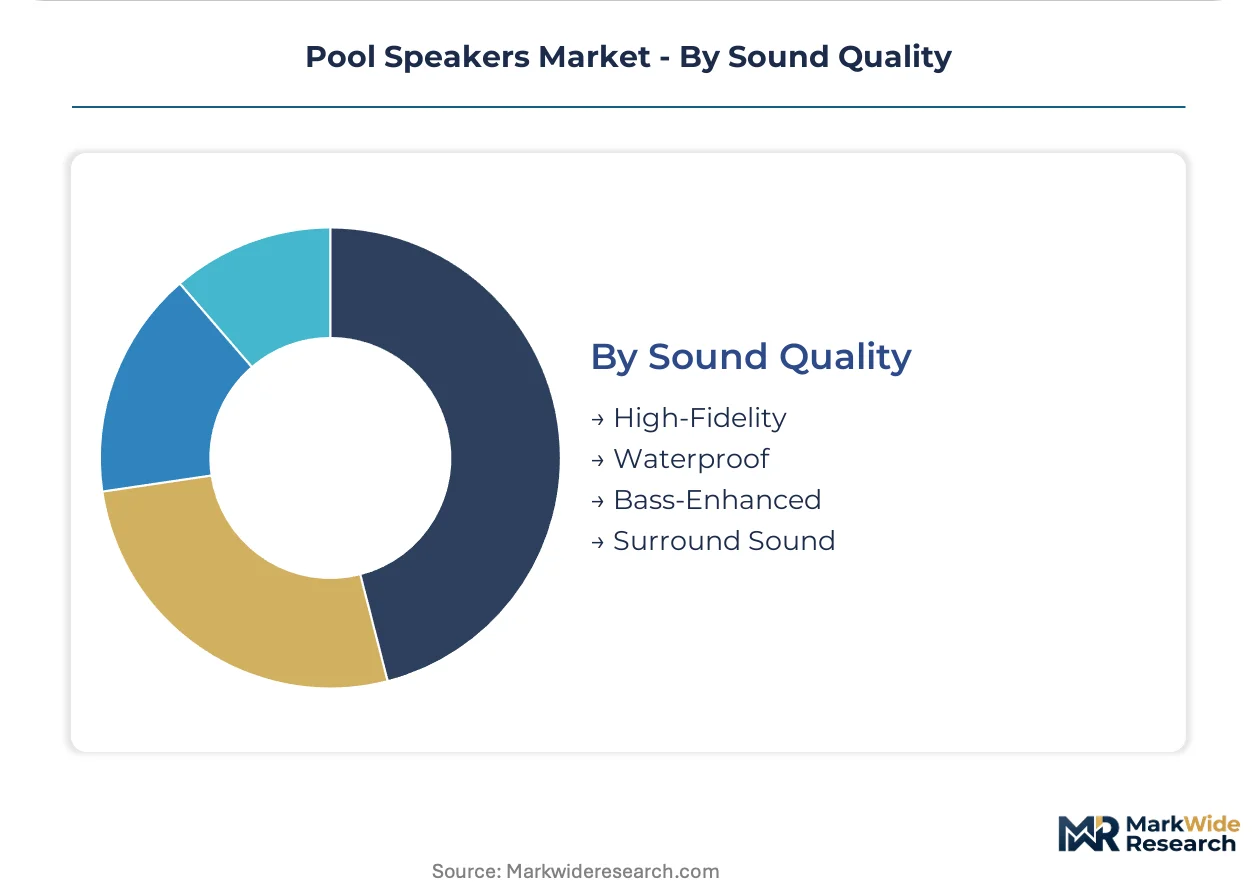
- High-Fidelity:High-resolution audio codec support commands premium pricing tiers in built-in segments through Sony differentiation.
- Waterproof:IP68 ingress protection ratings with corrosion-resistant polymer housings address chlorinated and saline environment durability requirements.
- Bass-Enhanced:Low-frequency emphasis configurations capture attention in residential luxury tier through GaN amplification power efficiency gains.
- Surround Sound:Multi-channel spatial audio systems require acoustic engineering talent scarce in materials science and audio engineering crossover expertise.
Waterproof specifications dominate unit economics. Bass-Enhanced configurations climb fastest in residential luxury tier specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's resort-channel partnerships anchor international demand normalization for premium built-in specifications. Florida, California, and Arizona residential construction compresses product cycles toward permanent installations. Regulatory fragmentation around IEC submersion protocols shapes competitive barriers across all major markets.
United States
Florida, California, and Arizona residential pool construction drives specification timing toward gunite-phase conduit routing. FCC Part 15 governs wireless transmission protocols for Bluetooth and Wi-Fi enabled units. Scottsdale and Naples integrators specify GaN amplification for heat-dissipation-constrained poolside enclosures.
Australia
Queensland resort-channel partnerships normalize premium built-in specifications filtering into Southeast Asian adjacent markets. TGA-equivalent electrical safety standards govern outdoor audio equipment deployment. Gold Coast and Sunshine Coast hospitality developments specify corrosion-resistant polymer housings for saline environment durability.
Germany
CE marking and REACH compliance requirements shape material safety and electromagnetic compatibility for European market access. BaFin-adjacent consumer protection frameworks influence warranty and service obligation structures. Bavarian and Baden-Württemberg residential integrators specify architecturally integrated wall-mounted systems.
China
MIIT radio transmission regulations and GB standards govern wireless protocol certification for domestic and export manufacturing. Dual carbon goals pressure energy efficiency specifications in amplification circuitry. Pearl River Delta contract assembly clusters attract relocation interest under cost structure pressures.
India
PLI scheme electronics manufacturing incentives attract contract assembly relocation from established Asian supply bases. BIS certification requirements shape product design for domestic market entry. Maharashtra and Karnataka industrial corridors develop component sourcing capabilities for audio hardware assembly.
Pool Speakers Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek resort-channel access and architect specification relationships. The vendor base organizes around three tiers: multinational electronics conglomerates with audio divisions, specialty portable audio brands with direct-to-consumer distribution, and contract manufacturers serving private-label hospitality programs. Two strategic archetypes predominate: waterproofing certification leaders pursuing aggressive IP67/IP68 standardization, and architectural integration specialists embedding specifications into construction documentation cycles. Portfolio diversification into saline-environment specialization and Wi-Fi 6E mesh configurations represents the dominant competitive vector alongside geographic expansion into Queensland and Indian manufacturing corridors.
Within the multinational tier, Sony Corporation and JBL occupy positions exemplifying divergent strategic emphases. Sony anchors premium-tier positioning through high-resolution audio codec differentiation and built-in segment focus. JBL represents aggressive waterproofing certification and resort-channel partnership archetypes. Ultimate Ears sits within the specialty portable segment, exemplifying direct-to-consumer distribution normalization and durability-focused product architecture. These three companies collectively illustrate the competitive tension between permanent installation value capture and portable unit volume expansion.
| Leading Market Players |
|---|
| Ultimate Ears |
| Marshall |
| JBL |
| Tribit |
| Bose |
| soundcore |
| EarFun |
| Anker |
| Sony |
| Others |
Value Network & Pricing Analysis
GaN amplification circuitry adoption is compressing thermal-management costs in compact waterproof housings while simultaneously concentrating amplifier sourcing among specialized semiconductor foundries. This technology transition rewards manufacturers with direct foundry relationships and squeezes mid-tier competitors dependent on merchant supply.
Pricing Analysis
Corrosion-resistant polymer input costs pass through to end pricing with minimal absorption capacity across floating speaker categories. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified built-in systems from seasonal portable replacements from novelty floating units. Price differentiation hinges on IP68 certification tier and professional installation bundling. Pricing pressure stems from petrochemical volatility in housing materials, with commercial water park operators exhibiting highest price sensitivity and residential luxury buyers showing lowest.
Supply Chain Analysis
Lithium-ion battery cell supply rests on South Korean and Chinese producers, with Japanese specialty chemical manufacturers anchoring electrolyte and separator inputs. Amplifier modules draw from Taiwan semiconductor packaging clusters, while corrosion-resistant polymer resins feed from German and US petrochemical complexes. Single-source vulnerability concentrates in GaN wafer supply for premium amplification tiers. Distribution runs through residential integrator channels in Florida and Arizona, resort procurement offices in Queensland, and direct-to-consumer platforms for portable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pool speakers hinges on lithium-ion battery density gains reducing per-unit power component costs and premium built-in specifications capturing greater specification timing in construction documentation.
For Market Incumbents: Lock in architect specification relationships through gunite-phase conduit routing partnerships before post-tile retrofit margins compress entirely. Deepen backward integration into corrosion-resistant polymer compounding to offset petrochemical price volatility threatening floating speaker categories. Certification investment in IP68 submersion-depth testing protocols creates defensive moats against regional regulatory divergence. For New Entrants and Emerging Players: Launch via direct-to-consumer distribution targeting seasonal replacement cycles in Florida, California, and Arizona residential pools where brand loyalty remains undeveloped. Saline environment specialization for saltwater pool conversion trends in coastal United States counties offers white-space penetration with underdeveloped corrosion engineering. Wi-Fi 6E mesh networking configurations for residential luxury buyers provide entry vector with lower certification burden than built-in electrical installations. For Investors and Strategic Acquirers: Roll-up economics work for regional residential integrator networks because construction-phase specification timing is eliminating aftermarket installer viability and concentrating customer relationships with early-engagement specialists. Target acquisition archetype: Scottsdale or Naples-based integrators with established GaN amplification specification relationships and resort-channel hospitality contracts. Watch IEC submersion-depth testing harmonization progress as inflection indicator for certification cost barriers and competitive consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Resort-Channel Partnership Expansion | Queensland hospitality developments normalize premium specifications filtering into Southeast Asian adjacent markets. |
| GaN Amplification Integration | Scottsdale and Naples integrators specify power-efficient circuitry for heat-dissipation-constrained poolside enclosures. |
| Saline Environment Specialization | Saltwater pool conversion trends in coastal United States counties create specification gaps for chloride-exposure engineering. |
| Wi-Fi 6E Mesh Deployment | Low-latency multi-speaker synchronization enables whole-pool audio zoning for residential luxury configurations. |
| India PLI Scheme Assembly Relocation | Maharashtra and Karnataka industrial corridors develop component sourcing capabilities reshaping cost structures. |
Research Methodology
Multiple input streams — primary interviews with residential integrators, resort procurement officers, and pool construction contractors; secondary validation through FCC certification databases, EPA battery disposal guidelines, and IEC standard harmonization documents; plus customs and trade flow analysis — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Data-stream reconciliation across product type, form factor, connectivity protocol, and sound quality tier dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated lithium-ion battery density improvement curves and residential construction permit flows in Florida, California, and Arizona.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IEC submersion-depth testing protocol divergence or acute petrochemical price spikes. Forecasts reflect documented assumptions around Bluetooth IP67 certification harmonization and resort-channel partnership normalization rates. A small set of triggers — regulatory fragmentation acceleration, GaN wafer supply disruption, saltwater pool conversion velocity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Earphones Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Closed Back Studio Headphone Market