
 Middle East and Africa Smartphones Market | 2026-2036
Middle East and Africa Smartphones Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Smartphones Market Foresight
E-commerce and mobile-first retail platforms are rewriting smartphone distribution across the Middle East and Africa. Transsion Holdings Limited dominates offline wholesale networks in West Africa through its Tecno, Itel, and Infinix brands. Samsung Electronics Co., Ltd. leverages premium retail partnerships in Gulf Cooperation Council malls and urban centers. Xiaomi Corporation anchors aggressive online flash sales and local assembly strategies to undercut import duties in key markets.
Smartphones are handheld personal computing devices integrating cellular modems, application processors, touch-sensitive displays, and lithium-ion power systems for voice communication, internet access, and multimedia consumption. Touchscreen models lead volume shipments across the region, though foldable variants command concentrated margin pools in Gulf urban centers. Budget and mid-range price tiers absorb the bulk of first-time buyer demand, while enterprise end users are shifting toward ruggedized Android devices for field logistics and inventory management.
Spectrum licensing frameworks from national telecommunications regulators in Saudi Arabia, South Africa, and Nigeria directly determine which frequency bands devices must support for market access. Egypt's National Telecom Regulatory Authority and the UAE's Telecommunications and Digital Government Regulatory Authority enforce type-approval standards that shape import volumes and local certification timelines. Stakeholders must monitor diverging 5G band allocations and local content requirements as governments tighten device registration protocols and consumer protection rules.
Market Dynamics
5G infrastructure rollouts across Saudi Arabia, South Africa, and Nigeria are forcing device manufacturers to recalibrate modem compatibility and certification timelines. Spectrum auctions and local assembly mandates from national regulators are compressing product development cycles while expanding addressable demand pools.
Growth Catalysts
- TRAI-equivalent spectrum reforms:Nigeria's National Communications Commission and South Africa's ICASA are liberalizing frequency access, lowering barriers for sub-6 GHz device certification and accelerating 5G handset eligibility.
- Gig economy workforce expansion:Delivery platforms and ride-hailing services across Kenya and Egypt are mandating smartphone-based dispatch systems, converting feature phone users to touchscreen devices.
- Lithium-ion supply localization:Assembly plants in Morocco and Egypt are securing captive battery supply chains, reducing import dependency and shortening replenishment lead times for regional distributors.
Market Restraints
- Currency volatility exposure:Egyptian pound and Nigerian naira depreciation against the dollar is inflating landed costs for imported chipsets and display panels, squeezing margin structures for mid-tier OEMs.
- Single-source display dependency:AMOLED panel supply concentrates in East Asian fabrication facilities, exposing African assembly operations to shipping disruptions and tariff cascades.
- Legacy 2G network persistence:Rural coverage gaps in Ethiopia and Sudan delay 4G/5G device adoption, fragmenting SKUs and complicating inventory planning for national distributors.
Strategic Opportunities
- Underpenetrated East African corridors:Ethiopia's Addis Ababa-Djibouti logistics axis and Tanzania's Dar es Salaam port hinterland show sub-35% smartphone penetration, creating first-mover whitespace for budget device entrants.
- Local content assembly incentives:Egypt's industrial development zones and Morocco's free trade agreements with the EU offer tariff exemptions for devices with 30%+ local value addition, rewarding regional manufacturing investment.
- Convergence of mobile money and device financing:M-Pesa integration with smartphone installment plans in Kenya is hybridizing distribution models, embedding credit access directly into retail channels.
Industry Challenges
- Certification timeline compression:Egypt's NTRA and UAE's TDRA are tightening type-approval protocols for 5G devices, extending testing cycles by 6-8 weeks and delaying seasonal product launches.
- Technical workforce scarcity:Field repair networks across West Africa lack trained technicians for foldable display and multi-camera module servicing, elevating warranty costs and customer churn.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Smartphones Market |
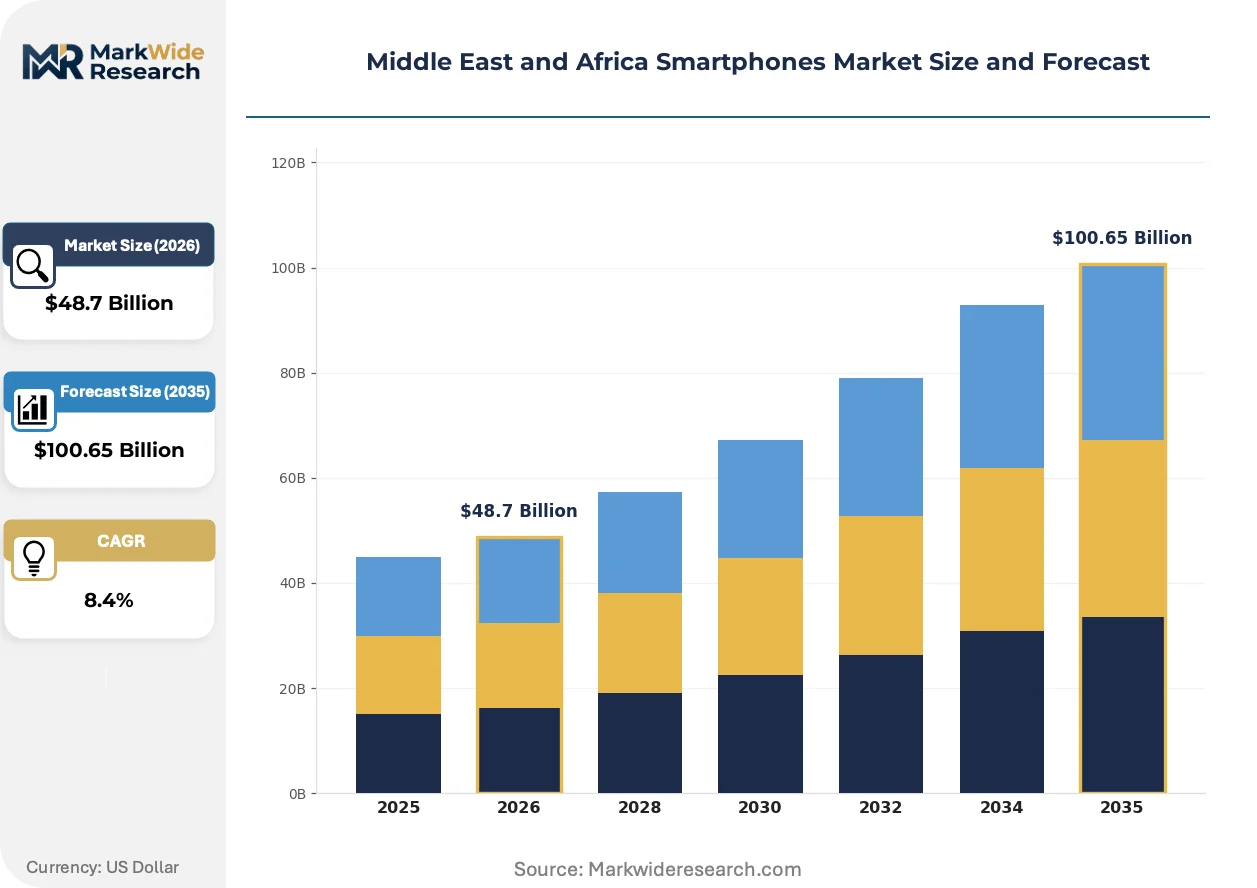
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen, Foldable, Rugged, Feature Phone End User: Consumers, Enterprises, Education Institutions, Government Operating System: Android, iOS, HarmonyOS, KaiOS Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | Samsung Electronics Co., Ltd., Xiaomi Corporation, Transsion Holdings Limited, Huawei Technologies Co., Ltd., Infinix Mobility Limited, Oppo Guangdong Mobile Communications Co., Ltd., Apple Inc., HMD Global Oy, Vivo Communication Technology Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Smartphones Market Shifts & Advancements
Device architecture and distribution logistics are converging around modular component sourcing and localized assembly. Regulatory pressure on data sovereignty and supply chain traceability is accelerating certification complexity across the region.
MediaTek Dimensity chipsets with integrated 5G modems are hybridizing cost-performance positioning for mid-range African smartphones. Cairo-based distributors are adopting these platforms to hit sub-$200 retail price points while maintaining sub-6 GHz connectivity. The structural consequence is compressing Qualcomm Snapdragon dominance in tier-two city markets where margin sensitivity dominates procurement criteria.
Saudi Arabia's Communications and Information Technology Commission is mandating IMEI registration for all imported devices, creating a centralized traceability database. Industrial consequence includes elevated compliance costs for gray-market importers and accelerated exit of uncertified white-label manufacturers. Gulf Cooperation Council retail channels are responding by consolidating supplier relationships with type-approved OEMs exclusively.
Flash sale mechanics pioneered by Chinese e-commerce platforms are displacing traditional wholesale credit terms across Nigerian and Kenyan urban centers. Jumia and Konga are unbundling device sales from carrier subsidies, forcing offline retailers to match cash-upfront pricing or cede volume. Lagos and Nairobi consumer segments are exhibiting the fastest channel rotation, with online share doubling in premium-mid price tiers.
Middle East and Africa Smartphones Market Segmentation
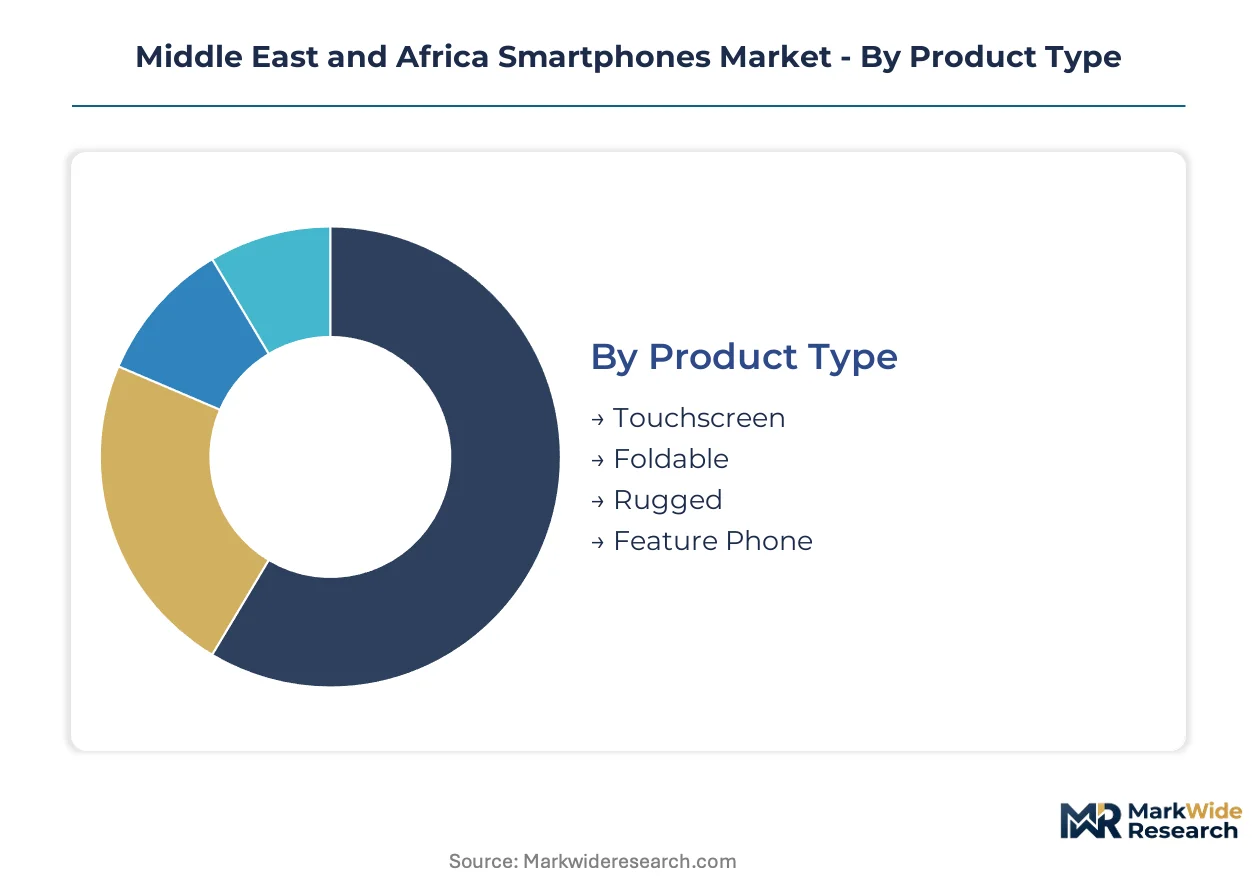
Smartphone segmentation across the Middle East and Africa maps directly to divergent infrastructure maturity and purchasing power corridors. Device specifications, operating platforms, and price positioning must align with spectrum availability in Saudi Arabia, Egypt, and Nigeria while accommodating currency volatility in Kenya and South Africa.
Product Type:
Mature touchscreen architectures dominate established urban corridors, while emerging form factors target specific use-case niches in Gulf Cooperation Council centers and East African logistics hubs.
- Touchscreen:Capacitive multi-touch displays with Gorilla Glass protection and IPS/LCD or AMOLED panels constitute the baseline interface standard. Demand concentrates in Egypt's Cairo-Alexandria corridor and South Africa's Gauteng province, where young professionals and gig economy workers upgrade from feature phones for ride-hailing and mobile banking applications.
- Foldable:Hinge mechanisms with flexible OLED substrates enable tablet-sized screen real estate in pocketable form factors. Adoption clusters in Dubai, Riyadh, and Jeddah retail channels, driven by status-conscious consumers seeking device differentiation in premium mall environments.
- Rugged:Reinforced polycarbonate housings with IP68 ingress protection and MIL-STD-810G shock resistance serve field logistics and inventory management use cases.
- Feature Phone:Physical keypad interfaces with limited internet connectivity persist in rural Ethiopia and Sudan where 2G network infrastructure delays touchscreen migration.
Touchscreen handles the majority of throughput; Foldable is the fastest mover on share.
End User:
Customer archetypes span individual purchasers, institutional procurement officers, and public sector IT administrators with divergent specification requirements and volume negotiation leverage.
- Consumers:Individual purchasers selecting devices based on price-performance ratios, brand recognition, and camera specifications. Volume concentrates in Nigerian and Kenyan urban centers where mobile-first retail platforms and installment financing expand access.
- Enterprises:Corporate IT departments procuring fleet deployments with mobile device management compatibility and security certification requirements. Demand is accelerating across South African mining operations and Saudi Arabian logistics companies adopting ruggedized Android for field workforce tracking.
- Education Institutions:School and university administrators sourcing bulk quantities for student learning programs and digital literacy initiatives.
- Government:Public sector agencies requiring type-approved devices with local data sovereignty compliance and IMEI traceability for security applications.
Consumer procurement absorbs the largest volume base; Enterprise represents the steepest expansion trajectory as fleet management digitization accelerates.
Operating System:
Platform competition reflects ecosystem lock-in effects, hardware optimization requirements, and geopolitical technology access constraints across the region's diverse regulatory environments.
- Android:Open-source Linux-based platform with customizable OEM skins and Google Mobile Services integration. Dominates budget and mid-range tiers through Transsion Holdings' Tecno, Itel, and Infinix brand deployments across West African wholesale networks.
- iOS:Proprietary Apple ecosystem with tight hardware-software integration and extended software support cycles. Premium positioning aligns with Gulf Cooperation Council mall retail and high-income consumer segments in Johannesburg and Cape Town.
- HarmonyOS:Huawei's distributed operating system with cross-device connectivity and absence of Google services. Gaining traction in markets where US trade restrictions limit Android access for Chinese OEMs.
- KaiOS:Lightweight web-based platform optimized for feature phone hardware with limited memory and processing constraints. Serves rural coverage gaps where smartphone affordability barriers persist.
Android commands the dominant installed base; HarmonyOS is climbing the fastest as Chinese OEMs expand regional manufacturing presence.
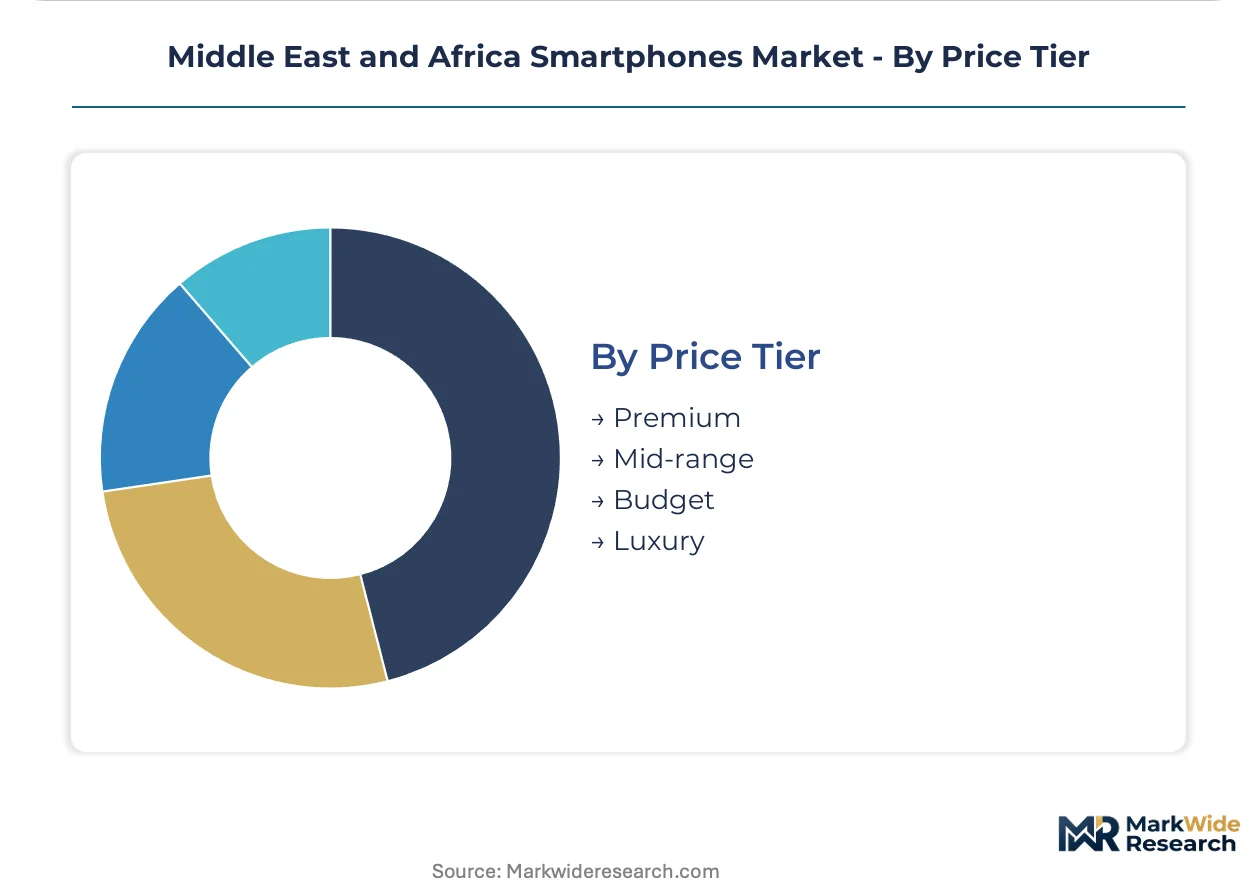
Price Tier:
Purchase thresholds segment directly against disposable income distribution, financing access, and import duty exposure across currency-volatile economies.
- Budget:Sub-$150 retail positioning with MediaTek Dimensity or entry-level Snapdragon chipsets, LCD displays, and plastic unibody construction. Absorbs first-time buyer demand in Nigeria, Kenya, and Ethiopia where M-Pesa and equivalent mobile money platforms enable installment purchase models.
- Mid-range:$150-$400 positioning with 5G modem integration, AMOLED displays, and multi-camera arrays. Fastest-growing segment as Egyptian and Moroccan assembly plants localize production to reduce import dependency.
- Premium:$400-$800 flagship specifications with latest-generation processors, high-refresh-rate displays, and advanced computational photography.
- Luxury:$800+ positioning with precious metal finishes, concierge services, and limited edition collaborations targeting ultra-high-net-worth individuals in Dubai and Riyadh.
Budget tier moves the highest unit volumes; Mid-range is gaining share fastest as 5G infrastructure rollouts expand device eligibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Djibouti-Addis Ababa railway corridor underwrites Ethiopia's emergence as an East African logistics hub for device distribution, while the Suez Canal Economic Zone anchors Egypt's assembly-to-export manufacturing role in Mediterranean trade flows.
Saudi Arabia
Neom and the Red Sea Project are generating fleet procurement demand for ruggedized enterprise devices among construction and logistics contractors. The Communications and Information Technology Commission mandates IMEI registration for all imported devices, creating centralized traceability requirements. Riyadh and Jeddah retail channels concentrate premium foldable sales in mall environments serving status-conscious consumers.
South Africa
Gauteng province's mining operations and logistics companies are accelerating fleet deployments of Android-based field workforce tracking devices. The Independent Communications Authority of South Africa liberalizes sub-6 GHz spectrum access, compressing 5G handset certification timelines. Johannesburg and Cape Town absorb iOS premium positioning while mid-range Android volumes concentrate in township retail networks.
Nigeria
Lagos-based delivery platforms and ride-hailing services mandate smartphone-based dispatch systems, converting feature phone users to touchscreen devices at scale. The National Communications Commission enforces type-approval standards that shape import volumes and local certification timelines. Kano and Ibadan wholesale networks distribute Transsion Holdings' Tecno, Itel, and Infinix brands through established offline credit relationships.
Egypt
The Cairo-Alexandria corridor concentrates young professional demand upgrading from feature phones for mobile banking and gig economy applications. The National Telecom Regulatory Authority tightens testing protocols for 5G devices, extending certification cycles by 6-8 weeks. Industrial development zones in Suez offer tariff exemptions for devices with 30%+ local value addition, rewarding assembly plant investment.
Kenya
Nairobi's M-Pesa integration with smartphone installment plans is hybridizing distribution models, embedding credit access directly into retail channels. The Communications Authority of Kenya manages spectrum allocation frameworks that determine device eligibility requirements. Mombasa port hinterland logistics corridors show sub-35% smartphone penetration, creating first-mover whitespace for budget device entrants.
Middle East and Africa Smartphones Market Competitive Landscape
On the supply side, the industry is tiered across premium ecosystem players, volume-driven assembly specialists, and regional wholesale distributors. Samsung Electronics and Apple occupy premium positioning through Gulf Cooperation Council mall retail and carrier partnerships. Transsion Holdings and Xiaomi anchor mid-range and budget tiers via offline wholesale networks and online flash sales mechanics respectively. Dominant competitive moves include local assembly mandates to secure tariff exemptions and strategic partnerships with mobile money platforms to embed financing into distribution.
Within the premium-tier vector, Samsung Electronics Co., Ltd. and Apple Inc. represent ecosystem-locked positioning with extended software support cycles and tight hardware-software integration. Transsion Holdings Limited exemplifies the volume-driven archetype through multi-brand deployment across West African wholesale networks. Xiaomi Corporation occupies a position between these poles, leveraging online flash sales and local assembly strategies to compress landed costs in currency-volatile markets.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Xiaomi Corporation |
| Transsion Holdings Limited |
| Huawei Technologies Co., Ltd. |
| Infinix Mobility Limited |
| Oppo Guangdong Mobile Communications Co., Ltd. |
| Apple Inc. |
| HMD Global Oy |
| Vivo Communication Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Egyptian assembly plants is compressing supplier margins while simultaneously enabling aggressive retail pricing in Cairo-Alexandria corridor markets. This utilization dynamic forces component distributors to accept extended payment terms from Transsion Holdings and Xiaomi Corporation, transferring working capital pressure upstream while downstream buyers capture sub-$200 price points.
Pricing Analysis
Volume-discount tiering structures separate flagship positioning from mid-range 5G eligibility and entry-level feature phone replacement tiers. Price differentiation hinges on local assembly qualification for Egypt's 30% value-add tariff exemption and MediaTek versus Snapdragon chipset tiering. Cost compression in the budget segment is intensifying because Egyptian pound depreciation inflates landed panel costs. Delivery platform procurement officers in Lagos and Nairobi exhibit highest price sensitivity; Gulf Cooperation Council mall retailers show lowest.
Supply Chain Analysis
Contract-manufacturing concentration rests with Foxconn and BYD Electronics facilities in Morocco and Egypt, supplemented by Transsion's captive assembly in Ethiopia. Component sourcing draws from Chinese AMOLED panel fabricators, South Korean memory suppliers, and Taiwanese chipset foundries. Single-source display dependency creates vulnerability to Red Sea shipping disruptions. Distribution runs through Jumia and Konga flash-sale platforms in Nigeria and Kenya, alongside traditional wholesale credit networks in Kano and Ibadan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa smartphones market sits at a platform-economics inflection where M-Pesa financing integration and Google Mobile Services lock-in are converging to reshape customer acquisition economics. HarmonyOS expansion by Huawei Technologies is fragmenting Android's historical ecosystem dominance.
For Market Incumbents: Entrench position by deepening captive battery supply chains in Moroccan industrial zones and accelerating IMEI-registration compliance ahead of Saudi Arabia's Communications and Information Technology Commission enforcement waves. Defend against Xiaomi's online flash-sale mechanics by consolidating exclusive retail partnerships in Gauteng province mall networks.
For New Entrants and Emerging Players: Pursue whitespace in Ethiopia's Addis-Ababa-Djibouti logistics corridor where smartphone penetration remains below 35% and 2G infrastructure delays incumbent SKU optimization. Target ruggedized Android deployments for South African mining fleet procurement. Anchor go-to-market through M-Pesa-integrated installment financing in Nairobi consumer segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across local assembly operations as Egypt's National Telecom Regulatory Authority tightens 5G certification timelines. Long-term viability favors vertically integrated assemblers with captive component sourcing and tariff-exempt zone access. Monitor ICASA spectrum auction outcomes as inflection signal for sub-6 GHz device eligibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Footprint Expansion | Egypt's Suez Canal Economic Zone tariff exemptions reward 30%+ value-add manufacturing with duty-free EU market access. |
| Mobile Money Platform Integration | M-Pesa and equivalent financing embedment in Kenyan and Nigerian retail channels hybridizes distribution economics. |
| 5G Certification Pre-Positioning | Early alignment with NTRA and TDRA testing protocols compresses seasonal product launch timelines by 6-8 weeks. |
| Ruggedized Enterprise SKU Development | South African mining and Saudi logistics fleet procurement accelerates demand for MIL-STD-810G field devices. |
| Flash Sale Channel Optimization | Jumia and Konga mechanics displace wholesale credit terms in Lagos and Nairobi urban consumer segments. |
Research Methodology
Initial hypotheses were tested against primary input from smartphone OEM procurement directors, national telecommunications regulator officials, mobile money platform executives, and regional wholesale distributors, then refined through secondary validation against TRAI-equivalent spectrum filings, customs import databases, and ICASA regulatory disclosures. Bottom-up shipment estimates from Egyptian and Moroccan assembly plants were triangulated with top-down consumer expenditure surveys across Nigeria and Kenya.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, operating system platform, price tier positioning, end-user procurement archetype, and national spectrum maturity cluster. CAGRs were derived from installed base replacement cycles and first-time buyer conversion rates in underpenetrated corridors. Forecast inputs incorporated lithium-ion supply localization progress and 5G infrastructure rollout cadence from national communications commissions.
Sensitivities concentrate around Egyptian pound and Nigerian naira depreciation trajectories, Red Sea logistics disruption persistence, and ICASA sub-6 GHz auction timing. Forecasts reflect documented assumptions regarding feature phone-to-smartphone migration velocity and gig economy workforce expansion. Quarterly review of NTRA certification queue lengths and M-Pesa financing default rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Tablet Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Europe Cigarette Lighter Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Mouse Pad Market