
 Ereader Market | 2026-2036
Ereader Market Size, Share, and Industry Trends Forecast 2026-2036
Ereader Market Analysis
E-paper display technology is repositioning the economics of ereader manufacturing as color-capable panels replace monochrome alternatives. Amazon leverages vertical integration across content, hardware, and cloud infrastructure to sustain pricing power in premium tiers. Rakuten Kobo differentiates through open-format ecosystem support and library lending integration. Onyx International dominates the professional and academic segment with large-format devices that extend beyond traditional reading use cases.
An ereader is a dedicated electronic device employing electrophoretic display technology, typically measuring six to thirteen inches diagonally, with front-lighting arrays and weeks-long battery endurance designed for extended text consumption. The primary commercial purpose centers on portable, low-power access to digitized books, periodicals, and documents. Color eReaders represent the fastest-growing product type as educational publishers and graphic novel distributors shift content investment toward full-color digital formats. Academic Institutions constitute the most concentrated end-user segment for volume procurement, while Professionals drive margin pools through premium large-format and stylus-enabled configurations. Wi-Fi connectivity remains the standard specification, though 4G LTE variants capture mobile worker segments willing to absorb recurring data costs.
FCC equipment authorization requirements in the United States govern radio-frequency emissions for connected ereader models, while EU RoHS and REACH directives restrict hazardous substances in display assemblies and battery systems sold across Europe. ECHA substance-of-very-high-concern listings are forcing manufacturers to reformulate solder alloys and display encapsulants ahead of compliance deadlines. China's GB standards and MIIT radio-type approval processes shape product specifications for the world's largest production base. Stakeholders must monitor how color e-ink yield rates and regional content licensing fragmentation determine which product configurations merit regional customization investment.
Market Dynamics
E Ink Holdings' Gallery 3 color display technology is compressing monochrome product lifecycles and forcing manufacturers to retool assembly lines for pigment-based electrophoretic panels. This single supply-side pivot is redistributing margin pools across the value chain.
Growth Catalysts
- EU REACH SVHC listings:ECHA-mandated reformulation of solder alloys and encapsulants is accelerating R&D investment in compliant display assemblies, creating first-mover advantages for certified suppliers.
- Academic digital literacy mandates:Multi-device fleet procurement by universities and K-12 districts is generating predictable volume demand with standardized specifications.
- China's MIIT radio-type approval:Streamlined certification pathways for Wi-Fi and 4G LTE variants are reducing time-to-market for connected models targeting mobile worker segments.
Market Restraints
- Input cost volatility:Indium tin oxide and specialized PET substrate prices fluctuate with electronics-grade chemical supply chains concentrated in East Asian refineries.
- Color e-ink yield rates:Manufacturing defect rates for pigment microcapsule alignment remain structurally higher than monochrome equivalents, constraining panel availability.
- Smartphone/tablet substitution:Multi-function devices with OLED displays capture casual readers who prioritize app ecosystem breadth over battery endurance.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for display assembly and finished device production are attracting contract manufacturers to establish non-China supply bases.
- Stylus-enabled large-format configurations:Convergence of capacitive touch and active pen technologies is opening annotation and document-signing workflows in legal and healthcare verticals.
- Library lending platform integration:OverDrive and similar digital lending APIs embedded at firmware level create differentiated channel partnerships with public library systems.
Industry Challenges
- Color calibration certification timelines:Obtaining consistent color accuracy validation across E Ink's Gallery 3, Kaleido, and rival DES display technologies delays product launches by 4-6 months.
- Legacy content format fragmentation:Publishers maintain parallel workflows for fixed-layout EPUB, PDF, and proprietary formats, increasing per-title production costs.
- Specialized electro-optical engineering talent:Scarcity of professionals with e-paper driver IC and front-lighting array design experience constrains OEM engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ereader Market |
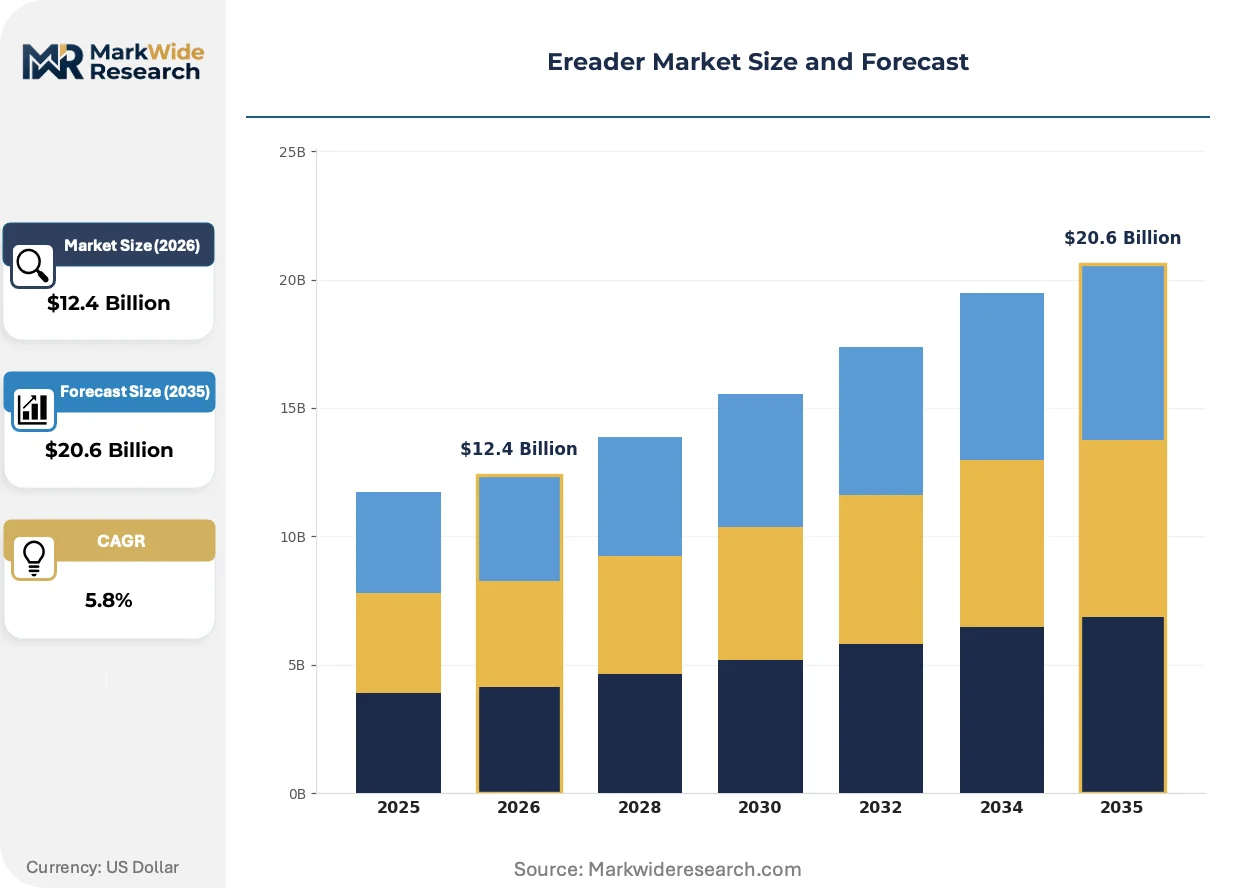
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic eReaders, Premium eReaders, Color eReaders, Multi-function eReaders End User: Students, Professionals, Casual Readers, Academic Institutions Connectivity: Wi-Fi, 4G LTE, Bluetooth, USB Content Type: E-books, Magazines, Newspapers, Audiobooks |
| Companies Covered | Amazon, Rakuten Kobo, Onyx International, Sony, PocketBook International, Barnes & Noble, Bookeen, Hanvon Technology, ReMarkable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ereader Market Emerging Trajectories
Display technology roadmaps, regulatory compliance frameworks, and procurement model evolution are simultaneously reshaping competitive positioning. These three forces operate on different time horizons but intersect in product configuration decisions.
Gallery 3 color electrophoretic technology is automating the transition from monochrome to full-color display stacks in premium education and graphic novel segments. Publishers in Japan and South Korea are adopting color-native workflows ahead of hardware availability. This automation is compressing the viable lifecycle of monochrome-only device portfolios and forcing inventory write-downs at distributors.
China's GB standards for electronic display energy efficiency and MIIT radio-type approval processes are tightening certification requirements for connected ereaders sold domestically. Manufacturers must submit updated test reports for Wi-Fi 6 and emerging 5G variants. The professional mobile worker segment is most affected, with vendors delaying 4G LTE model launches until dual-mode certification completes.
Academic procurement committees are consolidating vendor relationships through multi-year fleet replacement contracts with standardized device specifications. This concentration is displacing fragmented single-unit retail purchases in North American and European higher education. The shift is most visible in California and Texas public university systems, where digital literacy program budgets now cover 10,000-plus device deployments.
Ereader Market Segmentation
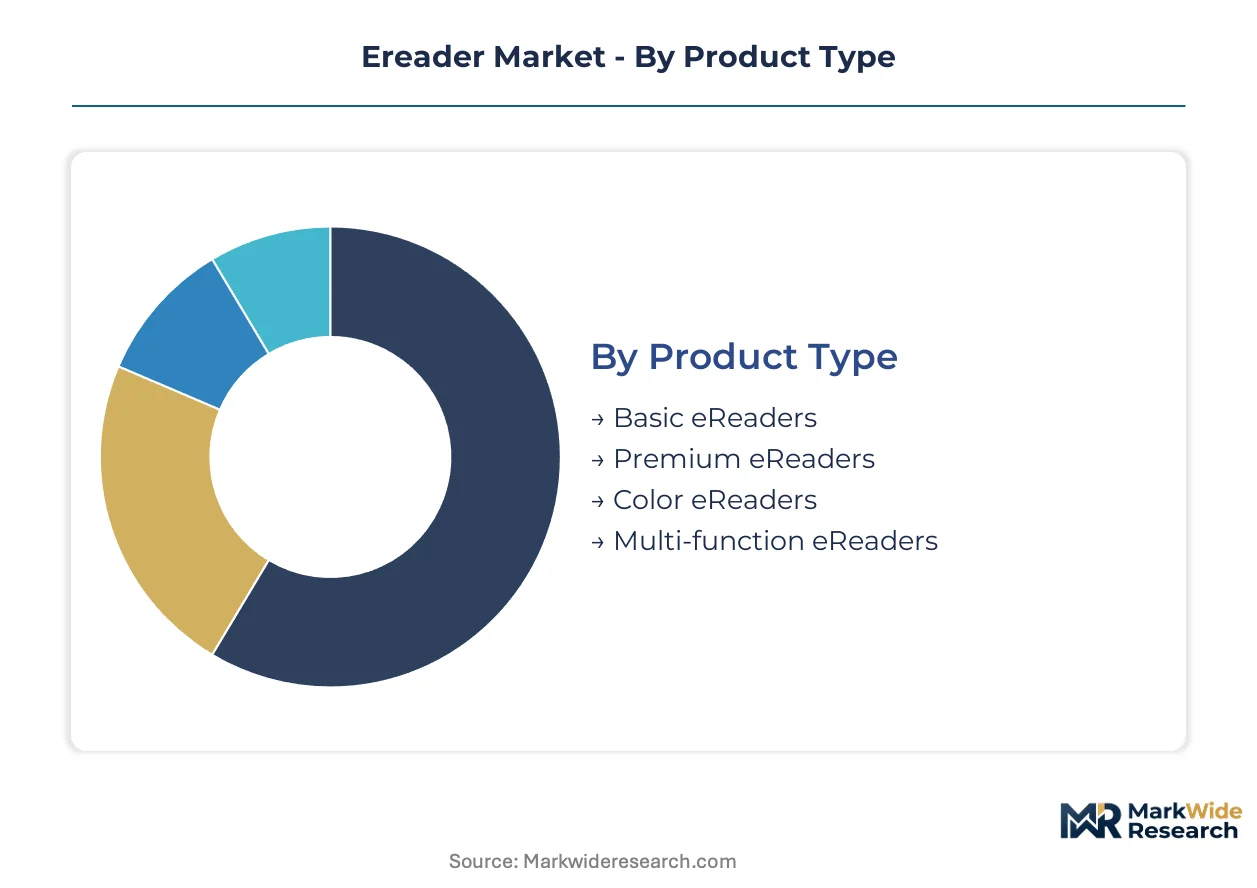
Product configuration decisions in the ereader market hinge on display technology roadmaps, institutional procurement patterns, and content format requirements. Segmentation reveals where margin pools concentrate and which device specifications merit development investment.
Product Type:
Upgrade cycles vary dramatically across price-performance tiers, with color display adoption compressing replacement timelines for legacy monochrome portfolios.
- Basic eReaders:Six-inch monochrome electrophoretic panels with front-lighting arrays dominate volume shipments. Procurement concentrates in Indian and Southeast Asian education ministries seeking standardized fleet deployments with multi-year replacement schedules.
- Premium eReaders:Larger-format devices with adjustable warm-light systems and waterproofing target professionals and heavy readers. Demand clusters in Germany, Japan, and South Korea where consumers absorb price premiums for hardware durability.
- Color eReaders:Gallery 3 pigment microcapsule technology enables educational content and graphic novel consumption.
- Multi-function eReaders:Stylus-enabled configurations with note-taking applications extend beyond reading into document annotation workflows.
Basic eReaders sits at the top of the volume ranking, with Color eReaders climbing the fastest.
End User:
Customer archetypes determine connectivity specifications, content licensing requirements, and support service levels.
- Students:Price-sensitive users requiring durable hardware and annotation capabilities. K-12 districts in Texas and California are consolidating vendor relationships through standardized fleet contracts with multi-year replacement guarantees.
- Professionals:Stylus-enabled large-format devices with document-signing workflows command margin premiums. Legal and healthcare verticals in the United States and United Kingdom drive specifications for encryption and audit-trail compliance.
- Casual Readers:Smartphone substitution pressure is highest in this segment.
- Academic Institutions:Volume procurement with standardized specifications displaces fragmented retail purchases.
Academic Institutions anchor procurement volume, with Professionals generating the steepest expansion trajectory for premium configurations.
Connectivity:
Radio-type approval requirements shape regional product availability and time-to-market for connected variants.
- Wi-Fi:Standard specification across all price tiers with dual-band support increasingly mandatory. China's MIIT certification and India's WPC approval processes govern market entry for Asian manufacturing hubs.
- 4G LTE:Mobile worker segments in the United States and Japan absorb recurring data costs for always-connected document access.
- Bluetooth:Audiobook and peripheral pairing functionality.
- USB:Sideloading and charging interface remaining essential for library lending workflows.
Wi-Fi dominates shipment volume, with 4G LTE gaining share fastest among professional mobile worker segments.
Content Type:
Publisher investment patterns and format fragmentation determine hardware display requirements and storage specifications.
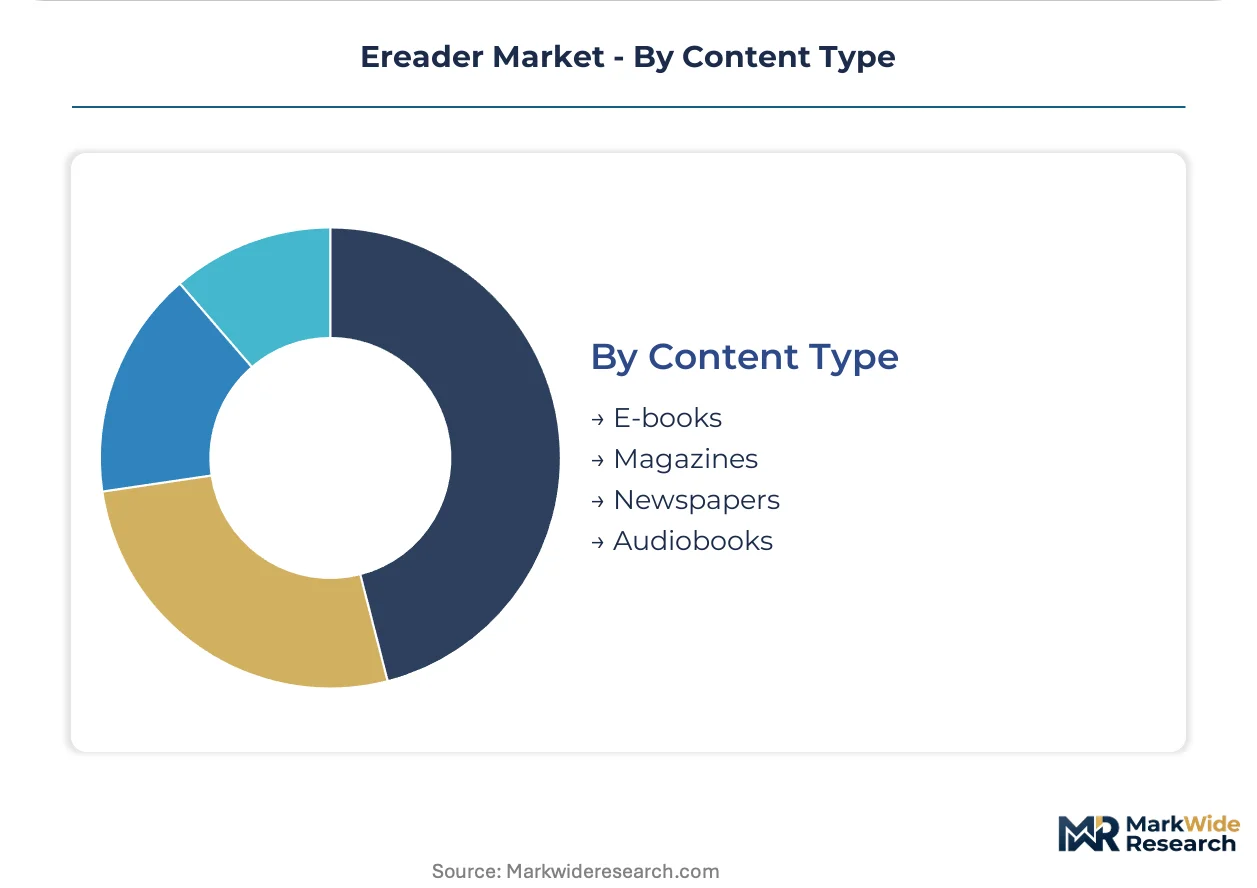
- E-books:Reflowable text formats with adjustable typography remain the core use case. Demand concentrates in public library systems across the United States and Canada integrating OverDrive lending APIs at firmware level.
- Magazines:Fixed-layout color content requires Gallery 3 or Kaleido display technology. Japanese and South Korean publishers are adopting color-native workflows ahead of hardware availability.
- Newspapers:Subscription bundling with daily delivery applications.
- Audiobooks:Bluetooth audio output and speaker integration expanding device utility beyond visual consumption.
E-books commands the largest addressable base, with Magazines showing the most rapid uptake as color panel yields improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the dominant manufacturing cluster for electrophoretic display assembly, with panel fabrication and finished-device production concentrating in the Pearl River Delta's vertically integrated electronics corridor.
United States
Academic fleet procurement by California and Texas public university systems drives institutional volume demand. FCC equipment authorization governs radio-frequency emissions for connected models entering the market. Seattle hosts Amazon's hardware development operations for premium-tier device engineering.
China
Domestic consumption absorbs the majority of global color e-ink panel output as educational publishers shift to full-color workflows. MIIT radio-type approval streamlines certification for Wi-Fi 6 and 4G LTE variants. Beijing anchors Hanvon Technology's research operations for large-format professional devices.
Germany
EU RoHS and REACH directives restrict hazardous substances in display assemblies and battery systems sold across Europe. ECHA substance-of-very-high-concern listings force solder alloy reformulation ahead of compliance deadlines. Berlin clusters hardware distributors serving the Nordic and Central European markets.
Japan
Graphic novel publishers adopt color-native content workflows ahead of hardware availability, compressing monochrome device lifecycles. METI standards for electronic display energy efficiency shape product specifications. Tokyo houses Rakuten Kobo's ecosystem development for open-format library lending integration.
India
Production-linked incentives for electronics manufacturing attract contract manufacturers establishing non-China assembly bases. BIS certification requirements govern safety standards for imported devices. Karnataka's Bangalore corridor hosts software development for firmware-level OverDrive API integration.
Ereader Market Vendor Landscape
Global majors compete with regional champions across content ecosystem integration and hardware specialization dimensions. The vendor base stratifies into three tiers: vertically integrated platform operators controlling content-hardware-cloud stacks, display-technology specialists leveraging E Ink Holdings' panel roadmaps, and regional assemblers serving price-sensitive education ministries. Dominant competitive moves include backward integration into captive display supply and multi-year fleet procurement contracts with academic institutions.
Within the vertically integrated platform tier, Amazon exemplifies the content-hardware-cloud archetype, while Rakuten Kobo occupies a position emphasizing open-format ecosystem support. Among display-technology specialists, Onyx International anchors the professional and academic segment with large-format device configurations. These three companies represent the primary competitive anchors reshaping margin distribution across premium and institutional market tiers.
| Leading Market Players |
|---|
| Amazon |
| Rakuten Kobo |
| Onyx International |
| Sony |
| PocketBook International |
| Barnes & Noble |
| Bookeen |
| Hanvon Technology |
| ReMarkable |
| Others |
Supply Flow & Price Mechanics
E Ink Holdings' Gallery 3 pigment microcapsule transition is simultaneously elevating bill-of-materials costs and concentrating panel procurement leverage among certified assemblers in the Pearl River Delta. This technology pivot feeds pricing stratification across premium color and legacy monochrome tiers while reshaping supplier qualification timelines.
Pricing Analysis
Input-cost pass-through from indium tin oxide and specialized PET substrate volatility runs through finished-device pricing, with premium large-format configurations absorbing margin compression better than economy tiers. Three-tier pricing structure across premium, standard, and economy levels separates stylus-enabled professional devices from basic education fleet units. Pricing pressure stems from color e-ink yield rates constraining panel availability. Academic Institutions exhibit highest price sensitivity through consolidated procurement tenders, while Professionals absorb premiums for encryption-compliant configurations.
Supply Chain Analysis
Single-source vulnerability sits with E Ink Holdings' monopoly on pigment microcapsule electrophoretic technology for color panels. Manufacturing concentrates in China, Taiwan, and South Korea, with Shenzhen's Pearl River Delta corridor anchoring display assembly and finished-device production. Raw material dependencies include indium tin oxide coatings, PET substrates, and lithium-polymer cells. Tariff exposure on electronics imports into the United States and European Union threatens margin structures. Distribution runs through academic procurement committees, consumer electronics retail channels, and direct-to-institution fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ereader Market functions as a stable compounder, with academic digital literacy mandates generating predictable replacement cycles that smooth revenue volatility across economic conditions.
For Market Incumbents: To counter smartphone and tablet substitution in casual reader segments, incumbents should deepen backward integration into captive color panel supply through exclusive E Ink Holdings allocation agreements, while expanding multi-year fleet procurement contracts with Texas and California public university systems to lock in institutional volume. For New Entrants and Emerging Players: Direct-to-institution digital sales channels offer the lowest customer acquisition cost for unproven brands, with India's state education ministries and Southeast Asian K-12 districts representing the most penetrable procurement environments. White-space targets include stylus-enabled healthcare annotation workflows and firmware-embedded OverDrive library lending integration. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers lacking content ecosystem integration but possessing MIIT-certified production capacity. The 5-10 year viability thesis rests on color display adoption sustaining replacement cycle compression. The signal to watch is Gallery 3 yield rate improvements at E Ink Holdings' Hsinchu fabrication facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Gallery 3 Color Panel Allocation Agreement | Secures priority supply from E Ink Holdings for premium education and graphic novel segments. |
| Multi-Year Academic Fleet Contract | Locks in predictable volume with California and Texas public university procurement committees. |
| Firmware-Level Library Lending Integration | Embeds OverDrive APIs to differentiate through public library system channel partnerships. |
| India PLI Scheme Manufacturing Footprint | Establishes non-China assembly base with BIS certification for education ministry tenders. |
| Stylus-Enabled Healthcare Configuration | Targets legal and healthcare verticals with encryption and audit-trail compliance specifications. |
Methodological Framework
Multiple input streams — executive interviews with display technology suppliers, procurement directors at academic institutions, and firmware engineering leads — were reconciled against secondary validation from MIIT certification databases, FCC equipment authorization filings, and ECHA REACH SVHC regulatory updates. Primary fieldwork engaged hardware OEMs, E Ink Holdings distribution partners, and K-12 district technology coordinators. Bottom-up device shipment modeling and top-down content revenue estimates were cross-referenced for triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product type, end-user archetype, connectivity specification, and content format. CAGRs were derived from installed base replacement dynamics and color adoption curve assumptions. Forecast inputs incorporated E Ink Holdings' disclosed panel yield trajectories and academic procurement budget allocations from Texas and California public filings.
The model assumes a particular technology adoption path; alternative pathways for Gallery 3 color electrophoretic diffusion would alter the outlook if Kaleido or rival DES display technologies achieve superior yield economics. Forecasts reflect assumptions about regulatory compliance timelines and content licensing fragmentation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Gaming PC Market