
 Transportation Predictive Analytics Market | 2026-2036
Transportation Predictive Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Predictive Analytics Market Outlook
Germany is tilting toward predictive analytics capacity as its automotive engineering base integrates real-time data layers into logistics and mobility platforms. IBM Corporation leverages deep learning toolkits to anchor enterprise fleet contracts across European road networks. SAP AG sustains dominance in supply-chain prediction through embedded ERP-to-telemetry workflows. Siemens AG specializes in rail and multimodal optimization, controlling a narrow but high-value niche in predictive maintenance for rolling stock.
Transportation predictive analytics applies statistical modeling and machine-learning algorithms to historical and real-time mobility data streams, generating forecasts of asset failure, demand spikes, and network congestion with latency thresholds often below one hundred milliseconds. Its primary commercial purpose is to convert reactive fleet and infrastructure operations into preemptive resource allocation, cutting downtime and energy waste. Route optimization commands the largest share of current deployment value because fuel and labor represent the two largest variable cost pools in logistics. Machine learning is displacing rule-based forecasting fastest in traffic management, where computer-vision fusion with loop-sensor feeds enables sub-minute incident prediction. Cloud computing underpins margin expansion for vendors by collapsing per-customer infrastructure setup from months to days.
The EU AI Act and GDPR constrain how predictive platforms ingest driver-behavior data and biometric traces from in-cab monitoring, pushing vendors toward edge-computing architectures that process sensitive inputs locally. The U.S. DOT and EPA jointly influence adoption through fuel-economy standards and emissions-reporting mandates that reward predictive idling reduction. Stakeholders must monitor whether emerging algorithmic-audit requirements in Brussels and Washington force revalidation of model training sets already deployed across live fleets.
Market Dynamics
Fleet operators face relentless pressure from the EU Green Deal's Fit for 55 framework, which mandates granular emissions accountability across road and rail networks. This regulatory compression is forcing carriers to abandon reactive dispatch models in favor of real-time prediction engines that optimize fuel burn and idle time.
Growth Catalysts
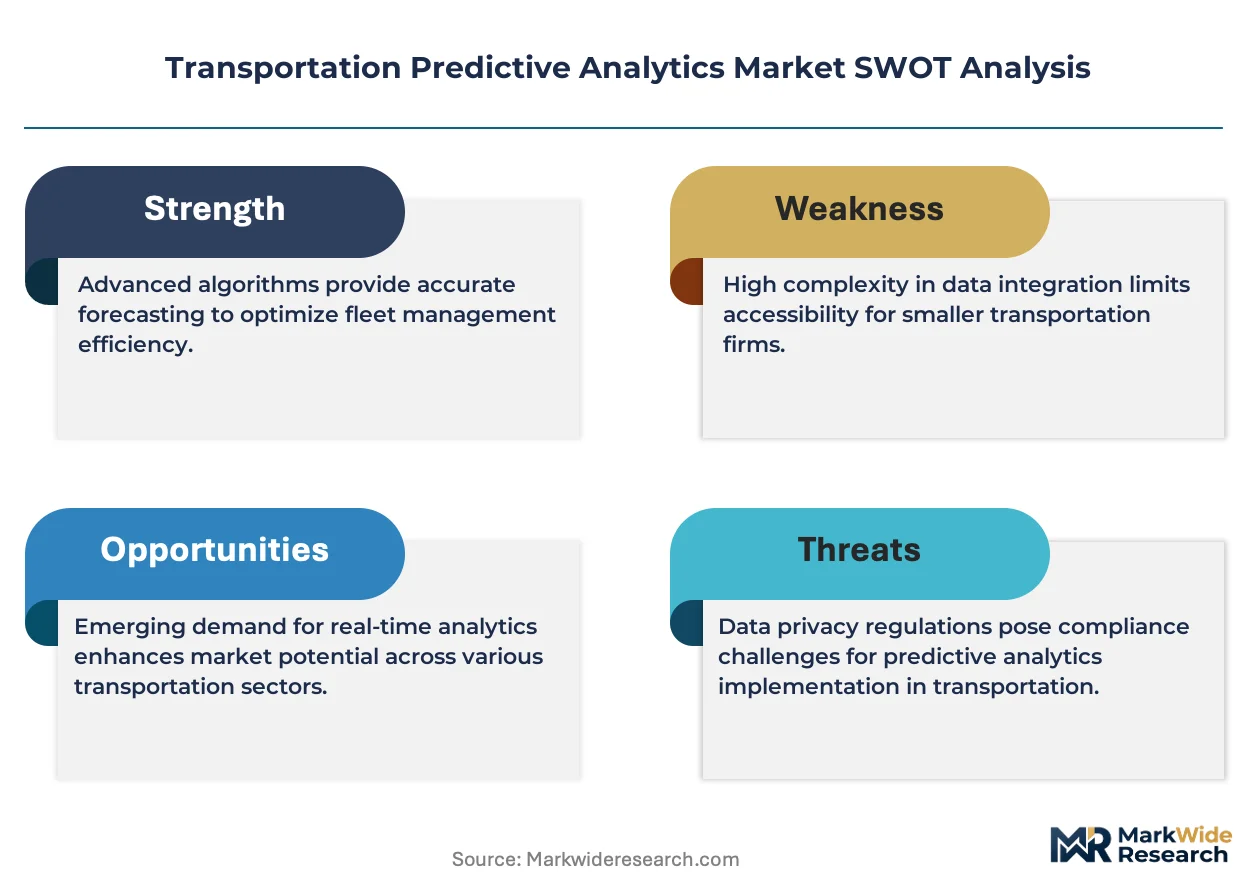
- EU Green Deal stringency:The Fit for 55 framework requires logistics fleets to document route-level emissions, creating mandatory demand for predictive optimization tools that calculate fuel consumption before dispatch.
- Edge computing architectures:GDPR and the EU AI Act restrict centralized processing of driver-behavior data, pushing deployment toward localized inference engines that process biometric inputs within vehicle hardware.
- German automotive engineering concentration:OEMs and Tier-1 suppliers in Stuttgart and Munich are embedding predictive modules into connected-vehicle platforms, creating a captive demand base for multimodal analytics.
Market Restraints
- Semiconductor supply concentration:Specialized AI accelerators for edge inference remain concentrated among Taiwan-based foundries, exposing fleet technology rollouts to foundry capacity constraints.
- GDPR algorithmic-audit friction:The EU AI Act's emerging requirements for training-set revalidation create compliance latency for models already deployed across live commercial fleets.
- Legacy fleet replacement cycles:Heavy-duty trucks operate on 7-10 year replacement timelines, slowing hardware refresh rates necessary for sensor-rich predictive platforms.
Strategic Opportunities
- Rail predictive maintenance white space:European freight rail operators underfit rolling stock with vibration-analysis systems, creating opening for predictive maintenance vendors specializing in axle-bearing and brake-pad failure forecasting.
- Computer-vision traffic fusion:Municipal traffic authorities are converging loop-sensor data with camera feeds to achieve sub-minute incident prediction, opening procurement channels for multimodal analytics providers.
- Cloud infrastructure compression:Containerized deployment models are reducing per-customer setup from months to days, enabling vendors to serve mid-sized freight operators previously excluded from enterprise contracts.
Industry Challenges
- Machine-learning operations talent scarcity:Fleet operators lack in-house expertise to retrain models as traffic patterns shift, creating dependency on vendor-managed MLOps contracts.
- Telematics-ERP integration complexity:SAP-dominated supply-chain environments require custom API development to ingest real-time vehicle telemetry, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Predictive Analytics Market |
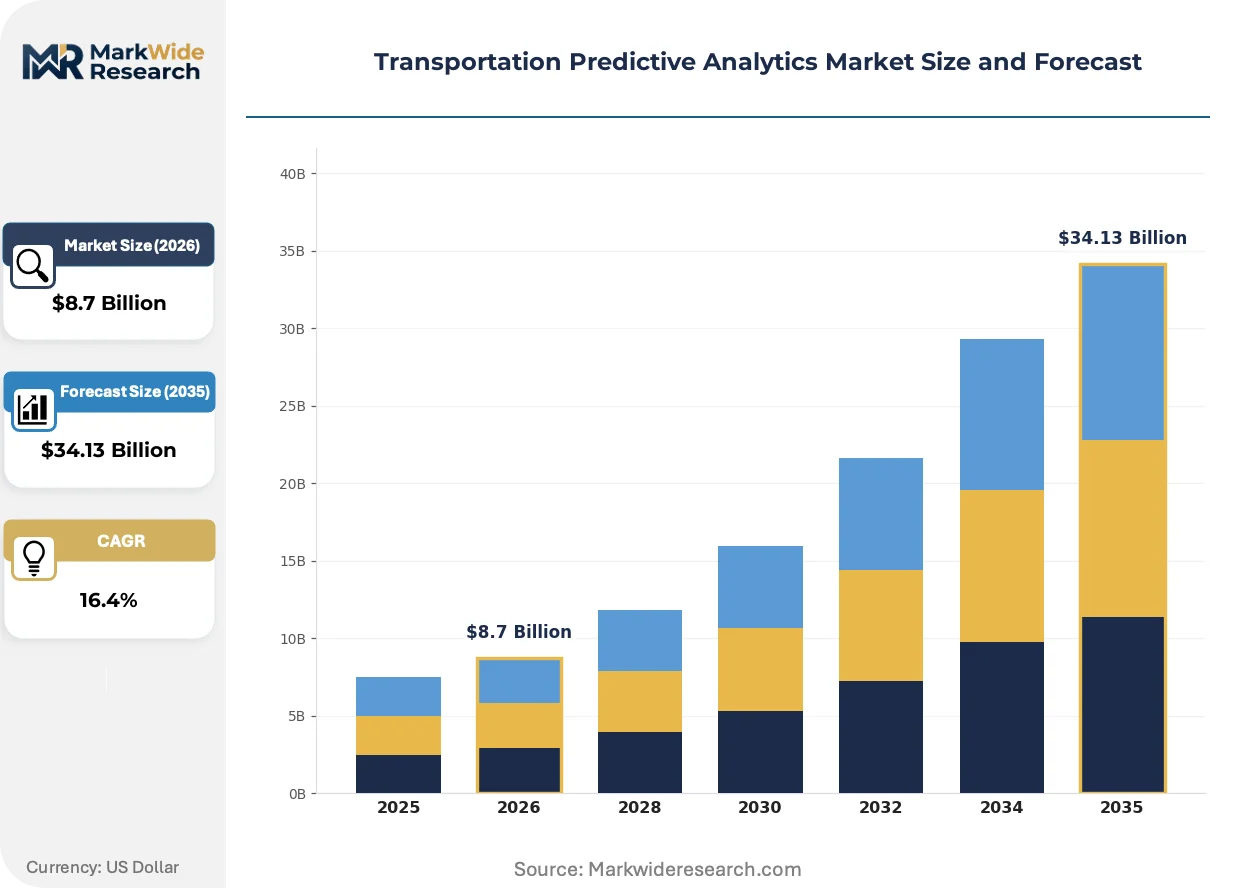
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Route Optimization, Traffic Management, Fleet Management, Demand Forecasting Technology: Machine Learning, Big Data Analytics, Cloud Computing, IoT End User: Logistics Providers, Public Transport Agencies, Automotive Manufacturers, Retail Chains Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | IBM Corporation, SAP AG, Cubic Corporation, PTV Group, Oracle Corporation, Siemens AG, INRIX, T-Systems International GmbH, Cyient Insights Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Predictive Analytics Market Strategic Shifts
Real-time inference architectures are compressing decision latency from minutes to milliseconds, enabling preemptive rather than reactive fleet dispatch. This shift is redrawing competitive boundaries between cloud-centric vendors and edge-first specialists.
Digital twin technology is collapsing the cost structure of fleet simulation. Logistics operators in the Rhine-Ruhr corridor deploy virtual replicas of entire distribution networks to stress-test routing algorithms against weather and congestion scenarios before live deployment. German automotive OEMs now require suppliers to demonstrate model performance within these simulated environments prior to contract award.
The EU AI Act's risk-classification framework is tightening compliance obligations for predictive platforms processing driver-behavior data. Vendors serving cross-border European fleets must now document training-set provenance and algorithmic audit trails, adding legal overhead but creating differentiation for providers with pre-certified edge architectures. French and German regulators are coordinating enforcement timelines, compressing the compliance window for non-compliant systems.
Freight procurement is fragmenting from annual contracts toward spot-market optimization. Small and mid-sized carriers in Poland and the Czech Republic now subscribe to predictive load-matching platforms that forecast demand surges 48-72 hours ahead, displacing traditional freight broker relationships. This behavioral shift concentrates margin pressure on asset-light intermediaries while rewarding fleet operators with proprietary prediction capabilities.
Transportation Predictive Analytics Market Segmentation
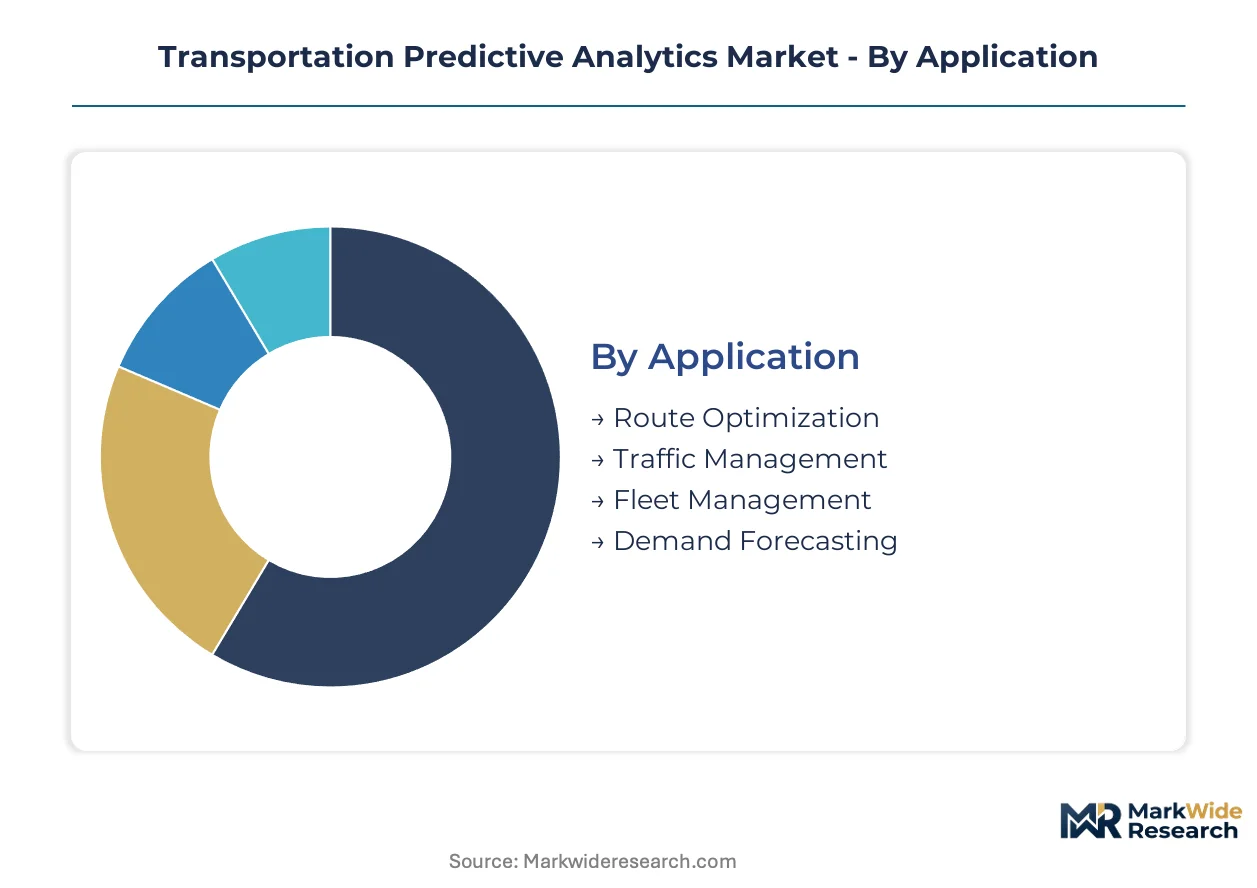
Transportation predictive analytics vendors configure pricing and deployment models around four distinct axes: operational use case, underlying compute architecture, customer industry vertical, and service delivery mode. Each axis carries different margin profiles and implementation complexity, shaping how providers allocate engineering and sales resources.
Application:
Cost tier separates the four application domains, with fuel-sensitive logistics operators driving premium pricing for route-centric modules while municipal buyers constrain traffic management budgets.
- Route Optimization:Algorithms ingest real-time fuel pricing, weather patterns, and road-grade elevation to compute minimum-cost paths for heavy-duty fleets. German automotive OEMs in Stuttgart and Munich embed these modules into connected-vehicle platforms, captive demand from Tier-1 supplier networks sustaining vendor margins.
- Traffic Management:Computer-vision fusion with inductive-loop sensor feeds achieves sub-minute incident prediction latency. Municipal authorities in the Rhine-Ruhr corridor deploy these systems to preempt congestion cascades before they propagate across arterial networks.
- Fleet Management:Predictive maintenance for axle-bearing and brake-pad failure forecasting dominates rail operator procurement in Europe.
- Demand Forecasting:Polish and Czech freight carriers subscribe to 48-72 hour load-matching platforms, displacing traditional broker relationships.
Route optimization commands the established base. The steepest expansion runs through traffic management.
Technology:
Application maturity varies sharply across the four technology layers, with cloud infrastructure now commoditized while edge inference remains capability-constrained.
- Machine Learning:Deep learning toolkits anchor enterprise fleet contracts across European road networks, displacing rule-based forecasting in traffic incident detection. GDPR and the EU AI Act push deployment toward localized inference engines that process biometric inputs within vehicle hardware.
- Big Data Analytics:Historical telemetry aggregation enables pattern recognition across multi-year operational datasets, though training-set revalidation requirements under emerging Brussels mandates create compliance latency.
- Cloud Computing:Containerized deployment models collapse per-customer infrastructure setup from months to days.
- IoT:Sensor-rich predictive platforms face hardware refresh constraints from 7-10 year heavy-duty truck replacement cycles.
Cloud computing holds the volume base. Edge-first architectures are gaining share fastest.
End User:
Customer type determines contract structure, with asset-heavy operators preferring perpetual licenses while asset-light intermediaries favor consumption-based pricing.
- Logistics Providers:Freight operators face EU Green Deal Fit for 55 mandates requiring route-level emissions documentation, forcing abandonment of reactive dispatch models. Edge-computing architectures satisfy GDPR constraints on driver-behavior data processing.
- Public Transport Agencies:Municipal procurement channels converge loop-sensor data with camera feeds for multimodal optimization.
- Automotive Manufacturers:OEMs require suppliers to demonstrate model performance within digital twin environments prior to contract award.
- Retail Chains:Distribution network operators deploy virtual replicas to stress-test routing algorithms against weather scenarios.
Logistics providers anchor current revenue. Public transport agencies show the steepest budget expansion trajectory.
Service Type:
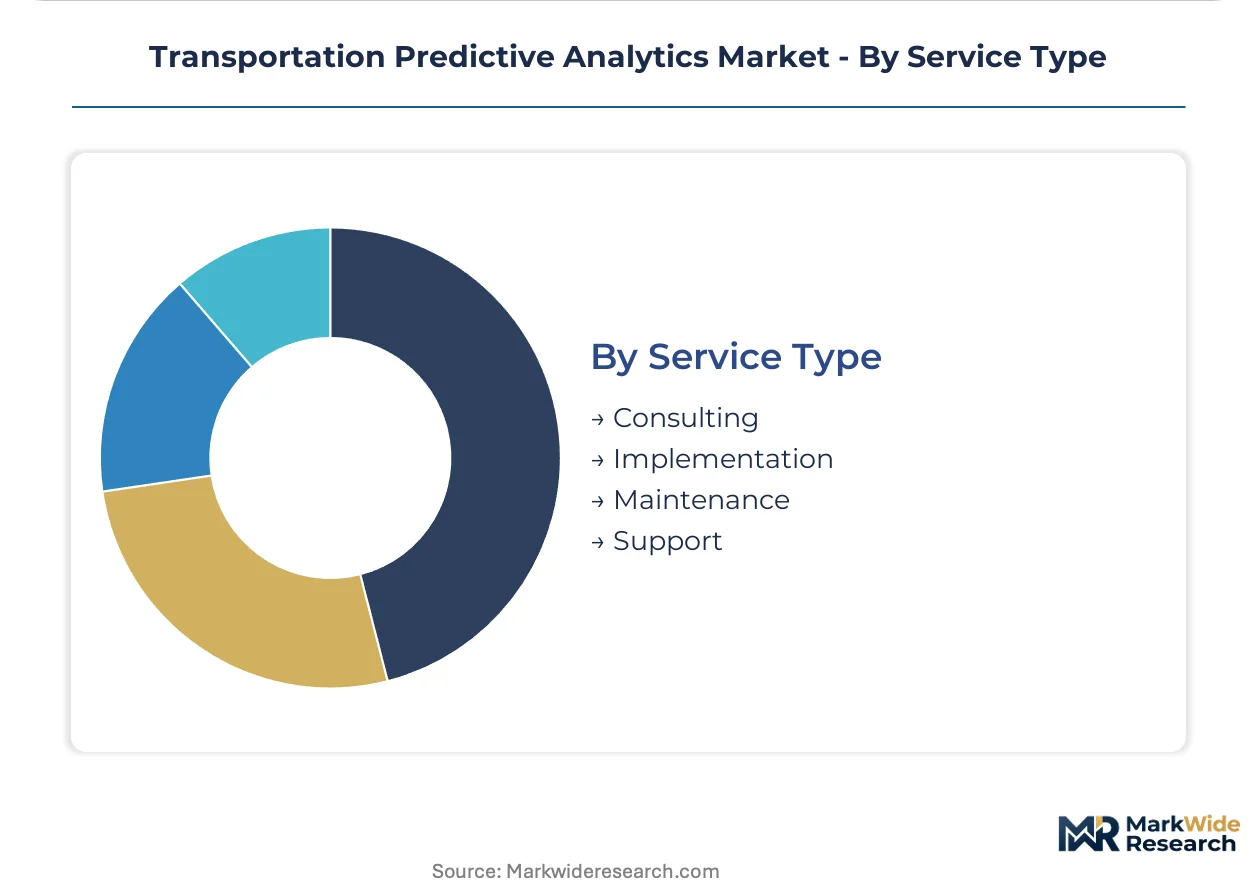
Margin concentration follows the implementation lifecycle, with upfront consulting commanding rate premiums while maintenance contracts sustain recurring revenue.
- Consulting:Custom API development for SAP-dominated supply-chain environments extends implementation timelines, creating billable hours concentration for systems integrators.
- Implementation:Hardware installation and model calibration for sensor-rich platforms faces semiconductor supply concentration among Taiwan-based foundries.
- Maintenance:Vendor-managed MLOps contracts address fleet operator talent scarcity in model retraining.
- Support:Algorithmic audit trail documentation satisfies EU AI Act risk-classification requirements for cross-border European fleets.
Implementation services capture the largest project value. Maintenance contracts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR and the EU AI Act anchor European regulatory gravity, while the U.S. DOT and EPA jointly shape North American adoption through emissions mandates. Demand clusters in Germany, the United States, China, Japan, and the United Kingdom.
Germany
Automotive OEMs and Tier-1 suppliers drive predictive module integration into connected-vehicle platforms. The EU Green Deal's Fit for 55 framework mandates route-level emissions documentation for logistics fleets. Stuttgart and Munich engineering clusters embed real-time data layers into multimodal mobility platforms.
United States
Freight operators deploy predictive fleet tools to cut idle time and fuel burn across interstate networks. The EPA and DOT jointly enforce fuel-economy standards and emissions-reporting mandates that reward predictive idling reduction. Detroit and Dallas-Fort Worth logistics hubs anchor enterprise fleet contract concentration.
China
MIIT and dual carbon goals accelerate smart transport infrastructure investment across provincial highway networks. National standards for connected-vehicle data interoperability push predictive analytics into municipal traffic management procurement. Yangtze River Delta manufacturing clusters integrate supply-chain prediction engines into port-to-factory logistics.
Japan
METI promotes autonomous mobility and logistics efficiency targets through public-private technology partnerships. JIS standards for vehicle telematics create compliance pathways for predictive maintenance platform deployment. Kanto region Tokyo-Yokohama corridor concentrates rail predictive maintenance demand for rolling stock operators.
United Kingdom
Transport for England procurement channels converge loop-sensor and camera-feed data for sub-minute incident prediction. The Department for Transport aligns with EU AI Act risk-classification frameworks for cross-border fleet operations. London and Midlands logistics operators stress-test routing algorithms within digital twin environments.
Transportation Predictive Analytics Market Competitive Environment
Enterprise software conglomerates and specialized industrial-technology providers split the market along capability-depth versus scale-of-deployment axes. Market structure tilts toward consolidated enterprise contracting with narrow specialist niches in multimodal and rail applications. Three archetypes dominate: cloud-centric platform vendors, edge-first inference specialists, and industrial-automation incumbents with captive hardware channels. Competitive moves concentrate on strategic partnerships for telematics-ERP integration and portfolio diversification into predictive maintenance modules.
Within the enterprise-platform tier, IBM Corporation and SAP AG exemplify contrasting strategic positions. IBM leverages deep learning toolkits to anchor fleet contracts across European road networks. SAP sustains dominance through embedded ERP-to-telemetry workflows that address supply-chain prediction demand. Siemens AG occupies a narrow but high-value position in rail and multimodal optimization.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP AG |
| Cubic Corporation |
| PTV Group |
| Oracle Corporation |
| Siemens AG |
| INRIX |
| T-Systems International GmbH |
| Cyient Insights Private Limited |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cloud infrastructure provisioning across North American hyperscaler regions compresses margins for platform vendors while simultaneously lowering entry barriers for mid-sized freight operators seeking predictive analytics subscriptions. This utilization dynamic forces incumbent providers to differentiate through edge-computing hardware bundles and SAP-integrated consulting services rather than pure software licensing.
Pricing Analysis
Geographic price spreads between German automotive OEM contracts and Polish mid-tier carrier subscriptions exceed three-to-one ratios, reflecting divergent customization requirements and compliance overhead. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling digital-twin simulation environments and EU AI Act audit documentation. Price differentiation hinges on certification grade for edge-hardware compliance and volume scale of fleet nodes under management. Pricing pressure stems from containerized deployment commoditizing cloud infrastructure setup. Municipal traffic authorities in the Rhine-Ruhr corridor exhibit highest price sensitivity due to constrained public procurement budgets, while German Tier-1 suppliers demonstrate lowest sensitivity given embedded platform requirements.
Supply Chain Analysis
Export-control regimes restricting AI accelerator chip flows from Taiwan-based foundries to Chinese equipment vendors constrain global availability of edge-inference hardware for predictive fleet platforms. Supply concentrates in Taiwan for specialized semiconductors, Germany for industrial automation components, and the United States for cloud infrastructure software. Raw material dependencies span silicon wafers, rare-earth magnets for sensor assemblies, and high-grade aluminum for vehicle-mounted edge enclosures. Single-source vulnerability around Taiwan-based foundry capacity exposes rollout timelines to geopolitical disruption. Distribution runs through direct enterprise sales for automotive OEMs, systems integrator channels for municipal authorities, and self-service platforms for mid-sized logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around EU AI Act compliance documentation creates sticky vendor relationships difficult for challengers to displace.
For Market Incumbents: Insulate core enterprise fleet contracts by embedding EU AI Act audit-trail capabilities into maintenance service tiers, creating switching costs that bind logistics operators through compliance dependency. Deepen backward integration into edge-computing hardware design to circumvent Taiwan foundry bottlenecks and capture margin otherwise lost to component suppliers. Prioritize SAP API certification investments to accelerate telematics-ERP integration timelines and defend against cloud-native challengers. For New Entrants and Emerging Players: Pursue rail predictive maintenance white space across European freight operators currently underfit with vibration-analysis systems, where incumbent presence remains weakest. Target Polish and Czech mid-sized carriers seeking spot-market load-matching platforms as the most penetrable segment, given their displacement of traditional freight broker relationships. Anchor go-to-market strategy through digital-twin simulation demonstrations that satisfy German OEM supplier qualification requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among edge-first inference specialists with pre-certified GDPR-compliant architectures, positioning them for premium valuation multiples relative to cloud-centric platform vendors. Long-term viability favors vendors controlling proprietary sensor-data pipelines rather than those dependent on third-party telematics feeds. Monitor EU AI Act enforcement coordination between French and German regulators as the signal indicating compliance-window compression that would accelerate consolidation among non-certified providers.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Hardware Certification | Pre-certification against EU AI Act risk classifications accelerates procurement cycles with cross-border European fleets. |
| SAP ERP Integration Partnership | Embedded telemetry-to-ERP workflows reduce implementation friction in supply-chain prediction deployments. |
| Rail Predictive Maintenance Module Launch | Vibration-analysis specialization captures underpenetrated European freight rolling stock operator budgets. |
| Digital-Twin Simulation Platform | Virtual environment demonstrations satisfy German OEM supplier pre-qualification requirements for contract access. |
| Spot-Market Load-Matching Service | Forty-eight-hour demand forecasting displaces traditional freight broker relationships in Polish and Czech markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and hyperscaler capex disclosures. Primary interviews engaged fleet operations directors, municipal traffic authority procurement managers, Tier-1 supplier platform engineers, and edge-computing hardware product managers. Secondary validation drew from EU AI Act implementation guidance, EPA emissions reporting databases, and connected-vehicle telematics standards documentation. Bottom-up sizing of vendor contract values triangulated against top-down macroeconomic freight volume indicators.
Forecast inputs incorporate machine learning application maturity curves, cloud infrastructure cost compression trajectories, and edge-hardware foundry capacity utilization across the analysis window. Segmentation dimensions span operational use case, compute architecture deployment model, customer industry vertical, and service delivery mode. CAGRs derive from logistic function adoption modeling calibrated to regulatory mandate enforcement timelines. Industry-specific inputs include EU Green Deal Fit for 55 compliance cost burdens and heavy-duty truck replacement cycle constraints.
Macroeconomic conditions sit as an overlay; deviation in diesel fuel pricing, semiconductor foundry utilization, or cross-border freight volumes would shift the trajectory. Forecasts assume stable regulatory enforcement coordination between Brussels and member-state authorities. Material shifts in Taiwan export-control enforcement or EU AI Act risk-classification expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
North America Vehicle Tolling System Market