
 United States Pet Market | 2026-2036
United States Pet Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pet Market Analytics
Millennial and Gen Z household formation is recalibrating companion animal ownership patterns toward premium nutrition and subscription-based care. Chewy dominates online pet product distribution through automated replenishment and telehealth integrations. Mars Petcare anchors wet and dry cat food manufacturing with vertically controlled supply chains. Nestlé Purina PetCare differentiates through prescription diet formulations and veterinary channel partnerships.
The United States Pet Market encompasses commercial production and distribution of food, supplies, medical services, and care solutions for domesticated companion animals, typically formulated to AAFCO nutritional adequacy profiles and manufactured through extrusion, retorting, or cold-pressed processes to preserve micronutrient density. Dog food and cat food command the largest revenue pools, though pet treats generate disproportionate margins due to functional ingredient premiums. E-commerce distribution channels are displacing supermarket shelf space fastest, while specialty pet shops sustain high-margin grooming and training service bundling.
The FDA's Center for Veterinary Medicine enforces pet food labeling and ingredient safety standards, while state agriculture departments conduct feed facility inspections that shape manufacturer compliance costs. USDA APHIS regulates interstate animal health certification, affecting breeder supply chains and veterinary clinic biosecurity protocols. Stakeholders must monitor state-level veterinary practice act reforms that could expand telemedicine prescribing authority and reshape service delivery economics.
Market Dynamics
Humanization of companion animals is restructuring expenditure patterns across food, diagnostics, and preventive care, with households now allocating discretionary income previously reserved for human family members toward veterinary wellness plans and functional nutrition formulations.
Growth Catalysts
- Veterinary channel expansion:The FDA's Center for Veterinary Medicine has streamlined telemedicine prescribing protocols, enabling remote consultation models that extend specialist access into underserved rural counties and secondary metro corridors.
- Functional ingredient premiums:Probiotic and omega-3 enriched formulations command shelf space displacement as pet owners prioritize digestive health and coat quality claims validated through AAFCO feeding trials.
- California and Texas metro concentration:Dual-income household density in Los Angeles, San Francisco, Dallas, and Austin generates disproportionate demand for subscription-based replenishment and same-day delivery logistics.
Market Restraints
- Protein input cost volatility:Rendering supply fluctuations and human-grade meat diversion pressures wet food margin structures, particularly for mid-tier manufacturers without captive slaughterhouse contracts.
- Midwestern manufacturing concentration:Kansas, Iowa, and Nebraska host over sixty percent of extrusion capacity, creating single-point vulnerability to freight rate spikes and weather-related distribution interruptions.
- Veterinary workforce scarcity:American Veterinary Medical Association data documents persistent DVM graduate shortfalls relative to clinic demand, extending appointment wait times and compressing service revenue per patient.
Strategic Opportunities
- Prescription diet telehealth bundling:State veterinary practice act reforms in Florida and Ohio are expanding remote prescribing authority, creating regulatory tailwinds for integrated nutrition-and-care subscription platforms.
- Senior pet therapeutic nutrition:Kidney-support and joint-mobility formulations for animals aged eight-plus represent underpenetrated white space as demographic aging accelerates across the owned pet population.
- Cold-pressed and freeze-dried formats:Raw and minimally processed alternatives are absorbing shelf space from conventional kibble in Pacific Northwest and Northeast urban markets where human food values transfer to purchase decisions.
Industry Challenges
- Veterinary technician certification bottlenecks:NAVTA-credentialed training program capacity constraints limit clinic scaling velocity, particularly for multi-location rollouts in secondary markets.
- Legacy ERP integration friction:Independent retailers and regional distributors face capex barriers when migrating inventory management systems to support automated replenishment APIs demanded by platform partners.
- Ingredient provenance verification:USDA APHIS interstate health certificate requirements and state feed facility inspection schedules create compliance timeline uncertainty for suppliers sourcing across multiple agricultural zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pet Market |
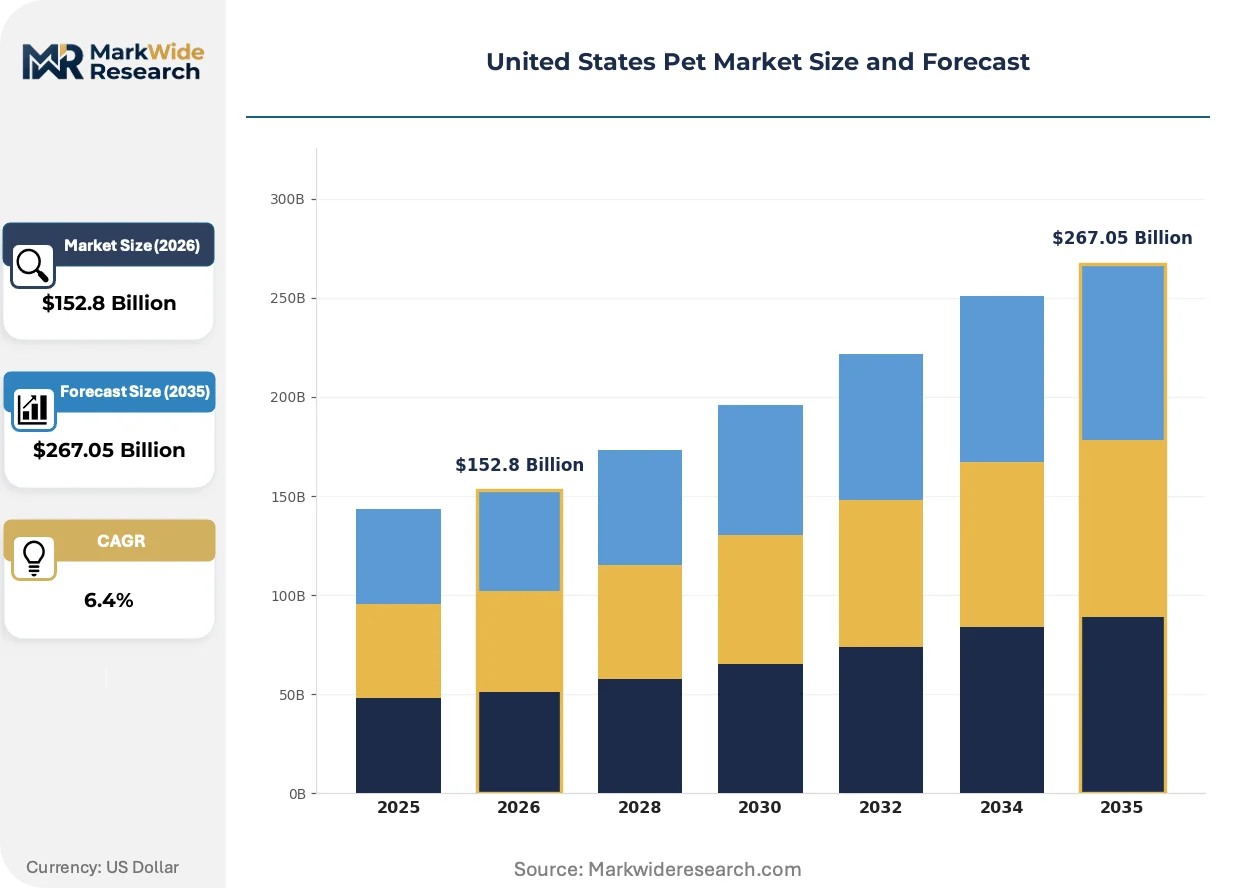
| Market Size in 2026 | $152.8 Billion |
| Market Size in 2035 | $267.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dog Food, Cat Food, Pet Accessories, Pet Treats Customer Type: Pet Owners, Veterinarians, Pet Stores, Online Retailers Distribution Channel: Supermarkets, Specialty Pet Shops, E-commerce, Veterinary Clinics Service Type: Grooming, Training, Boarding, Vet Services |
| Companies Covered | Chewy, Hill's Pet Nutrition, Mars Petcare, Diamond Pet Foods, General Mills, Nestlé Purina PetCare, J.M. Smucker, Central Garden & Pet, PetSmart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pet Market Evolving Landscape
Digital infrastructure and shifting household formation patterns are compressing traditional channel hierarchies while elevating transparency and personalization as purchase determinants across all price tiers.
Artificial intelligence-driven diagnostic tools are absorbing capital allocation from conventional imaging equipment. Veterinary clinics in metropolitan corridors deploy machine-learning radiograph interpretation to extend specialist reach without full-time radiologist employment. This technology is absorbing mid-tier diagnostic revenue pools and compressing regional referral network economics.
The FDA's Center for Veterinary Medicine has intensified scrutiny of grain-free diet formulations following dilated cardiomyopathy correlation studies, triggering reformulation cycles across dry food portfolios. Manufacturers are responding by reintroducing traditional carbohydrate sources and submitting expanded feeding trial documentation to substantiate cardiac safety claims.
Subscription-based replenishment models now capture substantial volume in consumables categories, displacing supermarket and big-box purchase occasions. Millennial and Gen Z households in coastal metro areas demonstrate highest propensity for automated delivery scheduling, with telehealth integration further locking in platform loyalty through consolidated service access.
United States Pet Market Segmentation
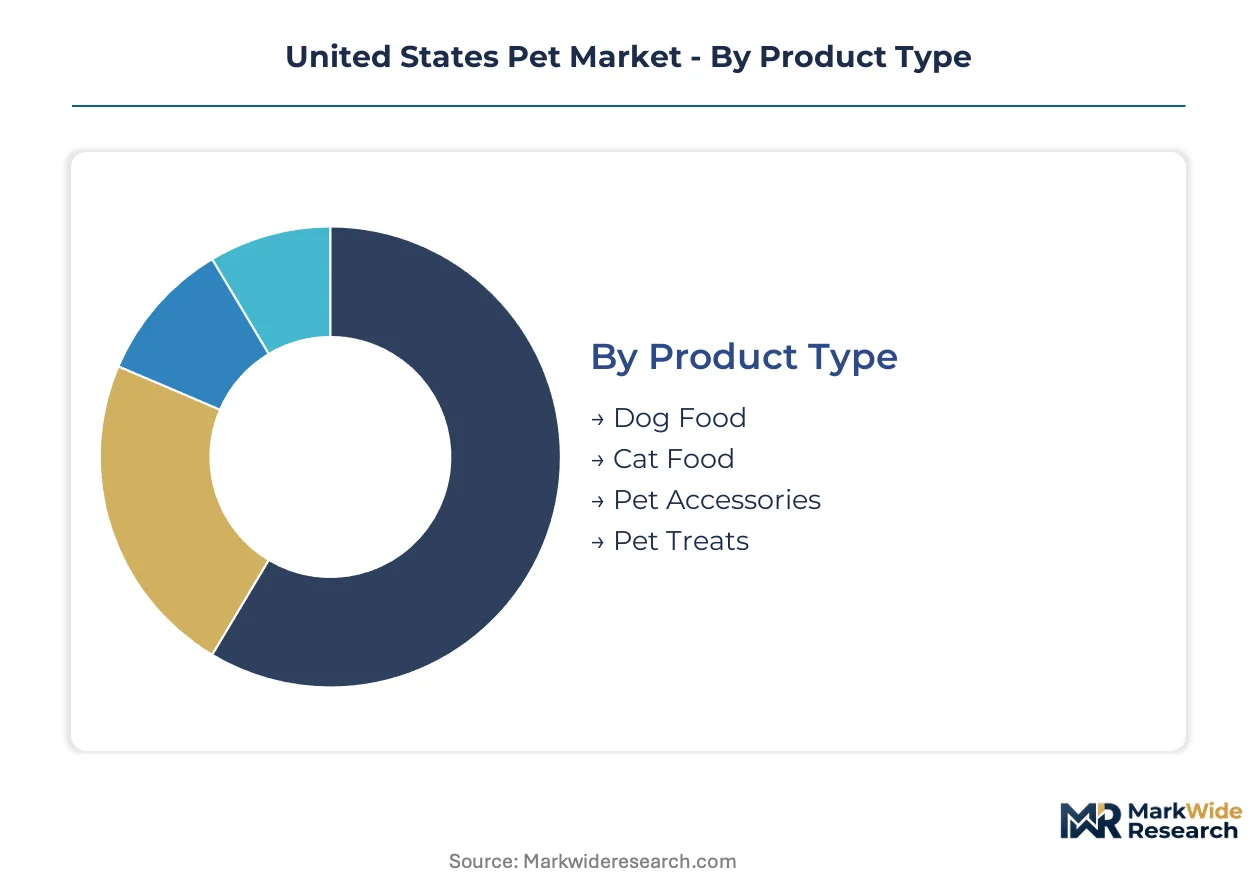
Segmentation in the United States Pet Market reveals how regulatory requirements, channel economics, and household formation patterns concentrate margin capture across distinct product and service categories. Understanding these divisions clarifies where FDA compliance burdens, state veterinary practice acts, and distribution infrastructure investments reshape competitive positioning.
Product Type:
AAFCO nutritional adequacy profiles and FDA Center for Veterinary Medicine labeling standards impose tiered compliance costs across formulations, with therapeutic and grain-free variants triggering enhanced feeding trial documentation.
- Dog Food:Extruded kibble and wet retorted formulations dominate tonnage, with functional ingredient premiums for digestive health and joint mobility concentrating demand in California and Texas dual-income households. Protein input volatility from rendering supply fluctuations compresses margins for mid-tier manufacturers lacking captive slaughterhouse contracts.
- Cat Food:Wet formulations command disproportionate shelf space investment from Mars Petcare and Nestlé Purina PetCare, driven by obligate carnivore nutritional requirements and higher palatability thresholds. Prescription diet formulations for renal and urinary health generate recurring revenue through veterinary channel partnerships.
- Pet Accessories:Collars, leashes, bedding, and containment systems face lower regulatory barriers but higher SKU fragmentation, with e-commerce platforms absorbing volume through automated replenishment bundling.
- Pet Treats:Functional ingredient claims for dental health and training reinforcement support margin premiums, though FDA scrutiny of jerky imports and additive safety has intensified supplier verification protocols.
Leading the category by volume: Dog Food. Growing fastest: functional ingredient-enriched Cat Food formulations.
Customer Type:
Purchasing authority and margin capture diverge sharply between emotionally driven household decision-makers and clinically oriented professional intermediaries who control prescription-access categories.
- Pet Owners:Millennial and Gen Z households in coastal metros demonstrate highest subscription platform attachment, consolidating food, treats, and telehealth access through Chewy and similar integrated providers. Humanization trends redirect discretionary income toward premium nutrition and preventive care.
- Veterinarians:Prescription diet authorization and diagnostic service bundling concentrate influence over therapeutic nutrition and chronic disease management, with state practice act reforms in Florida and Ohio expanding remote prescribing authority.
- Pet Stores:Specialty retailers sustain high-margin service bundling through grooming and training appointment anchoring, though legacy ERP integration friction limits automated replenishment API adoption.
- Online Retailers:Platform economics favor consolidated demand aggregation, with same-day delivery logistics investments concentrating in Los Angeles, San Francisco, Dallas, and Austin corridor density.
Pet Owners generate absolute volume. Veterinarians control the steepest expansion trajectory through prescription diet telehealth bundling.
Distribution Channel:
Channel selection determines compliance exposure, with veterinary clinics facing USDA APHIS interstate health certificate requirements and supermarkets navigating FDA food facility registration mandates.
- Supermarkets:Mass-market kibble and mid-tier wet food occupy shrinking shelf space as e-commerce displaces routine replenishment occasions, though club store formats retain volume through private label aggregation.
- Specialty Pet Shops:Grooming and training service bundling sustains foot traffic and margin capture, with cold-pressed and freeze-dried formats absorbing disproportionate shelf space in Pacific Northwest and Northeast urban markets.
- E-commerce:Automated replenishment algorithms and telehealth integration lock in platform loyalty, with Chewy dominating through veterinary partnership networks and same-day delivery infrastructure.
- Veterinary Clinics:Prescription diet exclusivity and diagnostic service anchoring concentrate therapeutic nutrition revenue, though DVM workforce scarcity extends appointment wait times and compresses patient throughput.
E-commerce is gaining share fastest. Veterinary Clinics retain the highest margin per transaction.
Service Type:
Service delivery economics hinge on labor credentialing requirements, with NAVTA-certified technician bottlenecks constraining clinic scaling velocity across multi-location rollouts.
- Grooming:High-frequency appointment scheduling generates recurring revenue with lower capital intensity than medical services, though technician wage pressure in metro corridors compresses operating margins.
- Training:Behavioral modification and obedience programming concentrate demand among first-time pet owners, with subscription-based group class models displacing individual session economics.
- Boarding:Capacity constraints in secondary markets create regional pricing premiums, with biosecurity protocol investments driven by USDA APHIS interstate health certification requirements affecting breeder supply chain integration.
- Vet Services:Preventive care plans and chronic disease management anchor lifetime value calculations, with AI-driven radiograph interpretation extending specialist reach without full-time radiologist employment in metropolitan corridors.
Vet Services dominate revenue contribution. Grooming expands most quickly through platform bundling with consumables subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in California and Texas concentrate pet industry investment through state tax credits and workforce development grants that anchor manufacturing and distribution infrastructure.
California
Los Angeles and San Francisco metro corridors generate disproportionate subscription platform demand from Millennial and Gen Z households. The California Department of Public Health enforces feed facility inspection schedules that shape manufacturer compliance timelines. San Diego anchors specialty veterinary diagnostic clusters where AI-driven radiograph interpretation extends specialist reach.
Texas
Dallas and Austin dual-income density drives same-day delivery logistics investment and automated replenishment adoption. Texas Department of State Health Services veterinary practice act reforms expand telemedicine prescribing authority into rural counties. Houston hosts cold-pressed and freeze-dried format distribution hubs serving Gulf Coast markets.
Midwest Manufacturing Belt
Kansas, Iowa, and Nebraska concentrate over sixty percent of extrusion capacity for dry kibble production. State agriculture departments conduct feed facility inspections that determine manufacturer operating schedules. Omaha anchors rendering supply chain coordination that buffers protein input cost volatility for wet food formulations.
Florida
Senior pet therapeutic nutrition demand concentrates in Tampa and Miami retirement corridors with aging companion animal populations. Florida Board of Veterinary Medicine reforms enable prescription diet telehealth bundling through expanded remote prescribing authority. Orlando supports multi-location veterinary clinic rollouts constrained by NAVTA-certified technician training bottlenecks.
Pacific Northwest
Seattle and Portland urban markets absorb disproportionate shelf space for raw and minimally processed alternatives. Washington State Department of Agriculture enforces biosecurity protocols affecting interstate breeder supply chain integration. Boise anchors regional distribution for freeze-dried format penetration into Mountain West secondary markets.
United States Pet Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration and platform economics determining margin capture. The market structures around three tiers: multinational CPG conglomerates with captive supply chains, pure-play pet specialists with veterinary channel anchoring, and platform-native distributors with telehealth integration. Consolidation pressure concentrates among mid-tier manufacturers lacking protein sourcing contracts or automated replenishment infrastructure. Dominant competitive moves include prescription diet portfolio diversification and same-day delivery logistics partnerships.
Within the multinational CPG tier, Mars Petcare and Nestlé Purina PetCare exemplify vertically integrated supply chain control over wet and dry formulation production. Among platform-native distributors, Chewy occupies the automated replenishment and telehealth integration position that locks in coastal metro household loyalty. These three companies represent distinct archetypes: manufacturing scale, veterinary channel exclusivity, and digital infrastructure consolidation.
| Leading Market Players |
|---|
| Chewy |
| Hill's Pet Nutrition |
| Mars Petcare |
| Diamond Pet Foods |
| General Mills |
| Nestlé Purina PetCare |
| J.M. Smucker |
| Central Garden & Pet |
| PetSmart |
| Others |
Value Network & Pricing Analysis
Millennial and Gen Z subscription households in coastal metros anchor demand concentration that props premium pricing for automated replenishment and same-day delivery tiers. Protein input volatility from rendering supply fluctuations compresses wet food margins, while cold-pressed format premiums absorb shelf space displacement in Pacific Northwest and Northeast urban corridors.
Pricing Analysis
Short lead-time premiums for same-day delivery logistics concentrate in Los Angeles, San Francisco, Dallas, and Austin corridor density. Three-tier pricing structure across premium, standard, and economy levels stratifies by functional ingredient density and AAFCO feeding trial documentation. Cost compression in mid-tier wet food is intensifying because rendering supply fluctuations pressure manufacturers lacking captive slaughterhouse contracts. Price-sensitive mass-market kibble buyers in supermarket channels contrast with least-sensitive veterinary clinic customers purchasing prescription diet formulations.
Supply Chain Analysis
Returns and refurbishment flows for pet accessories concentrate through e-commerce platform reverse logistics networks, with bedding and containment systems generating highest return velocity. Manufacturing draws from Kansas, Iowa, and Nebraska extrusion capacity for dry kibble, plus Midwest rendering facilities for wet food protein inputs. Single-source vulnerability centers on over sixty percent extrusion capacity clustering in the Midwest Manufacturing Belt. Distribution runs through Chewy's automated replenishment infrastructure and veterinary clinic direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary workforce scarcity constrains clinic scaling velocity, propping service pricing power and extending appointment wait times across secondary metro corridors.
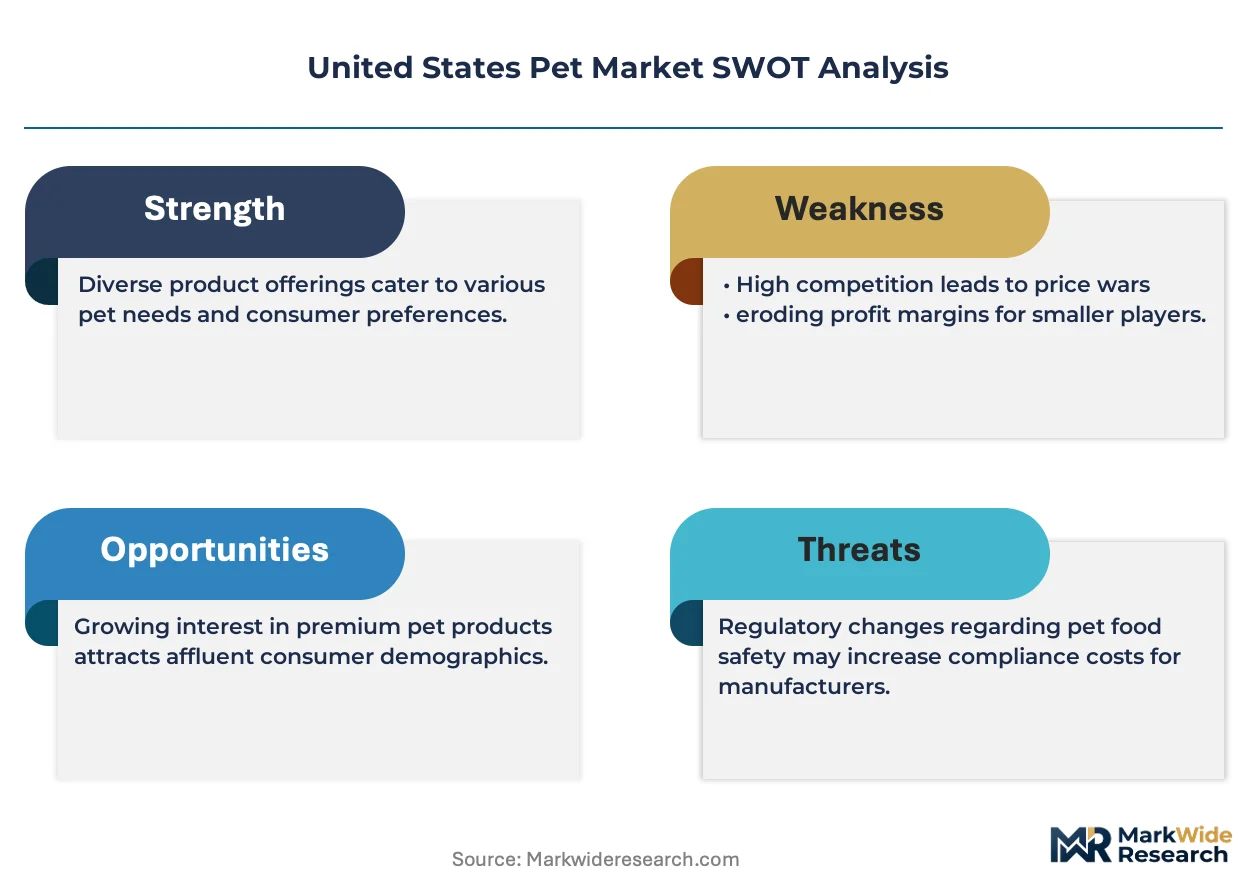
For Market Incumbents: Extend prescription diet portfolio diversification into kidney-support and joint-mobility formulations for animals aged eight-plus. Deepen backward integration into captive slaughterhouse contracts to buffer protein input cost volatility. Mars Petcare and Nestlé Purina PetCare should consolidate telehealth partnership networks before state veterinary practice act reforms in Florida and Ohio mature competitive access. For New Entrants and Emerging Players: Enter via senior pet therapeutic nutrition white space in Tampa and Miami retirement corridors where aging companion animal populations concentrate. Target Pacific Northwest and Northeast urban markets for cold-pressed and freeze-dried format penetration where human food values transfer to purchase decisions. Deploy subscription-based grooming and training bundling to anchor platform loyalty without competing head-to-head against Chewy's automated replenishment infrastructure. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with protein sourcing contracts and NAVTA-certified technician training programs. Long-term viability hinges on regulatory tailwinds from telemedicine prescribing authority expansion and functional ingredient premium absorption. Monitor FDA Center for Veterinary Medicine grain-free diet reformulation mandates as inflection indicator for portfolio repositioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription Diet Telehealth Bundling | Florida and Ohio regulatory reforms expand remote prescribing authority for integrated platforms. |
| Backward Integration into Rendering | Captive slaughterhouse contracts buffer protein input volatility pressuring wet food margins. |
| Cold-Pressed Format Shelf Space Expansion | Pacific Northwest and Northeast urban markets absorb raw alternatives displacing conventional kibble. |
| AI-Driven Diagnostic Deployment | Machine-learning radiograph interpretation extends specialist reach without full-time radiologist employment. |
| NAVTA-Certified Technician Program Scaling | Training capacity expansion unlocks multi-location clinic rollouts in secondary markets. |
Research Methodology
Multi-period observation of subscription platform attachment rates and veterinary channel prescription volumes anchored the trend analysis, supplemented by interviews with pet food manufacturing executives, veterinary clinic operators, specialty retail category managers, and e-commerce logistics directors. Secondary validation drew from FDA Center for Veterinary Medicine filings, AAFCO feeding trial documentation, state veterinary practice act reform records, and USDA APHIS interstate health certificate data. Bottom-up SKU-level volume aggregation and top-down household expenditure survey triangulation cross-checked segment sizing.
Input-output matrix modeling connected protein rendering supply fluctuations to wet food margin compression and subscription renewal elasticity to customer lifetime value projections across the analysis window. Segmentation dimensions included product type, customer archetype, distribution channel, and service category. CAGRs derived from trend extrapolation of Millennial and Gen Z household formation patterns and aging pet demographic trajectories. Industry-specific forecast inputs incorporated NAVTA-certified technician training program capacity and state-level telemedicine prescribing authority expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA grain-free diet reformulation mandates and Midwest weather-related distribution interruptions. Practitioners should monitor protein rendering supply contract renegotiations and state veterinary practice act reform passage for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Apparel Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Dog Treats Market
Pet Care Products
Organic Dog Food Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
South Africa Pet Food Market
Pet Care Products
Bird Toy Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Natural Cat Litter Products Market