
 Dog Crate Furniture Market | 2026-2036
Dog Crate Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Crate Furniture Market Analytics
Direct-to-consumer channels is rewriting how dog crate furniture reaches end buyers, bypassing traditional pet specialty retail gatekeepers. MidWest Homes for Pets leverages its established veterinary and shelter relationships to sustain institutional volume. Yaheetech anchors the mass-market e-commerce tier with price-competitive metal and wooden designs. Ritzman's Amish Furniture differentiates through handcrafted solid-wood construction and domestic manufacturing credibility.
Dog crate furniture denotes enclosures engineered to house canines while integrating aesthetically with residential interiors, typically constructed from solid hardwood, engineered wood composites, powder-coated steel, or reinforced polymers with ventilation apertures and secure latching mechanisms. These units serve dual commercial purposes: containment compliance for training and travel protocols, plus interior design compatibility that eliminates visual conflict with household furnishings. Wooden crates and furniture-style crates command the dominant margin pools as consumers trade up from utilitarian metal cages, while metal crates retain volume leadership in veterinary and shelter procurement where durability and sanitization dominate purchasing criteria. The design style dimension shows modern and minimalist variants accelerating fastest among millennial and Gen Z pet owners prioritizing Scandinavian and Japandi interior aesthetics.
The Consumer Product Safety Commission monitors tip-over and entrapment hazards for furniture-integrated pet enclosures, while California's Air Resources Board enforces stringent formaldehyde limits on composite wood substrates used in domestic production. The EPA Toxic Substances Control Act provisions additionally govern volatile organic compound emissions from finishes and adhesives, pressuring manufacturers toward water-based coating systems and certified sustainable lumber sourcing. Stakeholders must monitor evolving state-level chemical disclosure requirements and third-party sustainability certifications as these standards increasingly filter into retailer procurement mandates and consumer purchase criteria.
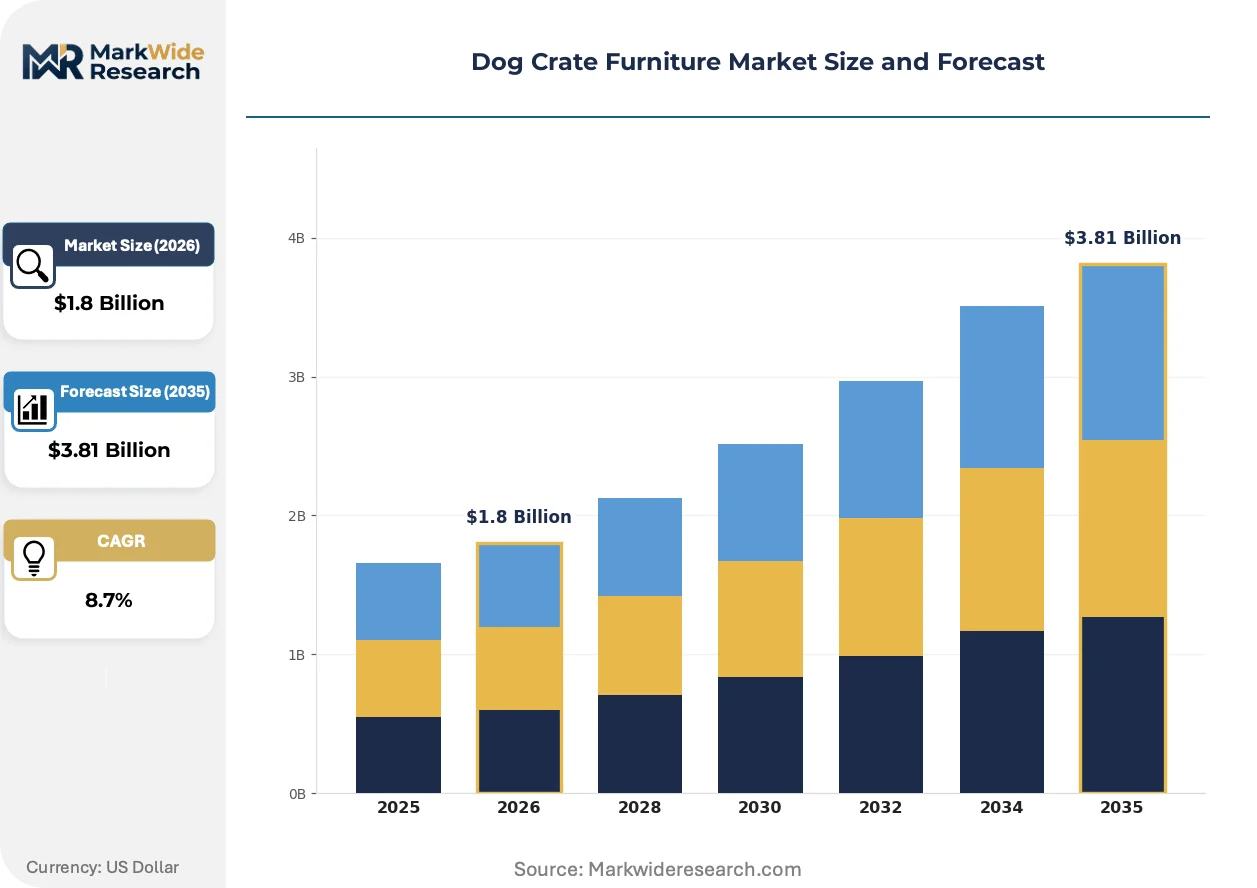
Market Dynamics
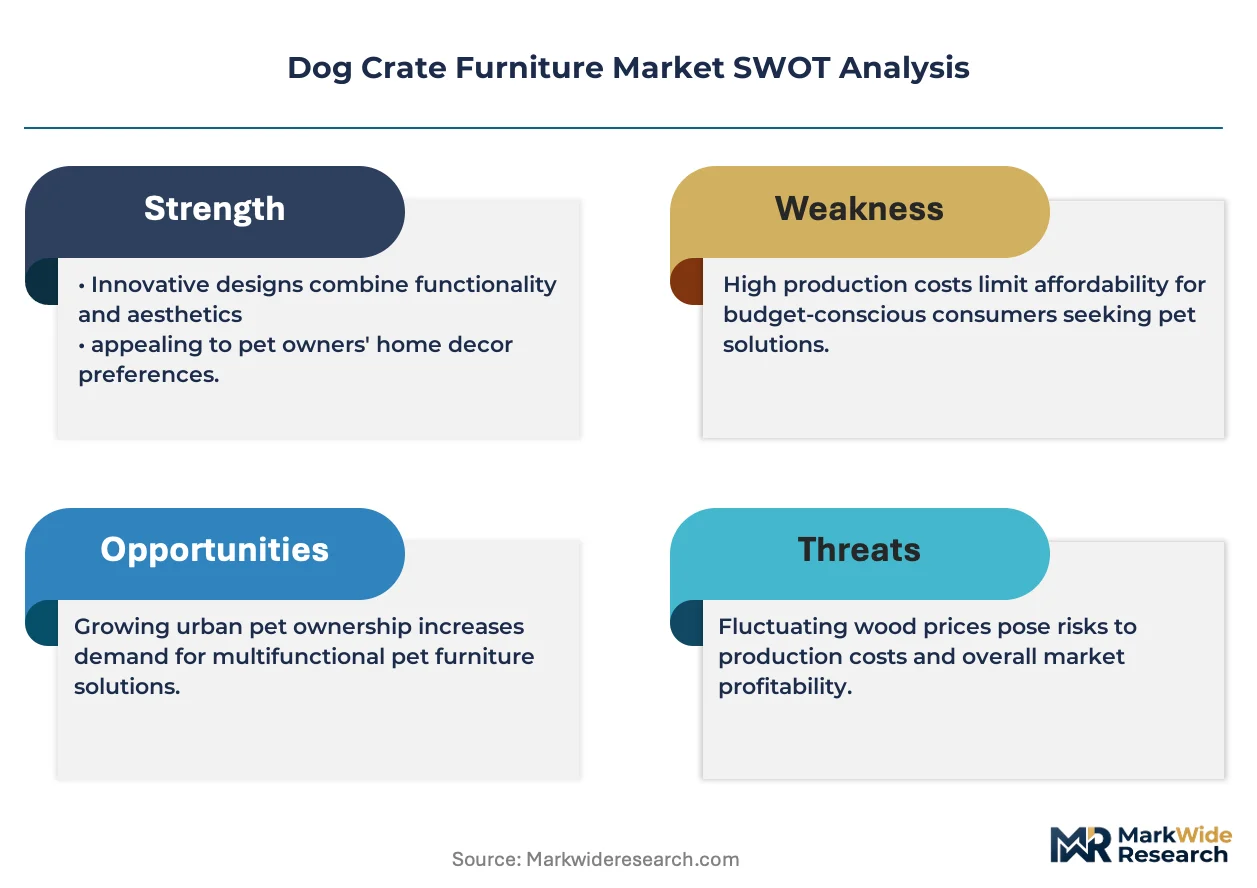
Pet humanization is compressing the functional-aesthetic tradeoff in canine containment, forcing manufacturers to engineer enclosures that satisfy both veterinary compliance and interior design integration. This tension between containment performance and residential visual harmony defines current competitive positioning.
Growth Catalysts
- EPA formaldehyde emission standards:Composite wood product regulations are accelerating certified sustainable lumber sourcing among domestic manufacturers, creating material differentiation premiums.
- Urban apartment dwellers:Space-constrained households in dense metropolitan cores are driving furniture-style crate adoption as multi-functional room dividers and end tables.
- Veterinary containment protocols:Post-surgical recovery and behavioral training standards in clinical settings sustain institutional procurement volume for durable, sanitizable enclosures.
Market Restraints
- Volatile engineered wood substrate costs:Resin and composite panel input prices fluctuate with petrochemical and forestry commodity cycles, compressing margin stability for mid-tier producers.
- Chinese manufacturing concentration:Powder-coated steel frame and hardware component supply clusters in Guangdong and Zhejiang provinces expose buyers to geopolitical and logistics disruption risk.
- Metal cage substitution:Basic wire kennels retain cost advantage in price-sensitive shelter and rescue organization procurement, limiting furniture-style premium capture.
Strategic Opportunities
- Japandi and Scandinavian aesthetic convergence:Minimalist interior design movements among millennial and Gen Z pet owners are opening white space for ash, oak, and bamboo-finish product lines.
- Direct-to-consumer channel expansion:E-commerce platforms are enabling bypass of pet specialty retail gatekeepers, capturing margin previously allocated to wholesale distribution.
- California Air Resources Board certification:CARB Phase 2 compliance is becoming a procurement filter for premium retailers, rewarding early-adopter manufacturers with shelf access.
Industry Challenges
- Furniture-grade finishing skill scarcity:Water-based coating application and hardwood joinery expertise resides in legacy woodworking regions, constraining production scaling for new entrants.
- Dual-use safety certification complexity:Tip-over testing under Consumer Product Safety Commission protocols and pet-specific ventilation standards require parallel engineering validation, extending product development timelines.
- Legacy metal cage distribution entrenchment:Veterinary supply cooperatives and shelter procurement networks maintain long-term supplier relationships, creating channel access friction for aesthetic-focused entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Crate Furniture Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Crates, Metal Crates, Plastic Crates, Furniture-Style Crates Customer Type: Pet Owners, Retailers, Veterinarians, Animal Shelters Design Style: Modern, Rustic, Vintage, Minimalist Size: Small, Medium, Large, Extra Large |
| Companies Covered | Eagle Furniture Manufacturers, MidWest Homes for Pets, The Dog Crate Co., Yaheetech, Petmate, Ritzman's Amish Furniture, Lilly and Max, Frisco (Chewy Brand), DutchCrafters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Crate Furniture Market Evolving Landscape
Material science and regulatory chemistry are rewriting the technical specifications for residential pet enclosures. Manufacturers now engineer for emission compliance and interior design compatibility simultaneously.
Smart ventilation systems with humidity-sensing airflow modulation are migrating from high-end veterinary equipment into consumer furniture-style crates. Premium residential buyers are adopting these climate-control features at accelerating rates. This technology is compressing the performance gap between clinical-grade containment and domestic aesthetic products.
California's Air Resources Board formaldehyde limits are forcing nationwide reformulation of engineered wood substrates and adhesive systems. Manufacturers serving multi-state distribution must now default to CARB-compliant material sourcing to avoid SKU fragmentation. Furniture-style crate producers with West Coast retail exposure face the steepest compliance cost absorption.
Subscription-based crate replacement programs are emerging as an alternative to outright purchase in urban rental markets. Younger pet owners in dense metropolitan areas favor access-over-ownership models for temporary living situations. This behavioral shift is most visible in New York, San Francisco, and Seattle apartment corridors where furniture turnover rates exceed national averages.
Dog Crate Furniture Market Segmentation
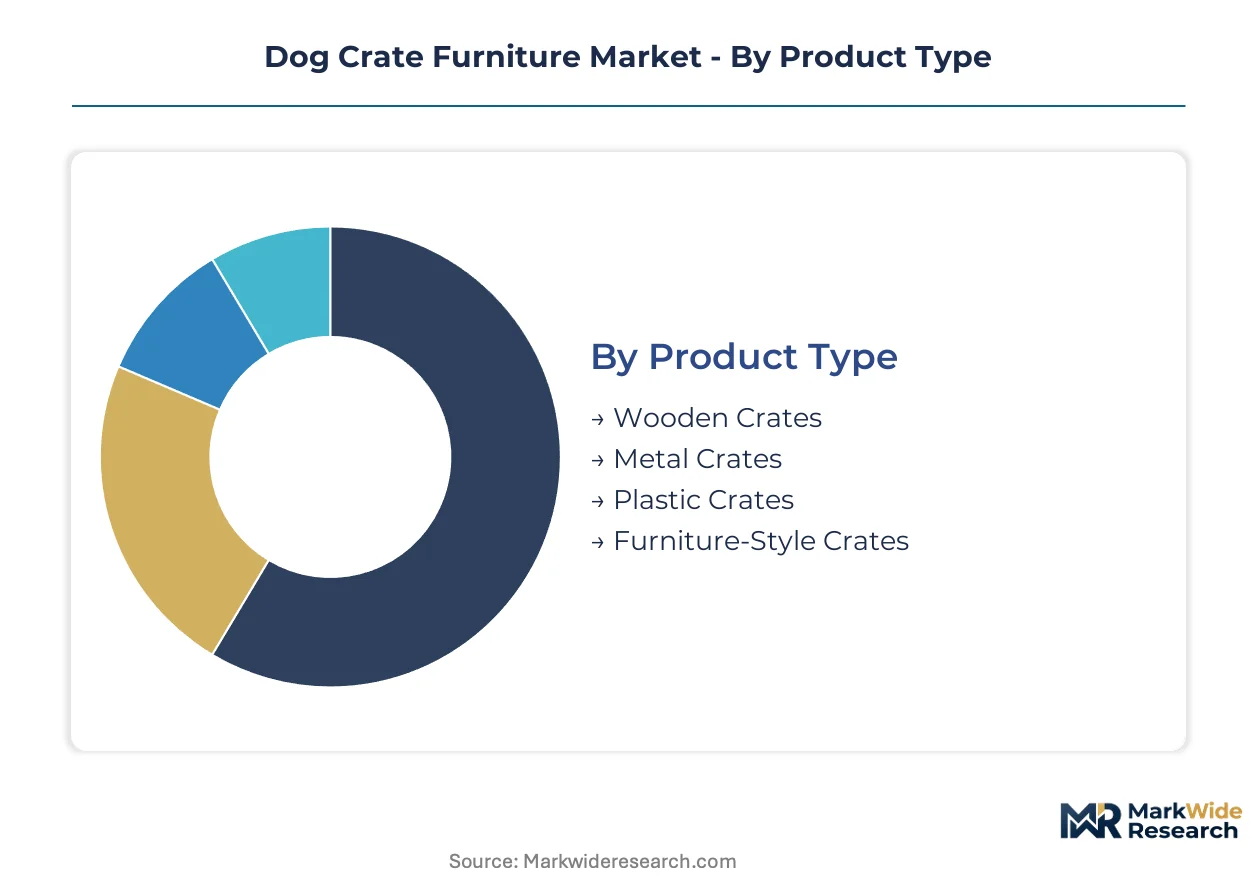
Segmentation in dog crate furniture reveals how containment hardware splits between clinical functionality and residential aesthetics. Manufacturers must engineer for divergent end-use specifications—veterinary sanitization protocols versus living room visual integration—while managing material cost differentials across construction methods.
Product Type:
After-sales service intensity varies sharply by construction material and finish durability. Wooden and furniture-style units demand refinishing support and hardware replacement programs, while metal crates require minimal post-purchase intervention.
- Wooden Crates:Solid hardwood and engineered composite constructions with furniture-grade finishes command premium positioning. Demand concentrates in United States suburban households where interior design compatibility drives replacement cycles and cross-selling to matching pet accessories.
- Metal Crates:Powder-coated steel wire configurations prioritize ventilation and sanitization for institutional procurement. Veterinary clinics and animal shelters in dense metropolitan cores sustain volume through durability requirements and disinfection protocols that degrade wooden alternatives.
- Plastic Crates:Injection-molded polymer enclosures serve travel and temporary containment with lightweight portability.
- Furniture-Style Crates:Dual-purpose designs functioning as end tables or room dividers integrate concealed latching and premium hardware.
By volume, Metal Crates leads. By growth pace, Furniture-Style Crates is ahead.
Customer Type:
Cost tier stratification separates procurement behaviors across the value chain. Institutional buyers prioritize total cost of ownership and sanitization compliance, while residential purchasers weight aesthetic integration and brand reputation.
- Pet Owners:Residential end-users driving furniture-style adoption for space-constrained apartments. United States urban markets show strongest conversion from utilitarian metal cages to hardwood-integrated designs matching Japandi and Scandinavian interior movements.
- Retailers:Pet specialty and home goods channels curating assortments based on CARB compliance certification and tip-over safety documentation.
- Veterinarians:Clinical procurement networks favoring metal crate durability and sanitization efficiency.
- Animal Shelters:Budget-constrained operations retaining wire kennel volume despite furniture-style premium growth.
By absolute units, Animal Shelters dominates procurement. By margin contribution, Pet Owners generates the highest returns.
Design Style:
Application context determines aesthetic specification—urban apartments favor space-efficient minimalism while rural properties accommodate larger rustic formats.
- Modern:Clean lines and neutral palettes align with contemporary interior architecture. Millennial and Gen Z pet owners in Seattle, San Francisco, and New York accelerate this segment through rental market turnover and design-conscious purchasing.
- Minimalist:Stripped-down forms emphasizing negative space and natural materials. Scandinavian and Japandi influence drives fastest expansion among design-forward consumers seeking visual quiet in small-footprint dwellings.
- Rustic:Distressed finishes and farmhouse styling serve traditional residential aesthetics.
- Vintage:Antique-reproduction hardware and period detailing target heritage home restoration markets.
By current installed base, Modern holds the largest share. By expansion trajectory, Minimalist is climbing the fastest.
Size:
Volume scaling follows breed demographics and housing trends—large dogs in suburban settings versus small breeds in urban apartments.
- Large:Accommodates retrievers, shepherds, and similar breeds in standalone residential settings. Suburban United States markets sustain demand through single-family home space availability and outdoor access requirements.
- Medium:Versatile sizing for mixed-breed populations and multi-pet households.
- Small:Compact formats for toy breeds and apartment constraints.
- Extra Large:Specialized containment for giant breeds and multi-dog configurations.
By manufacturing throughput, Medium leads production. By revenue per unit, Large commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium furniture-style crates command pricing power in United States suburban markets that Chinese mass-manufactured metal frames cannot replicate in tier-two European cities. This asymmetry shapes manufacturer sourcing decisions and margin allocation across geographies.
United States
Urban apartment dwellers in Seattle, San Francisco, and New York accelerate furniture-style adoption as multi-functional room dividers. The EPA's formaldehyde emission standards for composite wood products reshape material sourcing decisions among domestic manufacturers. Amish woodworking clusters in Ohio and Pennsylvania anchor handcrafted solid-wood production for premium residential channels.
Germany
Millennial pet owners in Berlin and Munich drive demand for Japandi and minimalist aesthetic crates matching interior design trends. ECHA REACH regulations govern volatile organic compound emissions from finishes and adhesives used in domestic production. Bavarian furniture manufacturing regions concentrate certified sustainable lumber sourcing for CARB-equivalent compliance.
United Kingdom
London's space-constrained rental market favors dual-purpose end-table crates serving temporary living situations. The Office for Product Safety and Standards monitors tip-over hazards for furniture-integrated pet enclosures. Midlands woodworking heritage regions retain water-based coating application expertise constraining new entrant scaling.
China
Guangdong and Zhejiang province manufacturing clusters produce powder-coated steel frames and hardware components for global export. The Ministry of Ecology and Environment enforces dual carbon goals pressuring factory emission reductions. Shenzhen and Dongguan industrial zones face logistics disruption exposure from geopolitical trade friction.
Canada
Toronto and Vancouver metropolitan areas mirror United States furniture-style premium adoption patterns. Health Canada and PMRA regulate pet product safety standards parallel to CPSC protocols. Quebec forestry regions supply certified lumber to North American manufacturers seeking CARB Phase 2 compliance.
Dog Crate Furniture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hardware and substrate materials. The vendor base stratifies across handcrafted solid-wood artisans, mass-market e-commerce platforms, and institutional veterinary supply networks. Three archetypes dominate: Amish heritage woodworkers leveraging domestic manufacturing credibility, Chinese-scale metal fabricators optimizing logistics efficiency, and direct-to-consumer brands bypassing retail gatekeepers. Competitive moves concentrate on CARB certification acquisition for shelf access and subscription-based replacement programs targeting urban rental markets.
Among heritage-focused fabricators, Ritzman's Amish Furniture and DutchCrafters exemplify the handcrafted solid-wood archetype, anchoring premium positioning through domestic manufacturing credibility. Yaheetech occupies a position within the mass-market e-commerce tier, representing Chinese-scale production optimized for price-competitive metal and wooden designs. MidWest Homes for Pets sits within the institutional supply network, sustaining veterinary and shelter procurement relationships that newer aesthetic-focused entrants struggle to penetrate.
| Leading Market Players |
|---|
| Eagle Furniture Manufacturers |
| MidWest Homes for Pets |
| The Dog Crate Co. |
| Yaheetech |
| Petmate |
| Ritzman's Amish Furniture |
| Lilly and Max |
| Frisco (Chewy Brand) |
| DutchCrafters |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang province manufacturing clusters for powder-coated steel frames and hardware components concentrate upstream bargaining power with Chinese fabricators, leaving downstream margin pools with domestic brands commanding CARB certification premiums and Amish heritage credibility in United States premium channels.
Pricing Analysis
Configured-to-order handcrafted solid-wood crates from Ohio and Pennsylvania Amish clusters command substantial premiums over mass-market standard SKUs from Chinese e-commerce platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth. Pricing pressure stems from volatile engineered wood substrate costs tied to petrochemical and forestry commodity cycles. Animal shelters and rescue organizations exhibit highest price sensitivity, while urban apartment dwellers in Seattle and New York show lowest sensitivity for furniture-integrated designs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become critical liquidity tools for mid-tier manufacturers navigating raw material cost volatility. Production draws from China for steel frames and hardware, Canada for certified lumber feedstock, and United States for finished hardwood assembly. Critical dependencies include powder-coated steel wire, CARB-compliant composite panels, and furniture-grade hardwood lumber. Single-source vulnerability concentrates in Guangdong stamping and coating operations. Distribution runs through direct-to-consumer platforms, pet specialty retail, and veterinary supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer platform economics are displacing wholesale gatekeeper margins, creating interoperability inflections between e-commerce fulfillment networks and subscription-based replacement program operators serving urban rental markets.
For Market Incumbents: Insulate position by deepening CARB Phase 2 certification moats and securing exclusive Amish woodworking cluster partnerships before new entrants replicate domestic manufacturing credibility. Vertical integration into certified sustainable lumber sourcing hedges engineered wood substrate cost volatility threatening mid-tier margin stability. For New Entrants and Emerging Players: Pursue white-space capture in Japandi and Scandinavian aesthetic segments where millennial and Gen Z pet owners in dense metropolitan cores remain underserved by legacy rustic and farmhouse styling. Target direct-to-consumer launch with climate-control smart ventilation features migrating from veterinary equipment into residential premium tiers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across furniture-grade finishing operations as water-based coating expertise scarcity constrains production scaling. Long-term viability favors acquisition targets combining CARB compliance certification with established e-commerce fulfillment infrastructure. Signal to monitor: California Air Resources Board enforcement intensity spreading to additional state-level procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| CARB Phase 2 Certification Investment | Unlocks shelf access at premium retailers filtering procurement by emission compliance. |
| Direct-to-Consumer Platform Launch | Bypasses pet specialty retail gatekeepers capturing margin previously allocated to wholesale distribution. |
| Amish Woodworking Cluster Partnership | Secures domestic manufacturing credibility and handcrafted solid-wood differentiation against mass-market imports. |
| Smart Ventilation Feature Integration | Compresses performance gap between clinical-grade containment and residential aesthetic products. |
| Subscription-Based Replacement Program | Captures urban rental market turnover with access-over-ownership models in high-churn metropolitan corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA formaldehyde emission documentation, CPSC tip-over safety filings, and customs trade records for steel frame and hardware imports. Primary interviews engaged product development executives at furniture-style crate manufacturers, procurement leads at veterinary supply cooperatives, category buyers at pet specialty retailers, and plant managers at Amish woodworking operations. Secondary validation drew from CARB certification databases, state-level chemical disclosure registries, and e-commerce platform sales analytics. Bottom-up unit economics and top-down market sizing were triangulated against segmentation splits across material construction, design aesthetic, and customer type.
Forecast inputs span pet humanization intensity indices, urban apartment household formation rates, and regulatory enforcement probability across EPA and state-level air quality jurisdictions. Modeled dimensions include product type, design style, customer segment, size tier, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and substitution dynamics between metal cage and furniture-style alternatives. Industry-specific inputs incorporate veterinary containment protocol adoption rates and interior design trend velocity among millennial and Gen Z cohorts.
Macroeconomic conditions sit as an overlay; deviation in housing affordability indices, pet ownership rates, or engineered wood substrate commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and supply chain logistics stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Pet Collar Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Pet Beds Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Pet Rugs Market