
 Pet Accessories Market | 2026-2036
Pet Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Accessories Market Analysis
Veterinary nutrition expertise is collapsing across the companion animal sector, constraining innovation pipelines for clinically validated accessories. Nestlé Purina PetCare leverages its nutritional science workforce to anchor premium positioning in vet-recommended feeding tools. KONG Company specializes in durable polymer engineering, sustaining brand loyalty among destructive-chewing dog owners. Central Garden & Pet controls broad retail shelf space, competing on distribution density rather than product differentiation.
Pet accessories encompass functional and discretionary goods manufactured from polymers, textiles, leather, and metal alloys, designed to support animal containment, enrichment, hygiene, and mobility. Injection-molded thermoplastics and woven ballistic nylons dominate mass production due to cost scalability and chew resistance, serving the primary commercial purpose of extending pet safety and owner convenience during daily routines. Toys and beds capture disproportionate margin pools as pet humanization elevates discretionary spending on enrichment and sleep comfort. Fabric materials gain share in premium tiers where antimicrobial coatings and orthopedic foam inserts command price premiums over standard plastic and metal alternatives.
FDA Center for Veterinary Medicine oversight of ingestible pet products and CPSC safety standards for small-part choking hazards shape material selection and labeling requirements across the United States. The EU REACH regulation and F-Gas Regulation restrict certain chemical treatments in imported pet textiles and cooling accessories, raising compliance costs for cross-border suppliers. China's SAMR enforces GB standards for plastics in pet products, creating a fragmented certification landscape that favors manufacturers with in-house testing laboratories. Stakeholders must monitor evolving state-level extended producer responsibility laws for pet product packaging and synthetic material disposal.
Market Dynamics
Pet humanization is collapsing traditional functional-premium boundaries, forcing manufacturers to embed veterinary-grade materials into mass-market SKUs while maintaining cost parity with commodity alternatives.
Growth Catalysts
- REACH chemical compliance:EU F-Gas Regulation restrictions on synthetic cooling agents in pet accessories are accelerating bio-based phase-change material R&D, opening premium positioning for compliant suppliers.
- Destructive-chewing behavior:Ballistic nylon and reinforced thermoplastic elastomer formulations now command outsized loyalty among large-breed dog owners, creating durable goods replacement cycles.
- Extended producer responsibility laws:California and New York state mandates for synthetic packaging recovery are incentivizing closed-loop polymer sourcing in domestic manufacturing.
Market Restraints
- Polypropylene feedstock volatility:Injection-molding input costs swing with propylene monomer pricing, compressing margin stability for volume-dependent producers.
- Guangdong province concentration:Over 60 percent of global pet toy molding capacity sits within 200 kilometers of Shenzhen, exposing supply chains to single-region logistics disruption.
- Antimicrobial coating limitations:Silver-ion and copper-based treatments face efficacy degradation in high-saliva environments, constraining premium claims for oral-contact accessories.
Strategic Opportunities
- India companion animal expansion:Mumbai and Bangalore metro areas show underpenetrated veterinary clinic distribution for prescription feeding accessories, creating first-mover shelf space.
- Telemedicine-integrated diagnostics:Wearable activity trackers paired with remote veterinary consultations are opening subscription revenue models beyond hardware sales.
- SAMR GB standard harmonization:China's consolidation of plastics safety certifications under national standards reduces testing redundancy for exporters with in-house laboratories.
Industry Challenges
- Veterinary nutritionist scarcity:Clinically validated feeding tool development stalls without access to board-certified animal nutrition specialists, forcing reliance on external consultancy.
- Multi-jurisdiction labeling complexity:Simultaneous FDA Center for Veterinary Medicine, CPSC, and EU REACH compliance requires parallel certification tracks, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Accessories Market |
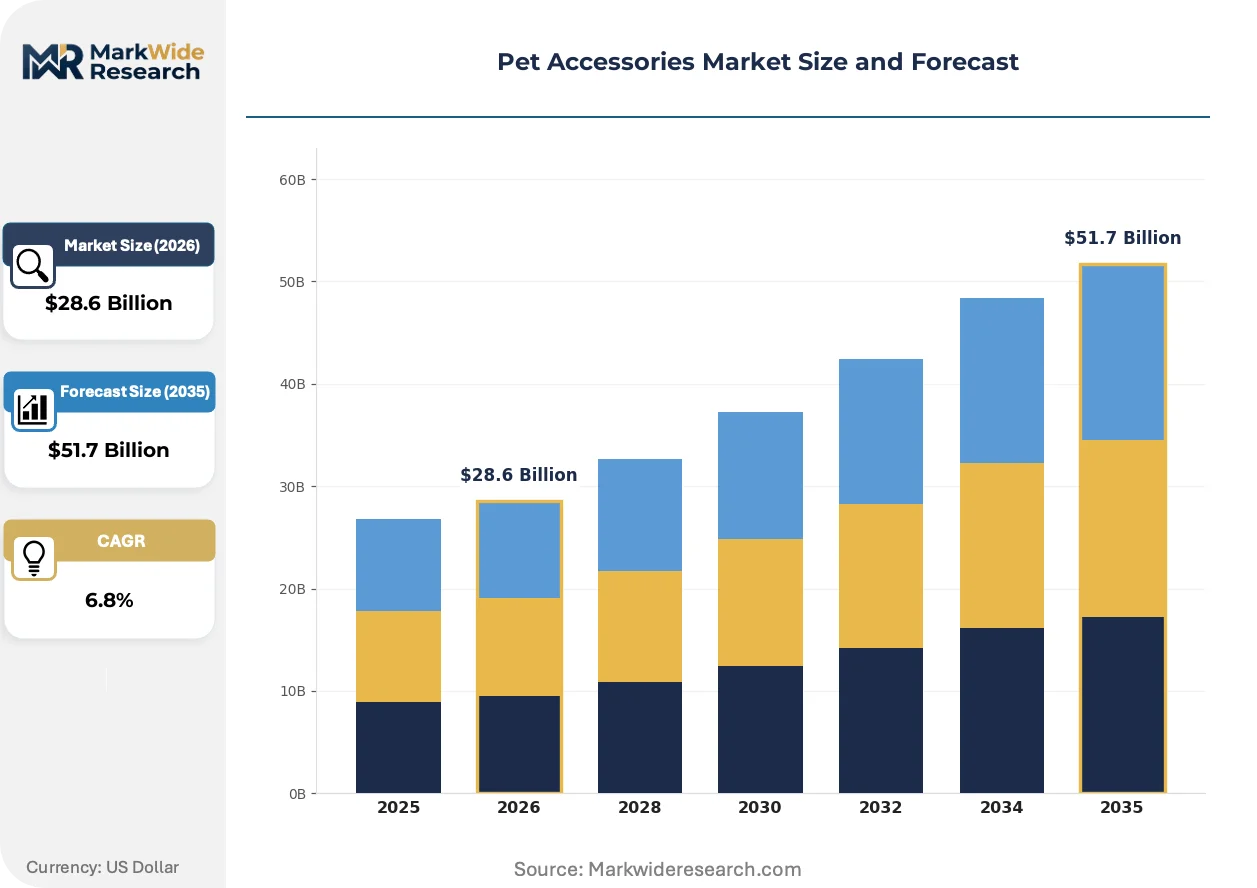
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collars, Leashes, Toys, Beds Material: Plastic, Fabric, Leather, Metal Use Case: Training, Grooming, Travel, Play Customer Type: Pet Owners, Retailers, Veterinarians, Wholesalers |
| Companies Covered | Central Garden & Pet, Coastal Pet Products, Ferplast, KONG Company, Nestlé Purina PetCare, Hartz Mountain, MidWest Homes for Pets, PetSafe, TRIXIE Heimtierbedarf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Accessories Market Emerging Trajectories
Smart connectivity and biomaterial substitution are rewriting performance benchmarks across containment, enrichment, and mobility categories, compressing legacy product lifecycles.
Biodegradable polylactic acid compounds reinforced with hemp fiber are displacing petroleum-based thermoplastics in disposable waste bag and single-use toy segments. Premium pet specialty retailers in Germany and the Netherlands are accelerating SKU transitions, with compostability certifications now filtering wholesale procurement decisions. This material shift is displacing conventional polyethylene volumes in European private-label programs and forcing Asian molders to retool extrusion lines.
EU REACH Annex XVII restrictions on phthalate plasticizers in oral-contact articles are tightening extractable limits for vinyl chew toys. Manufacturers serving the French and Italian markets are migrating to citrate-based plasticizer formulations ahead of 2025 enforcement windows. Small-batch artisan producers without reformulation chemistry capabilities are exiting the premium tier, consolidating share among compounders with in-house polymer science teams.
Subscription-based replenishment models for consumable accessories now capture recurring revenue from millennial urban pet owners. Direct-to-consumer veterinary partnerships in the United States are replacing big-box retail as the primary channel for prescription-grade mobility aids and orthopedic bedding. This channel rotation is most visible in coastal metropolitan markets where same-day delivery infrastructure supports urgent replacement purchasing.
Pet Accessories Market Segmentation
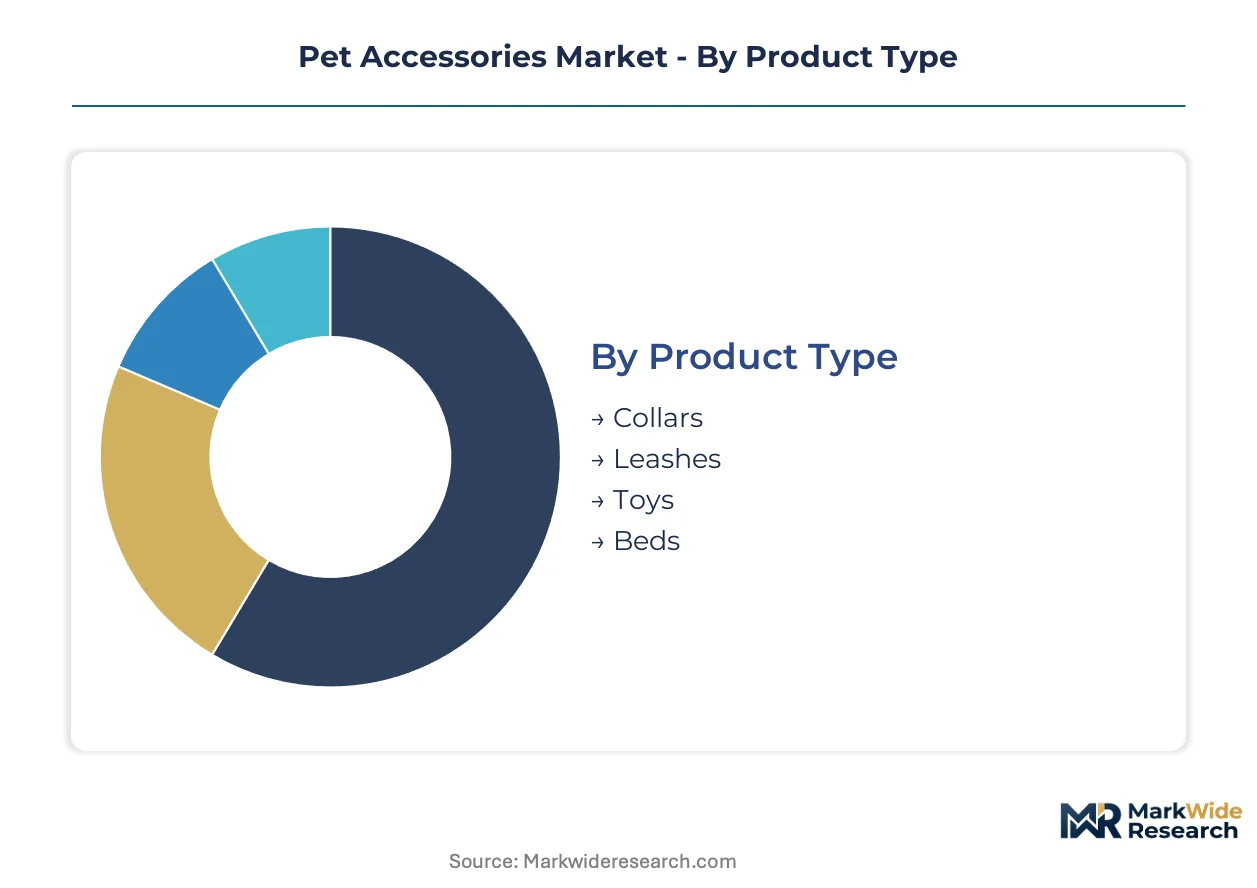
Segmentation in pet accessories determines which SKUs secure shelf space in veterinary clinics versus mass retail. Channel-specific compliance requirements and margin structures vary sharply across these divides.
Product Type:
Channel placement follows durability expectations and replacement frequency, with premium tiers concentrating in specialty pet retailers and veterinary partnerships.
- Toys:Injection-molded thermoplastics and ballistic nylon constructions withstand destructive chewing in large-breed dogs. Demand clusters among millennial urban owners in the United States and Germany who prioritize enrichment and behavioral management.
- Beds:Orthopedic foam cores with antimicrobial textile covers address aging pet mobility needs. Veterinary clinic distribution in coastal US metros and German urban centers drives premium positioning for clinically validated designs.
- Collars:Quick-release polymer hardware and reflective webbing serve everyday containment needs across mass-market channels.
- Leashes:Woven nylon and biothane constructions balance durability with handler comfort in high-traffic urban walking environments.
Toys dominate installed base volume. Beds represent the fastest-growing trajectory as pet humanization elevates sleep comfort spending.
Material:
Cost tier alignment separates commodity mass production from premium positioning, with regulatory compliance costs amplifying these spreads.
- Plastic:Polypropylene and thermoplastic elastomer formulations enable high-volume injection molding for toys and containment hardware. FDA Center for Veterinary Medicine oversight of oral-contact articles constrains plasticizer selection for chew applications.
- Fabric:Ballistic nylon and hemp-fiber reinforced textiles command price premiums through antimicrobial coatings and sustainability certifications. EU REACH Annex XVII phthalate restrictions are accelerating citrate-based plasticizer migration in European-bound production.
- Leather:Vegetable-tanned hides with reinforced stitching serve premium collar and leash segments in specialty retail.
- Metal:Stainless steel and aluminum alloys anchor hardware components where strength-to-weight ratios determine performance.
Plastic holds the largest production volume. Fabric is climbing the fastest as bio-based substitutions reshape procurement criteria.
Use Case:
Application-specific performance requirements dictate material selection and certification depth across consumer and professional channels.
- Play:Durable polymer engineering for unsupervised chewing and interactive retrieval games. CPSC small-part choking hazard standards shape design parameters for US market entry.
- Travel:Crash-tested carrier hardware and vehicle restraint systems. Germany's KBA-equivalent safety validation requirements influence premium product development for EU export.
- Training:Controlled-response collars and long-line leashes support behavioral modification protocols.
- Grooming:Ergonomic tools and restraint systems align with veterinary clinic hygiene workflows.
Play applications anchor unit volume. Travel is where expansion concentrates as pet-inclusive mobility norms spread.
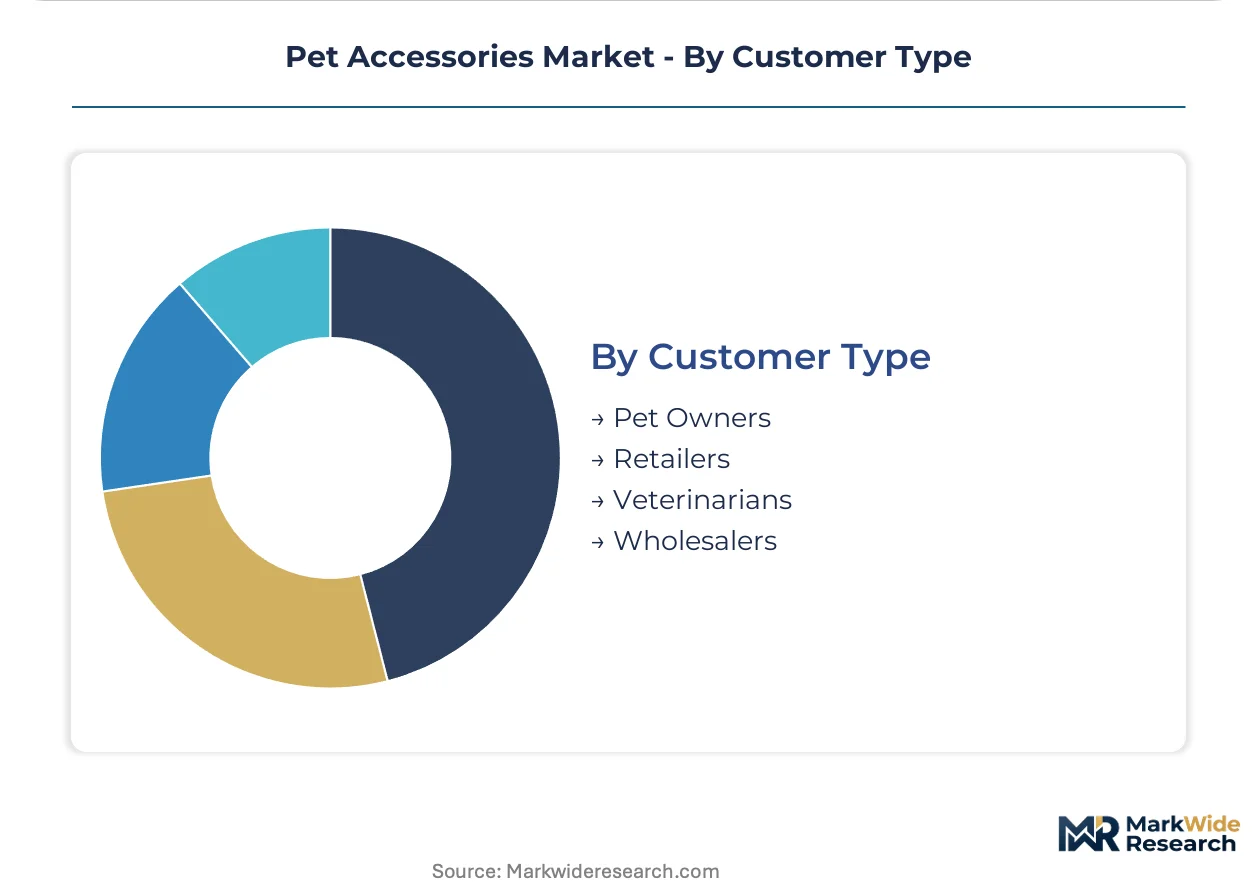
Customer Type:
Procurement authority and volume scale create distinct service models from direct-to-consumer through institutional distribution.
- Pet Owners:End-consumer purchasing decisions driven by veterinary recommendation and peer referral in digital channels.
- Veterinarians:Prescription-grade feeding tools and orthopedic aids requiring clinical validation and regulatory documentation.
- Retailers:Private-label sourcing power concentrated in Central Garden & Pet and specialty chain buyers.
- Wholesalers:Volume aggregation for independent pet store networks and regional distributors.
Pet owners drive absolute demand volume. Veterinarians represent the steepest expansion trajectory as telemedicine integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight anchors the United States as the regulatory reference point for pet product safety standards worldwide. Demand concentrates in three distinct national markets where millennial ownership patterns and compliance requirements create divergent competitive conditions.
United States
Millennial urban pet owners in coastal metros drive premium spending on enrichment and travel accessories. FDA and CPSC dual oversight of oral-contact articles and small-part hazards creates parallel certification tracks for chew toys and containment hardware. Injection-molding capacity clusters in Ohio and Illinois serving mass-market distribution through Central Garden & Pet's retail network.
Germany
Pet humanization norms elevate sleep comfort and mobility aid spending among aging companion animal populations. KBA-equivalent safety validation requirements for vehicle restraint systems shape premium product development for EU export. Manufacturing concentrates in Bavaria and North Rhine-Westphalia where compounders with in-house polymer science teams dominate reformulation capabilities.
China
SAMR enforcement of GB standards for plastics in pet products creates fragmented certification demands for exporters. Over sixty percent of global pet toy molding capacity sits within two hundred kilometers of Shenzhen, exposing supply chains to single-region logistics concentration. Yangtze River Delta and Pearl River Delta clusters are retooling extrusion lines for bio-based material transitions demanded by European buyers.
India
Mumbai and Bangalore metro areas show underpenetrated veterinary clinic distribution for prescription feeding accessories. BIS standards for pet product plastics remain less stringent than EU or US equivalents, creating first-mover opportunities for compliant suppliers. Manufacturing activity concentrates in Maharashtra and Gujarat where domestic molders serve emerging specialty retail channels.
Netherlands
EU REACH Annex XVII phthalate restrictions and F-Gas Regulation constraints accelerate bio-based phase-change material R&D for cooling accessories. Premium pet specialty retailers in Randstad cities are filtering wholesale procurement through compostability certifications. Dutch importers function as compliance gateways for Asian suppliers seeking European market entry.
Pet Accessories Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the pet accessories sector. The vendor base organizes into three functional tiers: multinational consumer goods conglomerates with nutritional science workforces, specialized polymer engineering firms with durable goods expertise, and broad-line distributors competing on shelf-space density rather than product differentiation. Two dominant competitive moves define current positioning: backward integration into captive polymer compounding capabilities and direct-to-consumer channel expansion bypassing traditional retail gatekeepers.
Among nutrition-science anchored conglomerates, Nestlé Purina PetCare exemplifies the veterinary-recommended positioning archetype. KONG Company occupies a specialist position in reinforced thermoplastic elastomer formulations for destructive-chewing applications. Central Garden & Pet represents the distribution-density competitive model, controlling broad retail shelf access without deep product-level differentiation. These three anchors illustrate the strategic divergence between clinical validation, materials engineering, and channel control as alternative bases for market position.
| Leading Market Players |
|---|
| Central Garden & Pet |
| Coastal Pet Products |
| Ferplast |
| KONG Company |
| Nestlé Purina PetCare |
| Hartz Mountain |
| MidWest Homes for Pets |
| PetSafe |
| TRIXIE Heimtierbedarf |
| Others |
Supply Flow & Price Mechanics
FDA Center for Veterinary Medicine certification tiers simultaneously gate supplier qualification and stratify price levels across oral-contact accessories, forcing manufacturers to absorb compliance costs or migrate toward premium positioning where certification premiums offset testing investments.
Pricing Analysis
Coastal US metros command price premiums of 15-25 percent over inland distribution points for identical SKUs due to same-day delivery infrastructure and veterinary clinic density. Three-tier pricing structure across premium, standard, and economy levels separates clinically validated orthopedic beds from mass-market alternatives. Cost compression in commodity injection-molded toys is intensifying because polypropylene feedstock volatility compresses margin stability. Mass-market retailers exhibit highest price sensitivity, while veterinary clinic procurement demonstrates inelastic demand for prescription-grade mobility aids.
Supply Chain Analysis
Inventory buffers for ballistic nylon and reinforced thermoplastic elastomer inputs have extended to 8-12 weeks as manufacturers hedge against Guangdong logistics disruption. Manufacturing gravity centers on China, Germany, and the United States, with over sixty percent of global pet toy molding capacity concentrated within two hundred kilometers of Shenzhen. Raw material sourcing draws from petroleum-based polypropylene, bio-based polylactic acid compounds, and hemp fiber reinforcements. Single-region concentration in Guangdong province exposes supply chains to logistics chokepoint vulnerability. Distribution runs through Central Garden & Pet's retail network for mass-market volume, with direct-to-consumer channels capturing premium tier growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among millennial urban pet owners and direct-to-consumer veterinary partnerships, fragmenting traditional retail gatekeeper influence and forcing manufacturers to split channel strategies.
For Market Incumbents: Compound polymer science capabilities through backward integration into captive compounding facilities, insulating margin structures from feedstock volatility while accelerating citrate-based plasticizer reformulation ahead of EU REACH Annex XVII enforcement. Defend shelf space against direct-to-consumer entrants by embedding telemedicine diagnostics into hardware SKUs, creating subscription lock-in beyond transactional replacement cycles. Prioritize certification investment in SAMR GB standard harmonization to reduce testing redundancy for China-export volumes. For New Entrants and Emerging Players: BIS certification fast-track for Maharashtra and Gujarat manufacturing clusters opens first-mover positioning in India's underpenetrated veterinary clinic distribution for prescription feeding accessories. White-space targets include Mumbai metro area specialty retail and Bangalore telemedicine-integrated diagnostic partnerships. Go-to-market angle should leverage compostability certifications to penetrate Dutch importer gateways serving EU REACH-compliant procurement filters. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by accelerating bio-based phase-change material R&D valuations and consolidating share among compounders with in-house polymer science teams. Long-term viability over the next decade hinges on capturing veterinary nutritionist scarcity premiums through clinically validated feeding tool platforms. Acquisition target archetype: mid-cap specialists with SAMR in-house testing laboratories and established EU importer relationships. Signal to watch: state-level extended producer responsibility law adoption rates in California and New York as predictors of closed-loop polymer sourcing mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of citrate-based plasticizers insulates EU REACH compliance costs from third-party markup. |
| Direct-to-Consumer Veterinary Partnership Launch | Same-day delivery infrastructure in coastal US metros supports urgent replacement purchasing for orthopedic bedding. |
| Bio-Based Material Transition Program | Compostability certifications filter wholesale procurement decisions at German and Dutch premium specialty retailers. |
| Telemedicine Diagnostics Integration | Wearable activity trackers paired with remote veterinary consultations open subscription revenue beyond hardware sales. |
| SAMR GB Standard Harmonization Investment | In-house testing laboratories reduce certification redundancy for exporters serving China's consolidated plastics safety standards. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with pet accessory brand managers, veterinary clinic procurement leads, polymer compounding technical directors, and specialty retail category buyers; and secondary validation through FDA Center for Veterinary Medicine filings, CPSC safety standard databases, EU REACH Annex XVII regulatory texts, SAMR GB standard documentation, and customs trade records. Bottom-up SKU-level volume aggregation was cross-checked against top-down manufacturer capacity disclosures.
Across the analysis window, the forecast framework modeled demand trajectories by product type, material composition, use case application, and customer procurement authority. CAGRs were derived from segment-level growth rate reconciliation against macro pet ownership demographic shifts and regulatory compliance cost pass-through assumptions. Industry-specific inputs included veterinary nutritionist workforce scarcity indices and state-level extended producer responsibility law adoption tracking.
Decision-makers should treat outputs as directional under assumptions of sustained millennial pet humanization spending and stable polypropylene feedstock pricing; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United States Pet Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Dog Harness Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Toy Dog Market
Pet Care Products
US Dog Food Market
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
Pet Beds Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Dog Vest Market
Pet Care Products
Smart Pet Collar Market
Pet Care Products
Modern Cat Furniture Market