
 E-Wallet Market | 2026-2036
E-Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
E-Wallet Market Analysis
Market Dynamics
Southeast Asia's payment infrastructure build-out is tilting toward mobile-first architectures. Alipay leverages its merchant network density to sustain dominance across Chinese cross-border corridors. PayPal anchors North American e-commerce checkout flows through deep platform integrations. WeChat Pay competes via super-app ecosystem lock-in across social, retail, and transit use cases.
Technical Landscape
An e-wallet constitutes a software-based payment system storing encrypted financial credentials on networked devices, enabling tokenized transaction authorization through NFC, QR codes, or in-app protocols. The primary commercial purpose centers on displacing physical cash and card-present interactions through real-time settlement rails. Merchant payment services occupy the deepest margin pools as interchange economics favor high-frequency business transactions over peer-to-peer transfers. Smartphone-based deployment leads by device type due to biometric authentication integration and ubiquitous cellular penetration.
Regulatory Environment
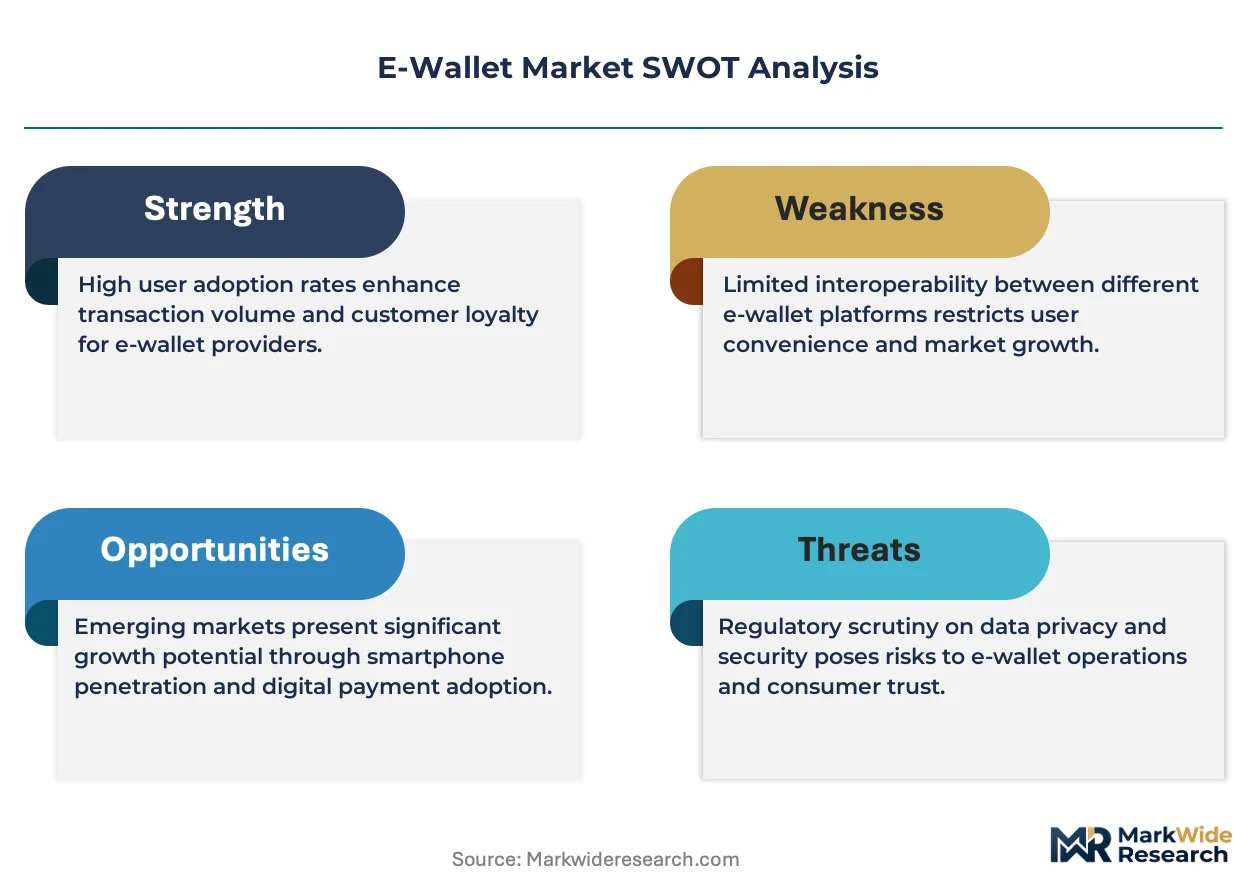
The EU's PSD2 open-banking framework and GDPR data sovereignty rules shape product architecture for entrants targeting European wallets. India's RBI mandates full KYC compliance for wallet balance thresholds, while China's SAMR enforces antitrust scrutiny on platform payment monopolies. Stakeholders must monitor central bank digital currency pilots as these programs threaten to disintermediate private wallet balances directly.
Market Dynamics
Central bank digital currency pilots across major economies are threatening to disintermediate private wallet balances directly, forcing incumbent providers to reposition around value-added services rather than deposit-holding.
Growth Catalysts
- India's UPI Interoperability Mandate:The RBI-mandated protocol stack forces wallet providers onto unified rails, expanding addressable merchant acceptance networks and compressing consumer friction at checkout.
- QR Code Standardization:Indonesia's unbanked population corridors are adopting interoperable QRIS standards, enabling single-code acceptance across competing wallet platforms and accelerating cash displacement.
- Biometric Authentication Integration:Fingerprint and facial recognition hardware on sub-$100 smartphones is collapsing KYC friction for first-time financial service users in frontier markets.
Market Restraints
- Interchange Rate Compression:Regulatory caps on merchant discount rates in India and Southeast Asia are squeezing transaction economics for wallet providers dependent on payment volume monetization.
- Data Localization Requirements:Indonesia's government mandates server placement within national borders, elevating infrastructure capex for foreign entrants and complicating cross-border architecture.
- Banking Partnership Concentration:Settlement rails in the Philippines depend on a narrow set of incumbent universal banks, creating single-point-of-failure risk for wallet liquidity management.
Strategic Opportunities
- Merchant Lending Adjacencies:Transaction data exhaust from high-frequency small-business payments enables cash-flow-based underwriting products unavailable through traditional credit bureaus.
- Transit System Integration:Jakarta's KRL commuter rail and Bangkok's BTS Skytrain are opening fare collection to private wallets, capturing daily recurring payment behavior.
- Cross-Border Remittance Rails:ASEAN payment connectivity initiatives are creating licensed corridors for wallet-to-wallet international transfers, bypassing correspondent banking delays and SWIFT fees.
Industry Challenges
- Legacy Core Banking Integration:Tier-2 regional banks in Vietnam and the Philippines maintain COBOL-based ledger systems, requiring expensive middleware development for real-time wallet reconciliation.
- Certification Timeline Compression:PCI-DSS Level 1 compliance for wallet providers processing over six million annual transactions demands 12-18 month audit cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Wallet Market |
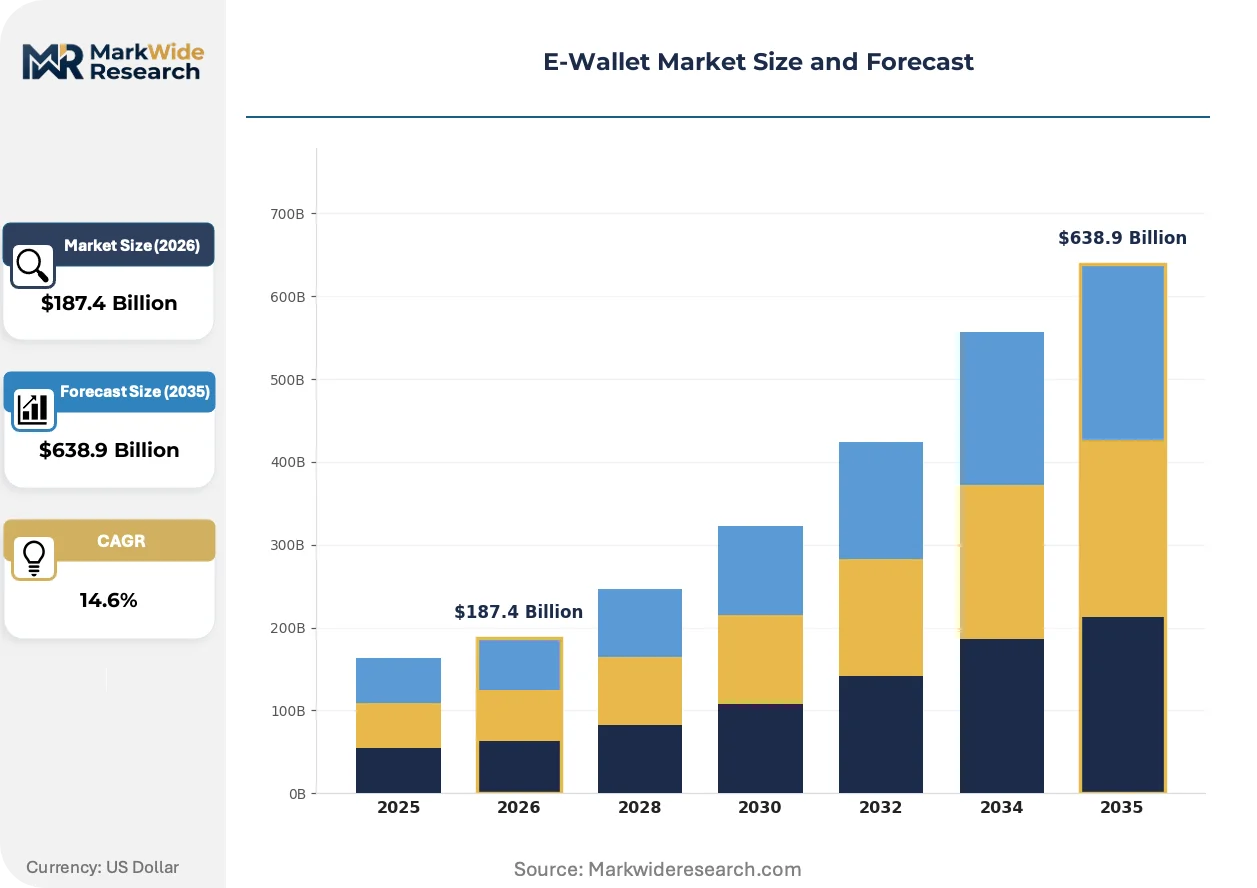
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Bank Transfer, Mobile Payment Service Type: Peer-to-Peer, Merchant Payments, In-App Payments, Bill Splitting End User: Retail Consumers, Small Businesses, Corporates, Freelancers Device Type: Smartphones, Tablets, Wearables, Desktop |
| Companies Covered | PayPal, Alipay, Apple Pay, Cash App, WeChat Pay, Ant Group, Block Inc., Revolut, Google Pay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Wallet Market Emerging Trajectories
Tokenized credential architectures and embedded finance distribution models are collapsing the distinction between payment instruments and the software surfaces where transactions originate.
Biometric payment authorization is rendering obsolete PIN-entry and signature-based verification for in-person transactions. Quick-service restaurants and transit operators in Singapore and Malaysia are deploying palm-vein and facial recognition terminals at scale. This shift is compressing checkout latency to sub-500 milliseconds while eliminating credential-sharing fraud vectors.
Europe's PSD2 Strong Customer Authentication requirements are mandating two-factor verification for electronic payments above low-value thresholds. Wallet providers serving EU corridors must implement dynamic linking of transaction amount to authentication code. Merchant checkout abandonment rates are spiking 15-20% at initial implementation, forcing UX investment in invisible authentication flows.
Platform-embedded wallet distribution is displacing standalone app downloads as the primary customer acquisition channel. Ride-hailing and food delivery super-apps in Indonesia and Vietnam are integrating native payment balances that never expose users to external wallet interfaces. This behavior concentrates transaction volume within closed ecosystems and fragments regulatory visibility into actual payment flows.
E-Wallet Market Segmentation
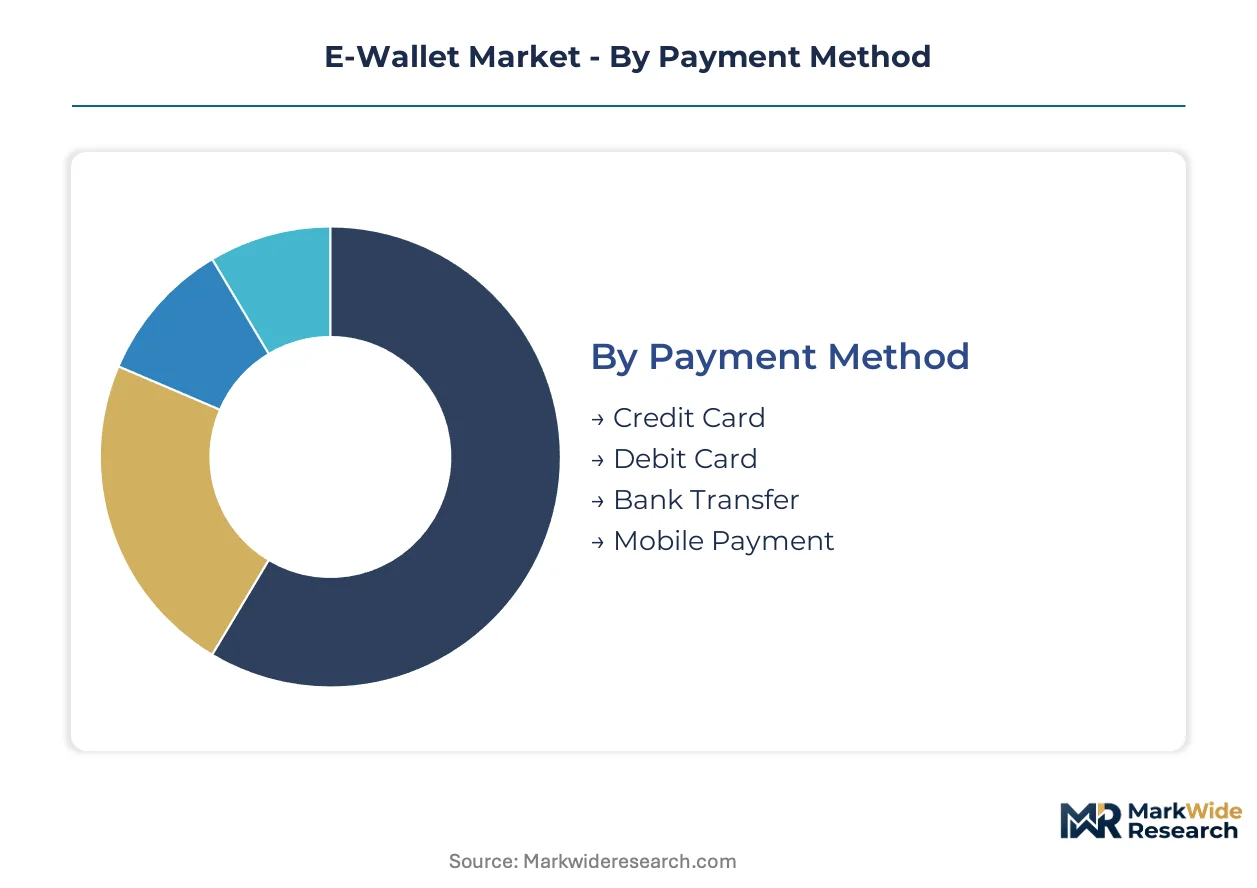
E-wallet segmentation reveals distinct monetization profiles across payment rails and user contexts. Providers optimize architecture differently for high-frequency merchant flows versus low-margin peer-to-peer transfers.
Payment Method:
Mature card-linked infrastructure dominates transaction volume, while emerging bank-direct rails capture regulatory tailwinds in developing markets.
- Credit Card:Tokenized credential storage enables one-tap checkout at premium merchant tiers. Travel and hospitality verticals in Singapore and Thailand concentrate demand as interchange economics reward high-ticket transactions.
- Debit Card:Real-time bank account linking through open banking APIs reduces settlement latency to sub-seconds. India's UPI rails and Indonesia's BI-FAST network are accelerating debit-first wallet architectures among price-sensitive users.
- Bank Transfer:Direct account-to-account settlement bypasses card network fees entirely. Germany's Girocard ecosystem and the Netherlands' iDEAL demonstrate mature instant transfer adoption.
- Mobile Payment:Carrier billing and telco-integrated wallets serve underbanked segments across the Philippines and Vietnam where formal banking penetration lags smartphone ownership.
Credit card linkage handles the majority of throughput; mobile payment is gaining share fastest among first-time financial service users.
Service Type:
Application context determines margin structure, with merchant-facing services commanding premium economics over social payment utilities.
- Merchant Payments:QR-code acceptance at small-business terminals generates interchange revenue plus float on settlement delays. Indonesia's warung sector and Vietnam's street vendors are driving hardware-light deployment models.
- Peer-to-Peer:Social payment splits and remittance flows operate at near-zero margins, functioning primarily as customer acquisition channels. Nigeria's P2P volume and Kenya's M-Pesa social transfers illustrate this dynamic.
- In-App Payments:Embedded checkout within ride-hailing and food delivery super-apps never surfaces external wallet interfaces. Grab and Gojek in Southeast Asia capture recurring daily transactions through native balance systems.
- Bill Splitting:Group expense management tools aggregate fragmented social payments into single settlement events. Young professional cohorts in urban India and Brazil show highest engagement with split-payment features.
Merchant payments generate the deepest revenue pools; in-app payments are climbing the fastest as platform ecosystems consolidate.
End User:
Customer scale and transaction frequency create diverging service requirements across individual and commercial segments.
- Retail Consumers:Mass-market users prioritize friction reduction and merchant acceptance breadth over feature depth. Biometric authentication on sub-$100 smartphones is collapsing KYC barriers across Indonesia's unbanked corridors.
- Small Businesses:Micro-merchants require instant settlement and simple reconciliation tools without enterprise complexity. QRIS standardization in Indonesia enables single-code acceptance across competing wallet platforms.
- Corporates:Treasury management and bulk disbursement capabilities demand API-first architecture with audit trails. India's enterprise payout market and Brazil's B2B payment corridors show concentrated procurement of corporate wallet solutions.
- Freelancers:Gig workers need rapid access to earnings with minimal documentation burden. Platform-integrated wallets for drivers and delivery couriers in Mexico and Colombia address this segment's cash-flow volatility.
Retail consumers anchor total addressable volume; freelancers represent the steepest expansion trajectory as gig economy participation broadens.
Device Type:
Hardware capabilities and portability constraints shape authentication methods and use-case viability across form factors.
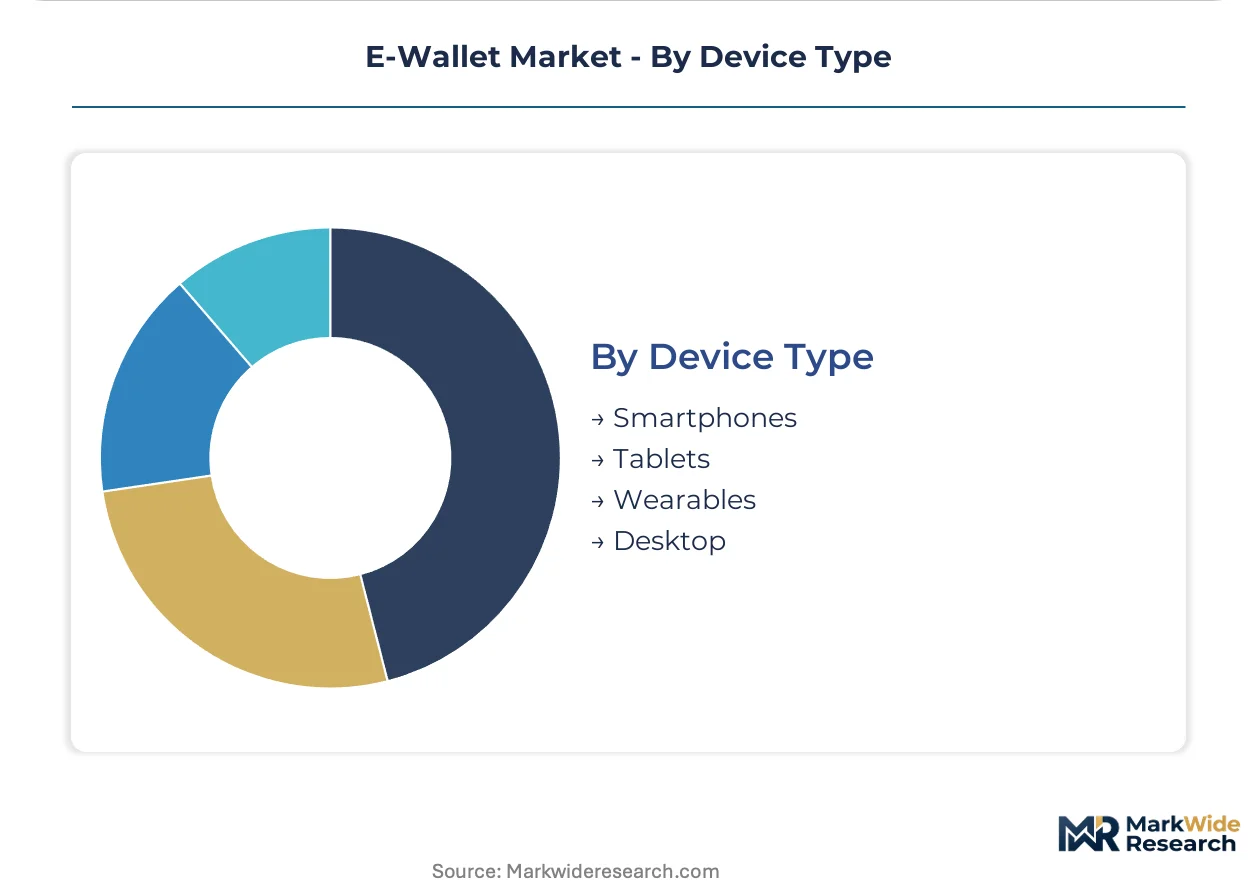
- Smartphones:Biometric sensors and ubiquitous cellular penetration make handsets the default wallet deployment target. India's feature-phone-to-smartphone migration is expanding addressable biometric-authenticated users by hundreds of millions.
- Tablets:Larger screens suit kiosk and counter-top merchant acceptance with customer-facing interfaces. Quick-service restaurants in Malaysia and retail pharmacies in Thailand deploy tablet-based checkout terminals.
- Wearables:NFC-enabled watches and rings enable truly contactless transit and micropayment scenarios. Singapore's MRT and London's TfL demonstrate mature wearable payment adoption for daily commuting.
- Desktop:Browser-based wallets persist for high-value e-commerce and corporate procurement workflows. Cross-border B2B marketplaces in the Netherlands and UAE maintain desktop-first checkout experiences.
Smartphones process the dominant transaction share; wearables are expanding most quickly as transit operators open fare collection to private wallet providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys e-wallets primarily for merchant QR payments at street vendors, while Brazil concentrates volume on utility bill settlements—revealing how unbanked penetration shapes divergent consumption patterns across emerging corridors.
China
Alipay and WeChat Pay dominate retail checkout through super-app ecosystems integrating social, transit, and wealth management functions. SAMR enforces antitrust scrutiny on platform payment monopolies, forcing interoperability openings. Shenzhen and Hangzhou anchor fintech R&D clusters where facial recognition terminals achieve sub-500 millisecond authorization latency.
India
UPI interoperability mandates by RBI collapse friction between competing wallet balances, expanding merchant acceptance networks to 50 million touchpoints. Full KYC compliance requirements for balance thresholds above specified limits shape product architecture. Mumbai and Bangalore concentrate startup activity where biometric-authenticated onboarding reduces customer acquisition costs for first-time financial service users.
Indonesia
QRIS standardization enables single-code acceptance across GoPay, OVO, and DANA platforms, accelerating cash displacement among 90 million unbanked adults. Data localization mandates require server placement within national borders, elevating infrastructure capex for foreign entrants. Jakarta and Surabaya drive transit system integration where KRL commuter rail opens fare collection to private wallet providers.
Brazil
Pix instant payment rails displace traditional wallet balances for peer-to-peer transfers, forcing providers toward merchant lending adjacencies. Banco Central do Brasil regulates payment institution licensing with tiered capital requirements. São Paulo anchors B2B payment corridor development where enterprise treasury solutions capture corporate disbursement volume.
United States
Card-linked wallets dominate e-commerce checkout through deep platform integrations, contrasting with bank-direct rails prevalent in developing markets. State-level money transmission licensing creates compliance fragmentation for national deployment. San Francisco and New York concentrate fintech infrastructure where embedded finance distribution models collapse distinctions between payment instruments and software surfaces.
E-Wallet Market Vendor Landscape
Capability concentration sits with super-app platforms integrating merchant networks, financial services, and social functions; scale advantage sits with card network-linked providers anchoring e-commerce checkout flows. The vendor base stratifies across three tiers: closed-loop ecosystem operators, open banking infrastructure providers, and standalone payment utilities. Dominant competitive moves include strategic partnerships with transit operators and merchant lending portfolio diversification.
Within the super-app tier, Ant Group and WeChat Pay exemplify ecosystem lock-in architectures that consolidate daily recurring transactions within single interfaces. PayPal occupies a position representing card-linked scale advantages across North American digital commerce corridors. These anchors illustrate how geographic origin and corporate structure shape divergent strategic positioning—Hangzhou-based Ant Group as a fintech conglomerate versus California-incorporated PayPal as a standalone payments platform.
| Leading Market Players |
|---|
| PayPal |
| Alipay |
| Apple Pay |
| Cash App |
| WeChat Pay |
| Ant Group |
| Block Inc. |
| Revolut |
| Google Pay |
| Others |
Supply Flow & Price Mechanics
Shenzhen's fintech R&D cluster anchors biometric terminal manufacturing capacity, concentrating hardware cost leverage among Alipay and WeChat Pay suppliers. This geographic density cascades into downstream pricing power for wallet providers deploying facial recognition infrastructure across Chinese transit corridors.
Pricing Analysis
Southeast Asian corridors exhibit wider price spreads than North American markets, with Indonesian QRIS-enabled transactions commanding lower merchant discount rates than Singapore's premium biometric terminals. Transaction-based pricing dominates, with interchange economics stratifying across premium facial-recognition deployments, standard QR-code acceptance, and economy-tier carrier-billed micropayments. Price differentiation rests on authentication hardware sophistication and settlement speed guarantees. Pricing pressure stems from India's regulatory caps on merchant discount rates. Small-business merchants in Indonesia's warung sector demonstrate highest price sensitivity; corporate treasury clients in Brazil's B2B corridors show lowest.
Supply Chain Analysis
Extended payment terms from Taiwan's semiconductor foundries and supply-chain finance facilities through Singaporean trade banks shape component procurement for biometric authentication hardware. Hardware assembly concentrates in China, Vietnam, and Malaysia. NFC chipsets, palm-vein sensors, and secure element modules constitute critical input dependencies. Single-source vulnerability runs through Taiwan's advanced semiconductor node access. Distribution runs through OEM direct contracts with smartphone manufacturers and transit operator procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent wallet providers face substitution defense against central bank digital currency pilots threatening direct balance disintermediation. This structural threat demands repositioning toward value-added services that CBDC rails cannot replicate.
For Market Incumbents: Entrench merchant network density through exclusive transit system partnerships in Jakarta and Bangkok, capturing daily recurring payment behavior that CBDC infrastructure cannot easily replicate. Deepen data exhaust monetization into merchant lending products. Vertical integration into biometric terminal manufacturing secures hardware cost leverage against fintech challengers.
For New Entrants and Emerging Players: Indonesia's unbanked population corridors in Eastern Java and Sulawesi present the most penetrable white space, where QRIS standardization has collapsed acceptance friction but financial service penetration remains below 40%. Target gig economy freelancers through platform-embedded wallet distribution rather than standalone app acquisition. Go-to-market leverage rests on ride-hailing and food delivery super-app integration partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a data infrastructure play because transaction exhaust enables cash-flow-based underwriting products unavailable through traditional credit bureaus. Acquisition targets should profile as regional wallet providers with dense small-business merchant networks and established banking partnerships for settlement rails. Monitor CBDC pilot expansion timelines as the critical inflection signal for private wallet balance displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Transit System Integration | Jakarta's KRL and Bangkok's BTS capture daily recurring payment behavior through exclusive fare collection partnerships. |
| Merchant Lending Portfolio Development | Transaction data exhaust enables cash-flow-based underwriting for Indonesia's warung sector beyond traditional credit bureau access. |
| Biometric Terminal Deployment | Facial recognition infrastructure in Shenzhen and Singapore achieves sub-500 millisecond authorization latency for premium merchant tiers. |
| Cross-Border Remittance Licensing | ASEAN payment connectivity initiatives create licensed corridors bypassing correspondent banking delays and SWIFT fee structures. |
| Super-App Ecosystem Lock-In | Grab and Gojek native balance systems concentrate transaction volume within closed platforms without external wallet exposure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, payment volume disclosures, and transit operator procurement records. Primary interviews engaged wallet product executives, merchant acquiring leads, central bank digital currency program directors, and biometric hardware procurement managers. Secondary validation drew from RBI circulars, SAMR antitrust determinations, BI-FAST network statistics, and ASEAN payment connectivity memoranda. Bottom-up transaction volume modeling triangulates against top-down addressable market sizing across the analysis window.
Forecast inputs encompass payment method segmentation, service type margin structures, end-user adoption curves, and device type hardware penetration. The analytical framework models merchant payment rails, peer-to-peer transfer economics, in-app embedded checkout, and bill-splitting utilities across the projection horizon. CAGRs derive from regression analysis against smartphone penetration trajectories, biometric authentication hardware cost curves, and regulatory interoperability mandate implementation timelines. UPI transaction velocity and QRIS merchant acceptance expansion serve as India- and Indonesia-specific demand inputs.
Practitioners should monitor central bank digital currency pilot acceleration, merchant discount rate regulatory compression, and biometric hardware cost deflation for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
QR Codes Payment Market
Payments
United Arab Emirates Payment Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Australia Mobile Payment Market
Payments
Qatar Payments Market
Payments
Europe Clearing Houses and Settlements Market
Payments
India Gift Card and Incentive Card Market
Payments
Canada Real Time Payments Market
Payments
Transit Cards Market
Payments
Estonia POS Terminal Market
Payments
Canada Payment Gateway Market
Payments
Global Payment Monitoring Market
Payments
Europe Mobile Payment Market
Payments
Global Smart Payment Systems Market
Payments
Accelerator Card Market