
 Instant Payments Market | 2026-2036
Instant Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Payments Market Foresight
Software-defined routing layers is broadening what payment infrastructure providers monetize beyond transaction fees. Stripe leverages developer-centric APIs to anchor its position among platforms requiring embedded finance capabilities. JPMorgan Chase sustains institutional trust through its private blockchain settlement rails for corporate treasury clients. Adyen differentiates via single-platform consolidation of acquiring, issuing, and risk management across multiple geographies.
Instant payments denote electronic fund transfers that clear and settle within seconds through real-time gross settlement or deferred net settlement systems, typically operating on ISO 20022 messaging standards with 24/7 availability. Their primary commercial purpose is eliminating float periods between payer and payee, thereby reducing working capital requirements for businesses and improving liquidity management across supply chains. The credit transfer segment dominates transaction volume among financial institutions seeking to modernize legacy ACH rails, while mobile payment adoption accelerates fastest among retailers integrating QR-code acceptance into point-of-sale terminals. Blockchain-based settlement occupies the highest-margin tier within merchant services, where cross-border remittance friction creates pricing power for infrastructure operators.
The European Banking Authority enforces PSD2 open-access requirements that compel incumbent banks to expose account interfaces to licensed third-party providers, directly expanding addressable market entry for fintech intermediaries. The Reserve Bank of India mandates zero Merchant Discount Rate on UPI transactions below specified thresholds, reshaping revenue model viability for domestic payment aggregators. The US Federal Reserve's FedNow service establishes a regulatory-backed instant settlement alternative to private real-time networks, altering competitive dynamics for domestic financial institutions. Stakeholders must monitor how divergent national approaches to interchange regulation and data localization reshape cross-border payment architecture investments.
Market Dynamics
ISO 20022 migration is compressing clearing windows and forcing wholesale infrastructure replacement among correspondent banks and payment processors. This messaging standard shift is redistributing competitive advantage toward technology-native platforms capable of real-time data enrichment.
Growth Catalysts
- Open banking mandates:PSD2 in the European Union and similar frameworks in the United Kingdom compel incumbent banks to expose APIs, expanding third-party provider access to settlement rails.
- QR-code POS integration:Retailers across India and Southeast Asia are embedding instant acceptance into physical checkout flows, accelerating merchant onboarding velocity.
- Corporate treasury modernization:Real-time liquidity visibility is displacing end-of-day batch reconciliation for multinational working capital management.
Market Restraints
- Interference from legacy ACH networks:Deferred net settlement systems in the United States and Europe retain entrenched merchant relationships and switching costs.
- Zero-fee regulatory caps:India's Merchant Discount Rate elimination on low-value UPI transactions compresses aggregator margins and limits reinvestment capacity.
- Cross-border fragmentation:Divergent national data localization requirements prevent seamless interoperability between domestic instant payment schemes.
Strategic Opportunities
- Brazilian instant payment expansion:Pix adoption creates whitespace for cross-border settlement bridges connecting Latin American corridors to Asian real-time networks.
- Request-to-pay messaging:ISO 20022 structured remittance data enables invoice-to-payment automation for B2B procurement platforms.
- Embedded finance convergence:Software platforms integrating instant disbursement capabilities with accounting and ERP workflows capture merchant stickiness.
Industry Challenges
- ISO 20022 implementation timelines:Financial institutions face compressed migration deadlines for message format compliance across multiple clearing systems simultaneously.
- Fraud detection latency requirements:Sub-second settlement windows constrain risk scoring sophistication, exposing platforms to authorized push payment fraud.
- Core banking integration complexity:Real-time 24/7 availability demands conflict with legacy batch-oriented ledger architectures requiring parallel infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Payments Market |
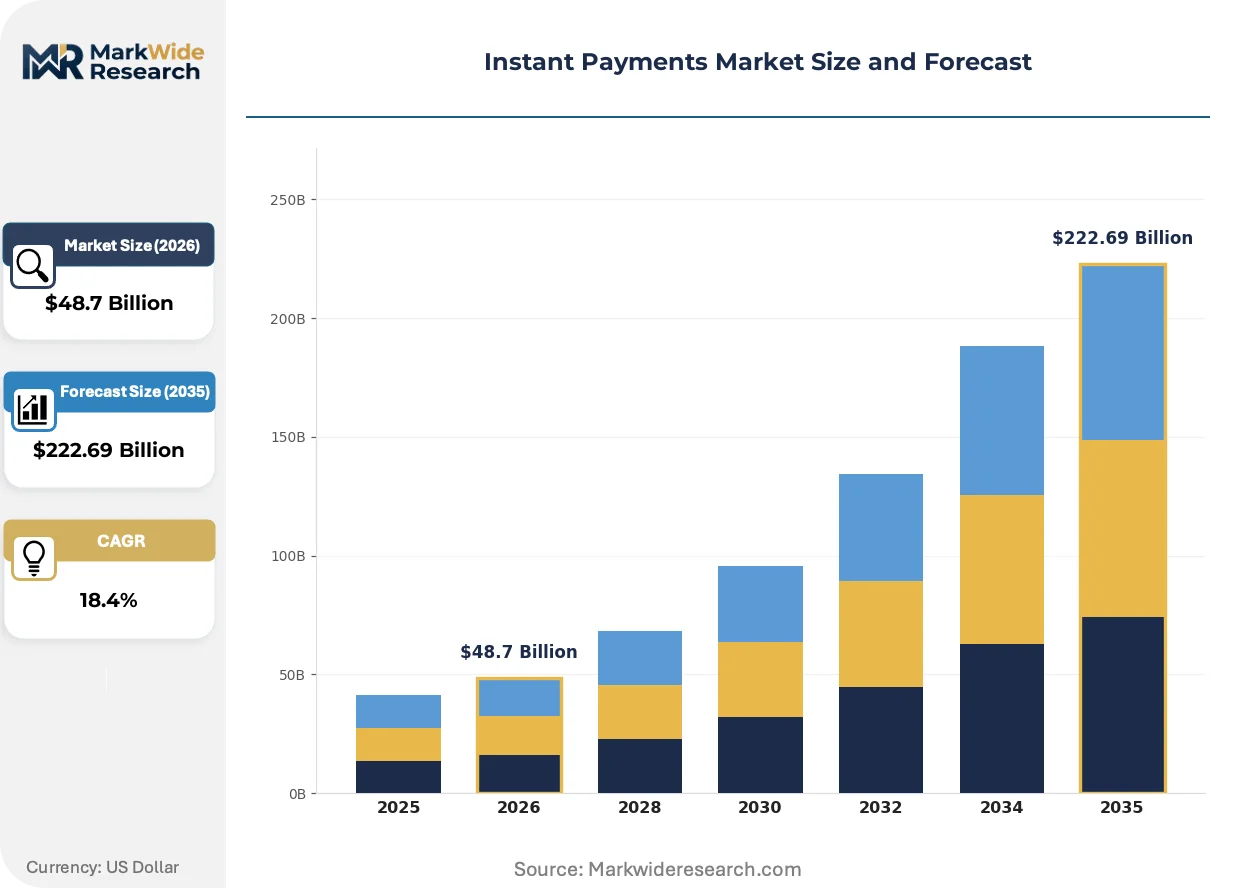
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Transfer, Mobile Payment, Digital Wallet, Instant Bank Transfer Technology: Blockchain, NFC, QR Code, Payment Gateway End User: Retailers, E-commerce Platforms, Financial Institutions, Corporates Service Type: Consumer Services, Merchant Services, Business Transactions, Peer-to-Peer |
| Companies Covered | Ripple, Moov Financial, Stripe, Global Payments, PayPal, Adyen, Zelle, Block, JPMorgan Chase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Payments Market Shifts & Advancements
Software-defined payment orchestration is dissolving traditional distinctions between issuance, acquiring, and risk management. Infrastructure providers now compete on developer experience and data velocity rather than network scale alone.
Artificial intelligence-powered transaction monitoring is rewriting fraud prevention economics for real-time environments. Tier-1 banks in Singapore and the United Kingdom deploy machine learning models scoring payments in under 50 milliseconds. This capability is compressing the window for manual intervention and shifting liability frameworks toward algorithmic accountability.
The European Banking Authority's PSD3 consultation proposes stricter strong customer authentication requirements and enhanced refund rights for instant credit transfers. These provisions would extend open banking access while tightening liability allocation between payers and payment service providers. Retail banks in Germany and France are accelerating authentication infrastructure investment to preempt compliance deadlines.
Merchant expectations for immediate fund availability are reshaping payment processor value propositions. Platforms serving gig economy marketplaces and on-demand delivery services now mandate T+0 settlement as a table-stakes requirement. This pattern is most pronounced in urban India and Indonesia, where cash flow velocity directly determines vendor participation rates.
Instant Payments Market Segmentation
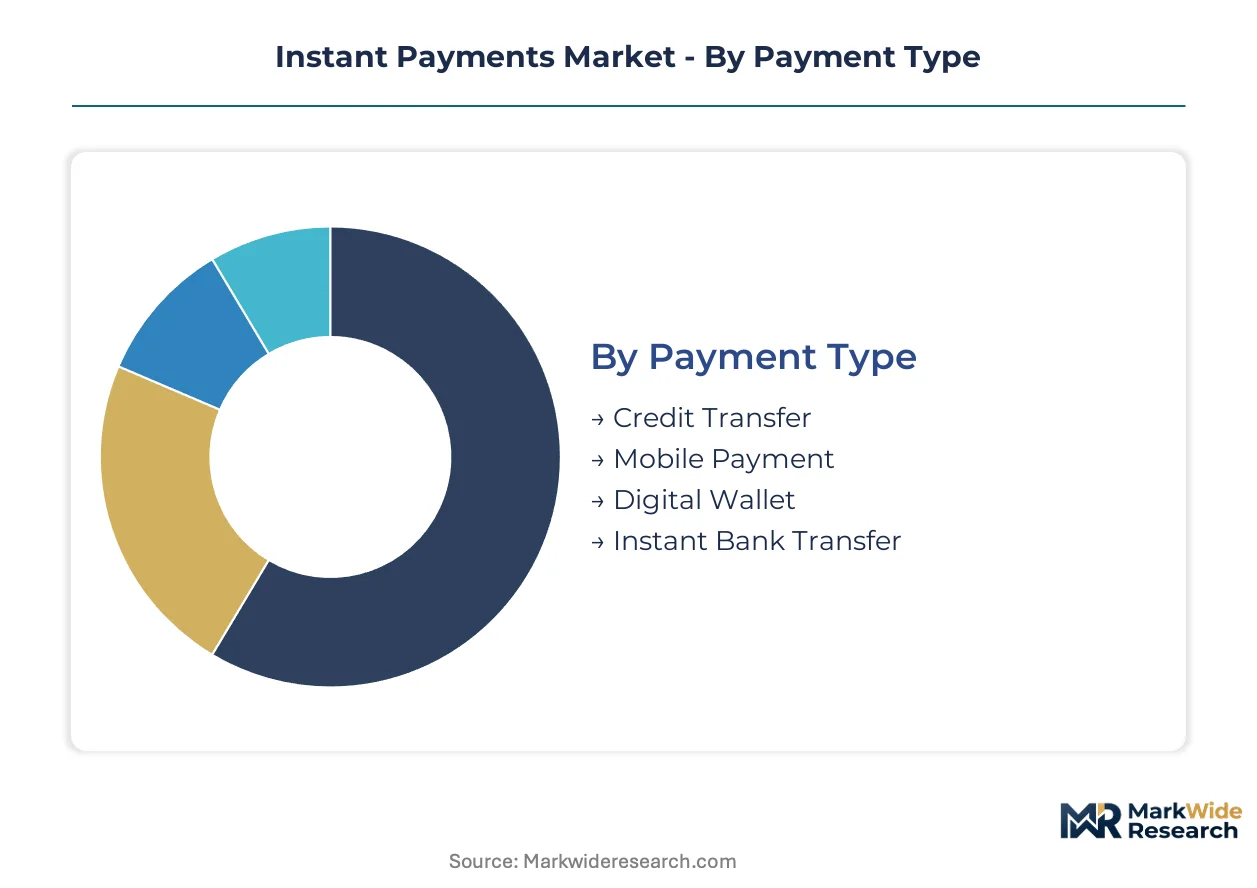
Instant payment architectures fragment across settlement rails, authentication technologies, and commercial use cases. Each dimension carries distinct regulatory certification requirements and infrastructure investment profiles that determine competitive viability.
Payment Type:
Certification burden concentrates on ISO 20022 messaging compliance for credit transfer rails, while mobile payment schemes face device-level security attestation from hardware manufacturers.
- Credit Transfer:Real-time gross settlement systems process high-value corporate disbursements through direct central bank connectivity. Demand clusters among financial institutions modernizing legacy ACH infrastructure in Germany and Singapore, where the Bundesbank and MAS mandate ISO 20022 migration deadlines.
- Mobile Payment:Device-native wallets leverage tokenized credentials stored in secure elements or host card emulation. Merchant adoption accelerates in urban India and Indonesia, where QR-code acceptance at point-of-sale terminals eliminates terminal hardware costs for small retailers.
- Digital Wallet:Cloud-credential platforms integrate loyalty and transit functionality through super-app ecosystems.
- Instant Bank Transfer:Account-to-account push payments bypass card networks entirely, requiring only payer authentication.
Credit Transfer sits at the top of the volume ranking, with Mobile Payment climbing the fastest.
Technology:
Cost tier stratification separates capital-intensive blockchain infrastructure from lightweight QR-code deployments that minimize merchant onboarding friction.
- Blockchain:Distributed ledger settlement enables programmable escrow and atomic cross-currency swaps for correspondent banking relationships. Infrastructure operators targeting Brazil-Asia remittance corridors exploit Pix-UPI interoperability pilots to capture margin from correspondent fee compression.
- QR Code:Static and dynamic barcode standards dominate emerging market retail penetration where terminal density remains low. Regulatory mandates from the Reserve Bank of India standardizing interoperable QR specifications accelerated merchant acquisition velocity.
- NFC:Contactless acceptance requires certified payment terminals and consumer device compatibility.
- Payment Gateway:Orchestration layers aggregate multiple settlement rails behind unified merchant APIs.
Payment Gateway commands the largest installed base, with Blockchain expanding most quickly.
End User:
Application-specific requirements differentiate treasury-grade uptime guarantees for corporates from consumer-facing fraud liability frameworks.
- Corporates:Treasury management platforms demand real-time liquidity visibility across multi-currency positions and subsidiary accounts. Working capital optimization drives replacement of end-of-day batch reconciliation with intraday position monitoring.
- E-commerce Platforms:Marketplace operators require instant disbursement to sellers and escrow release automation. T+0 settlement has become mandatory for gig economy participation in Southeast Asian urban corridors.
- Financial Institutions:Banks modernize core systems to support 24/7 availability conflicting with legacy batch architectures.
- Retailers:Physical merchants prioritize checkout speed and interchange cost reduction.
Financial Institutions anchor current infrastructure spending, with E-commerce Platforms gaining share fastest.
Service Type:
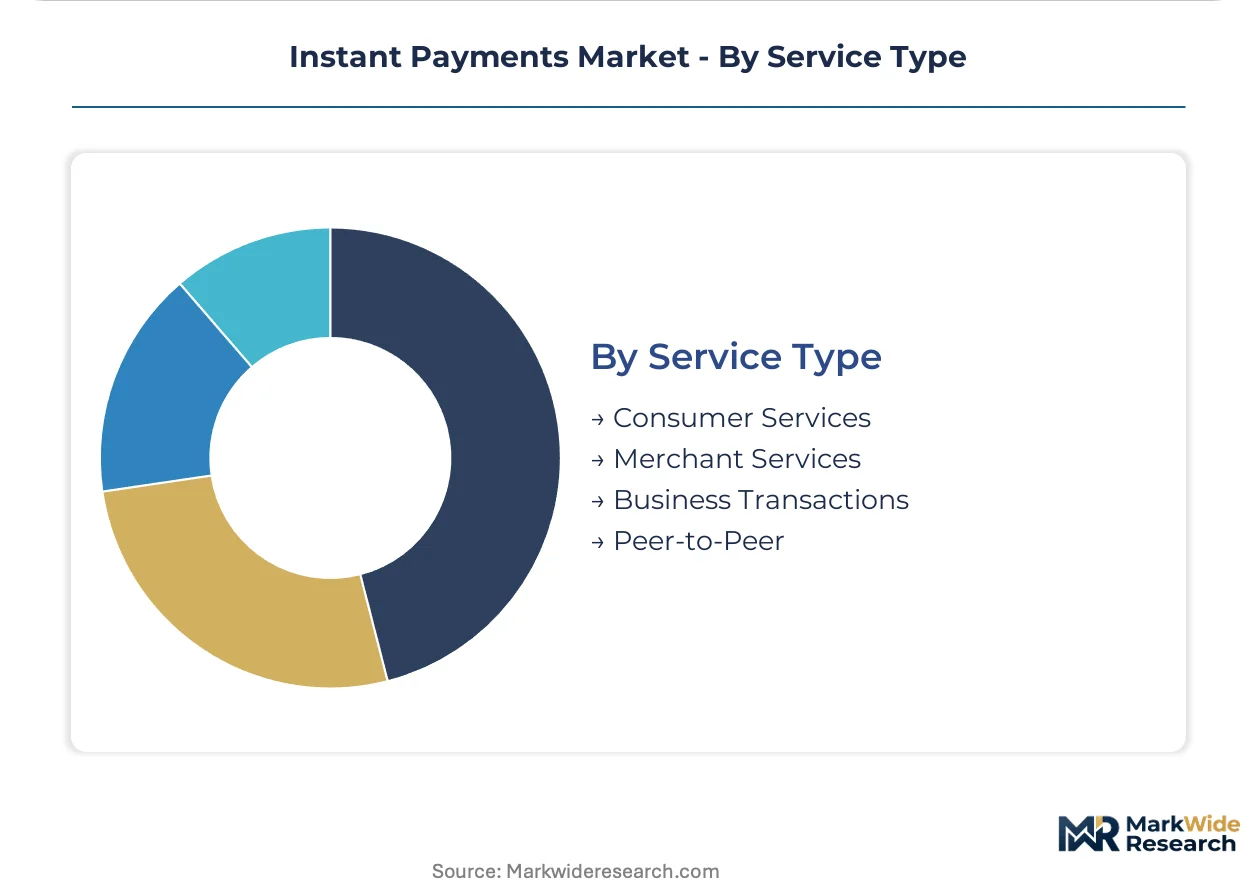
Margin structure varies from thin-fee consumer services to high-value B2B transaction banking with embedded FX and risk management.
- Business Transactions:Request-to-pay messaging combined with structured remittance data automates invoice matching and procurement reconciliation. ISO 20022 data enrichment enables straight-through processing for enterprise ERP integration.
- Merchant Services:Acquiring and instant settlement convergence captures merchant stickiness through fund availability guarantees. Competitive pressure from zero-fee regulatory caps in India compresses aggregator margins and forces volume scale economics.
- Consumer Services:Retail payment apps compete on authentication convenience and loyalty integration.
- Peer-to-Peer:Social payment functionality drives user acquisition with minimal monetization.
Merchant Services generates the highest revenue concentration, with Business Transactions showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes more retail digital transactions through real-time rails than the United States and Germany combined, while Brazil's Pix network has achieved comparable penetration rates in half the deployment time.
United States
Corporate treasury departments at Fortune 500 manufacturers drive demand for real-time liquidity visibility across multi-currency positions. The Federal Reserve's FedNow service establishes regulatory-backed instant settlement infrastructure that competes with private real-time networks. New York-based money center banks are modernizing core systems to support 24/7 availability conflicting with legacy batch architectures.
India
Urban gig economy marketplaces mandate T+0 settlement as a table-stakes requirement for vendor participation across food delivery and ride-hailing platforms. The Reserve Bank of India mandates zero Merchant Discount Rate on UPI transactions below specified thresholds, compressing aggregator margins. Mumbai and Bangalore fintech clusters dominate payment aggregator licensing and QR-code merchant acquisition velocity.
Germany
Automotive suppliers and industrial manufacturers seek real-time gross settlement for high-value B2B procurement reconciliation. The Bundesbank mandates ISO 20022 migration deadlines for credit transfer rails serving corporate treasury clients. Frankfurt's banking concentration anchors infrastructure investment for request-to-pay messaging automation.
Brazil
Small retailers and informal merchants accelerate QR-code POS integration to eliminate terminal hardware costs and capture previously cash-based transactions. The Central Bank of Brazil's Pix regulation standardizes interoperable instant payment rails across all licensed financial institutions. São Paulo's fintech corridor hosts the dominant share of Pix-enabled payment aggregators targeting cross-border settlement bridges to Asian networks.
Singapore
Wealth management platforms and family offices demand sub-second settlement for multi-currency portfolio rebalancing. The Monetary Authority of Singapore enforces strict fraud detection latency requirements through machine learning scoring models under 50 milliseconds. The city-state's banking hub concentrates Tier-1 bank investment in AI-powered transaction monitoring for real-time environments.
Instant Payments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology-native platforms capturing developer-centric segments while incumbent banks retain institutional trust through private infrastructure. The vendor base concentrates around three strategic archetypes: API-first infrastructure providers, single-platform consolidators, and blockchain settlement specialists. M&A activity targets payment orchestration capabilities, while geographic expansion focuses on bridging Latin American and Asian real-time networks.
Within the technology-native tier, Stripe and Moov Financial exemplify developer-centric API strategies that anchor embedded finance capabilities among platforms requiring instant disbursement integration. JPMorgan Chase occupies a distinct position among incumbent banks leveraging private blockchain settlement rails for corporate treasury relationships. Adyen represents the single-platform consolidation archetype, spanning acquiring, issuing, and risk management across multiple geographies without fragmentation.
| Leading Market Players |
|---|
| Ripple |
| Moov Financial |
| Stripe |
| Global Payments |
| PayPal |
| Adyen |
| Zelle |
| Block |
| JPMorgan Chase |
| Others |
Supply & Pricing Matrix
ISO 20022 migration compresses clearing windows while simultaneously concentrating infrastructure investment among technology-native platforms capable of real-time data enrichment, reshaping both cost economics and supplier power across correspondent banking relationships. This messaging standard shift forces wholesale replacement of legacy batch systems, creating divergent cost structures between incumbent banks maintaining parallel architectures and cloud-native entrants operating single-stack environments.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for transaction processing services as zero-fee regulatory caps compress aggregator margins and force volume scale economics. Three-tier pricing structure across premium treasury-grade, standard merchant-acquiring, and economy peer-to-peer levels differentiates by settlement speed guarantees and fraud liability coverage. Cost compression in standard-tier acquiring intensifies because India's Merchant Discount Rate elimination on low-value UPI transactions removes traditional revenue per-transaction. E-commerce platforms and gig economy marketplaces demonstrate highest price sensitivity, demanding T+0 settlement as table-stakes without premium tolerance, while corporate treasury clients accept premium pricing for real-time liquidity visibility and multi-currency position management.
Supply Chain Analysis
Direct-to-bank API channels handle hyperscale fintech demand, bypassing traditional payment processor intermediaries. Infrastructure concentration centers on the United States, India, and Singapore, where regulatory clarity and central bank backing anchor core system investment. Raw material dependencies include cloud compute capacity from hyperscalers, cryptographic hardware security modules, and ISO 20022 message validation software licenses. Single-source vulnerability runs through SWIFT network dependencies for cross-border message routing, exposing domestic instant payment schemes to correspondent banking friction. Distribution runs through developer-centric platform marketplaces and direct enterprise sales to corporate treasury departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's zero-fee regulatory compression and Brazil's open-banking expansion, where divergent national approaches to interchange regulation create cost and margin differentials for infrastructure operators.
For Market Incumbents: Anticipate authorized push payment fraud exposure as sub-second settlement windows constrain risk scoring sophistication, mandating machine learning investment under 50-millisecond latency thresholds. Consolidate ISO 20022 implementation timelines across multiple clearing systems simultaneously to preempt compliance deadline conflicts. Vertical integration into private blockchain settlement rails defends institutional trust among corporate treasury relationships against API-first infrastructure entrants. For New Entrants and Emerging Players: API-first orchestration layers targeting embedded finance convergence represent the most penetrable white-space, capturing merchant stickiness through instant disbursement integration with accounting and ERP workflows. Brazilian cross-border settlement bridges connecting Pix to Asian real-time networks offer geographic expansion with limited incumbent saturation. Go-to-market positioning should anchor on developer experience and data velocity rather than network scale alone. For Investors and Strategic Acquirers: Valuations sit cheapest among payment orchestration specialists with multi-rail aggregation capabilities but limited geographic footprint, as M&A activity concentrates on bridging Latin American and Asian networks. Long-term viability across the projection horizon hinges on regulatory-backed instant settlement infrastructure rather than private real-time networks vulnerable to FedNow-style displacement. The signal to watch is central bank interoperability pilots between domestic instant payment schemes, indicating infrastructure consolidation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Infrastructure Migration | Compliance deadlines from Bundesbank and MAS force wholesale system replacement among correspondent banks. |
| Cross-Border Settlement Bridge | Pix-UPI interoperability pilots capture margin from correspondent fee compression in Brazil-Asia corridors. |
| AI-Powered Fraud Detection | Machine learning scoring under 50 milliseconds rewrites prevention economics for Tier-1 banks in Singapore. |
| Embedded Finance Integration | Instant disbursement capabilities with ERP workflows capture merchant stickiness in gig economy platforms. |
| Request-to-Pay Messaging | Structured remittance data enables straight-through processing for enterprise procurement reconciliation. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with payment infrastructure executives, central bank regulatory leads, corporate treasury directors, fintech platform engineers, and merchant acquiring specialists. Secondary validation draws from SEC filings of listed payment processors, central bank payment system reports, ISO 20022 migration disclosures, and customs data on cryptographic hardware imports. Bottom-up transaction volume estimates and top-down macroeconomic allocation triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume expansion from value-per-transaction evolution across payment type, technology, end user, and service type dimensions. Segmentation modeling incorporates settlement rail architecture, authentication technology tier, and commercial use case complexity alongside geographic regulatory cluster patterns. CAGRs derive from historical trajectory analysis adjusted for policy inflection points including open banking mandates and interchange regulation shifts. Industry-specific forecast inputs include UPI transaction velocity data and Pix adoption curves.
The model holds under stable regulatory enforcement of PSD2-style open access and zero-fee caps; deviation in central bank interoperability timelines or data localization requirements would shift cross-border infrastructure investment patterns. Forecasts reflect assumptions regarding ISO 20022 migration adherence and fraud detection technology diffusion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Digital Remittance Service Market
Payments
Finland Payments Market
Payments
Slovakia POS Terminal Market
Payments
Portugal Mobile Payments Market
Payments
Europe Mobile Payment Market
Payments
Sweden Mobile Payments Market
Payments
3D Secure Pay Authentication Market
Payments
Mobile POS Market
Payments
Japan POS Terminals Market
Payments
UAE Card Payments Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Smart Payment Market
Payments
Hong Kong Credit Cards Market
Payments
Netherlands POS Terminal Market
Payments
Australia Buy Now Pay Later Services Market