
 United States Clearing Houses and Settlements Market | 2026-2036
United States Clearing Houses and Settlements Market Size, Share, and Industry Trends Forecast 2026-2036
United States Clearing Houses and Settlements Market Outlook
Multi-source clearing arrangements is restructuring how buy-side firms manage counterparty exposure across equity and fixed-income transactions. DTCC sustains dominant infrastructure for US equity and fixed-income post-trade processing through its NSCC and FICC subsidiaries. Options Clearing Corporation anchors the listed derivatives segment with its monopoly over standardized equity options. ICE Clear US competes aggressively in the energy and credit derivatives clearing space with specialized margin methodologies.
Clearing houses and settlements constitute financial market utilities that interpose themselves between trading counterparties to guarantee performance, manage collateral, and effect final transfer of securities versus payment. These entities operate through legally protected novation processes, substituting their own creditworthiness for that of original counterparties while maintaining margin pools and default funds as financial buffers. Real-time gross settlement commands premium pricing structures due to its elimination of settlement risk through immediate finality, while blockchain-enabled clearing experiments remain confined to pilot programs and regulatory sandboxes. Cross-border payment services represent the fastest-expanding segment as correspondent banking networks face pressure from faster payment alternatives.
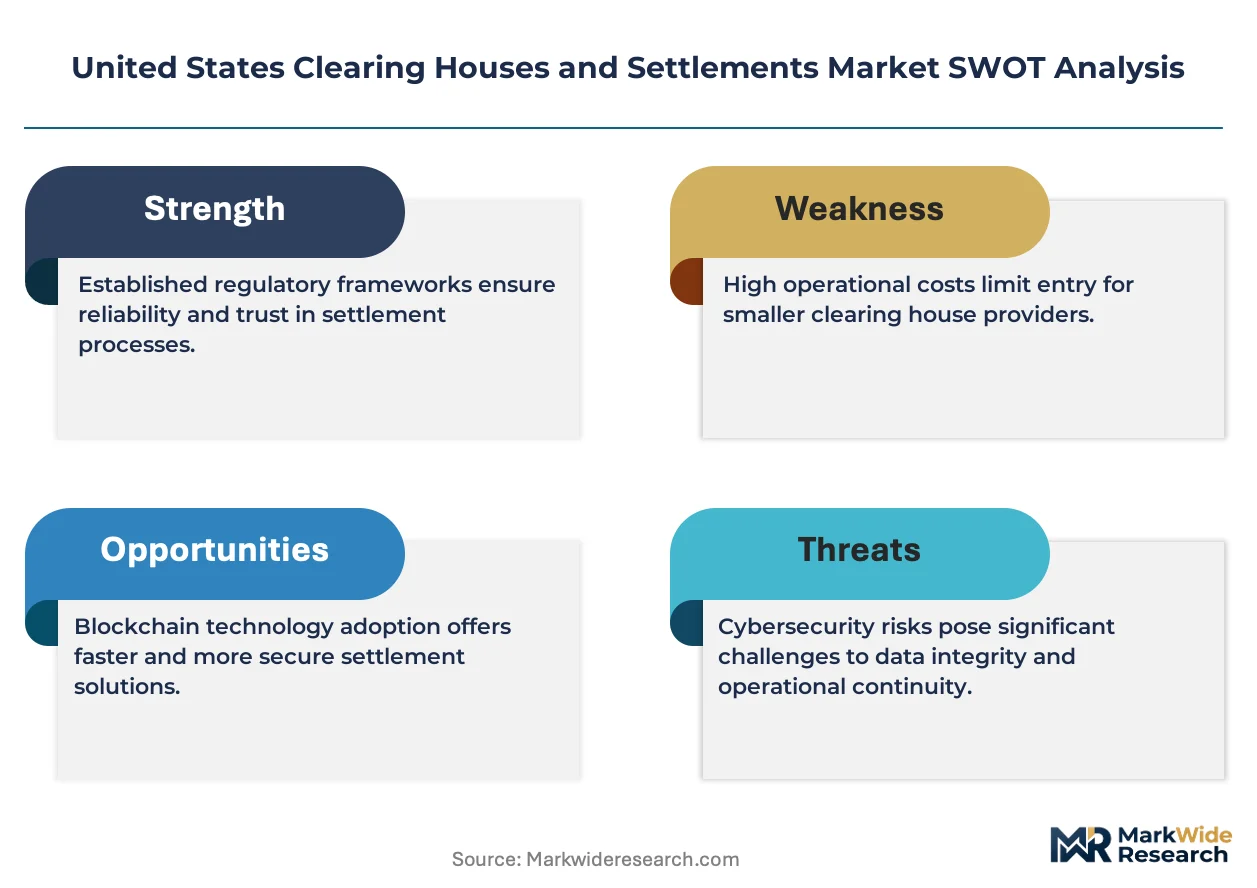
The SEC's T+1 settlement mandate, the CFTC's margin requirements for uncleared swaps, and the Federal Reserve's FedNow instant payment rails collectively reshape operational requirements for clearing infrastructure. These frameworks compress processing windows, elevate collateral demands, and create new interoperability obligations between traditional and real-time settlement channels. Stakeholders must monitor how regulatory pressure for settlement acceleration interacts with the capital intensity required to upgrade legacy batch-processing architectures.
Market Dynamics
SEC's T+1 settlement mandate compresses operational timelines across US clearing infrastructure, forcing asset managers and broker-dealers to reengineer batch-processing architectures for same-day affirmation and funding.
Growth Catalysts
- FedNow instant payment rails:The Federal Reserve's real-time gross settlement system eliminates settlement risk through immediate finality, creating premium pricing structures for clearing utilities that integrate these rails.
- Centralized counterparty exposure management:Asset managers are consolidating clearing relationships to reduce operational fragmentation across equity and fixed-income transactions.
- CFTC margin requirements for uncleared swaps:These rules elevate collateral demands and drive volume into cleared alternatives, expanding FICC's credit derivatives processing footprint.
Market Restraints
- Legacy system upgrade costs:Mainframe-dependent clearing architectures require substantial capital expenditure to achieve T+1 processing speeds without operational interruption.
- Concentrated geographic infrastructure risk:Primary data centers cluster in New York and Chicago, creating single-point-of-failure exposure for nationwide settlement continuity.
- Blockchain settlement immaturity:Distributed ledger experiments remain confined to regulatory sandboxes, preventing scalable alternatives to centralized novation models.
Strategic Opportunities
- Cross-border payment acceleration:Correspondent banking networks face displacement pressure, opening white space for clearing utilities to capture international payment flows.
- Interoperability mandates:Regulatory pressure for traditional and real-time settlement channel integration creates new service tiers for infrastructure providers.
- Energy derivatives specialization:Specialized margin methodologies in power and environmental markets attract non-traditional clearing members seeking collateral efficiency.
Industry Challenges
- Talent scarcity in real-time systems engineering:Clearinghouses compete for specialists capable of redesigning batch-oriented platforms for continuous processing.
- Integration complexity with legacy affiliate systems:NSCC and FICC participants face middleware reconfiguration demands to synchronize with compressed settlement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Clearing Houses and Settlements Market |
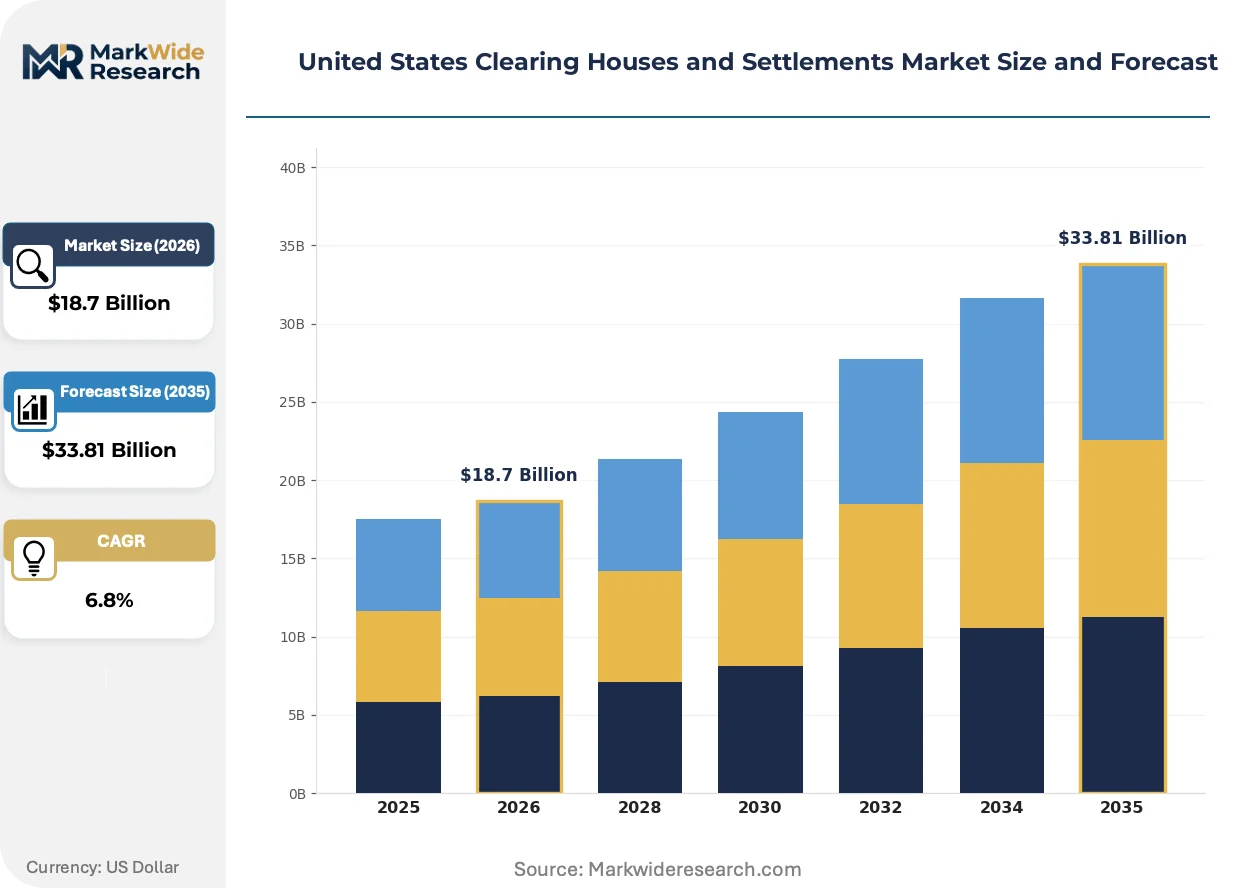
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real-time Gross Settlement, Instant Payment, Bulk Payment, Cross-border Payment Technology: Blockchain, Centralized Ledger, Decentralized Network, Digital Currency End User: Financial Institutions, Corporates, Governments, Retail Customers Transaction Type: Interbank Transfer, Peer-to-peer, Credit Transfer, Debit Transfer |
| Companies Covered | DTCC, National Securities Clearing Corporation, Fixed Income Clearing Corporation, The Clearing House, Options Clearing Corporation, Chicago Mercantile Exchange Clearing, ICE Clear US, New York Stock Exchange, NASDAQ, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Clearing Houses and Settlements Market Strategic Shifts
Settlement infrastructure is bifurcating between accelerated traditional rails and experimental distributed architectures, with regulatory mandates forcing adoption timelines faster than organic technology maturation would permit.
Distributed ledger technology is expanding into securities settlement pilots, substituting cryptographic finality for legal novation in limited-use cases. DTCC's Project Ion and similar initiatives test tokenized equities against regulatory benchmarks. The structural consequence is expanding into correspondent banking displacement as real-time gross settlement models prove operational viability.
SEC's T+1 settlement mandate compels same-day trade affirmation and eliminates fails coverage windows. Broker-dealers must reconfigure funding operations and securities lending programs. Prime services desks at major US brokerages face the most acute compression, accelerating automation investment to maintain service levels.
Buy-side firms are consolidating clearing relationships to reduce operational fragmentation and counterparty exposure monitoring overhead. Asset managers previously maintaining ten to fifteen clearing arrangements now target three to five strategic partnerships. This concentration is most visible among mid-sized institutional investors seeking operational leverage against margin and funding cost pressures.
United States Clearing Houses and Settlements Market Segmentation
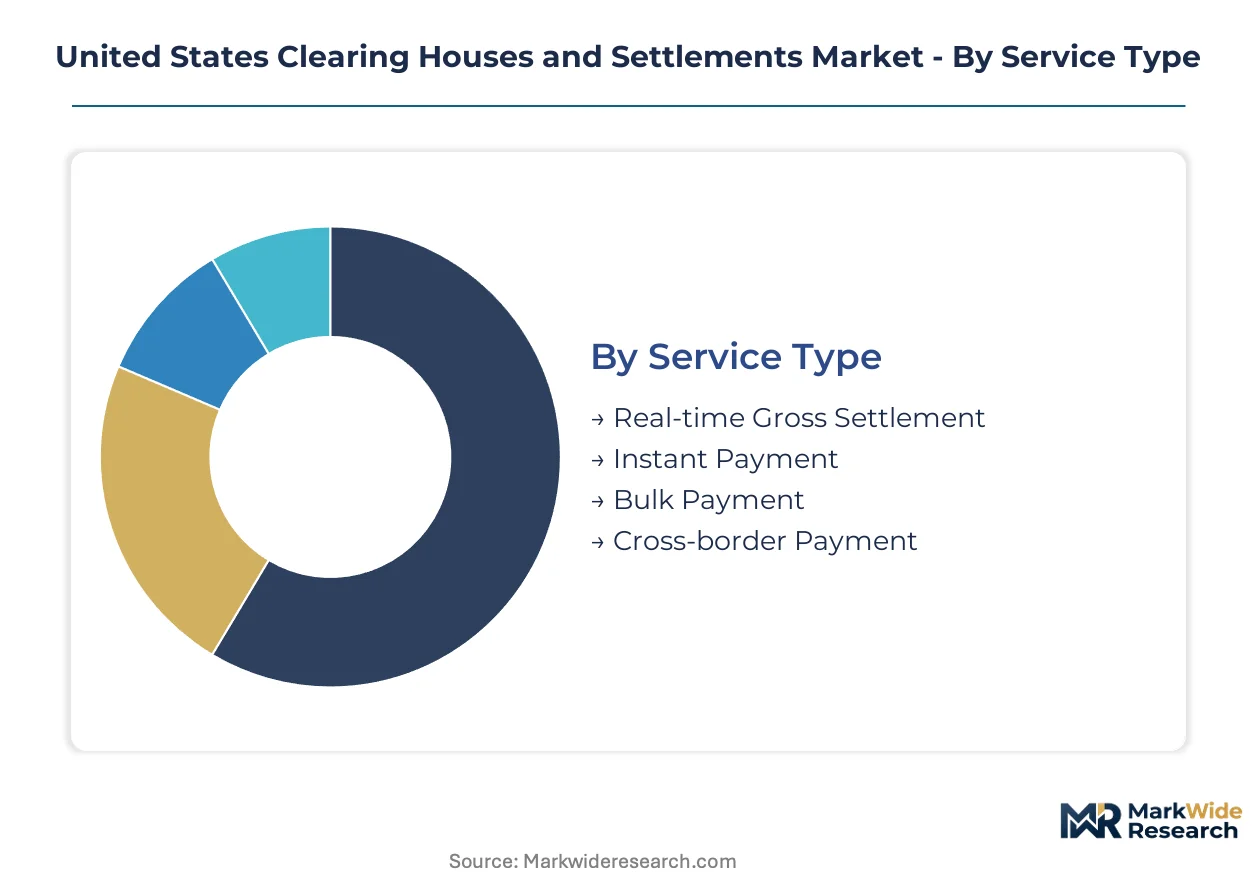
Clearing and settlement infrastructure serves heterogeneous participant needs across velocity, risk tolerance, and regulatory constraints. Segmentation reveals how service tiers align with operational requirements from wholesale interbank flows to retail payment finality.
Service Type:
Settlement velocity determines infrastructure architecture and pricing structures across the service spectrum.
- Real-time Gross Settlement:Immediate finality eliminates settlement risk through continuous gross fund transfers. Demand concentrates at Federal Reserve member banks processing high-value wholesale transactions, driven by intraday liquidity optimization requirements under SEC and Federal Reserve oversight.
- Instant Payment:Sub-ten-second confirmation enables retail and commercial use cases previously served by card networks. Newer deployment is concentrated in regional banks integrating FedNow rails to compete with non-bank payment providers.
- Bulk Payment:Batch processing of aggregated transactions maintains cost efficiency for payroll and dividend distributions. Corporate treasury departments in manufacturing and healthcare sectors drive sustained volume.
- Cross-border Payment:Correspondent banking alternatives face displacement from specialized clearing utilities offering FX-embedded settlement. Fintech-bank partnerships are expanding most quickly in this tier.
Mature deployment sits with Bulk Payment. Newer deployment is concentrated in Instant Payment.
Technology:
Ledger architecture choices reflect trade-offs between operational control, interoperability burden, and regulatory acceptance.
- Blockchain:Distributed consensus mechanisms substitute cryptographic finality for legal novation in pilot programs. DTCC's Project Ion and similar initiatives test tokenized equities against SEC benchmarks, with demand concentrated in derivatives post-trade automation.
- Centralized Ledger:Single-operator control maintains regulatory clarity and operational predictability. NSCC and FICC processing for US equity and fixed-income securities represents the dominant deployment model.
- Decentralized Network:Multi-party validation without central coordination remains experimental. Regulatory sandboxes at the CFTC limit scalable deployment.
- Digital Currency:Wholesale CBDC exploration and stablecoin settlement rails attract institutional interest. Banking consortiums are gaining share fastest in cross-border remittance corridors.
Mature deployment sits with Centralized Ledger. Newer deployment is concentrated in Digital Currency.
End User:
Participant scale and regulatory status shape clearing access tiers and service level agreements.
- Financial Institutions:Banks, broker-dealers, and asset managers constitute the core clearing membership with direct central counterparty access. Prime brokerage and custody operations in New York and Chicago anchor demand.
- Corporates:Non-financial enterprises access clearing through sponsored membership or bank intermediation. Treasury centralization trends are expanding most quickly among Fortune 500 entities.
- Governments:Federal, state, and municipal entities require specialized settlement for securities issuance and tax processing. Fedwire and FedNow integration supports debt management operations.
- Retail Customers:Individual participants access clearing indirectly through broker-dealers and payment apps. Mobile-first platforms are climbing the fastest in payment volume.
Mature deployment sits with Financial Institutions. Newer deployment is concentrated in Retail Customers.
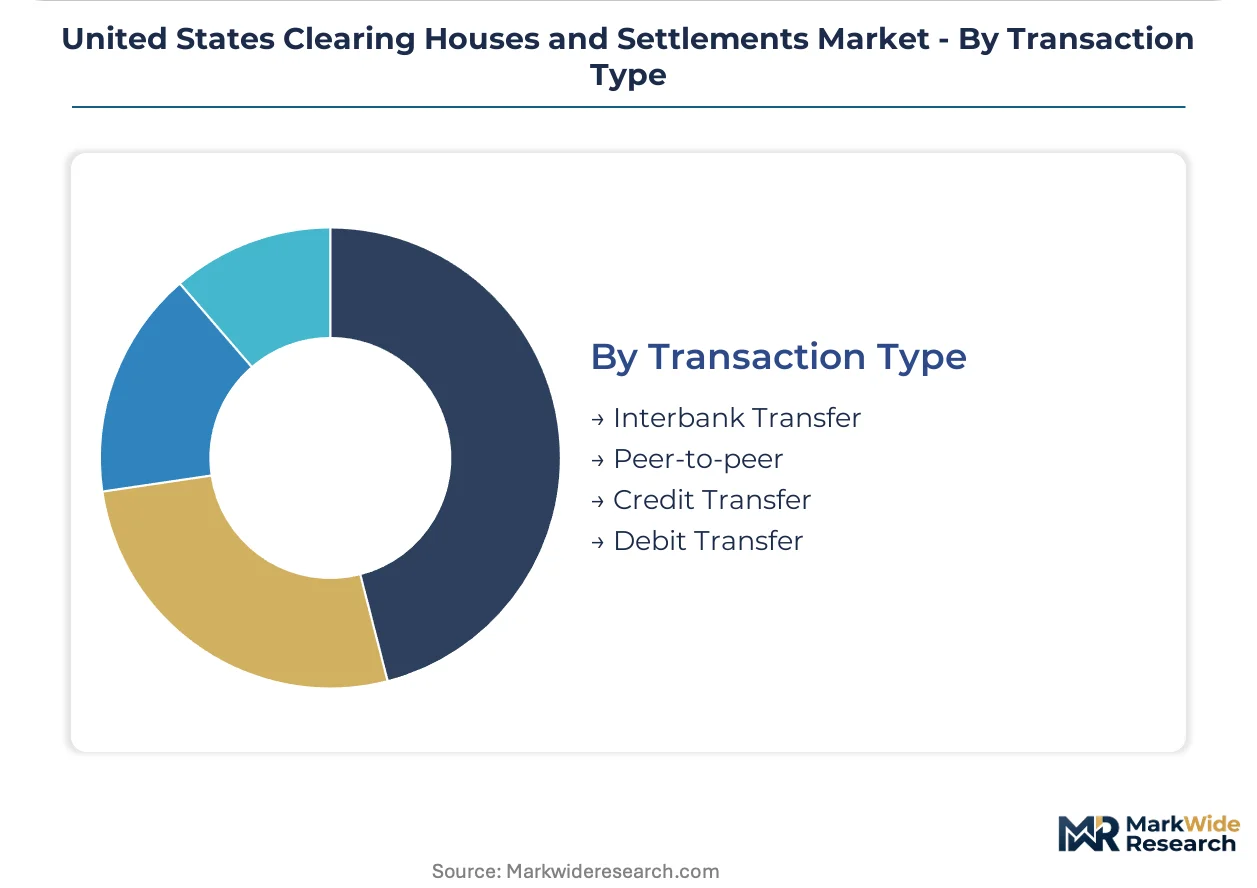
Transaction Type:
Payment initiation methods determine messaging standards, confirmation workflows, and dispute resolution frameworks.
- Interbank Transfer:Large-value wholesale movements between depository institutions settle through Fedwire and CHIPS. Reserve account management at the Federal Reserve Bank of New York drives operational requirements.
- Peer-to-peer:Direct consumer-to-consumer transfers bypass traditional correspondent networks. Real-time payment network participation is expanding most quickly among community banks.
- Credit Transfer:Payer-initiated push payments dominate commercial and payroll applications. ACH modernization supports same-day settlement adoption.
- Debit Transfer:Payee-initiated pull payments require pre-authorization frameworks. Utility and subscription billing sustains volume concentration.
Mature deployment sits with Interbank Transfer. Newer deployment is concentrated in Peer-to-peer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary data centers for clearing infrastructure cluster in financial hubs where fiber density and power redundancy support millisecond settlement finality.
New York Metro
DTCC's headquarters and NSCC processing facilities anchor equity and fixed-income post-trade operations. The SEC's T+1 settlement mandate drives same-day affirmation automation investment. Manhattan and Jersey City data centers host the critical matching engines for Fedwire and CHIPS integration.
Chicago
Options Clearing Corporation maintains its monopoly infrastructure for listed equity derivatives clearing. CFTC margin requirements for uncleared swaps elevate collateral processing volumes. The Loop district concentrates CME Clearing's futures and options settlement architecture.
Dallas-Fort Worth
ICE Clear US operates specialized energy derivatives clearing with collateral methodologies for power markets. Texas grid independence attracts disaster recovery and backup processing facilities. The Metroplex corridor expands as secondary data center capacity for primary New York and Chicago operations.
Boston
Asset manager consolidation of clearing relationships concentrates operational decision-making in fund management clusters. Massachusetts regulatory frameworks for investment advisers shape custody and settlement service procurement. The Seaport District houses fintech infrastructure firms integrating with DTCC rails.
San Francisco Bay Area
Technology-enabled clearing startups pilot blockchain settlement experiments in regulatory sandboxes. The Federal Reserve Bank of San Francisco oversees western payment system operations. Silicon Valley venture deployment targets real-time gross settlement middleware for institutional clients.
United States Clearing Houses and Settlements Market Competitive Environment
Global majors compete with regional champions across clearing utility provision, though geographic regulatory boundaries limit direct competition. The market structure concentrates around federally designated systemically important financial market utilities. Three archetypes dominate: central counterparty clearinghouses with monopoly franchises, exchange-affiliated clearing subsidiaries with specialized asset class focus, and bank consortium utilities for payment finality. Consolidation through regulatory designation and interoperability mandates shapes competitive positioning more than price competition.
Within the designated systemically important utility tier, DTCC represents the archetype of vertically integrated post-trade infrastructure spanning multiple asset classes. Options Clearing Corporation occupies a position as a specialized derivatives clearing monopoly with singular regulatory charter. ICE Clear US exemplifies exchange-affiliated clearing with targeted energy and credit derivatives specialization.
| Leading Market Players |
|---|
| DTCC |
| National Securities Clearing Corporation |
| Fixed Income Clearing Corporation |
| The Clearing House |
| Options Clearing Corporation |
| Chicago Mercantile Exchange Clearing |
| ICE Clear US |
| New York Stock Exchange |
| NASDAQ |
| Others |
Value Chain & Pricing Dynamics
SEC climate disclosure rules for financial market utilities gate qualified supply partnerships and premium-tier pricing access for clearing infrastructure providers. Compliance with the regulator's emissions reporting mandates requires data center operators to document carbon intensity across New York and Chicago facilities, filtering vendor pools and stratifying service tiers.
Pricing Analysis
Service-level bundling distinguishes full-stack clearing packages from unbundled transaction processing. Three-tier pricing structure across premium, standard, and economy levels segments by settlement velocity and affirmation automation depth. Price differentiation hinges on real-time gross settlement integration and default fund contribution requirements. Asset managers with concentrated clearing relationships demonstrate lowest price sensitivity, while regional broker-dealers face acute margin compression from T+1 upgrade costs.
Supply Chain Analysis
Dual-sourcing requirements for critical data center capacity mandate clearinghouses qualify multiple co-location providers across primary and backup sites. Supply concentrates in Northern Virginia, Dallas-Fort Worth, and Phoenix for hyperscale facility construction. Raw material dependencies span specialized cooling systems, redundant fiber optic interconnects, and uninterruptible power infrastructure. Tariff exposure on Chinese-manufactured server equipment elevates capital expenditure volatility. Distribution runs through direct procurement contracts with Tier III and Tier IV certified facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time systems engineering talent scarcity props pricing power across clearing infrastructure tiers, constraining capacity expansion velocity. Qualified personnel pools for legacy mainframe modernization remain shallower than T+1 mandate timelines demand.
For Market Incumbents: Deploy FedNow rail integration as the priority lever to capture premium settlement flows before competitor certification. Consolidate data center footprints in Dallas-Fort Worth to exploit Texas grid independence for disaster recovery capacity. Defend against fintech middleware entrants by accelerating API standardization across NSCC and FICC participant interfaces.
For New Entrants and Emerging Players: The mid-market price-point gap between DTCC's bundled utility pricing and regional bank self-clearing costs creates white-space opportunity. Target sponsored clearing membership for mid-sized asset managers consolidating from ten-plus relationships toward three strategic partnerships. Pursue cross-border payment corridor specialization as the most penetrable segment, leveraging correspondent banking displacement pressure.
For Investors and Strategic Acquirers: CFTC designation of additional systemically important derivatives clearing organizations is the leading indicator that regulatory fragmentation will favor multi-utility platforms. Long-term viability across the analysis window favors vertically integrated post-trade infrastructure spanning equities, fixed income, and derivatives. Monitor SEC staff statements on T+0 exploration as the signal for next-generation settlement architecture investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Gross Settlement Integration | FedNow rail certification enables premium pricing for immediate finality services. |
| Legacy System Modernization | Mainframe-to-cloud migration compresses T+1 affirmation windows without operational interruption. |
| Cross-Border Payment Corridor Expansion | Correspondent banking displacement opens white space for FX-embedded settlement utilities. |
| Energy Derivatives Specialization | ICE Clear US's power market margin methodologies attract non-traditional clearing members. |
| Blockchain Settlement Pilot Advancement | DTCC's Project Ion tests tokenized equities against SEC regulatory benchmarks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with clearing operations executives, data center infrastructure planners, and securities lending desk heads at asset managers and broker-dealers were combined with SEC rulemaking dockets, DTCC processing volume disclosures, and Federal Reserve payment system reports. Bottom-up transaction flow modeling and top-down utility revenue triangulation validated segmentation outputs.
Granularity-level modeling deployed service type, technology architecture, end-user scale, and transaction velocity as core segmentation dimensions. CAGRs were derived from regression analysis across historical processing volume trajectories and regulatory mandate implementation schedules. Cross-border payment acceleration curves and T+1 operational readiness scores served as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; real-time gross settlement and instant payment tiers carry tighter precision than bulk payment and cross-border corridors due to disclosed FedNow adoption metrics. Forecasts reflect assumptions regarding regulatory timeline adherence and technology upgrade completion rates. Deviation in SEC T+0 exploration announcements or CFTC margin rule recalibration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Direct Carrier Billing Platform Market
Payments
Global Accounts Payable Software Market
Payments
Accelerator Card Market
Payments
Digital Remittance Service Market
Payments
Smart POS System Market
Payments
Vietnam E-Wallet Market
Payments
Cloud Billing Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Digital Payment in Healthcare Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
North America Payment Analytics Software Market
Payments
3D Secure Payment Authentication Market
Payments
Smart Home Payments Market
Payments
South Korea Real Time Payments Market
Payments
United Kingdom Payment Market
Payments
Digital Payment Market