
 Blockchain in Smart Home Market | 2026-2036
Blockchain in Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Smart Home Market Outlook
Decentralized identity verification is narrowing the attack surface for connected residential devices. Comcast leverages its broadband infrastructure to anchor blockchain node distribution across North American households. Xage Security specializes in edge-native security architectures that extend tamper-resistant consensus to thermostat and sensor networks. IOTA Foundation competes through its feeless distributed ledger protocol designed specifically for resource-constrained IoT endpoints.
Blockchain in Smart Home denotes a distributed trust architecture where cryptographic consensus validates device-to-device transactions without centralized intermediaries, typically operating on lightweight proof-of-stake or directed acyclic graph protocols that maintain sub-second finality on gateway-class hardware. Its primary purpose is to eliminate single points of failure in residential automation while creating immutable audit trails for energy, access, and maintenance events. Smart Locks currently dominate product-type revenue as hardware margin pools concentrate on physical-digital authentication convergence. Smart Contracts within the technology dimension represent the fastest-growing structural segment, automating peer-to-peer energy trading between prosumers without utility intermediation. Homeowners as an end-user category sustain the volume base, though Property Managers capture disproportionate value through portfolio-scale keyless access orchestration.
FCC guidelines on IoT cybersecurity labeling in the United States intersect with GDPR data minimization principles enforced by European regulators to shape product development roadmaps for cross-border vendors. ETSI standards for cyber security of consumer IoT devices, adopted across EU member states, mandate cryptographic credential storage that blockchain architectures satisfy natively. Stakeholders must monitor whether national building codes begin requiring auditable device provenance as a condition for smart home insurance underwriting.
Market Dynamics
The residential automation sector is experiencing a fundamental trust architecture migration. Homeowners and property managers are rejecting centralized cloud dependency in favor of cryptographic consensus mechanisms that validate device interactions locally.
Growth Catalysts
- GDPR data minimization mandates:European regulators enforce strict limits on cross-border data flows. Blockchain-enabled local verification satisfies these requirements without cloud intermediation.
- Edge computing maturation:Gateway-class hardware now processes sub-second finality for resource-constrained IoT endpoints. This technical threshold unlocks practical deployment at thermostat and sensor scale.
- Prosumer energy trading:Distributed generation adoption creates peer-to-peer electricity exchange demand. Smart contracts automate settlement without utility intermediation.
Market Restraints
- Silicon supply concentration:Cryptographic processor fabrication depends on TSMC and Samsung foundry capacity. Geographic concentration in Taiwan and South Korea creates vulnerability.
- EU AI Act compliance costs:Automated decision systems in residential security face mandatory risk classification. Small vendors lack resources for conformity assessment.
- Legacy Wi-Fi protocol persistence:Installed base of 802.11n devices cannot support modern encryption standards. Replacement cycles stretch hardware depreciation timelines.
Strategic Opportunities
- India smart city integration:National urban digitization programs prioritize decentralized identity for municipal service access. Residential blockchain layers align with broader infrastructure.
- Insurance underwriting mandates:German and Swiss carriers pilot auditable device provenance requirements. Policy discounts incentivize tamper-proof access logging.
- 5G network slicing convergence:Isolated bandwidth partitions enable dedicated consensus channels. Telecom operators seek value-added residential services beyond connectivity.
Industry Challenges
- Embedded cryptography talent scarcity:Secure element design requires specialized hardware-software integration skills. Universities produce insufficient graduates for vendor hiring needs.
- Cross-protocol interoperability:Competing ledger architectures fragment device ecosystems. Homeowners face stranded asset risk from format obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Smart Home Market |
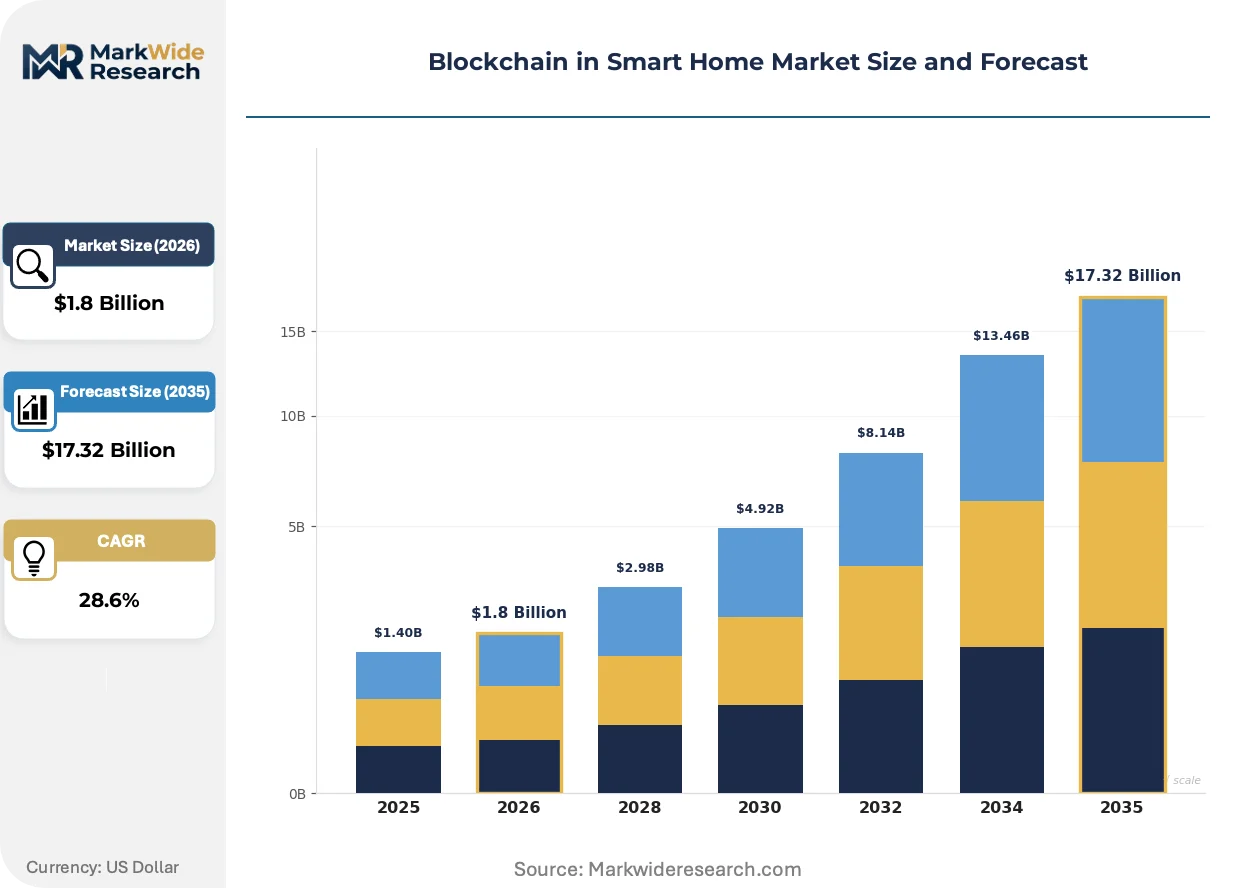
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Locks, Smart Lighting, Smart Thermostats, Smart Sensors Technology: Distributed Ledger, Smart Contracts, IoT Integration, Cryptography End User: Homeowners, Property Managers, Real Estate Developers, Service Providers Application: Energy Management, Security, Home Automation, Remote Monitoring |
| Companies Covered | Comcast, Telstra, OSIZ Technologies, Blockchain App Factory, Xage Security, Mobiloitte, Teksun, SoluLab, IOTA Foundation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Smart Home Market Strategic Shifts
Residential automation is abandoning hub-and-spoke architectures for mesh-validated trust networks. Three developments are compressing deployment timelines and restructuring competitive positioning.
Directed acyclic graph protocols are collapsing the cost barrier for feeless micro-transactions between resource-constrained endpoints. Property managers deploying portfolio-scale keyless access systems adopt these architectures to eliminate per-transaction gas fees. The compression of operating economics is displacing traditional proof-of-stake implementations in high-frequency sensor environments.
FCC guidelines on IoT cybersecurity labeling intersect with ETSI consumer device security standards to mandate cryptographic credential storage. Cross-border vendors must engineer single hardware SKUs satisfying both regulatory regimes. The compliance burden falls heaviest on budget-tier smart lock manufacturers lacking dedicated certification teams.
Hardware-as-a-service subscriptions are replacing upfront device purchases in multi-family residential deployments. Property technology platforms bundle installation, maintenance, and keyless orchestration into monthly fees. This model concentrates fastest in German and Dutch rental markets where tenant turnover demands rapid credential reissuance.
Blockchain in Smart Home Market Segmentation
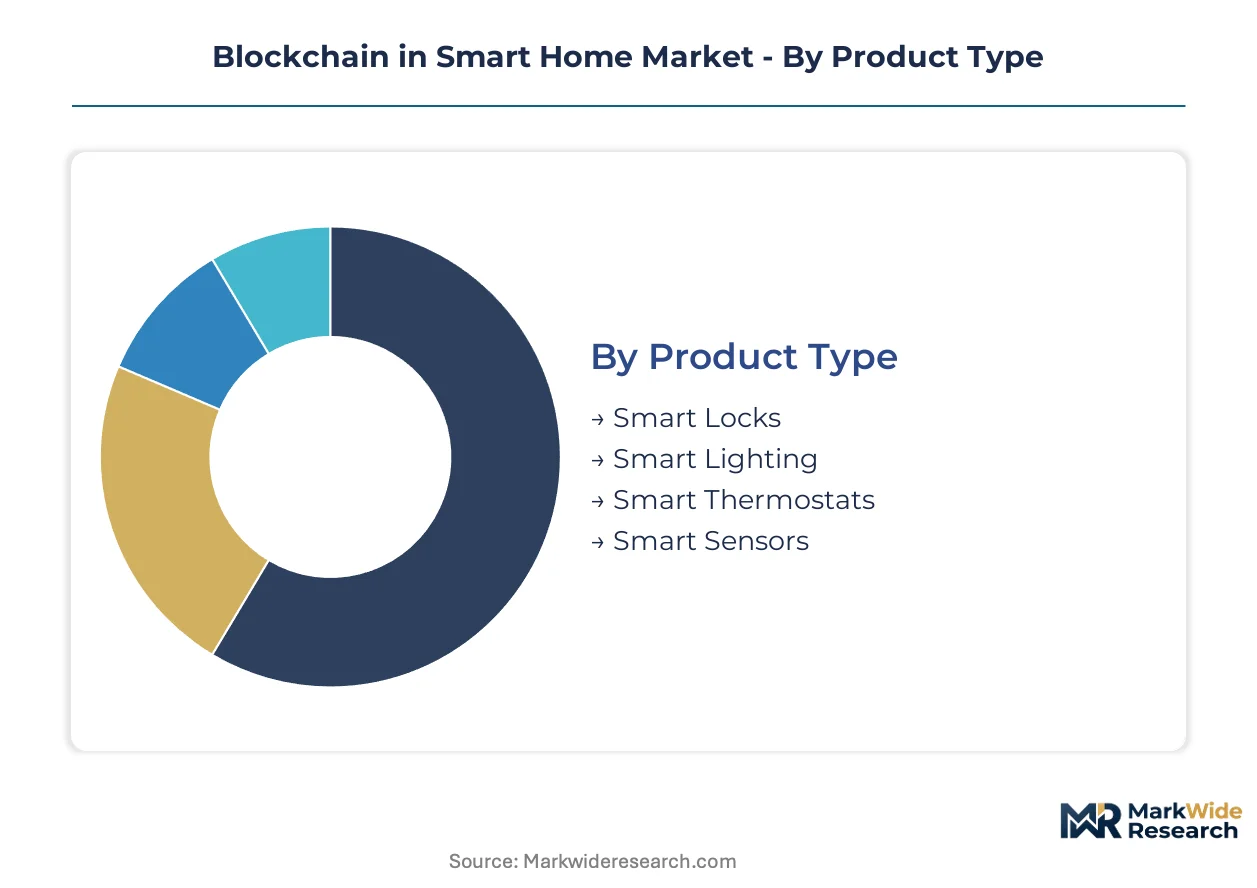
Blockchain deployment in residential environments fragments across hardware form factors, protocol layers, and stakeholder economics. Each segmentation axis reveals distinct margin pools and technical requirements that shape vendor R&D allocation and partnership strategies.
Product Type:
Mature physical-digital authentication hardware sits alongside emerging climate-control endpoints where consensus mechanisms remain experimental.
- Smart Locks:Tamper-resistant credential storage anchors device-to-cloud authentication pipelines. German property managers and Swiss insurance underwriters drive specification intensity for audit-grade access logging.
- Smart Lighting:Mesh-networked luminaires execute localized consensus for energy attribution. Demand concentrates in Dutch multi-family rentals where hardware-as-a-service subscriptions accelerate replacement cycles.
- Smart Thermostats:Gateway-class processors enable sub-second finality for HVAC automation.
- Smart Sensors:Resource-constrained endpoints favor feeless directed acyclic graph protocols.
Smart Locks handle the majority of throughput; Smart Sensors are expanding most quickly on share.
Technology:
Cost tier stratification separates capital-intensive infrastructure from lightweight protocol implementations.
- Distributed Ledger:Immutable transaction records eliminate single points of failure in device orchestration. Property technology platforms in Germany deploy these architectures for portfolio-scale credential management.
- Smart Contracts:Self-executing settlement logic automates peer-to-peer energy trading between residential prosumers. EU prosumer tariff reforms accelerate deployment timelines.
- IoT Integration:Edge-native consensus extends cryptographic validation to thermostat and sensor networks.
- Cryptography:Secure element design satisfies ETSI consumer device mandates for credential isolation.
Distributed Ledger captures the largest installed base; Smart Contracts are climbing the fastest on deployment velocity.
End User:
Customer type determines contract structure and lifetime value calculations across residential deployments.
- Homeowners:Individual purchasers prioritize tamper-proof access control and energy audit transparency. GDPR data minimization requirements steer specification toward local verification architectures.
- Property Managers:Portfolio-scale operators demand rapid credential reissuance and centralized orchestration dashboards. German and Dutch rental markets show strongest subscription model adoption.
- Real Estate Developers:Pre-installation contracts favor standardized hardware SKUs satisfying cross-border regulatory regimes.
- Service Providers:Maintenance and monitoring contracts create recurring revenue attachment to device deployment.
Homeowners sustain the volume base; Property Managers generate disproportionate value through portfolio economics.
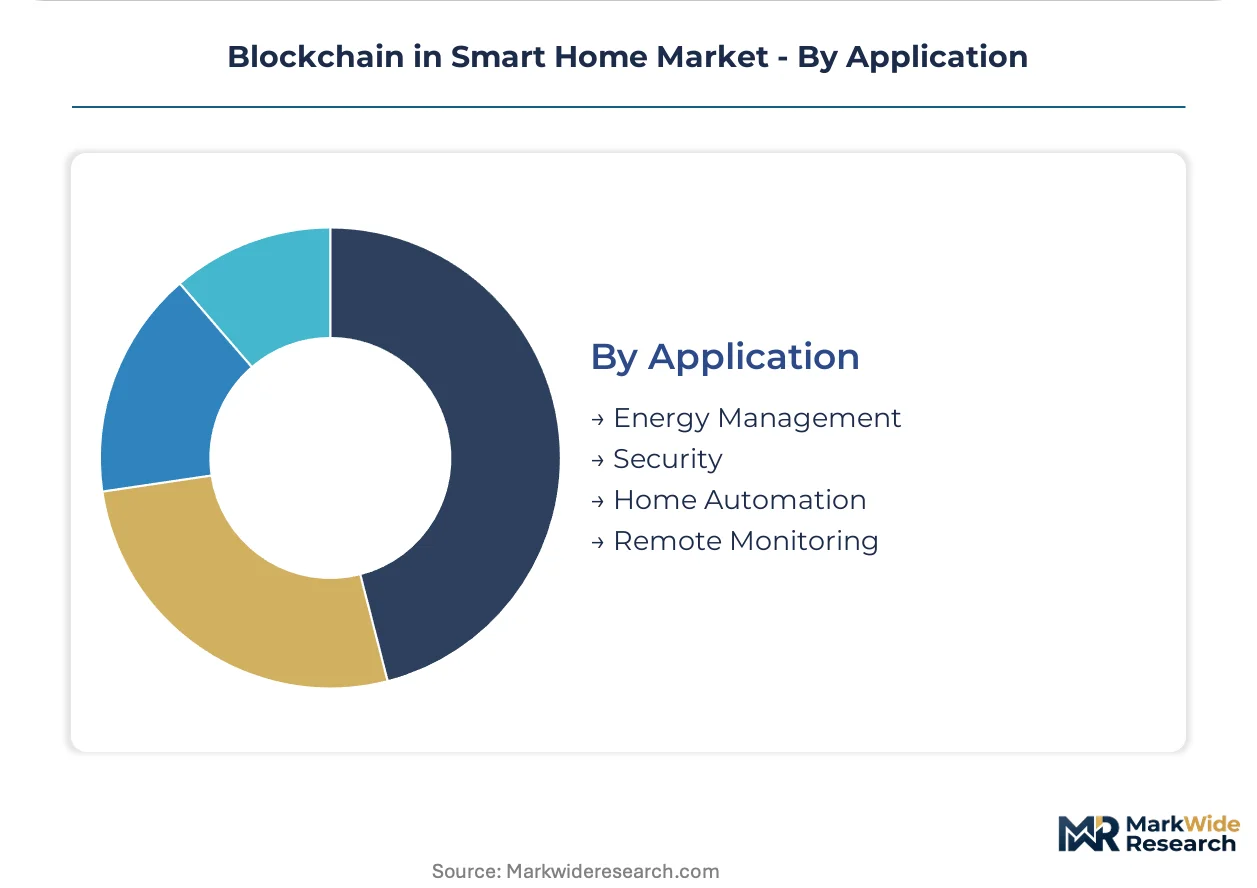
Application:
Geography shapes regulatory pressure intensity across functional use cases.
- Energy Management:Peer-to-peer electricity exchange demands automated settlement without utility intermediation. German grid codes and prosumer tariff structures favor blockchain-enabled automation.
- Security:Tamper-proof access logging satisfies insurance underwriting requirements in German and Swiss markets.
- Home Automation:Device-to-device transaction validation reduces cloud dependency.
- Remote Monitoring:Immutable audit trails support predictive maintenance and warranty claims.
Security commands the dominant specification priority; Energy Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German smart building component exports flow into Dutch and Swiss property technology installations, establishing a trade corridor that channels hardware and compliance protocols across Central European residential markets.
Germany
Smart building codes and energy efficiency mandates accelerate blockchain-enabled automation adoption. The EU AI Act and GDPR compliance requirements enforce decentralized identity verification standards. Berlin-Brandenburg clusters host property technology platforms deploying portfolio-scale credential management systems for multi-family housing.
Switzerland
Insurance underwriters pilot auditable device provenance requirements with policy discount incentives. Swissmedic-equivalent consumer protection frameworks align with ETSI cybersecurity standards for credential isolation. Zurich and Geneva financial centers channel capital into hardware-as-a-service subscription models for rental markets.
Netherlands
Multi-family rental operators demand rapid credential reissuance through centralized orchestration dashboards. GDPR data minimization principles steer specifications toward local verification architectures. Randstad urban corridors concentrate hardware-as-a-service deployment for tenant turnover-intensive housing stock.
United States
Broadband infrastructure anchors blockchain node distribution across residential households. FCC IoT cybersecurity labeling guidelines intersect with state-level privacy regulations. Comcast leverages its network footprint to extend edge-native consensus into North American thermostat and sensor deployments.
India
National smart city integration programs prioritize decentralized identity for municipal service access. TRAI digital infrastructure policies support residential blockchain layers aligning with broader urban digitization. Maharashtra and Karnataka technology corridors develop gateway-class hardware processing capabilities for sub-second finality.
Blockchain in Smart Home Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates around telecommunications infrastructure owners and edge-security architects. The vendor base stratifies into three tiers: network-anchored platforms with broadband distribution advantages, protocol-native specialists with directed acyclic graph implementations, and development services firms customizing implementations for property managers. Dominant competitive moves include strategic partnerships between hardware manufacturers and insurance underwriters, plus geographic expansion through municipal smart city integration programs.
Within the network-anchored tier, Comcast and Telstra exemplify channel control through broadband infrastructure leverage. Xage Security occupies a position among edge-native security architects extending tamper-resistant consensus to sensor networks. IOTA Foundation represents the protocol-specialist archetype with feeless distributed ledger implementations designed for resource-constrained IoT endpoints.
| Leading Market Players |
|---|
| Comcast |
| Telstra |
| OSIZ Technologies |
| Blockchain App Factory |
| Xage Security |
| Mobiloitte |
| Teksun |
| SoluLab |
| IOTA Foundation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Taiwanese cryptographic processor foundries compresses margin structures for smart lock OEMs while simultaneously accelerating price competition in gateway-class hardware tiers, forcing vendors to recalibrate component sourcing strategies toward second-source qualification.
Pricing Analysis
Current-generation directed acyclic graph protocol implementations command premium positioning against prior-generation proof-of-stake architectures, while next-generation hardware-anchored consensus remains pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates ETSI-certified secure element designs from baseline credential storage modules. Pricing pressure stems from silicon supply concentration as TSMC and Samsung foundry queues extend lead times for cryptographic processors. Property managers in German multi-family rentals exhibit lowest price sensitivity due to hardware-as-a-service subscription absorption, while individual homeowners in price-competitive markets drive economy-tier volume.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for smart home device manufacturers. Cryptographic processor fabrication concentrates in Taiwan and South Korea, with assembly and testing distributed across Vietnam and Mexico. Raw material dependencies span silicon wafers, secure element substrates, and rare-earth magnet components for sensor motorization. Single-source vulnerability in TSMC's advanced node capacity creates concentration risk for edge-native security architectures. Distribution runs through property technology platforms and telecommunications infrastructure owners rather than traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled residential automation represents high-growth disruption justified by the EU AI Act's mandatory risk classification for automated residential security systems, which forces compliance investment cycles across vendor tiers.
For Market Incumbents: Build certification moats around ETSI consumer IoT cybersecurity standards and GDPR data minimization compliance. Incumbent vendors should deepen backward integration into secure element design to offset embedded cryptography talent scarcity. Channel control through broadband infrastructure partnerships with Comcast and Telstra anchors node distribution advantages against protocol-native specialists. For New Entrants and Emerging Players: Mid-market commercial buildings in India smart city corridors represent the most penetrable entry point for directed acyclic graph protocol implementations. New entrants should target hardware-as-a-service subscription models in Dutch and German rental markets where tenant turnover demands rapid credential reissuance. Municipal service access integration offers a go-to-market angle aligned with national urban digitization programs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among property technology platforms deploying portfolio-scale credential management systems. Long-term viability in this market hinges on protocol interoperability resolution and insurance underwriting mandate adoption. Acquisition targets should display edge-native security architecture capabilities and municipal smart city integration track records. The signal to watch is German and Swiss carrier auditable device provenance requirement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Interoperability Partnership | Cross-ledger standardization reduces stranded asset risk for multi-vendor deployments. |
| Insurance Underwriter Collaboration | Policy discount programs accelerate tamper-proof access logging specification intensity. |
| Municipal Smart City Integration | Decentralized identity alignment with India urban digitization programs unlocks volume. |
| Hardware-as-a-Service Subscription Launch | Monthly fee structures concentrate value capture in German and Dutch rental markets. |
| Secure Element Design Acquisition | In-house cryptographic credential isolation satisfies ETSI mandates and reduces foundry dependency. |
Study Parameters
Initial hypotheses were tested against primary input from property technology platform executives, smart home device procurement officers, telecommunications infrastructure planners, and insurance underwriting specialists and refined through secondary validation against FCC IoT cybersecurity labeling guidelines, ETSI consumer device security standards, EU AI Act compliance documentation, and smart building code filings. Bottom-up demand modeling across homeowner, property manager, and real estate developer segments was triangulated with top-down market sizing from broadband infrastructure deployment disclosures and gateway-class hardware shipment data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology layer, end-user archetype, and application function, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from installed base penetration curves and replacement cycle acceleration factors. Industry-specific forecast inputs incorporated prosumer tariff reform timelines and smart city integration program commitment schedules.
Practitioners should monitor silicon foundry capacity allocation shifts and EU AI Act conformity assessment backlog expansion for early signals of supply constraint or compliance bottleneck. Forecasts reflect assumptions regarding edge computing maturation velocity and cross-protocol standardization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain Technology in Healthcare Market