
 Tube and Dressing Securement Products Market | 2026-2036
Tube and Dressing Securement Products Market Size, Share, and Industry Trends Forecast 2026-2036
Tube and Dressing Securement Products Market Analytics
Capital-intensity divergence between automated coating lines and manual assembly operations is reorganizing competitive tiers in tube and dressing securement. 3M Company leverages proprietary adhesive polymer science to sustain premium positioning across hospital systems. B. Braun Melsungen AG anchors European supply through vertically integrated silicone processing and sterile packaging infrastructure. Medline Industries competes on distribution density, controlling procurement channels across mid-tier acute care facilities in North America.
Tube and dressing securement products encompass adhesive-backed strips, retention caps, and mechanical fixation devices engineered from silicone, polyurethane, or foam substrates with peel strengths calibrated to 1-5 N/cm for skin-contact applications; these systems prevent dislodgement of catheters, drains, and wound dressings during patient movement and hygiene protocols. Silicone securement strips command expanding share in long-term care facilities where gentle removal reduces medical adhesive-related skin injuries. Polyurethane adhesive dressings dominate surgical management applications requiring moisture vapor transmission rates above 800 g/m² per 24 hours. Retention caps for IV securement represent the fastest-growing product configuration as outpatient infusion volumes rise.
FDA biocompatibility testing under ISO 10993 governs material approval pathways, while EMA's Medical Device Regulation enforces post-market surveillance for adhesive securement systems distributed in Europe. Japan's PMDA maintains distinct pharmaceutical affairs standards for antimicrobial-impregnated dressings, creating separate registration requirements for silicone-based catheter fixation products. Stakeholders must monitor evolving pressure-sensitive adhesive tariffs and sterilization validation protocols as supply chain regionalization accelerates.
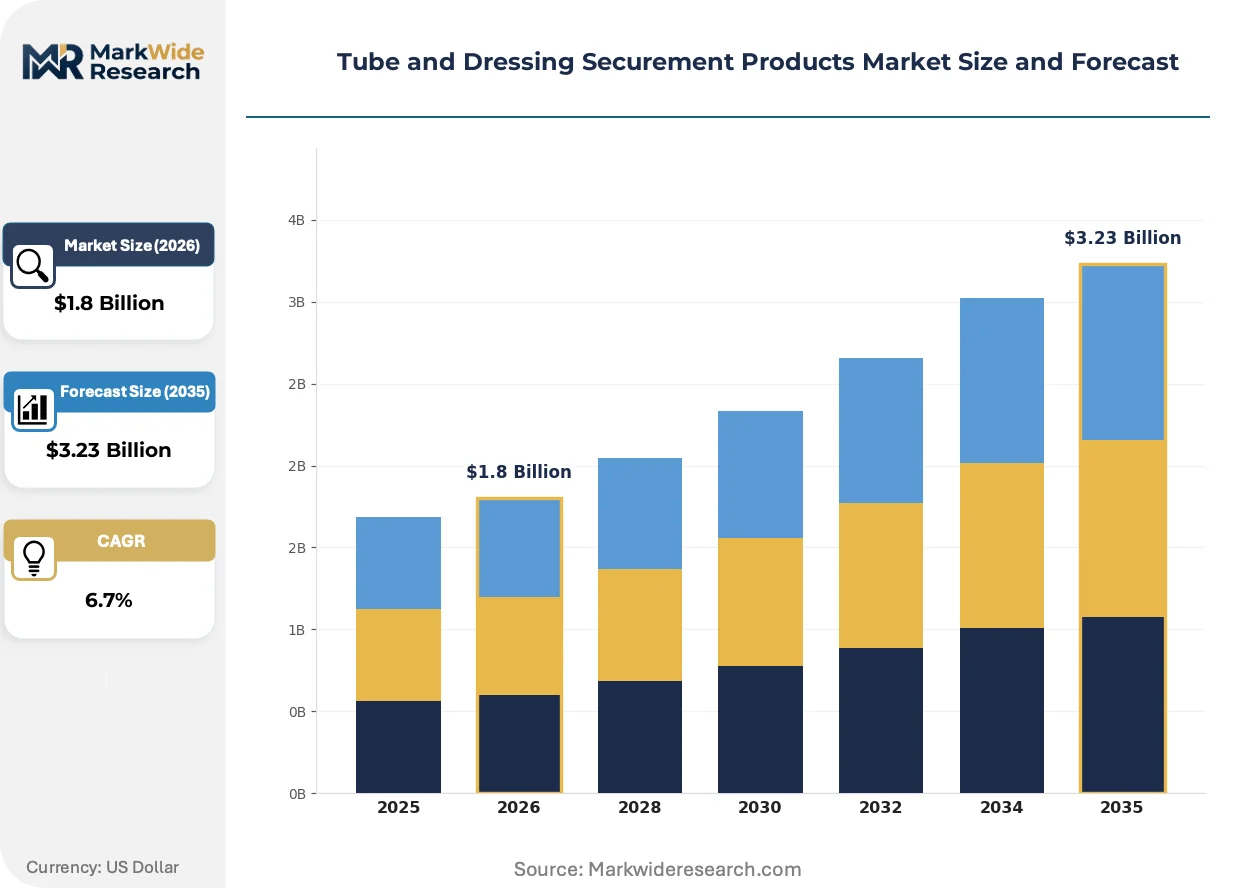
Market Dynamics
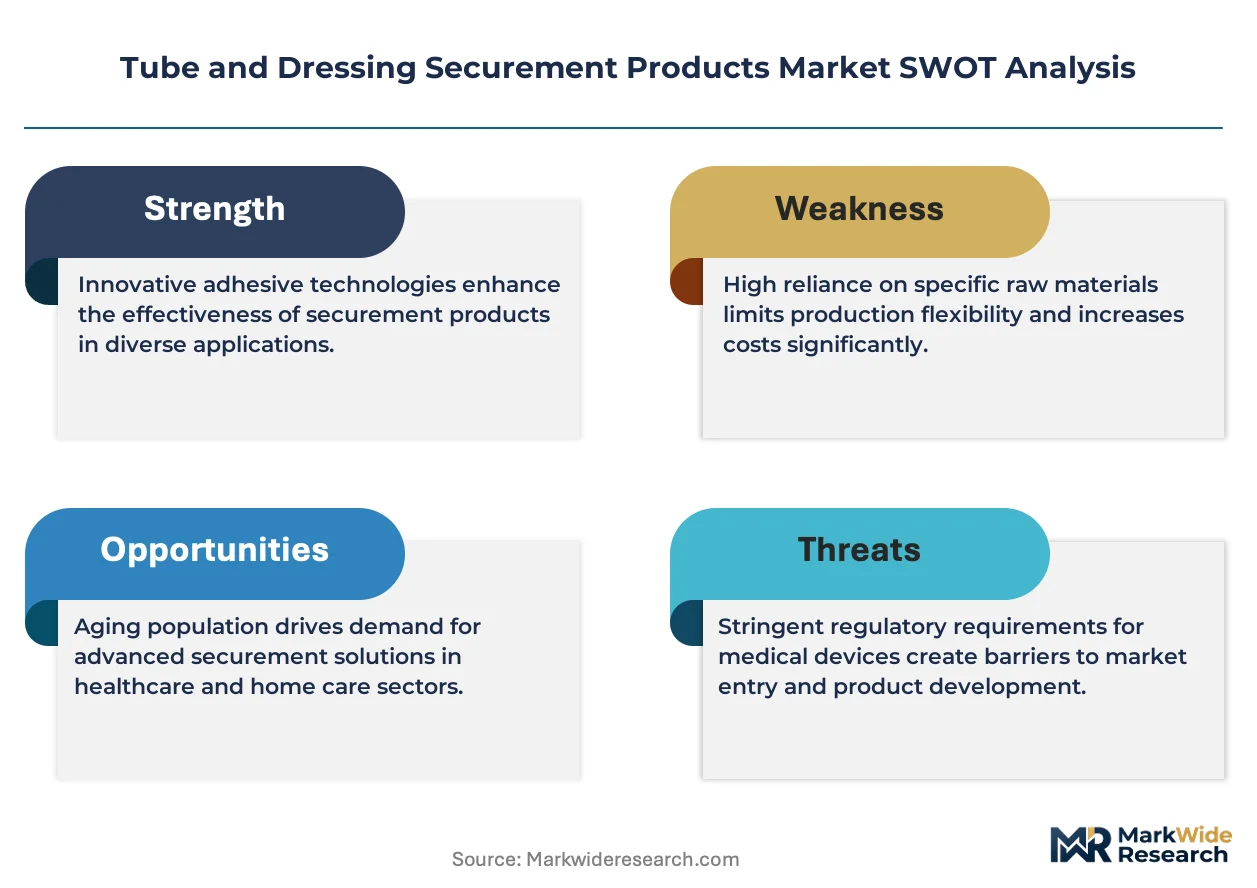
Silicone adhesive polymer science is fragmenting competitive tiers as automated coating lines concentrate production among capital-heavy manufacturers while manual assembly operations retreat to niche custom orders. This technological divergence is compressing mid-tier margins and forcing strategic repositioning across the value chain.
Growth Catalysts
- FDA ISO 10993 biocompatibility pathways:Tightened material certification requirements are accelerating hospital procurement of validated silicone-based securement devices that demonstrate proven skin integrity outcomes.
- Outpatient infusion volumes:Rising ambulatory chemotherapy and antibiotic administration is pulling demand for retention caps engineered for IV catheter stabilization during patient mobility.
- Germany's surgical infrastructure:High-volume catheterization procedures in acute care facilities sustain consumption of polyurethane adhesive dressings with calibrated moisture vapor transmission.
Market Restraints
- Medical-grade silicone feedstock volatility:Petrochemical input costs for platinum-cured silicone elastomers create margin pressure across substrate-dependent product lines.
- EMA MDR post-market surveillance:Expanded clinical evidence requirements for adhesive securement systems extend certification timelines and elevate regulatory compliance expenditures.
- Non-adhesive mechanical fixation:Subcutaneous anchor devices for long-term catheterization present substitution risk in intensive care applications where skin integrity is paramount.
Strategic Opportunities
- Japan's aging long-term care facilities:Underpenetrated demand for gentle-removal silicone strips aligns with PMDA pharmaceutical affairs standards for elderly skin protection protocols.
- Antimicrobial-impregnated dressing convergence:Silver-ion and chlorhexidine integration with silicone substrates opens premium positioning against standard adhesive platforms.
- Direct hospital system contracting:Bypassing traditional distribution layers captures procurement budgets from integrated delivery networks consolidating spend across multiple facilities.
Industry Challenges
- Polymer formulation chemistry expertise:Scarce talent capable of calibrating peel strength to 1-5 N/cm specifications while maintaining biocompatibility compliance constrains R&D throughput.
- Gamma and E-beam sterilization validation:Extended facility qualification timelines for adhesive securement products delay commercial launches and tie up capital in work-in-process inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube and Dressing Securement Products Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Securement Strips, Adhesive Dressings, Retention Caps, Securement Devices Material: Silicone, Foam, Polyurethane, Vinyl End User: Hospitals, Home Care, Clinics, Long-Term Care Facilities Application: Wound Care, IV Securement, Catheter Fixation, Surgical Management |
| Companies Covered | 3M Company, B. Braun Melsungen AG, Medline Industries, Teleflex Incorporated, ConvaTec Inc., Smith & Nephew, Becton, Dickinson & Company, Baxter International, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube and Dressing Securement Products Market Evolving Landscape
Active materials science and regulatory precision are compressing product lifecycles while elevating performance thresholds across tube and dressing securement categories. Manufacturers must now synchronize polymer innovation with evolving biocompatibility frameworks.
Silicone-based gentle adhesion is fragmenting the long-term care segment as nursing facilities prioritize medical adhesive-related skin injury prevention. Skilled nursing operators are replacing standard acrylic adhesives with soft silicone platforms at accelerating pace. This substitution is fragmenting legacy supply relationships and enabling direct manufacturer-to-facility contracting models.
EMA Medical Device Regulation enforcement is compressing competitive participation in European markets. Post-market clinical follow-up requirements for adhesive securement systems now demand systematic adverse event documentation. German and French hospital procurement teams are prioritizing suppliers with established MDR technical files and notified body certifications.
Hospital system consolidation is compressing vendor rosters as integrated delivery networks centralize catheter and wound care procurement. Mid-tier acute care facilities are losing independent purchasing authority to corporate supply chain offices. This concentration is most visible across United States health systems where GPO-affiliated hospitals now represent dominant volume allocation.
Tube and Dressing Securement Products Market Segmentation
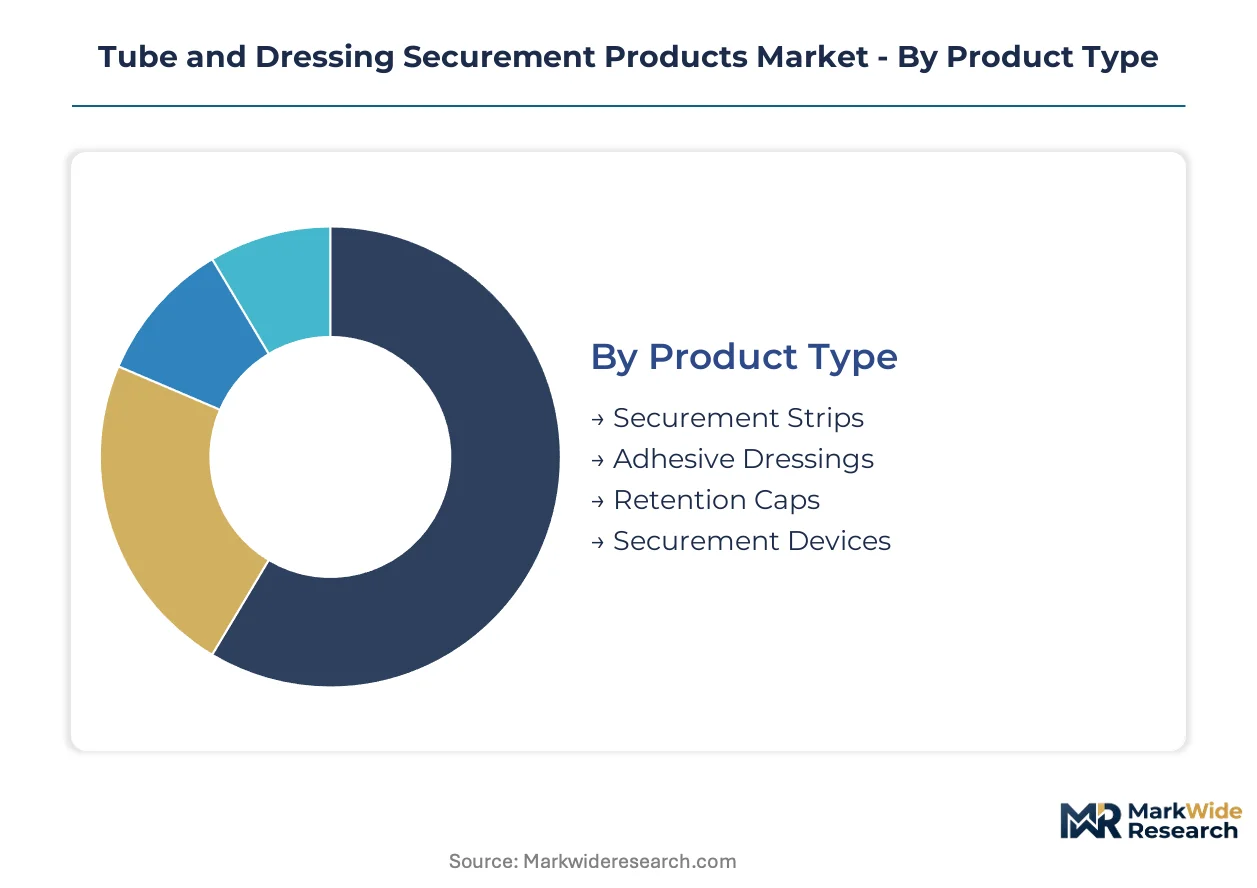
Tube and dressing securement products fragment across multiple technical and clinical dimensions. Procurement patterns diverge sharply between acute care systems prioritizing standardized fixation protocols and long-term facilities emphasizing skin integrity outcomes.
Product Type:
Retention caps face the most acute substitution pressure from integrated catheter systems with built-in stabilization features, while securement strips defend share through silicone adhesion chemistry that mechanical alternatives cannot replicate.
- Securement Strips:Silicone-backed adhesive strips engineered for 1-5 N/cm peel strength enable gentle removal protocols in elderly patient populations. Demand concentrates in United States long-term care facilities where medical adhesive-related skin injury prevention drives procurement specifications.
- Adhesive Dressings:Polyurethane and foam composite dressings with moisture vapor transmission rates exceeding 800 g/m² per 24 hours dominate surgical wound management. German hospital systems prioritize these platforms for post-operative catheter site protection where exudate management is critical.
- Retention Caps:Mechanical caps engineered for IV catheter hub stabilization during patient ambulation.
- Securement Devices:Integrated fixation systems combining adhesive substrates with mechanical locking mechanisms.
Adhesive dressings anchor the volume base while retention caps gain share at the steepest rate.
Material:
Cost tier stratification separates platinum-cured silicone elastomers commanding premium hospital contracts from vinyl substrates competing on price in high-volume disposable applications.
- Silicone:Soft silicone adhesives with low trauma removal characteristics command expanding share in Japan's geriatric care infrastructure where PMDA pharmaceutical affairs standards govern elderly skin protection protocols.
- Polyurethane:Moisture-permeable films with calibrated breathability specifications dominate surgical fixation applications requiring extended wear duration.
- Foam:Absorbent polyurethane foam substrates integrated with adhesive borders for exudate-heavy wound environments.
- Vinyl:Cost-optimized synthetic substrates for short-term catheter fixation in high-turnover clinical settings.
Polyurethane materials anchor the volume base while silicone substrates expand most quickly.
End User:
Customer type determines regulatory exposure intensity, with hospital procurement teams demanding ISO 10993 biocompatibility documentation that home care distributors rarely require.
- Hospitals:Integrated delivery networks centralize procurement of validated securement platforms across catheterization, wound care, and surgical service lines. United States health systems prioritize FDA-cleared silicone strips with established skin integrity outcome data.
- Long-Term Care Facilities:Skilled nursing operators in Germany and Japan drive demand for gentle-removal silicone platforms as medical adhesive-related skin injury prevention becomes a quality metric.
- Home Care:Patient-administered fixation products distributed through retail and durable medical equipment channels.
- Clinics:Outpatient infusion centers requiring rapid-application retention caps for high-throughput chemotherapy and antibiotic delivery.
Hospitals anchor the volume base while long-term care facilities gain share at the steepest rate.
Application:
Volume concentration in wound care contrasts with margin expansion in IV securement where outpatient chemotherapy growth sustains premium positioning.
- Wound Care:Post-operative and chronic wound dressing fixation represents the largest consumption category by unit volume across acute and post-acute settings.
- IV Securement:Retention caps and adhesive platforms for peripheral and central line stabilization. United States ambulatory infusion centers drive accelerating demand as chemotherapy and antibiotic administration shifts outpatient.
- Catheter Fixation:Urinary and drainage catheter securement systems requiring moisture-resistant adhesion for extended dwell times.
- Surgical Management:Sterile field-compatible fixation products for intraoperative and immediate post-operative application.
Wound care anchors the volume base while IV securement gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany demonstrate the lowest price elasticity, prioritizing EMA MDR-certified silicone platforms, while high-turnover clinical settings in emerging markets drive volume through vinyl-based alternatives. This demand stratification concentrates premium innovation in Western Europe and Japan while cost-optimized production gravitates toward scale-efficient manufacturing clusters.
United States
Integrated delivery networks centralize catheter and wound care procurement across multi-facility systems, with GPO-affiliated hospitals now controlling dominant volume allocation. FDA ISO 10993 biocompatibility pathways tighten material certification requirements, accelerating validated silicone-based securement device adoption. The Greater Boston and Minneapolis-St. Paul medical device corridors host concentrated R&D operations for next-generation adhesive polymer platforms.
Germany
High-volume catheterization procedures in acute care facilities sustain consumption of polyurethane adhesive dressings with calibrated moisture vapor transmission specifications. EMA Medical Device Regulation enforcement demands systematic post-market clinical follow-up documentation for adhesive securement systems. The B. Braun Melsungen AG headquarters in Melsungen anchors European silicone processing and sterile packaging infrastructure.
Japan
Aging long-term care facilities generate underpenetrated demand for gentle-removal silicone strips aligned with PMDA pharmaceutical affairs standards for elderly skin protection protocols. METI industrial policy supports domestic medical materials innovation through targeted R&D subsidies. The Kanto region surrounding Tokyo concentrates hospital system procurement offices and medical device distribution networks.
United Kingdom
NHS supply chain consolidation compresses vendor rosters for catheter fixation and wound dressing procurement across acute trusts. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel certification requirements for adhesive securement products. The Oxford-Cambridge-London golden triangle hosts specialized polymer formulation research facilities serving medical adhesive developers.
India
CDSCO medical device regulations are tightening import substitution requirements for catheter securement products distributed through government hospital procurement channels. The PLI scheme for pharmaceuticals and medical devices incentivizes domestic manufacturing capacity for silicone-based dressing platforms. Gujarat and Maharashtra industrial corridors attract contract manufacturing investments from multinational securement device suppliers.
Tube and Dressing Securement Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in tube and dressing securement manufacturing. Automated coating line investments concentrate production among capital-heavy manufacturers while manual assembly operations retreat to niche custom orders. Three strategic archetypes dominate: diversified healthcare conglomerates with proprietary adhesive polymer science, European vertically integrated silicone processors, and North American distribution-intensive suppliers. Competitive positioning depends on backward integration into medical-grade silicone feedstock and direct hospital system contracting capabilities.
Among diversified technology and healthcare conglomerates, 3M Company exemplifies premium-tier positioning through proprietary materials science capabilities. B. Braun Melsungen AG occupies a central position within European supply architecture through in-house silicone processing infrastructure. Medline Industries represents the distribution-density archetype, anchoring procurement channel control across mid-tier acute care facilities. These three entities illustrate the structural divergence between polymer innovation, vertical manufacturing control, and logistical scale as alternative competitive vectors.
| Leading Market Players |
|---|
| 3M Company |
| B. Braun Melsungen AG |
| Medline Industries |
| Teleflex Incorporated |
| ConvaTec Inc. |
| Smith & Nephew |
| Becton, Dickinson & Company |
| Baxter International |
| Merit Medical Systems |
| Others |
Value Network & Pricing Analysis
Platinum-cured silicone elastomers displacing vinyl substrates in long-term care procurement are simultaneously shifting supply geography toward Germany and Japan while compressing margins on legacy acrylic adhesive platforms. This material transition concentrates premium pricing power with manufacturers possessing in-house polymer formulation capabilities.
Pricing Analysis
After-sales service contracts for sterilization validation and technical training drive lifetime value for hospital system accounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification tier and peel strength calibration precision. Pricing pressure stems from medical-grade silicone feedstock volatility as petrochemical input costs fluctuate. Mid-tier acute care facilities exhibit highest price sensitivity while integrated delivery networks prioritize validated outcomes over unit cost.
Supply Chain Analysis
Germany and Japan anchor medical-grade silicone processing and sterile packaging infrastructure for premium securement platforms. The supply chain draws from platinum-cured silicone elastomers, polyurethane films with calibrated moisture vapor transmission, and gamma-sterilization equipment. Single-source vulnerability concentrates in specialized coating line operators with FDA-validated processes. Distribution runs through group purchasing organizations and integrated delivery network supply chain offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone adhesive polymer science is disrupting legacy acrylic platforms as FDA and EMA biocompatibility pathways tighten, creating asymmetric growth opportunities for validated manufacturers.
For Market Incumbents: Compound proprietary polymer formulation advantages by deepening backward integration into medical-grade silicone feedstock and expanding direct hospital system contracting capabilities. Defend against non-adhesive mechanical fixation substitutes by accelerating retention cap innovation for outpatient infusion volumes. Prioritize EMA MDR technical file completion to lock out mid-tier competitors from German and French procurement channels.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for silicone-based gentle adhesion platforms offer the most penetrable entry point into United States long-term care facilities. Target Japan's underpenetrated geriatric care infrastructure where PMDA pharmaceutical affairs standards favor soft silicone skin protection protocols. Pursue white-label manufacturing partnerships with established sterile packaging infrastructure rather than greenfield facility investment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors capital-heavy manufacturers with automated coating line investments and established regulatory certifications. Long-term viability over the next decade rests on backward integration depth and hospital system direct contracting relationships. Watch antimicrobial-impregnated dressing convergence with silver-ion and chlorhexidine integration as the signal for premium tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market entry for silicone-based securement platforms targeting hospital procurement specifications. |
| CE Marking Pathway under MDR | Unlocks German and French hospital system procurement channels requiring notified body certification. |
| Hospital System Partnership | Captures procurement budgets from integrated delivery networks consolidating spend across multiple facilities. |
| Backward Integration into Silicone Feedstock | Insulates margin pressure from platinum-cured elastomer petrochemical cost volatility. |
| Antimicrobial Dressing Convergence | Positions premium platforms against standard adhesives through silver-ion and chlorhexidine integration. |
Research Methodology
The analysis maps silicone securement strips, polyurethane adhesive dressings, retention caps, and integrated fixation devices, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists. Primary interviews with these stakeholders combined secondary validation from FDA 510(k) filings, EMA MDR technical file databases, hospital procurement contracts, and CMS Medicare utilization data. Bottom-up unit volume estimates and top-down market sizing underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material substrate, end-user facility category, and clinical application dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating surgical volume forecasts, outpatient infusion expansion patterns, and long-term care facility admission trends as key inputs.
Decision-makers should treat outputs as directional under stable regulatory certification timelines and silicone feedstock cost assumptions; material deviation would warrant model refresh. Specific risk factors include EMA MDR enforcement delays, gamma sterilization facility qualification bottlenecks, and substitution acceleration from subcutaneous anchor devices. Recalibration cycles align with material shifts in biocompatibility standards and hospital system consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market