
 Smart Crib Market | 2026-2036
Smart Crib Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Crib Market Outlook
Pediatric sleep technologist talent is bifurcating the competitive landscape, as hardware engineering expertise diverges from infant behavioral science credentials. Cradlewise leverages its Silicon Valley roots to anchor AI-driven cry detection algorithms, while SNOO sustains premium positioning through proprietary responsive swaddling mechanics. Delta Children competes on manufacturing scale, operating one of the largest juvenile furniture production footprints in North America.
A smart crib denotes an infant sleep enclosure integrating sensor arrays, microprocessors, and wireless communication modules to monitor respiration, motion, and ambient conditions, typically employing non-contact radar or capacitive sensing with sub-millimeter displacement resolution for safety-critical applications. IoT cribs lead product type segmentation by installed base, though sleep monitors capture the fastest growth trajectory as retrofit accessories for conventional cribs. Home automation integration concentrates margin pools, where voice control and mobile app connectivity command pricing premiums over standalone health monitoring configurations.
FCC Part 15 governs radiofrequency emissions from connected nursery devices in the US, while the EU Cyber Resilience Act imposes mandatory security update obligations for IoT crib firmware sold in Europe. China's NMPA and GB standards for electrical toy safety extend to smart cradle certification, creating multi-jurisdictional compliance burdens for cross-border suppliers. Stakeholders must weigh certification sequencing strategies against regional go-to-market timelines, as regulatory divergence between RF exposure limits and data localization mandates intensifies.
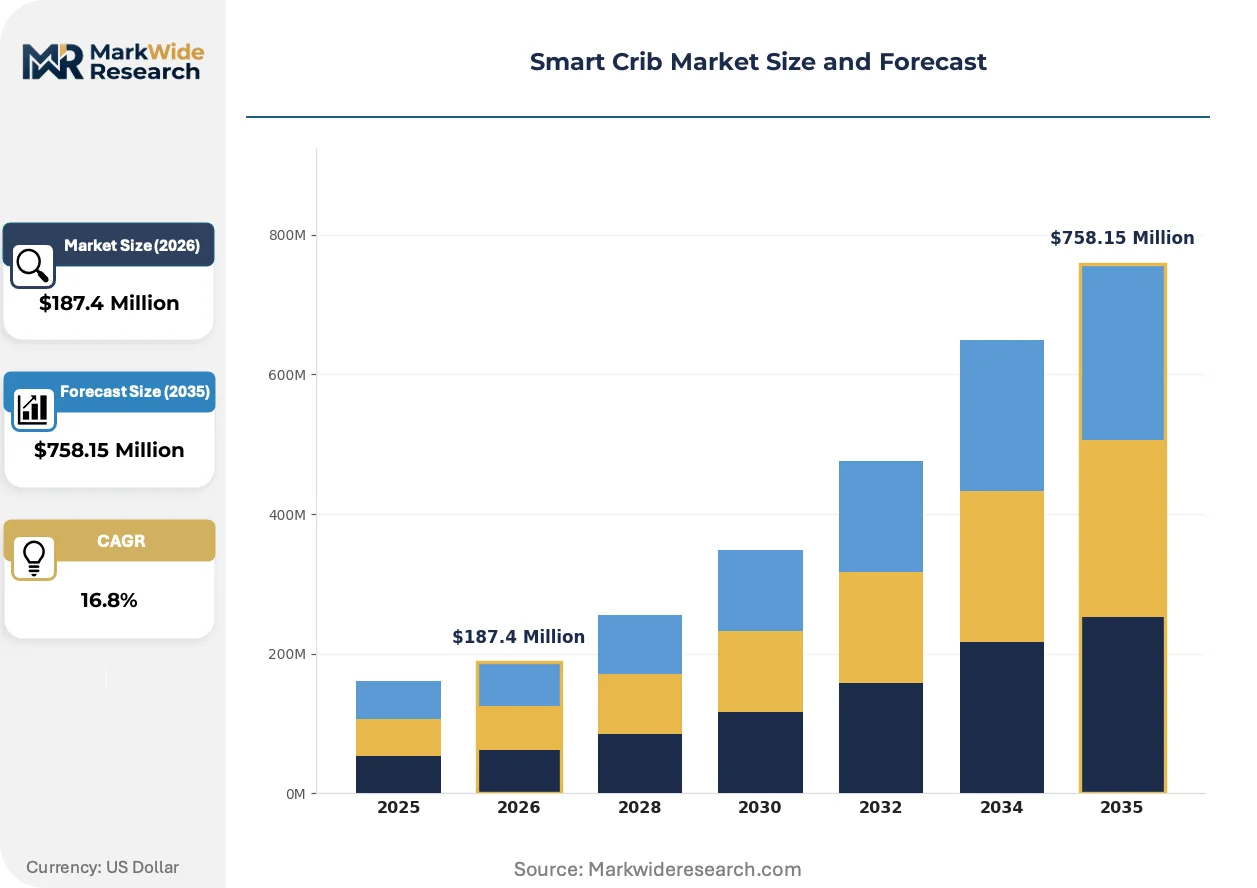
Market Dynamics
Dual-income household expansion in China and FCC Part 15 compliance complexity in the US are compressing product development cycles while fragmenting vendor certification strategies across three regulatory jurisdictions.
Growth Catalysts
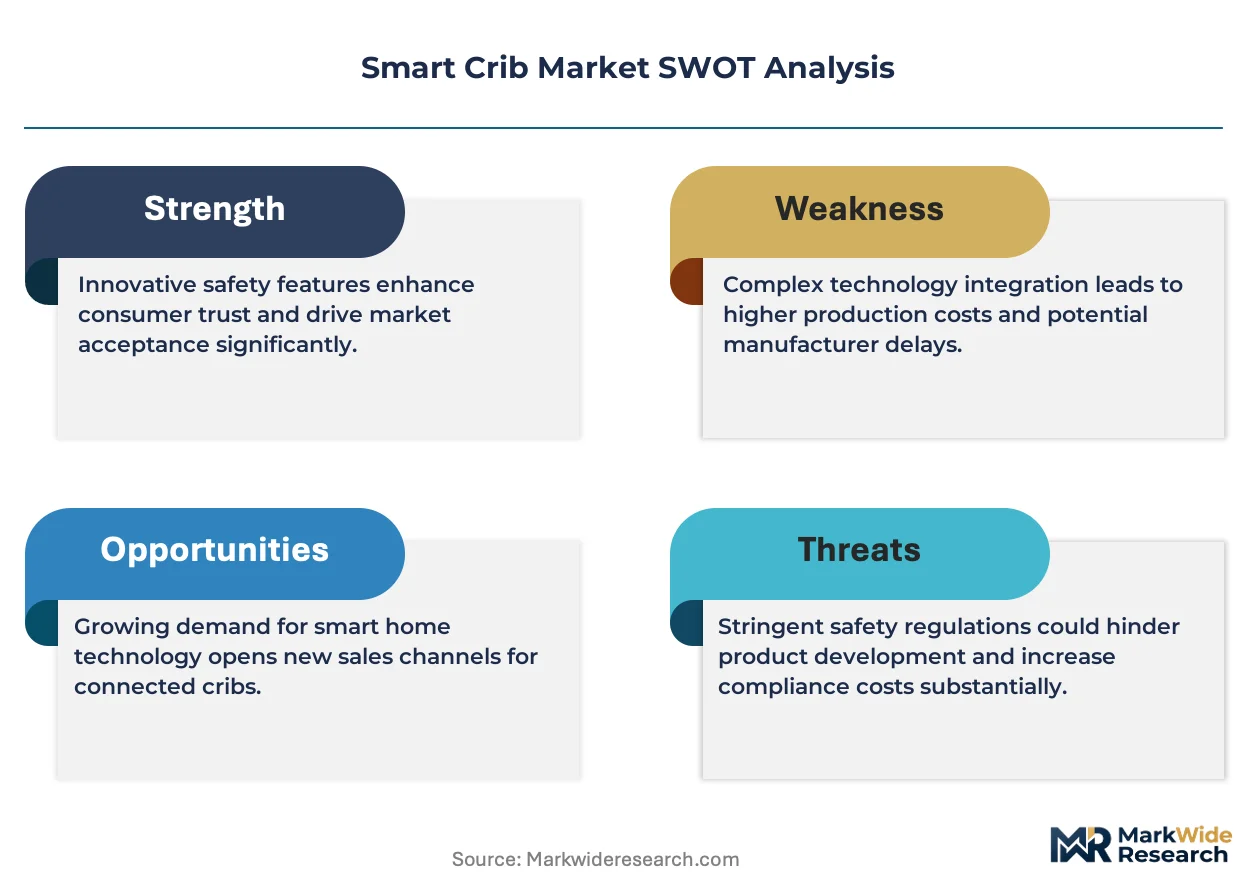
- EU Cyber Resilience Act:Mandatory firmware update obligations for IoT crib manufacturers selling in Europe create recurring revenue streams through subscription-based security maintenance services.
- Radar-based respiration sensing:Non-contact vital sign monitoring technology eliminates wearable attachment risks, accelerating hospital-grade safety adoption in residential nursery settings.
- Shanghai-Shenzhen corridor:Concentrated smart home ecosystem development in these Chinese manufacturing hubs reduces component procurement lead times for connected sleep hardware.
Market Restraints
- Semiconductor input volatility:Discrete radar sensor chip supply concentrates among three foundry operators, exposing hardware margins to wafer allocation disruptions.
- RF exposure threshold divergence:FCC Part 15 limits in the US, EU RED guidelines, and China's MIIT radio licensing create conflicting electromagnetic compliance testing requirements.
- Capacitive sensing substitution:Lower-cost pressure mat alternatives for motion detection threaten displacement of millimeter-wave radar in economy-tier product configurations.
Strategic Opportunities
- India's BIS certification pathway:Underpenetrated premium nursery hardware demand in Mumbai and Bangalore metro corridors offers first-mover positioning before domestic manufacturing scales.
- Voice control convergence:Integration of Amazon Alexa and Google Assistant protocols with sleep analytics platforms unlocks home automation hub positioning beyond standalone crib sales.
- Japan's METI energy efficiency incentives:Subsidized adoption of low-power wide-area network connectivity for IoT cribs reduces cellular data plan dependency in cost-sensitive segments.
Industry Challenges
- Pediatric sleep technologist scarcity:Hardware engineering talent pools in Shenzhen and Taipei lack infant behavioral science credentials, forcing cross-functional team assembly across three time zones.
- Multi-jurisdictional certification sequencing:NMPA GB standard testing in China, FCC Part 15 authorization in the US, and EU CE marking create 14-18 month hardware launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Crib Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IoT Cribs, Smart Cradles, Sleep Monitors, Baby Trackers Integration Level: Home Automation, Health Monitoring, Mobile App Connectivity, Voice Control End User: Parents, Caregivers, Hospitals, Daycares Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Direct Sales |
| Companies Covered | Newton Baby, Delta Children, Cradlewise, Mokee, Babyletto, Nestig, Stokke, Graco, SNOO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Crib Market Strategic Shifts
Sensor fusion architectures and edge computing migration are redefining competitive differentiation in connected nursery hardware, shifting value capture from device sales to predictive analytics subscriptions.
Millimeter-wave radar modules for contactless breathing monitoring is miniaturizing from 60GHz industrial footprints to compact 24GHz consumer-grade packages. Tier-one suppliers in Taiwan and South Korea are shipping these components to OEMs at volume scale. This compression is enabling integration into retrofit sleep monitor accessories rather than solely factory-built crib structures.
The EU Cyber Resilience Act imposes mandatory vulnerability disclosure timelines and end-of-life security support guarantees for IoT crib firmware distributed in European markets. Hardware vendors must maintain software engineering teams for 5-8 years post-shipment. Premium positioning segments absorb these compliance costs through subscription pricing, while economy tiers face margin compression.
Direct-to-consumer channel expansion is displacing traditional juvenile specialty retail distribution for smart crib purchases. Millennial and Gen-Z parents in Austin, Berlin, and Melbourne research sensor specifications through manufacturer apps before purchase. This behavior concentrates marketing spend on performance data transparency rather than retail floor placement.
Smart Crib Market Segmentation
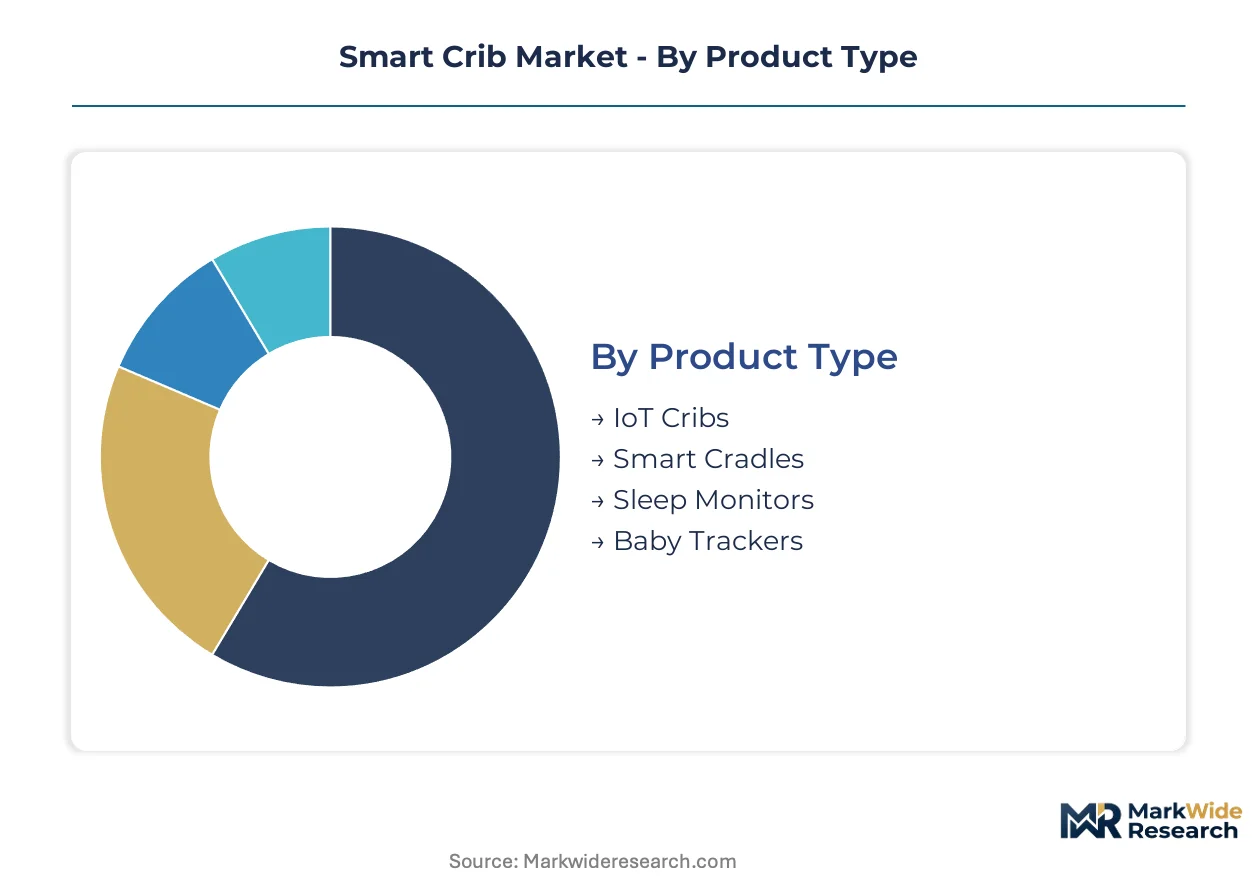
Smart crib segmentation reveals how hardware specifications, connectivity depth, and procurement channels fragment addressable demand across residential and institutional buyers. Manufacturers sequence R&D investment against margin pools that concentrate in subscription-integrated configurations rather than standalone sensor hardware.
Product Type:
Domestic assembly dominates IoT cribs and smart cradles for North American and European markets, while sleep monitors and baby trackers flow predominantly from Shenzhen and Taipei contract manufacturers serving export demand.
- IoT Cribs:Factory-integrated sensor arrays with radar-based respiration monitoring and mesh network connectivity ship as complete sleep enclosures. Demand clusters in Shanghai, Shenzhen, and Austin metro corridors where dual-income households prioritize connected nursery ecosystems.
- Sleep Monitors:Retrofit accessories employing 24GHz millimeter-wave radar or capacitive pressure sensing attach to conventional crib rails. These units expand most quickly in Europe under EU Cyber Resilience Act compliance timelines that favor modular upgrade paths over full crib replacement.
- Smart Cradles:Rocking-enabled enclosures with motorized motion response and ambient sound generation target premium residential segments in Japan and South Korea.
- Baby Trackers:Wearable or clip-on devices measuring temperature, position, and activity levels serve as entry-tier connectivity for price-sensitive first-time parents in India.
IoT cribs hold the largest share; momentum sits with sleep monitors.
Integration Level:
Cost tier stratification separates subscription-backed home automation configurations from one-time-purchase health monitoring setups, with voice control commanding intermediate pricing.
- Home Automation:Full ecosystem integration with Amazon Alexa, Google Assistant, and Apple HomeKit protocols enables crib status queries and routine automation through existing hub infrastructure. Adoption concentrates in Berlin, Melbourne, and Seattle where smart home penetration exceeds residential averages.
- Voice Control:Embedded microphone arrays with natural language processing allow hands-free operation during nighttime care routines. FCC Part 15 certification complexity in the US and EU RED testing in Europe extend development cycles for these RF-intensive configurations.
- Health Monitoring:Standalone vital sign dashboards without external connectivity target hospital procurement and privacy-conscious residential buyers in Germany and Switzerland.
- Mobile App Connectivity:Bluetooth-tethered smartphone interfaces deliver sleep analytics and alert routing without cloud dependency, dominating economy-tier positioning in China.
Home automation integration captures premium margin pools; mobile app connectivity dominates volume shipments.
End User:
Application maturity diverges sharply between institutional buyers demanding ISO 13485-adjacent documentation and residential consumers prioritizing installation simplicity.
- Parents:Millennial and Gen-Z residential buyers in premium urban markets drive specification transparency through manufacturer-direct research behavior. Direct-to-consumer channel expansion has displaced traditional juvenile specialty retail for this cohort.
- Hospitals:Neonatal intensive care units and pediatric wards require FDA 510(k) or equivalent national regulator clearance for clinical-grade respiration monitoring. Procurement runs through group purchasing organizations with multi-year service agreements.
- Caregivers:Professional home health aides and nanny services utilize employer-provisioned hardware with centralized fleet management dashboards.
- Daycares:Multi-crib facilities prioritize cost-scaled motion detection over individual respiration monitoring, creating demand for hub-and-spoke sensor architectures.
Parents represent the dominant addressable base; hospitals command highest per-unit pricing.
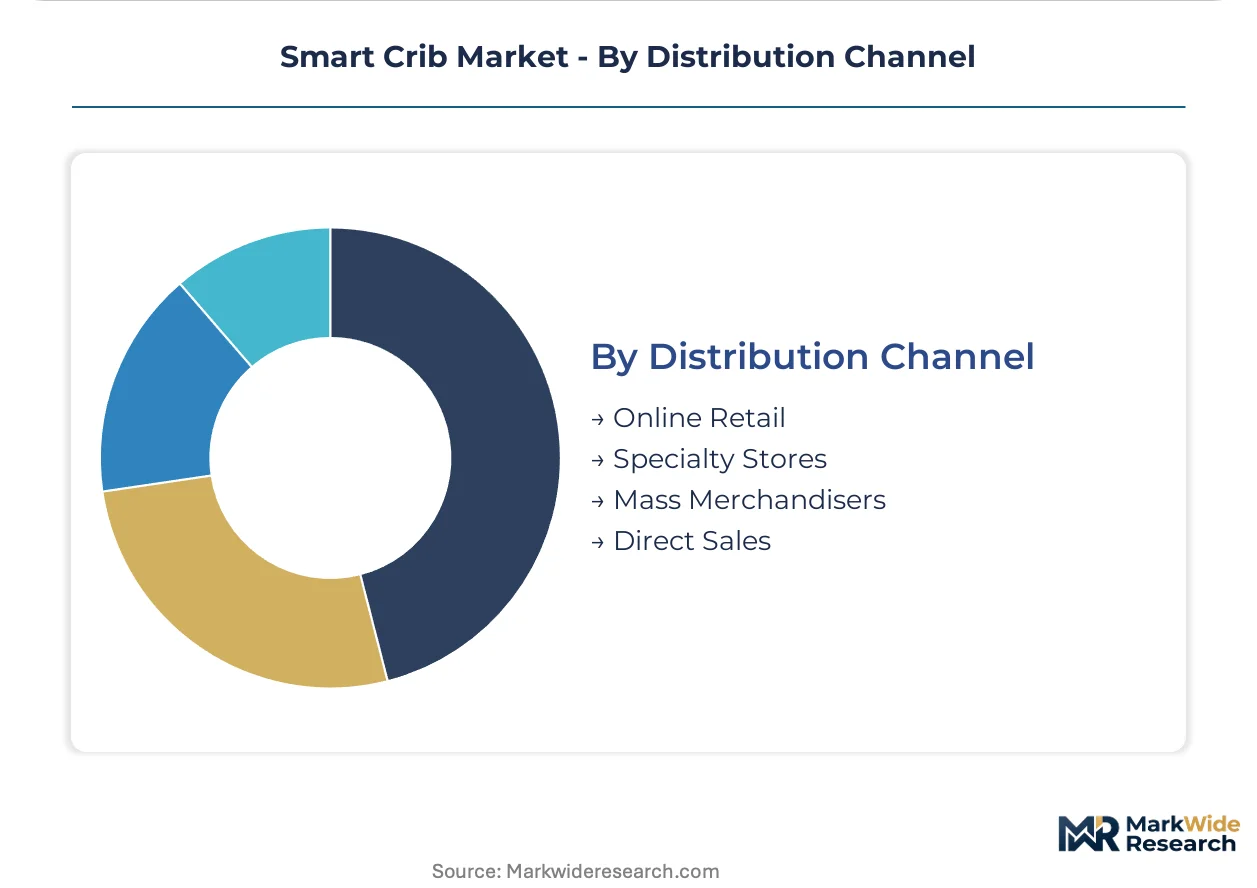
Distribution Channel:
Supply concentration in direct sales and online retail is compressing specialty store footprint, with mass merchandisers capturing economy-tier volume through private-label sourcing.
- Online Retail:Amazon, Tmall, and manufacturer-owned storefronts aggregate specification-comparison behavior from research-intensive buyers. This channel concentrates marketing spend on performance data transparency rather than retail floor placement.
- Direct Sales:Subscription-integrated hardware with multi-year security update obligations ships through owned channels to ensure service attachment. EU Cyber Resilience Act compliance costs absorb more cleanly through this route.
- Specialty Stores:Juvenile furniture boutiques and baby gear retailers retain relevance for tactile evaluation of rocking mechanics and material quality in Japan and France.
- Mass Merchandisers:Walmart, Target, and Carrefour shelf placement targets first-time parents with bundled accessory promotions and extended warranty attachments.
Online retail holds volume leadership; direct sales gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 compliance complexity in the United States anchors regulatory divergence across major demand centers, fragmenting certification timelines and compressing product development cycles for connected nursery hardware vendors.
United States
Millennial and Gen-Z parents in Austin, Seattle, and Brooklyn drive specification-transparent research behavior through manufacturer-direct channels. FCC Part 15 RF exposure guidelines impose electromagnetic testing burdens that extend hardware launch timelines. Silicon Valley engineering clusters concentrate AI-driven cry detection algorithm development for premium crib configurations.
China
Dual-income households in Shanghai and Shenzhen accelerate adoption of IoT-integrated sleep solutions with smart home penetration exceeding residential averages. NMPA GB standards for electrical toy safety extend certification requirements to smart cradle hardware. The Shanghai-Shenzhen manufacturing corridor reduces component procurement lead times for radar sensor modules.
Germany
Privacy-conscious residential buyers in Berlin and Munich prioritize health monitoring configurations without external cloud connectivity. EU Cyber Resilience Act mandatory firmware update obligations create recurring revenue opportunities through subscription security services. Bavarian industrial clusters supply precision motion control components for motorized rocking mechanisms.
Japan
Premium residential segments in Tokyo and Osaka demand rocking-enabled smart cradles with ambient sound generation. METI energy efficiency incentives subsidize low-power wide-area network connectivity adoption. Kanto region electronics manufacturers specialize in compact 24GHz millimeter-wave radar miniaturization for consumer-grade packages.
India
First-time parents in Mumbai and Bangalore metro corridors represent underpenetrated premium nursery hardware demand. BIS certification pathways offer first-mover positioning before domestic manufacturing scales. Karnataka's technology corridor hosts contract manufacturers assembling baby tracker entry-tier devices for price-sensitive segments.
Smart Crib Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with premium AI-driven positioning separating from manufacturing-scale and design-centric archetypes. Hardware engineering expertise diverges from infant behavioral science credentials, bifurcating talent acquisition strategies. Three archetypes dominate: Silicon Valley-rooted algorithm developers, North American juvenile furniture manufacturers with captive production footprints, and European design-forward nursery brands. Competitive moves concentrate on direct-to-consumer channel expansion and multi-jurisdictional certification sequencing.
Among the integrated leaders, Cradlewise and SNOO exemplify algorithm-driven premium positioning, while Delta Children represents manufacturing-scale supply security. Cradlewise anchors AI-native cry detection development, SNOO occupies responsive swaddling mechanics specialization, and Delta Children sits within North American production footprint dominance. These three illustrate how competitive differentiation fragments across software engineering depth, proprietary mechanical IP, and supply chain vertical control.
| Leading Market Players |
|---|
| Newton Baby |
| Delta Children |
| Cradlewise |
| Mokee |
| Babyletto |
| Nestig |
| Stokke |
| Graco |
| SNOO |
| Others |
Value Chain & Pricing Dynamics
FCC Part 15 certification requirements gate both supplier qualification and price differentiation simultaneously, as RF exposure testing burdens concentrate margin pools among vendors with capital reserves for electromagnetic compliance, while economy-tier manufacturers face exclusion from premium residential segments demanding hospital-grade safety documentation.
Pricing Analysis
Long-term offtake contracts dominate procurement for institutional buyers in neonatal intensive care units, while spot purchasing characterizes direct-to-consumer residential transactions. Three-tier pricing structure across premium, standard, and economy levels separates subscription-integrated home automation configurations from standalone health monitoring dashboards and mobile-app-tethered entry devices. Cost compression in economy tiers intensifies because capacitive pressure sensing substitutes threaten radar-based respiration monitoring displacement. First-time parents in India exhibit highest price sensitivity, whereas hospital procurement committees demonstrate least sensitivity due to multi-year service agreement structures.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for North American-bound finished goods. Radar sensor module production concentrates in Taiwan, South Korea, and Japan, while final assembly for domestic markets flows from Shenzhen and Taipei contract manufacturers. Component sourcing draws from discrete semiconductor foundries, millimeter-wave radar fabs, and precision motion control suppliers in Bavaria. Single-source vulnerability concentrates in 60GHz industrial radar chip supply among three foundry operators. Distribution runs through Amazon and Tmall for research-intensive millennial buyers, with direct sales channels gaining fastest share for subscription-backed security update obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart crib penetration remains in early-cycle expansion, with millennial and Gen-Z parent cohorts in premium urban corridors driving specification-transparent research behavior that rewards performance data disclosure over traditional retail placement.
For Market Incumbents: Secure algorithm engineering talent pools in Silicon Valley against poaching from AI-native entrants developing cry detection capabilities. Fortify manufacturing scale advantages through captive production footprint expansion in North America, insulating against tariff exposure on Shenzhen-sourced assemblies. Prioritize FCC Part 15 pre-certification investment to compress 14-18 month multi-jurisdictional launch timelines.
For New Entrants and Emerging Players: Anchor in India's underpenetrated Mumbai and Bangalore metro corridors before BIS certification pathways mature and domestic manufacturing scales. Target sleep monitor retrofit accessories for European residential buyers navigating EU Cyber Resilience Act compliance timelines favoring modular upgrade paths. Pursue voice control convergence with Amazon Alexa and Google Assistant protocols as primary go-to-market angle for home automation hub positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across subscription-integrated firmware maintenance services requiring 5-8 year software engineering team retention. Long-term viability over the coming decade rests on vendors capturing recurring revenue streams from security update obligations rather than transactional hardware margins. Acquisition target archetype: AI-native crib developers with proprietary cry detection algorithms and established direct-to-consumer channels. Signal to watch: BIS certification completion rates for entrants targeting Indian premium residential segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Certification Sequencing | FCC Part 15, EU CE marking, and NMPA GB standard alignment compresses 14-18 month hardware launch timelines for cross-border vendors. |
| Radar Sensor Module Miniaturization | 24GHz consumer-grade package development by Kanto region electronics manufacturers enables retrofit sleep monitor accessory expansion. |
| Subscription Security Service Attachment | EU Cyber Resilience Act mandatory firmware update obligations create recurring revenue absorption of compliance cost burdens. |
| Voice Control Protocol Integration | Amazon Alexa and Google Assistant ecosystem convergence unlocks home automation hub positioning beyond standalone crib sales. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned storefronts aggregate millennial and Gen-Z specification-comparison behavior displacing juvenile specialty retail. |
Study Parameters
Initial hypotheses were tested against primary input from pediatric sleep technologists, hardware engineering directors at connected nursery OEMs, procurement managers at hospital group purchasing organizations, and regulatory affairs leads specializing in FCC Part 15 and EU Cyber Resilience Act compliance, then refined against secondary validation from FDA 510(k) filings, NMPA GB standard documentation, EU CE marking databases, and smart home penetration surveys in Shanghai, Austin, and Berlin. Bottom-up unit economics modeling triangulated with top-down addressable market sizing across the projection horizon.
Variance decomposition across product type, integration level, end user, and distribution channel dimensions shaped analytical framework construction throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macro drivers including dual-income household expansion, smart home ecosystem penetration, and regulatory compliance timeline compression. Industry-specific inputs encompassed radar sensor module shipment data from Taiwan and South Korea foundries, voice control protocol adoption metrics, and subscription service attachment rates for firmware maintenance obligations.
Decision-makers should treat outputs as directional under assumptions of sustained millennial and Gen-Z parent cohort expansion in premium urban corridors and stable semiconductor wafer allocation for radar sensor chip production; material deviation in either would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Feeding Bottles Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Baby Pacifier Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Children Products Market
Baby Products
Baby Seat Liners Market
Baby Products
Home Care Packaging Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Baby Playpens Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Baby Swing Market
Baby Products
Puppy Teething Toys Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Netherlands Baby Care Products Market
Baby Products
North America Baby Bottle Market