
 Infant Care and Baby Care Equipment Market | 2026-2036
Infant Care and Baby Care Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Care and Baby Care Equipment Market Outlook
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for infant respiratory and monitoring equipment. Medtronic leverages its vertical integration in neonatal ventilation to sustain leadership across European hospital networks. Koninklijke Philips N.V. anchors its position through R&D intensity in connected baby monitoring ecosystems. Fisher & Paykel Healthcare differentiates via specialized humidification technology for infant care settings.
Infant care and baby care equipment encompasses devices, consumables, and furniture engineered for neonatal through preschool-age children, typically incorporating biocompatible plastics, medical-grade silicones, and organic textiles tested for phthalate and heavy-metal content. The category serves clinical neonatal intensive care units, home nurseries, and childcare facilities with functional parameters spanning respiratory support, physiological monitoring, mobility assistance, and safe sleep environments. Diapers and baby monitors command the largest revenue pools, with monitors recording the fastest structural expansion as Wi-Fi-enabled and biometric-tracking models displace audio-only units. Strollers and high chairs represent mature segments where margin concentration shifts toward lightweight aluminum-frame and sustainably sourced wood variants.
The FDA's 510(k) clearance pathway governs infant medical devices in the United States, while the EU AI Act imposes algorithmic transparency requirements on smart monitoring systems with automated alert functions. China's NMPA enforces GB standards for chemical migration in plastic feeding and care products, reshaping supplier qualification for brands accessing its domestic market. Stakeholders must track diverging regulatory timelines for software-enabled infant devices, as compliance lags in one jurisdiction will cascade into channel restrictions elsewhere.
Market Dynamics
Smart monitoring ecosystems are fragmenting competitive advantage in infant care, as hardware commoditization forces differentiation toward algorithmic reliability and data interoperability. CE marking under the EU Medical Device Regulation and FDA 510(k) clearance timelines now determine market access velocity more than manufacturing scale.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated alert functions in Wi-Fi-enabled monitors must now document decision logic, creating compliance barriers that favor established software-validated vendors over hardware-only entrants.
- Urban millennial parent clusters:Dense metropolitan nurseries in Shanghai, London, and New York drive concentrated demand for biometric-tracking monitors with subscription-based health analytics.
- Biocompatible silicone molding advances:Medical-grade liquid silicone rubber processing now enables integrated sensor embedding in feeding and respiratory products, collapsing assembly steps and failure modes.
Market Restraints
- Medical-grade silicone feedstock concentration:Three specialty chemical suppliers control 70% of implantable-grade silicone monomer, exposing infant device manufacturers to price volatility and allocation risk.
- GB standards chemical migration testing:China's NMPA enforcement of updated plastic feeding product standards extends supplier qualification timelines by 8-14 months for non-domestic brands.
- Audio-only monitor substitution:Basic sound-monitoring hardware faces accelerated replacement by smartphone-native apps, compressing margin pools in entry-tier segments.
Strategic Opportunities
- India's urban middle-class nursery expansion:BIS certification alignment for feeding and sleep products unlocks access to 15 million annual births in underpenetrated metro and tier-2 markets.
- Subscription-based predictive health analytics:Continuous biometric data from connected monitors enables recurring revenue models that decouple vendor economics from hardware replacement cycles.
- EU Green Deal sustainable materials procurement:Organic textile and FSC-certified wood variants in strollers and high chairs command 40-60% price premiums through institutional childcare channel mandates.
Industry Challenges
- FDA 510(k) software validation timelines:Algorithm updates in smart monitors trigger re-submission requirements that delay feature deployment by 9-18 months versus consumer electronics release cadences.
- ISO 13485 quality management system integration:Medical device-grade documentation and traceability requirements impose organizational capability gaps on traditional juvenile product manufacturers.
- Interoperability standard fragmentation:Proprietary data protocols across Philips, Owlet, and Nanit ecosystems prevent unified health record integration, frustrating pediatrician adoption and parent switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Care and Baby Care Equipment Market |
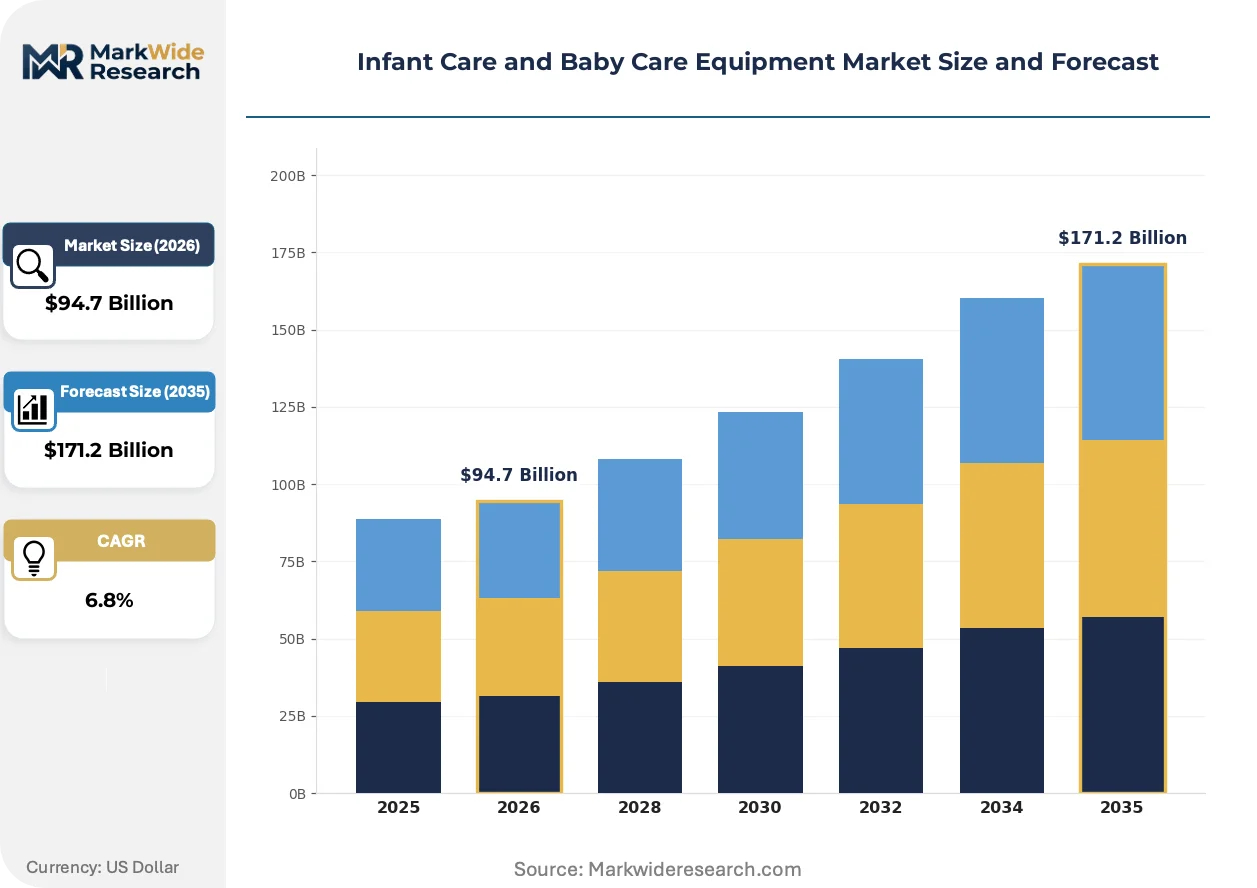
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $171.2 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Baby Monitors, Strollers, High Chairs Material: Cotton, Plastic, Wood, Metal Age Group: Newborn, Infant, Toddler, Preschooler Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Medtronic, Fisher & Paykel Healthcare, GE Healthcare, Natus Medical Incorporated, Cardinal Health, Drägerwerk AG & Co. KGaA, Masimo, Atom Medical Corporation, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Care and Baby Care Equipment Market Strategic Shifts
Sensor miniaturization and edge computing are redistributing value capture from hardware assembly toward firmware and cloud architecture. Regulatory software validation requirements now shape R&D resource allocation more than industrial design.
Biometric optical sensing in consumer-grade infant monitors is decomposing the traditional separation between wellness and medical-grade monitoring. Hospital NICU discharge planners now specify home monitoring systems with pulse oximetry and respiratory rate tracking. This capability migration compresses the addressable market for prescription-only pulse oximeters while expanding liability exposure for consumer brands.
REACH chemical restriction updates and RoHS substance bans are forcing reformulation of plasticizers and flame retardants in infant sleep products. European manufacturers face 12-18 month material requalification cycles for polyurethane foams and textile coatings. The stroller and carrier segments absorb disproportionate cost impact due to polymer weight minimization requirements conflicting with structural safety margins.
Direct-to-parent subscription models are displacing retail channel dominance for monitoring hardware. New parents in Germany and California increasingly purchase through branded ecommerce with integrated lactation consulting and pediatric telehealth. This shift concentrates customer acquisition spending on digital performance marketing while eroding traditional baby specialty store margins and inventory positions.
Infant Care and Baby Care Equipment Market Segmentation
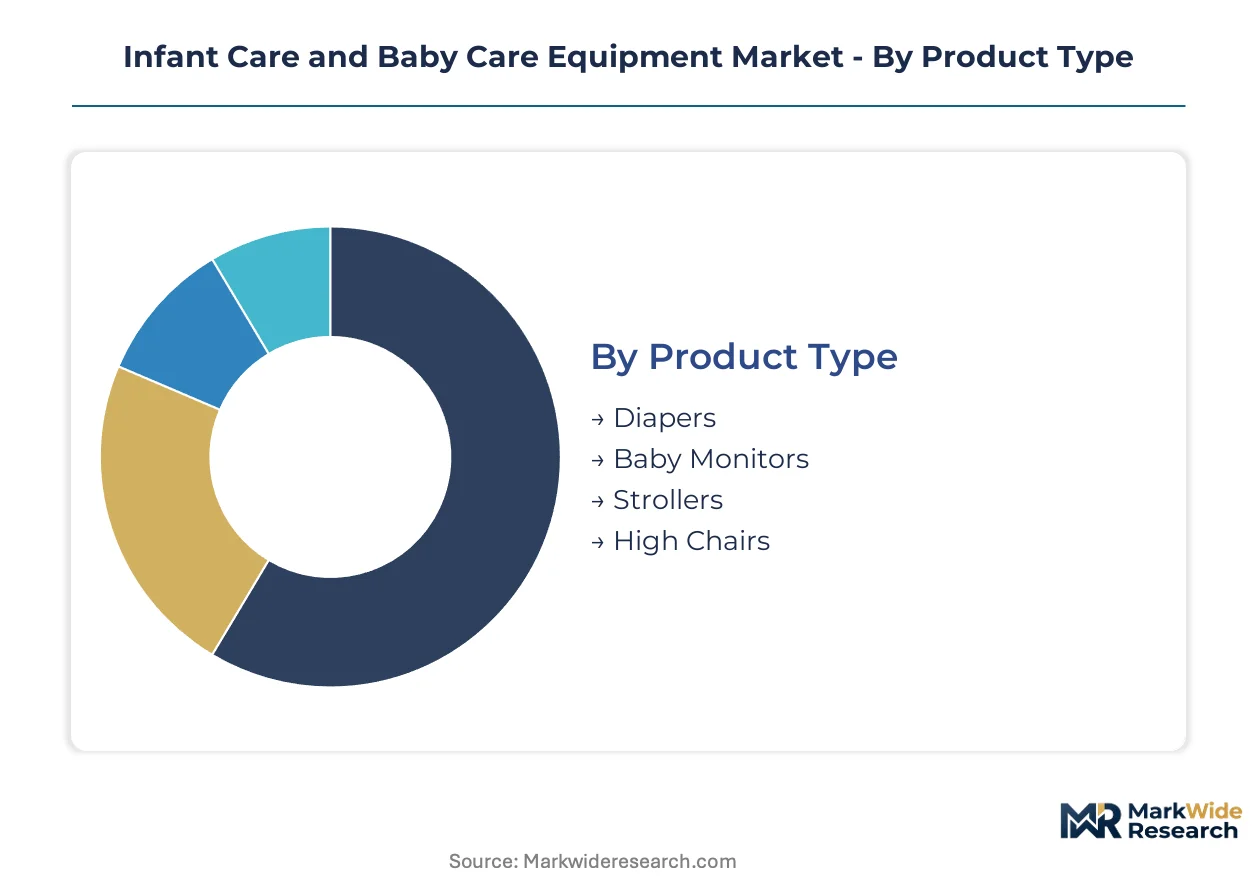
Infant care equipment segments fragment along clinical versus home-use boundaries, with regulatory intensity and parental digital behavior determining where margin pools concentrate. Material chemistry and distribution channel economics further stratify competitive positioning across newborn through preschool-age cohorts.
Product Type:
Margin pools concentrate in monitoring hardware where subscription attach rates and FDA 510(k) clearance create defensible pricing power, while consumables compete on manufacturing scale.
- Baby Monitors:Wi-Fi-enabled biometric units with pulse oximetry and respiratory rate tracking embed medical-grade optical sensors and edge computing firmware. Demand clusters in Shanghai, London, and New York metro nurseries where millennial parents pay premium subscription fees for predictive health analytics and pediatric telehealth integration.
- Diapers:Premium disposable and organic cloth variants incorporate superabsorbent polymers or GOTS-certified cotton with wetness indicators. China's domestic manufacturers capture volume leadership through scaled production of bamboo-fiber and aloe-infused premium lines for urban middle-class parents in Beijing and Shenzhen.
- Strollers:Lightweight aluminum-frame and carbon-fiber travel systems with reversible seating and all-terrain suspension. EU Green Deal procurement mandates drive sustainable material adoption in institutional childcare channels.
- High Chairs:Convertible wooden and plastic models with adjustable tray systems and fold-flat storage. REACH chemical restrictions force reformulation of polyurethane foams and textile coatings in European markets.
The dominant share belongs to Diapers, while Baby Monitors is closing the gap fastest.
Material:
Supply concentration and regulatory testing burden determine cost structures, with medical-grade feedstock availability constraining expansion in silicone-dependent segments.
- Plastic:Biocompatible polypropylene and liquid silicone rubber dominate feeding and respiratory products. FDA and NMPA GB standards enforcement extends supplier qualification timelines for phthalate-free formulations.
- Cotton:Organic and conventional textile grades for diapers, clothing, and sleep products. GOTS and OEKO-TEX certification requirements fragment supplier bases across Turkish and Indian spinning operations.
- Wood:FSC-certified birch and beech in strollers, high chairs, and nursery furniture. EU institutional procurement mandates command 40-60% price premiums for sustainably sourced variants.
- Metal:Aircraft-grade aluminum and stainless steel in stroller frames and hardware. Weight minimization requirements conflict with structural safety margins, absorbing disproportionate engineering cost.
Plastic commands the largest volume position, though Cotton is expanding most quickly on organic certification premiums.
Age Group:
Product lifecycles compress toward the newborn phase where clinical discharge protocols and first-time parent anxiety drive monitoring equipment purchases.
- Newborn:NICU discharge planning specifies home pulse oximetry and respiratory monitoring systems. Hospital network purchasing agreements favor vendors with FDA-cleared medical-grade devices.
- Infant:Feeding, sleep safety, and mobility equipment for 0-12 month cohorts. Biometric tracking demand peaks here as parents navigate SIDS risk mitigation and developmental milestone monitoring.
- Toddler:Transition products including convertible high chairs and lightweight strollers. Durability and multi-child reuse become primary purchase criteria.
- Preschooler:Hygiene and sleep products with extended size ranges. Price sensitivity increases as replacement cycles lengthen and brand loyalty weakens.
Newborn captures the highest per-capita equipment spend, while Toddler shows the steepest expansion trajectory on extended-use product innovation.
Distribution Channel:
Customer acquisition economics favor direct-to-parent digital models, though pharmacy and specialty retail retain clinical credibility for medical-adjacent devices.
- Online Retail:Branded ecommerce with integrated lactation consulting and subscription services. Performance marketing concentration erodes traditional baby specialty store margins in Germany and California.
- Specialty Stores:Physical showrooms with product demonstration and fitting services. Stroller and carrier segments depend on tactile evaluation for premium conversion.
- Supermarkets:Mass-market diaper and feeding product placement. Private label penetration concentrates here on price-competitive consumables.
- Pharmacies:Medical-grade monitors and feeding equipment with pharmacist consultation. FDA-cleared devices leverage clinical trust architecture for parent reassurance.
Online Retail holds the dominant position, while Pharmacies are gaining share fastest on medical-grade monitor distribution expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial parents in Shanghai, London, and New York metro clusters drive concentrated demand for biometric-tracking monitors with subscription-based health analytics. Urban nursery density and dual-income household penetration correlate directly with premium equipment adoption rates. Regulatory divergence across FDA, CE marking, and NMPA jurisdictions now determines market access velocity more than manufacturing scale.
United States
Hospital NICU discharge planners specify home pulse oximetry systems for post-acute monitoring. FDA 510(k) clearance timelines for algorithm-enabled monitors extend 9-18 months, delaying feature deployment versus consumer electronics cadences. Greater Boston and Pacific Northwest clusters concentrate telehealth-integrated subscription services for first-time parents.
China
Domestic manufacturers scale premium diaper and stroller production for urban middle-class parents in Beijing and Shenzhen. NMPA enforcement of GB standards for chemical migration extends supplier qualification timelines 8-14 months for non-domestic brands. Yangtze River Delta industrial zones dominate biocompatible silicone molding for feeding and respiratory products.
Germany
EU Green Deal procurement mandates command 40-60% price premiums for FSC-certified wood strollers in institutional childcare channels. ECHA REACH updates force 12-18 month material requalification cycles for polyurethane foams in sleep products. Bavaria-based fabricators lead lightweight aluminum-frame engineering for travel systems.
India
BIS certification alignment for feeding and sleep products unlocks access to 15 million annual births in underpenetrated metro and tier-2 markets. Maharashtra and Gujarat manufacturing corridors scale organic cotton diaper production for export to European markets. Bangalore and Hyderabad tech clusters incubate Wi-Fi-enabled monitor startups targeting domestic price sensitivity.
United Kingdom
London and Southeast England nurseries concentrate demand for connected monitoring ecosystems with pediatric telehealth integration. CE marking under EU MDR governs medical-grade respiratory equipment despite post-Brexit regulatory divergence discussions. Midlands manufacturing bases specialize in textile coating reformulation for REACH-compliant sleep products.
Infant Care and Baby Care Equipment Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with neonatal care divisions and specialized respiratory equipment fabricators. The vendor base stratifies across three tiers: hospital-grade device manufacturers with FDA-cleared portfolios, consumer-facing monitor specialists with subscription revenue models, and scaled consumables producers competing on manufacturing yield. Dominant competitive moves include backward integration into medical-grade silicone feedstock and algorithmic reliability investments for automated alert functions.
Within the diversified medical technology tier, Medtronic, Koninklijke Philips N.V., and GE Healthcare exemplify scale-driven positioning. Medtronic leverages its neonatal ventilation portfolio across European hospital networks. Philips anchors its presence through R&D intensity in connected baby monitoring ecosystems. GE Healthcare occupies a position bridging clinical NICU equipment and home-use monitoring transitions. Fisher & Paykel Healthcare represents the specialized respiratory equipment archetype with differentiated humidification technology for infant care settings.
| Leading Market Players |
|---|
| Medtronic |
| Fisher & Paykel Healthcare |
| GE Healthcare |
| Natus Medical Incorporated |
| Cardinal Health |
| Drägerwerk AG & Co. KGaA |
| Masimo |
| Atom Medical Corporation |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for medical-grade silicone feedstock lock in supply access and price visibility for infant device manufacturers, insulating them from spot-market volatility while binding working capital to three specialty chemical suppliers concentrated in Germany and Japan.
Pricing Analysis
Cost-plus contracts with silicone monomer indexation dominate procurement for respiratory and feeding equipment manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical-grade monitors from Wi-Fi-enabled wellness devices and audio-only legacy units. Price differentiation rests on certification tier and subscription attach rates, with entry-tier hardware facing cost compression from smartphone-native app substitution. Hospital procurement committees show lowest price sensitivity; mass-market parents through supermarket channels exhibit highest.
Supply Chain Analysis
China and Germany anchor biocompatible silicone molding and precision aluminum fabrication for infant care equipment. Yangtze River Delta facilities supply liquid silicone rubber components for feeding products; Bavarian fabricators produce lightweight stroller frames. Raw material dependencies include implantable-grade silicone monomer, aircraft-grade aluminum, and GOTS-certified organic cotton. Single-source vulnerability concentrates in the three specialty chemical suppliers controlling medical-grade silicone feedstock. Distribution runs through direct-to-parent branded ecommerce, hospital procurement networks, and pharmacy channels with clinical consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as proprietary data protocols from Owlet, Nanit, and Philips prevent unified health record integration, creating interoperability arbitrage for ecosystem orchestrators.
For Market Incumbents: Fortify algorithmic reliability investments and backward integration into medical-grade silicone feedstock to defend against hardware commoditization. FDA 510(k) software validation timelines create defensive moats against consumer electronics release cadences. Prioritize ISO 13485 quality management system integration to maintain hospital network purchasing agreements. For New Entrants and Emerging Players: Pediatric telehealth integration gaps in existing monitor ecosystems offer white-space entry. India's underpenetrated metro and tier-2 markets present the most penetrable geography with BIS certification alignment as the regulatory unlock. Pursue direct-to-parent subscription models with integrated lactation consulting to bypass retail channel margin erosion. For Investors and Strategic Acquirers: Algorithm-validated software specialists with FDA-cleared portfolios represent the priority acquisition archetype. Long-term viability favors vendors decoupling economics from hardware replacement cycles through recurring revenue models. Monitor EU AI Act algorithmic transparency enforcement as the signal for compliance-barrier intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks hospital network access across European neonatal intensive care units. |
| Software Companion Development | Subscription-based predictive health analytics decouples vendor economics from hardware cycles. |
| Backward Integration | In-house production of medical-grade silicone components mitigates feedstock allocation risk. |
| Hospital System Partnership | NICU discharge planning agreements specify home monitoring systems for post-acute care. |
| Sustainability Repositioning | FSC-certified wood and organic textile variants command institutional childcare procurement premiums. |
Study Parameters
Operator-level perspectives from neonatal intensive care unit directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EMA CE marking databases, NMPA GB standard registrations, and hospital procurement contract disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across regulatory timeline scenarios and raw material price volatility assumptions. Segmentation dimensions modeled include product type, material chemistry, age cohort, and distribution channel across the analysis window. CAGRs derived from historical trajectory analysis and adoption curve modeling. Industry-specific inputs incorporated NICU discharge protocol evolution and millennial parent digital behavior clustering.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA jurisdictions; material policy shifts would require re-modeling. Specific risks include EU AI Act enforcement intensity, REACH chemical restriction updates, and medical-grade silicone supply allocation disruptions. Recalibration cycles align with material shifts in regulatory timelines and interoperability standard developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Kids Training Pant Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Italy Baby Care Products Market
Baby Products
Baby Bottle Holder Market
Baby Products
Maternity Products Market
Baby Products
Home Care Packaging Market
Baby Products
Smart Pacifier Market
Baby Products
North America Baby Bottle Market
Baby Products
Netherlands Baby Care Products Market
Baby Products
Baby Swing Market
Baby Products
Baby Tableware Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Global Baby Car Seats Market
Baby Products
Postpartum Products Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Durable Juvenile Products Market