
 Baby Cradles Market | 2026-2036
Baby Cradles Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Cradles Market Insights
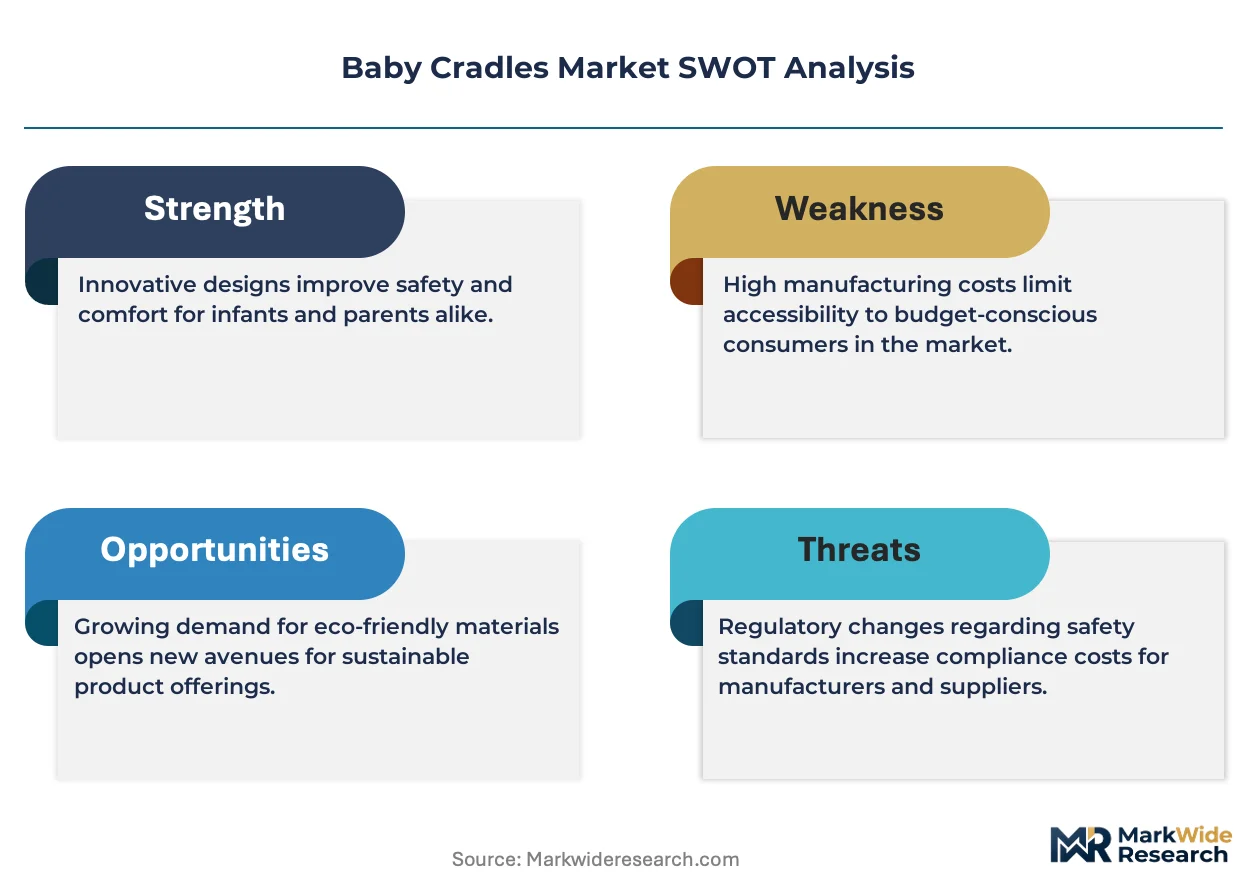
The gap between premium and commodity baby cradles is expanding along material sourcing, safety certification depth, and integrated technology. Delta Children's Products Corp. leverages large-scale manufacturing to anchor volume-tier distribution across mass retail channels. Million Dollar Baby Co. differentiates through solid-wood construction and Greenguard Gold certification. Silver Cross sustains heritage positioning in the luxury nursery segment through handcrafted frames and limited distribution.
A baby cradle is a suspended or rocked sleeping enclosure for infants, typically constructed with a rigid frame of hardwood, engineered wood, or metal tubing and a fabric or mesh sleeping surface, designed to provide gentle motion that soothes newborns. Wooden cradles dominate margin pools due to parental preference for natural materials and heirloom durability, while portable cradles lead volume growth as urban families prioritize space efficiency and travel compatibility. Bassinets compete closely with cradles in the zero-to-four-month sleep category, pressuring cradle manufacturers to emphasize longer usable lifespans and convertible designs.
The US Consumer Product Safety Commission enforces stringent stability and entrapment standards that elevate compliance costs for new entrants, while the EU's REACH and F-Gas Regulation restrict chemical treatments and volatile compounds in cradle finishes and adhesives. ASTM International and ISO 8124 provide voluntary but market-essential benchmarks that large retailers require for shelf placement. Stakeholders must monitor evolving flammability testing protocols and emerging state-level extended producer responsibility laws that could reshape material recovery obligations.
Market Dynamics
Millennial parents are forcing a bifurcation in cradle design between heirloom-grade solid wood and sensor-embedded smart sleep systems, pressuring mid-market manufacturers to choose sides or absorb dual development costs.
Growth Catalysts
- EU Green Deal material mandates:REACH and F-Gas Regulation restrictions on volatile compounds are accelerating certified wood sourcing and water-based finish adoption among European manufacturers seeking retail shelf access.
- Urban density patterns:Space-constrained apartments in New York, London, and Tokyo are concentrating demand for collapsible and wall-mounted cradle formats with sub-4-square-meter footprints.
- Smart nursery integration:Bluetooth-enabled motion sensors and breathing monitors are pulling technology-forward parents toward cradles that sync with smartphone ecosystems.
Market Restraints
- Baltic birch plywood supply concentration:Estonian and Latvian mills supply over 60 percent of premium cradle-grade plywood, exposing manufacturers to shipping rate volatility and energy cost spikes.
- ASTM F2194 stability testing costs:Third-party certification for US market entry requires 18-24 month validation cycles that consume 8-12 percent of initial product development budgets.
- Bassinet substitution pressure:Zero-to-four-month sleep solutions with faster assembly and lower price points are compressing cradle purchase windows in mass retail channels.
Strategic Opportunities
- Extended producer responsibility laws:California and Washington state mattress recycling mandates are creating first-mover advantage for cradle-to-cradle material recovery programs.
- Telehealth pediatric partnerships:Integration with remote infant monitoring platforms opens subscription revenue streams beyond hardware sales.
- Convertible furniture convergence:Cradle-to-toddler-bed transformation kits address parental resistance to 6-month usable lifespans.
Industry Challenges
- ISO 8124-1 mechanical testing backlog:Accredited laboratories in Asia-Pacific report 14-week queue times for small-batch prototype validation.
- Finishing technician scarcity:Water-based lacquer application requires humidity-controlled spray booths and specialized training that furniture apprenticeships rarely cover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Cradles Market |
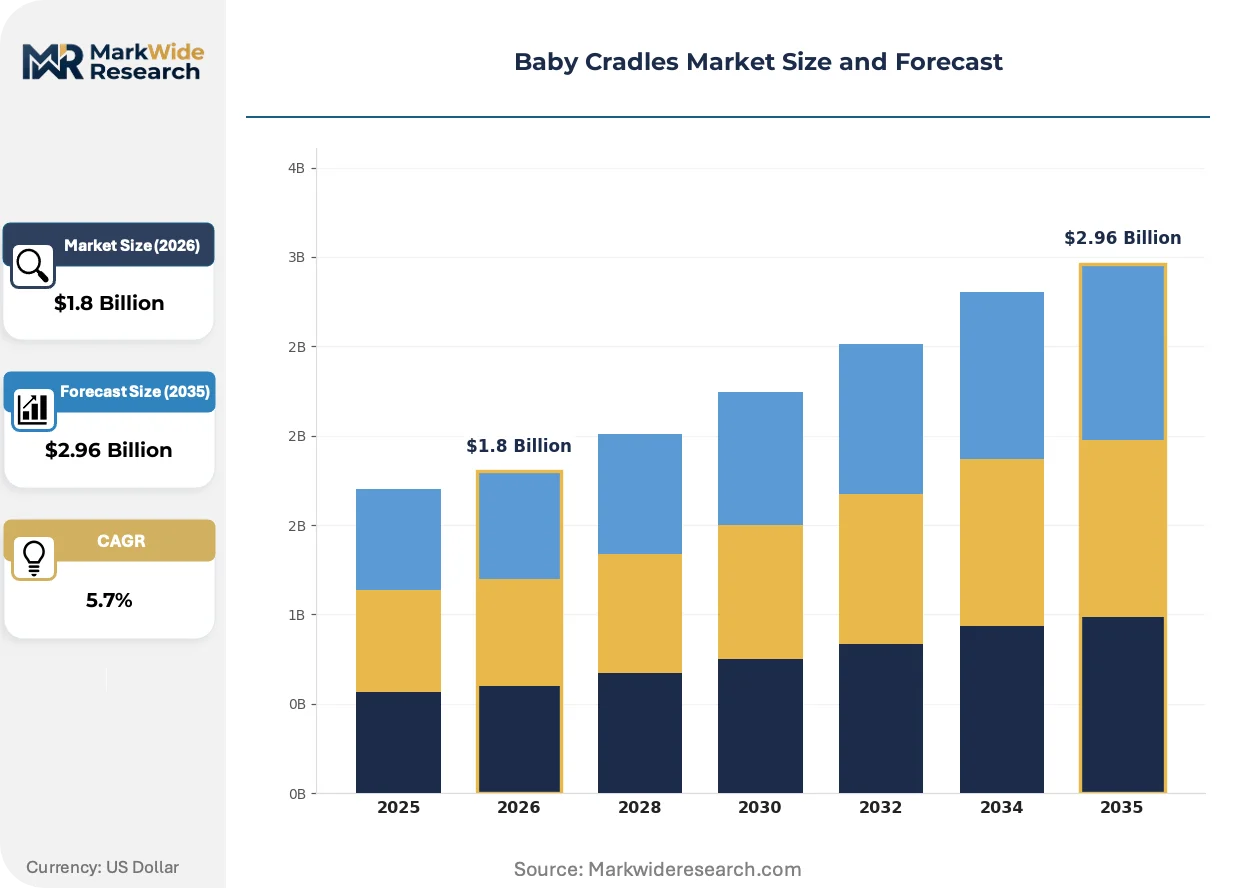
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Cradles, Portable Cradles, Rocking Cradles, Bassinets Material: Wood, Metal, Fabric, Plastic End User: Parents, Hospitals, Childcare Centers, Retailers Design Features: Foldable, Adjustable Height, Mosquito Net, Eco-Friendly |
| Companies Covered | Delta Children's Products Corp., Storkcraft, Graco Children's Products Inc., Million Dollar Baby Co., Dream On Me, Inc., Sorelle Furniture, Goodbaby International Holdings Ltd., Natart Juvenile, Inc., Silver Cross, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Cradles Market Trends and Innovations
Connected sleep hardware and circular material flows are converging to redefine cradle value propositions, while regulatory fragmentation across major economies forces parallel compliance architectures.
Sensor-embedded rocking mechanisms are automating the gentle motion patterns previously requiring manual intervention. High-income dual-earner households in Seoul and San Francisco are adopting these units at rates exceeding 40 percent of premium segment purchases. This automation is compressing the addressable market for traditional mechanical swing cradles and shifting R&D budgets toward firmware and app development.
REACH Annex XVII restrictions on formaldehyde-releasing agents in wood adhesives are forcing reformulation of engineered wood substrates. German and French manufacturers have absorbed 12-18 month recertification timelines to maintain CE marking validity. Solid-wood specialists are capturing margin premiums by marketing adhesive-free joinery as compliance-proof alternatives.
Millennial parents are treating nursery furniture as circular assets rather than disposable consumables. Resale platforms and peer-to-peer rental networks in Brooklyn and East London are displacing traditional big-box purchase cycles for second and third children. This behavioral pivot is most visible among households with above-median incomes and below-replacement fertility intentions.
Baby Cradles Market Segmentation
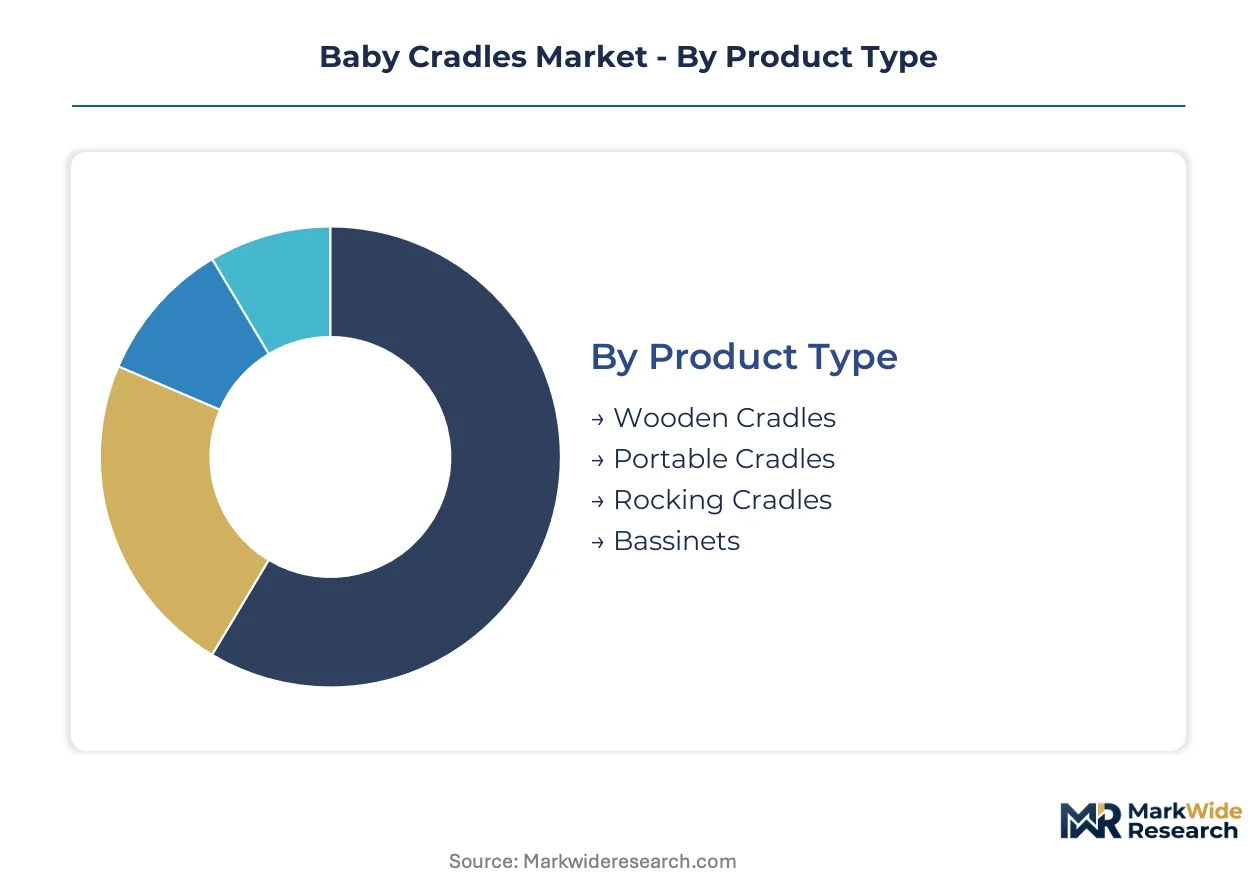
Parents choose cradles through layered trade-offs between material safety, spatial constraints, and usage duration. Each segmentation dimension captures a distinct decision node that manufacturers must optimize to capture purchase intent.
Product Type:
Space constraints and mobility needs drive the initial product selection for urban households.
- Wooden Cradles:Constructed from solid hardwood or engineered wood substrates with natural oil or water-based finishes. Demand concentrates in German and French households where REACH Annex XVII compliance on formaldehyde-releasing agents elevates preference for certified solid-wood construction over engineered alternatives.
- Portable Cradles:Lightweight aluminum or composite frames with collapsible mechanisms under 6 kilograms. Brooklyn and East London parents with below-replacement fertility intentions favor these for peer-to-peer rental network compatibility and resale platform liquidity.
- Rocking Cradles:Mechanical or automated swinging bases with arc motion between 15-30 degrees. Seoul and San Francisco dual-earner households above median income show strongest adoption for sensor-embedded variants.
- Bassinets:Compact sleep enclosures with faster assembly and sub-100-dollar entry pricing. Mass retail channels in the United States push these for zero-to-four-month sleep solutions, compressing traditional cradle purchase windows.
Volume sits with Wooden Cradles; growth tilts toward Portable Cradles.
Material:
Regulatory chemistry restrictions and heirloom durability expectations shape material sourcing strategies.
- Wood:Baltic birch plywood from Estonian and Latvian mills supplies over 60 percent of premium cradle-grade demand. Solid-wood specialists capture margin premiums by marketing adhesive-free joinery as REACH-proof alternatives.
- Metal:Aluminum tubing and powder-coated steel frames dominate portable and travel-oriented formats. Tokyo apartment dwellers prioritize sub-4-square-meter footprints that metal construction enables.
- Fabric:Breathable mesh and organic cotton sleeping surfaces with Oeko-Tex Standard 100 certification. Millennial parents seeking non-toxic nursery environments drive specification intensity here.
- Plastic:Injection-molded polypropylene frames for mass-market price positioning. Commodity tier manufacturers absorb dual development costs as EU Green Deal mandates force water-based finish adoption.
Margin concentrates in Wood; volume expansion tracks Metal.
End User:
Procurement authority and usage intensity diverge sharply across buyer types.
- Parents:Primary decision-makers with preference bifurcation between heirloom-grade solid wood and smart sleep systems. Millennial cohorts treat nursery furniture as circular assets, displacing big-box purchase cycles for second and third children.
- Hospitals:Institutional buyers requiring ISO 8124-1 mechanical validation and 18-24 month certification cycles. Third-party stability testing consumes 8-12 percent of product development budgets for US market entry.
- Childcare Centers:Volume purchasers prioritizing durability and multi-infant rotation capacity. ASTM F2194 compliance costs elevate barriers for new entrants serving this channel.
- Retailers:Channel gatekeepers demanding Greenguard Gold certification and CE marking validity for shelf placement. Extended producer responsibility laws in California and Washington reshape their material recovery obligations.
Revenue depth sits with Parents; contract stability favors Hospitals.
Design Features:
Functional specifications determine addressable market width and price realization.
- Foldable:Hinge mechanisms enabling sub-60-second collapse for storage and transport. Wall-mounted variants with sub-4-square-meter footprints gain traction in London and Tokyo urban density patterns.
- Adjustable Height:Telescoping legs or modular base systems accommodating parent bed alignment. Postpartum recovery ergonomics drive specification in premium segments.
- Mosquito Net:Integrated mesh canopies with zippered access panels. Tropical and subtropical geographies with vector-borne disease concerns sustain demand concentration.
- Eco-Friendly:Cradle-to-cradle material recovery programs and FSC-certified wood sourcing. EU Green Deal material mandates accelerate adoption among European manufacturers seeking retail shelf access.
Specification density peaks with Adjustable Height; sustainability premiums attach to Eco-Friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York Metro anchors cradle demand concentration through premium childcare infrastructure and high birth-rate urban clusters. Millennial parents in Brooklyn and Manhattan drive specification for collapsible formats and smart nursery integration.
United States
Urban density patterns in New York, Los Angeles, and Chicago concentrate demand for sub-4-square-meter cradle footprints. The US Consumer Product Safety Commission enforces stringent ASTM F2194 stability standards that elevate compliance costs. Seattle and San Francisco dual-earner households above median income show strongest adoption of sensor-embedded rocking variants.
Germany
REACH Annex XVII restrictions on formaldehyde-releasing agents in wood adhesives accelerate certified solid-wood sourcing. Berlin and Hamburg parents exhibit pronounced preference for heirloom-grade construction with Greenguard Gold certification. Munich manufacturers absorb 12-18 month recertification timelines to maintain CE marking validity.
China
Guangdong and Zhejiang provinces host the dominant manufacturing clusters for metal tubing and injection-molded frame components. GB standards and SAMR oversight shape domestic safety protocols while export-oriented producers navigate dual compliance architectures. Shenzhen technology integrators supply Bluetooth-enabled motion sensors for premium export lines.
United Kingdom
East London peer-to-peer rental networks displace traditional purchase cycles for second and third children. The UK's adoption of EU REACH-equivalent chemical restrictions post-Brexit maintains alignment with continental material standards. Manchester and Birmingham retail channels emphasize cradle-to-toddler-bed convertible designs.
South Korea
Seoul Capital Area dual-earner households exceed 40 percent adoption of automated rocking mechanisms. MFDS pediatric safety guidelines and K-Baby certification programs govern domestic market entry. Busan-Ulsan manufacturing corridors supply precision-machined hardware for sensor-embedded premium segments.
Baby Cradles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sourcing depth, safety certification intensity, and integrated technology levels. The vendor base organizes into three functional tiers: scale-driven mass retailers, solid-wood heritage specialists, and technology-integrated smart nursery providers. Dominant competitive moves include portfolio diversification into convertible furniture formats and strategic partnerships with telehealth pediatric platforms.
Within the heritage solid-wood tier, Million Dollar Baby Co. and Natart Juvenile, Inc. exemplify adhesive-free joinery positioning as REACH-proof alternatives. Delta Children's Products Corp. anchors the scale-driven commodity segment through large-scale manufacturing and mass retail channel penetration. Silver Cross occupies a position in the luxury nursery segment through handcrafted frame construction and limited distribution strategies.
| Leading Market Players |
|---|
| Delta Children's Products Corp. |
| Storkcraft |
| Graco Children's Products Inc. |
| Million Dollar Baby Co. |
| Dream On Me, Inc. |
| Sorelle Furniture |
| Goodbaby International Holdings Ltd. |
| Natart Juvenile, Inc. |
| Silver Cross |
| Others |
Pricing and Supply Chain Analysis
Baltic birch plywood from Estonian and Latvian mills feeds through three distinct pricing tiers as it transforms from raw material to finished cradle. Water-based lacquer application costs and ASTM F2194 certification expenses accumulate downstream, compressing margins for mid-market manufacturers while solid-wood specialists capture premiums through adhesive-free positioning.
Pricing Analysis
Value-based pricing anchors on sleep safety outcomes and heirloom durability expectations rather than input costs alone. Three-tier pricing structure across premium, standard, and economy levels separates Greenguard Gold-certified solid-wood construction from REACH-compliant engineered alternatives and commodity plastic formats. Price differentiation rests on certification depth and smart sensor integration, with dual-earner households in Seoul and San Francisco showing lowest price sensitivity for automated rocking variants. Pricing pressure stems from bassinet substitution in mass retail channels, where sub-hundred-dollar entry points compress traditional cradle purchase windows.
Supply Chain Analysis
CE marking and ASTM F2194 qualification gating creates 18-24 month validation cycles that filter supplier participation. Manufacturing concentrates in China for metal tubing and injection-molded components, Estonia and Latvia for premium plywood, and Germany for precision-finished solid wood. Raw material dependencies include Baltic birch plywood, aluminum tubing, and Oeko-Tex certified fabrics. Single-source vulnerability runs through Estonian and Latvian mill concentration for premium cradle-grade plywood. Distribution runs through mass retail chains, specialty nursery boutiques, and direct-to-consumer platforms with telehealth integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance scale and smart technology integration, with REACH recertification costs and ASTM validation timelines forcing sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: Extend convertible furniture portfolios to capture cradle-to-toddler-bed transformation demand and offset compressed six-month usable lifespans. Anchor supply security through backward integration into Baltic birch sourcing or captive water-based finish application capacity. Bassinet substitution in mass retail channels demands defensive positioning through smart nursery ecosystem partnerships that subscription revenue can sustain. For New Entrants and Emerging Players: Extended producer responsibility laws in California and Washington open a window for cradle-to-cradle material recovery programs that incumbent logistics networks have not optimized. Target wall-mounted and sub-4-square-meter collapsible formats for Brooklyn and East London rental network compatibility. Go-to-market through peer-to-peer resale platform integration rather than traditional retail shelf placement. For Investors and Strategic Acquirers: 12-18 month REACH recertification timelines among German and French manufacturers is the leading indicator that solid-wood specialists with adhesive-free joinery will command acquisition premiums. Long-term viability favors vertically integrated producers with captive certification capabilities and telehealth pediatric platform relationships. Watch for ISO 8124-1 laboratory queue times exceeding 14 weeks as signal of validation bottleneck creating distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Bluetooth-enabled motion monitoring captures Seoul and San Francisco dual-earner households above median income. |
| Convertible Furniture Development | Cradle-to-toddler-bed kits address parental resistance to short usable lifespans in Brooklyn rental networks. |
| Material Recovery Program | California and Washington extended producer responsibility laws create first-mover advantage for circular business models. |
| Telehealth Platform Partnership | Remote infant monitoring integration opens subscription revenue streams beyond hardware sales in pediatric care networks. |
| REACH-Compliant Sourcing | Certified solid-wood and water-based finish adoption secures CE marking validity for European retail shelf access. |
Research Methodology
Document review covered customs trade records, ASTM and ISO certification databases, and EU regulatory filings, complemented by interviews with nursery furniture procurement managers at mass retail chains, solid-wood manufacturing specialists in Germany and France, and telehealth pediatric platform engineers. Primary fieldwork included discussions with water-based finish application technicians and Baltic birch plywood sourcing directors. Secondary validation drew from CPSC enforcement actions, REACH Annex XVII amendment tracking, and peer-to-peer rental network transaction data. Bottom-up product-level modeling and top-down category sizing were triangulated against channel inventory estimates.
Historical shipment patterns were cross-referenced against panel input from manufacturing executives and retail category buyers to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product type, material substrate, end-user procurement authority, and design feature specification intensity. CAGRs were derived from regression analysis of birth rate trajectories, urban density patterns, and premium childcare infrastructure investment. Industry-specific inputs incorporated smart nursery technology adoption curves and extended producer responsibility law implementation timelines.
The model assumes a particular technology adoption path for sensor-embedded rocking mechanisms; alternative pathways for manual mechanical cradles would alter the outlook for traditional manufacturing clusters. Forecasts reflect assumptions about REACH enforcement consistency and ASTM F2194 stability testing cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Swing Market
Baby Products
Baby Shoes Market
Baby Products
Baby Tableware Market
Baby Products
Durable Juvenile Products Market
Baby Products
Japan Baby Care Product Market
Baby Products
Diaper Bag Market
Baby Products
Baby Bottle Holder Market
Baby Products
Global Baby Car Seats Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Baby Stroller Market
Baby Products
Baby Slings Market
Baby Products
Feeding Pillow Market
Baby Products
Kids Training Pant Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Baby Playpens Market
Baby Products
Home Care Packaging Market