
 Baby Swing Market | 2026-2036
Baby Swing Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Swing Market Analysis
Chinese contract manufacturers is restructuring output toward certified baby gear facilities with dedicated infant-product assembly lines. Fisher-Price leverages its North American retail footprint to sustain shelf dominance in big-box channels. Graco anchors its position through in-house production of frame components and motorized bases. Nuna differentiates via premium fabric sourcing and Scandinavian design positioning.
A baby swing is a motorized or manually actuated seating device that suspends an infant in a reclined position and generates repetitive rocking motion through pendulum mechanics, belt drives, or electromagnetic actuators, typically supporting weights up to 9-13 kg and operating at speeds of 2-6 cycles per minute to soothe or entertain non-ambulatory children. Full-size swings with plug-in power sources occupy the largest revenue pool due to higher unit prices and extended feature sets including Bluetooth audio and multi-directional motion, while portable battery-operated variants represent the fastest-expanding category as urban parents prioritize foldable designs for small living spaces and travel compatibility.
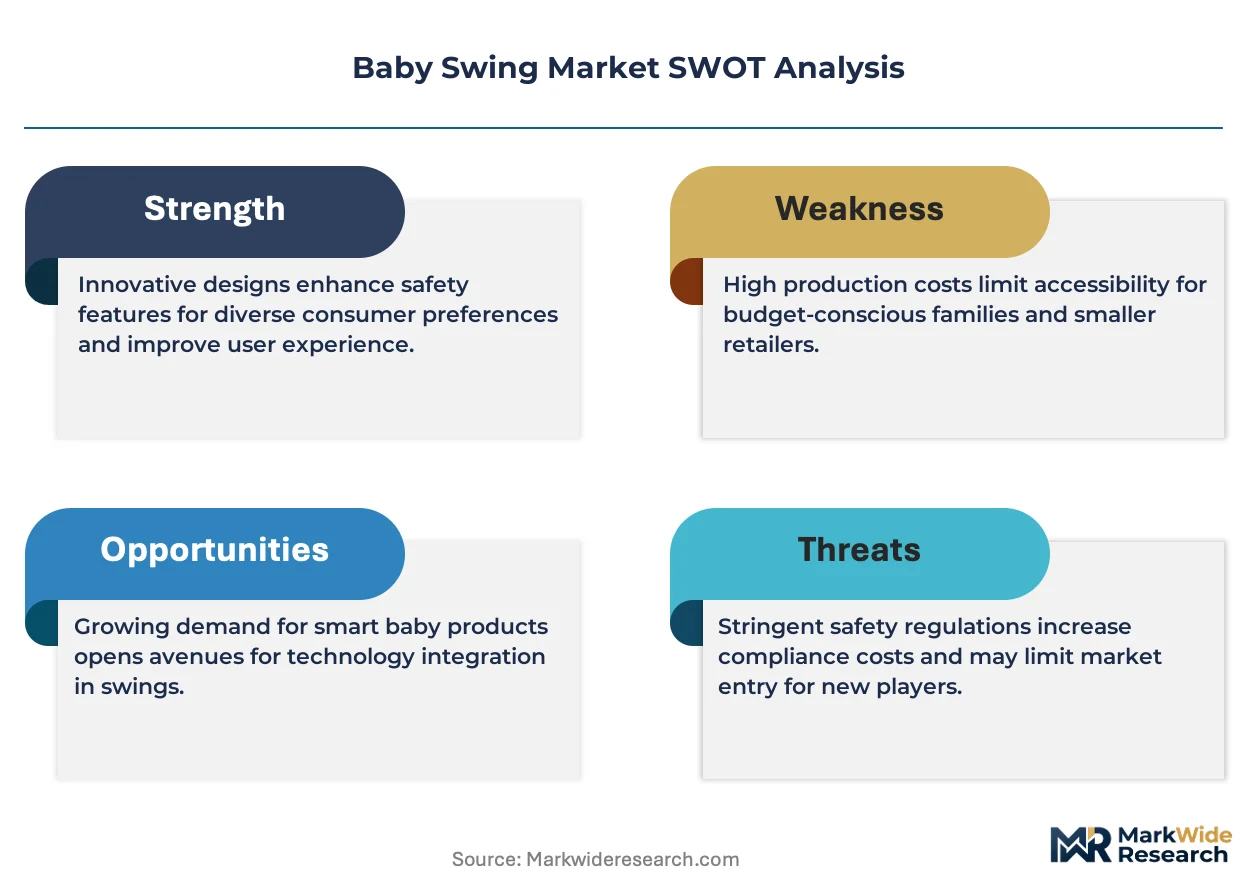
The US Consumer Product Safety Commission enforces mandatory safety standards for infant sleep products, compelling redesign of recline angles and restraint systems, while the EU's General Product Safety Regulation and CE marking requirements govern mechanical stability and chemical content for swings sold in European markets. China's SAMR administers GB standards for infant and child product safety, affecting export certification costs for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving sleep-product classification rules that could reclassify certain swing models into stricter regulatory categories.
Market Dynamics
The US Consumer Product Safety Commission's updated infant sleep product rule is compressing design cycles and forcing manufacturers to re-engineer recline angles, restraint systems, and motion profiles before products reach retail shelves.
Growth Catalysts
- Millennial suburban household formation:First-time parents in these zip codes prioritize motorized soothing devices with app connectivity and multi-directional motion, expanding the addressable base for premium full-size units.
- EU General Product Safety Regulation harmonization:CE marking requirements for mechanical stability and chemical content are streamlining cross-border certification, reducing redundant testing costs for brands selling into Germany, France, and the Netherlands.
- Electromagnetic actuator miniaturization:Belt-drive replacement with quieter, more efficient motor systems is enabling lighter frame designs without sacrificing swing amplitude or load capacity.
Market Restraints
- Polymer resin input volatility:Frame and housing manufacturers face margin pressure from petroleum-derived plastic price swings, complicating long-term supplier contracts.
- Chinese contract manufacturer concentration:Dedicated infant-product assembly lines remain concentrated in Guangdong and Zhejiang provinces, creating single-source vulnerability for brands without dual-facility qualification.
- Inclined sleeper recall spillover:Consumer confusion between recalled sleep products and compliant swings is depressing category trust, requiring heavier educational marketing spend.
Strategic Opportunities
- German premium retail channel expansion:Specialist baby boutiques in Munich, Hamburg, and Berlin are underserved by Scandinavian design-positioned entrants, creating shelf space for certified premium alternatives.
- Bluetooth-audio convergence with biometric monitoring:Integration of heart-rate and oxygen-saturation sensors into swing control units addresses parent anxiety while creating subscription data-service potential.
- India's BIS certification pathway:The Bureau of Indian Standards' expanding infant product safety mandate is opening formal retail channels previously blocked by import quality barriers.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous US CPSC, EU CE, and China GB testing creates 8-14 month product launch delays, freezing R&D amortization periods.
- Electromechanical systems integration complexity:Legacy frame suppliers struggle to source compatible motorized bases and control boards, forcing costly in-house engineering team buildouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Swing Market |
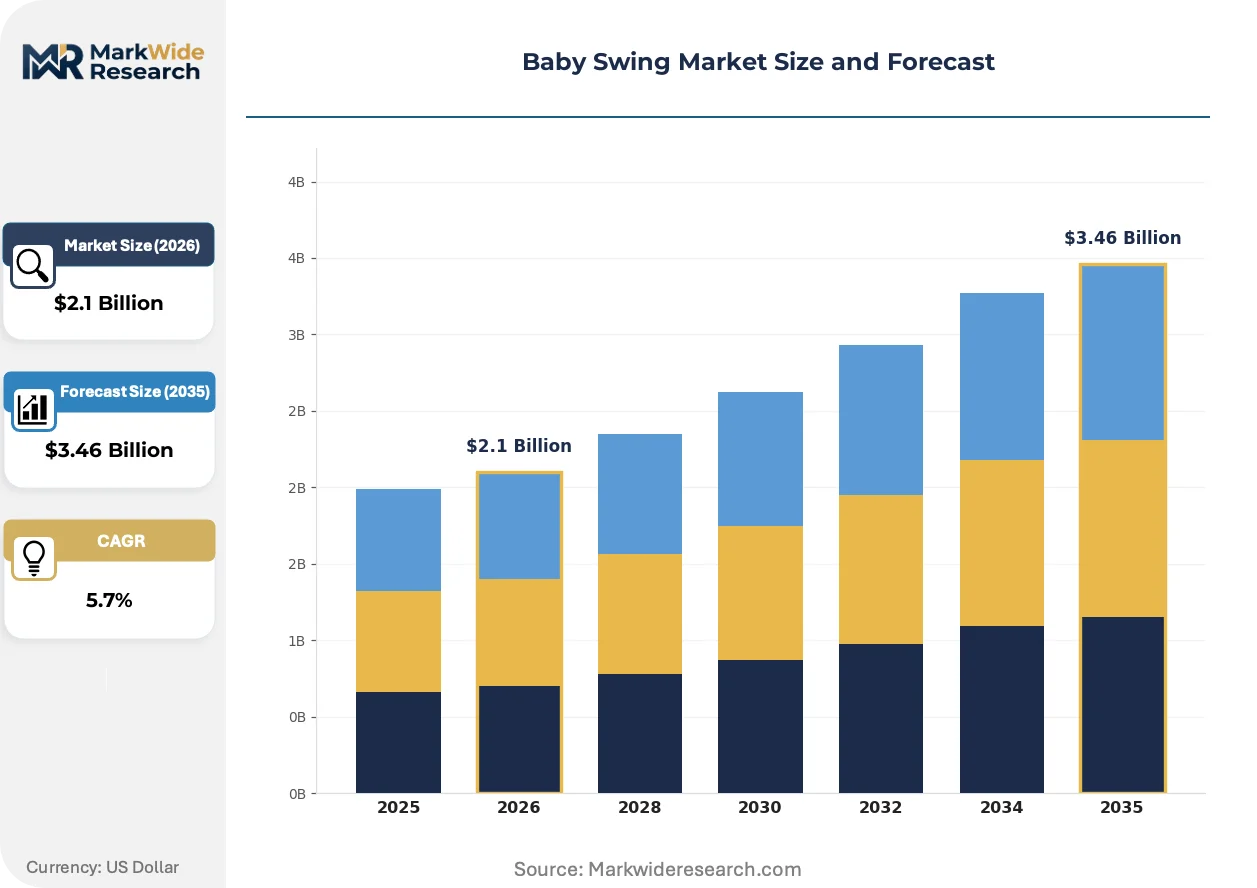
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.46 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Traditional Swing, Full-Size Swing, Portable Swing, Rocker Power Source: Battery-Operated, Plug-In, Manual, Hybrid Material: Wood, Plastic, Metal, Fabric Age Group: Newborn, Infants, Toddlers, Preschoolers |
| Companies Covered | 4Moms, BabyBjörn, Fisher-Price, Nuna, Munchkin, Graco, Ingenuity, Hauck, Maxi-Cosi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Swing Market Emerging Trajectories
Active redesign of swing architectures is compressing the boundary between soothing devices and monitored sleep environments, with sensor integration and power-system flexibility now determining competitive viability.
Electromagnetic actuator technology is modularizing swing drive systems into standardized motor-base units that detach from fabric seats and frame assemblies. Suburban millennial buyers are adopting these configurations fastest, valuing the ability to swap seat inserts across growth stages. This standardization is modularizing supplier relationships, allowing brands to source motors from specialty electromechanical vendors rather than captive frame manufacturers.
REACH chemical content restrictions and the EU's expanding Substances of Very High Concern list are forcing fabric and coating reformulations across European-bound production lines. Industrial consequence includes accelerated supplier audits and material traceability system investments. Premium Scandinavian-positioned brands are responding fastest, leveraging existing sustainability credentials to capture shelf space in German and Dutch specialist retail.
Urban parent cohorts are fragmenting purchase journeys across direct-to-brand websites, specialty boutique showrooms, and subscription rental services. Big-box channel dominance is eroding in dense metropolitan markets where square-footage constraints favor foldable, travel-compatible battery units. This behavioral pivot is most visible in Chinese tier-one cities and US coastal metros, where apartment living and gig-economy mobility patterns devalue plug-in full-size permanence.
Baby Swing Market Segmentation
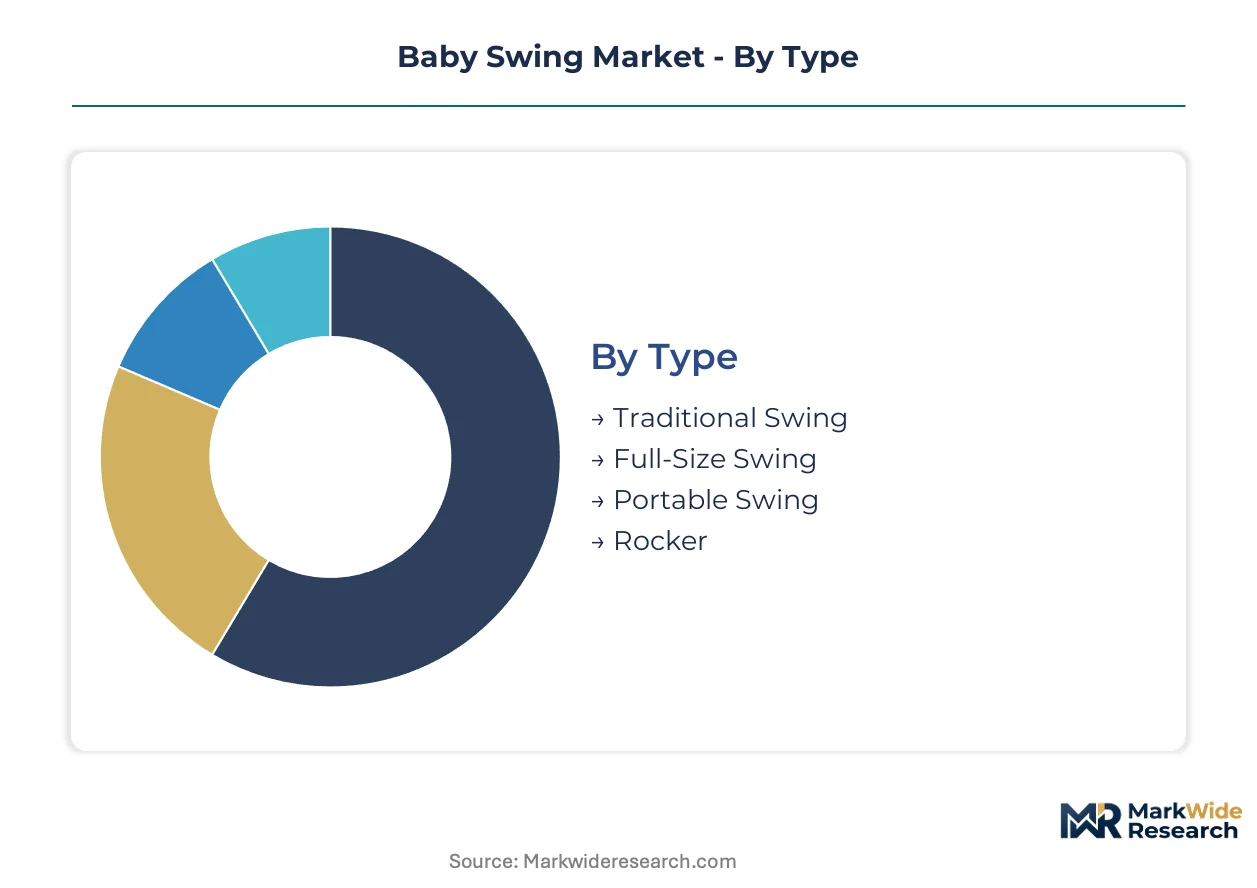
Segmentation in the baby swing market reveals how purchasing decisions split between permanent household fixtures and mobility-optimized solutions. Manufacturers must align R&D allocation with divergent technical requirements across power systems, material specifications, and developmental-stage weight capacities.
Type:
Suburban millennial households prioritize installation permanence and feature depth over portability when selecting swing architecture.
- Full-Size Swing:These units incorporate plug-in power sources, multi-directional motion mechanisms, and Bluetooth audio integration. Demand concentrates in United States suburban developments where dedicated nursery space accommodates larger footprints. Parents prioritize extended feature sets that justify premium positioning.
- Portable Swing:Foldable frame designs with battery operation dominate urban apartment dwellers in Chinese tier-one cities and US coastal metros. Compact storage and travel compatibility address square-footage constraints and gig-economy mobility patterns.
- Traditional Swing:Pendulum-based manual or basic motorized systems serve price-sensitive buyers in emerging markets with limited electrification infrastructure.
- Rocker:Static curved-base designs without suspension mechanics target caregivers seeking manual control over motion intensity for colic management.
Full-size swing leads on scale; portable swing leads on momentum.
Power Source:
Electrification infrastructure maturity and electricity pricing shape regional preference hierarchies for swing power systems.
- Plug-In:Continuous AC power enables higher-amplitude motors and integrated electronics without battery weight penalties. United States households with reliable grid access favor this configuration for primary nursery installations.
- Battery-Operated:Lithium-ion and alkaline configurations enable cordless placement flexibility. German urban parents prioritize this option for balcony and secondary room deployment where outlet proximity is limited.
- Hybrid:Dual-mode systems switch between AC and battery operation. These units appeal to frequent travelers seeking consistent functionality across destination power environments.
- Manual:Human-actuated mechanisms persist in rural China and India where electrification remains inconsistent and cost sensitivity is acute.
Plug-in power dominates revenue contribution; battery-operated systems are gaining share fastest.
Material:
Regulatory chemical restrictions and sustainability positioning drive material selection divergence across export destinations.
- Plastic:Polymer resin frames and housings enable complex geometries at scale. Manufacturers face margin pressure from petroleum-derived input volatility.
- Fabric:REACH-compliant textiles and coating reformulations dominate European-bound production. Premium Scandinavian-positioned brands leverage existing sustainability credentials.
- Metal:Aluminum and steel components provide structural rigidity for high-capacity units targeting toddler weight ranges.
- Wood:Aesthetic-focused designs target boutique retail channels in Germany and the Netherlands where visual integration with home décor influences selection.
Plastic dominates manufacturing throughput; fabric commands premium positioning.
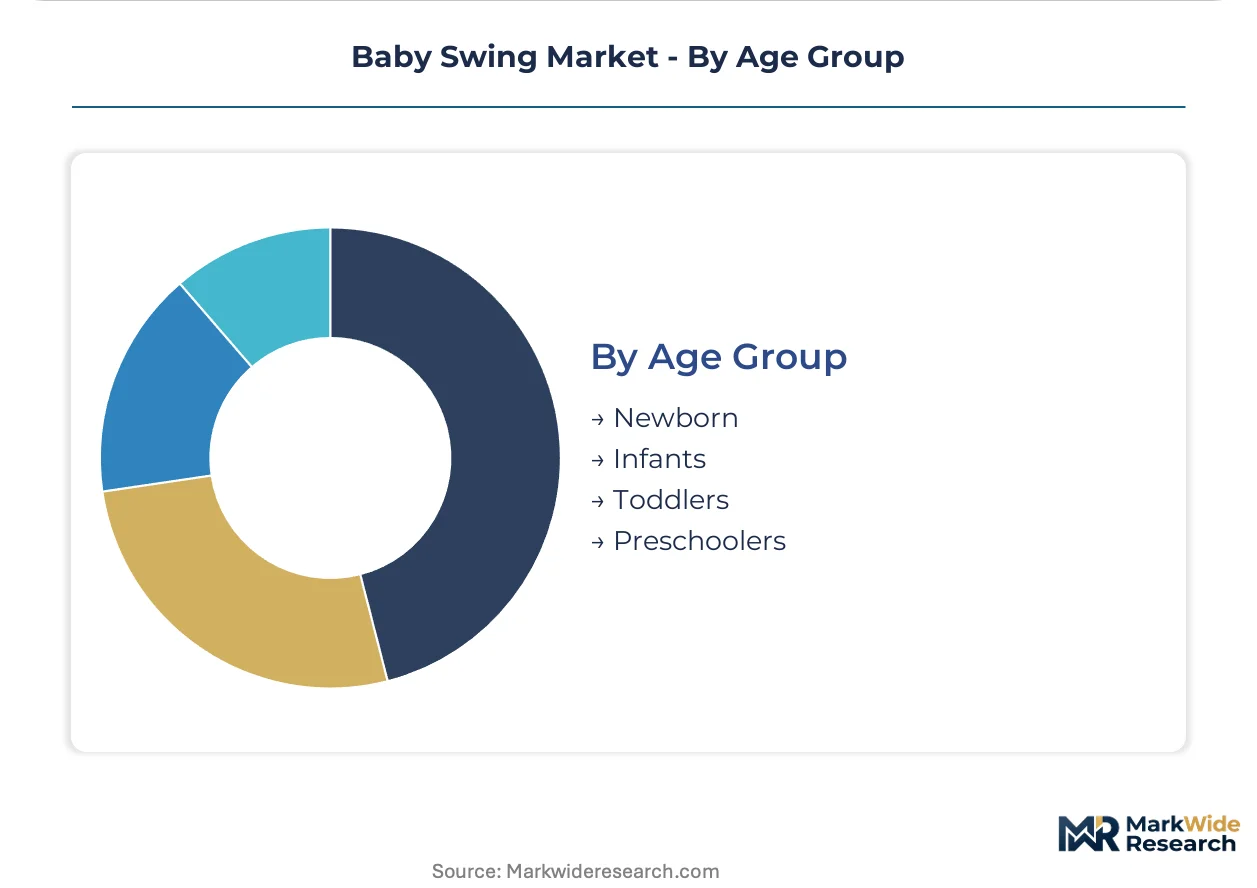
Age Group:
Weight capacity specifications and safety restraint complexity escalate with developmental progression.
- Infants:Units supporting 4-9 kg with five-point harness systems constitute the core volume base. US CPSC recline angle regulations specifically target this cohort.
- Newborn:Specialized inserts and flatter recline positions address pre-4 kg physiological requirements. Hospital discharge gift purchases concentrate demand here.
- Toddlers:Extended 9-13 kg capacity with reinforced frames captures extended product lifecycle value. Parents seek longevity justification for premium purchases.
- Preschoolers:Transitional seating configurations with reduced motion amplitude serve children approaching ambulatory independence.
Infant-targeted units lead on volume; toddler-capable designs lead on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are reshaping where baby swing production certifies and assembles. Manufacturers are migrating toward jurisdictions with streamlined infant-product safety pathways while demand concentrates in high-income households with nursery space.
United States
Suburban millennial household formation drives motorized full-size unit adoption across Texas, Florida, and Georgia developments. The US Consumer Product Safety Commission enforces mandatory infant sleep product standards that compress design cycles. Michigan and Ohio industrial corridors host contract manufacturers re-engineering recline angles and restraint systems for compliance.
China
Tier-one city apartment dwellers prioritize foldable battery-operated designs for space-constrained living in Shanghai and Shenzhen. The State Administration for Market Regulation administers GB standards affecting export certification costs. Guangdong and Zhejiang provinces concentrate dedicated infant-product assembly lines with dual-facility qualification investments.
Germany
Premium retail channel expansion accelerates in Munich, Hamburg, and Berlin specialist boutiques. REACH chemical content restrictions and CE marking requirements govern mechanical stability and textile formulations. Baden-Württemberg industrial clusters source REACH-compliant fabric coatings for Scandinavian-positioned brand supply.
India
First-time parents in Maharashtra and Karnataka urban centers seek motorized soothing devices with extended feature sets. The Bureau of Indian Standards expanding infant product safety mandate opens formal retail channels previously blocked by import barriers. Tamil Nadu assembly operations qualify for BIS certification to serve domestic demand growth.
Japan
Tokyo and Osaka metropolitan parents value compact hybrid power systems for balcony and secondary room deployment. METI oversees product safety standards harmonized with international infant gear protocols. Chubu region electromechanical suppliers miniaturize actuator systems for lighter frame designs.
Baby Swing Market Vendor Landscape
North American producers anchor one tier; European specialists hold premium positioning through design credentials. The vendor base splits between consolidated full-size manufacturers with captive retail footprints and fragmented portable unit assemblers serving urban mobility demand. Three archetypes dominate: Scandinavian-design premium brands, big-box channel incumbents with in-house frame production, and contract-manufacturing-dependent entrants. Capacity expansion and dual-facility qualification represent the dominant competitive moves as brands mitigate single-source vulnerability in Guangdong and Zhejiang.
Within the premium-tier vector, Nuna exemplifies Scandinavian design positioning through sustainability credentials and fabric sourcing discipline. Fisher-Price occupies a position as the big-box channel anchor with North American retail footprint dominance. Graco represents vertical integration archetypes through captive production of frame components and motorized bases. These three companies illustrate how competitive advantage separates across design premiumization, distribution scale, and manufacturing control.
| Leading Market Players |
|---|
| 4Moms |
| BabyBjörn |
| Fisher-Price |
| Nuna |
| Munchkin |
| Graco |
| Ingenuity |
| Hauck |
| Maxi-Cosi |
| Others |
Supply Flow & Price Mechanics
Electromagnetic actuator miniaturization is compressing unit economics while fragmenting supplier relationships, as brands abandon captive frame manufacturers for specialty electromechanical vendors. This technology transition concentrates cost pressure on legacy belt-drive producers while creating pricing power for modular motor-base suppliers serving multiple swing architectures.
Pricing Analysis
Distributor margin layering separates premium Scandinavian-positioned entrants from big-box channel incumbents. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with CE-marked and CPSC-compliant units commanding shelf premiums. Cost compression in the economy tier is intensifying because Chinese contract manufacturers face polymer resin input volatility. Urban apartment dwellers in Chinese tier-one cities and US coastal metros exhibit highest price sensitivity, while suburban millennial households in Texas and Florida developments demonstrate lowest sensitivity due to feature-depth prioritization.
Supply Chain Analysis
Polymer resin supply rests on petroleum-derived chemical producers in the United States, China, and Germany. Electromagnetic actuators, lithium-ion battery cells, and REACH-compliant textile coatings constitute critical input dependencies. Single-source vulnerability concentrates in Guangdong and Zhejiang provinces where dedicated infant-product assembly lines remain unqualified for dual-facility redundancy. Distribution runs through big-box retail channels for full-size units and direct-to-brand websites for foldable battery-operated variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the US Consumer Product Safety Commission's updated infant sleep product rule is accelerating replacement demand and compressing design cycles for non-compliant legacy inventory.
For Market Incumbents: Acquire dual-facility qualification assets in alternative Chinese provinces to mitigate single-source vulnerability in Guangdong and Zhejiang. Backward integration into electromagnetic actuator sourcing defends margin position against specialty vendor pricing power. CPSC compliance investment creates channel exclusion for non-compliant entrants.
For New Entrants and Emerging Players: Urban apartment dwellers in German tier-one cities represent an underserved buyer archetype with limited Scandinavian-design alternatives in Munich, Hamburg, and Berlin specialist boutiques. Portable battery-operated configurations with hybrid power systems penetrate this white-space fastest. Direct-to-brand website launch with subscription rental service bundling bypasses big-box channel gatekeeping.
For Investors and Strategic Acquirers: Roll-up economics work for modular electromechanical component suppliers because swing architecture standardization is displacing captive manufacturing relationships across multiple brand portfolios. Long-term viability centers on platform consolidation around detachable motor-base units. The signal to watch is BIS certification qualification rates among Tamil Nadu assembly operations serving Indian domestic demand growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Facility Qualification | Mitigates single-source vulnerability in Guangdong and Zhejiang infant-product assembly corridors. |
| Electromagnetic Actuator Integration | Enables lighter frame designs without sacrificing swing amplitude for suburban millennial buyers. |
| REACH-Compliant Fabric Sourcing | Captures German and Dutch specialist retail shelf space through sustainability credential alignment. |
| Bluetooth-Audio Biometric Convergence | Addresses parent anxiety while creating subscription data-service potential in premium segments. |
| BIS Certification Pathway Investment | Opens formal Indian retail channels previously blocked by import quality barriers in Maharashtra and Karnataka. |
Methodological Framework
Bottom-up suburban millennial household modeling reconciled against top-down Chinese contract manufacturer output tracking forms the analytical core of this study. Primary interviews with product safety compliance officers, category buyers at big-box retailers, electromechanical component procurement leads, and nursery furniture brand managers combined with secondary validation from CPSC recall databases, SAMR GB standard filings, EU RAPEX safety notifications, and customs trade records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of full-size versus portable swing adoption patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated power source architecture, material compliance tier, developmental stage weight capacity, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Electrification infrastructure maturity indices and apartment living density metrics informed regional penetration assumptions.
Underlying measurement precision varies by segment; battery-operated portable units and electromagnetic actuator technology adoption carry tighter precision than traditional manual swing categories in emerging markets. Forecasts reflect documented assumptions regarding CPSC rule enforcement timing and REACH substance restriction expansion. Regulatory reclassification risk, polymer resin price volatility, and Chinese manufacturer concentration constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Care Products Market
Baby Products
Global Baby Car Seats Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Baby Slings Market
Baby Products
South Korea Baby Care Products Market
Baby Products
Baby Personal Care Products Market
Baby Products
India Baby Care Products Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Diaper Bag Market
Baby Products
Sippy Cups Market
Baby Products
Puppy Teething Toys Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby High Chair Market
Baby Products
Portable Cribs Market
Baby Products
Electric Baby Nail Trimmer Market