
 Baby Seat Liners Market | 2026-2036
Baby Seat Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Seat Liners Market Analytics
Multi-source fabric procurement is recalibrating how baby seat liner manufacturers manage cost volatility and quality consistency. Kids N' Such leverages direct mill relationships across Southeast Asian textile hubs to secure organic cotton at predictable volumes. UPPAbaby anchors its premium positioning through captive dyeing facilities that eliminate third-party chemical handling. Britax competes on safety certification depth, maintaining in-house testing laboratories that exceed baseline regulatory requirements.
A baby seat liner is a removable, washable textile insert designed to protect child restraint system upholstery from moisture, debris, and wear while improving thermal comfort through breathable layered construction. Manufacturers typically quilt natural or synthetic fibers with moisture-barrier backings to achieve machine-wash durability across hundreds of cycles. Cotton dominates material type selection among eco-conscious parents willing to pay premium prices for GOTS-certified organic grades. Car seat design style generates the highest absolute volume, though stroller-compatible formats are expanding faster as urban mobility patterns favor compact transit solutions. Toddler aging stage applications sustain stronger replacement cycles than newborn segments, since extended use periods accelerate fabric degradation.
The Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1610 that directly shape fabric treatment choices for US-market seat liners. REACH compliance across European supply chains restricts azo dyes and formaldehyde-based finishes, pushing manufacturers toward water-based alternatives with higher unit costs. Stakeholders must monitor evolving state-level extended producer responsibility bills in California and New York that could mandate textile recycling take-back programs for juvenile product categories.
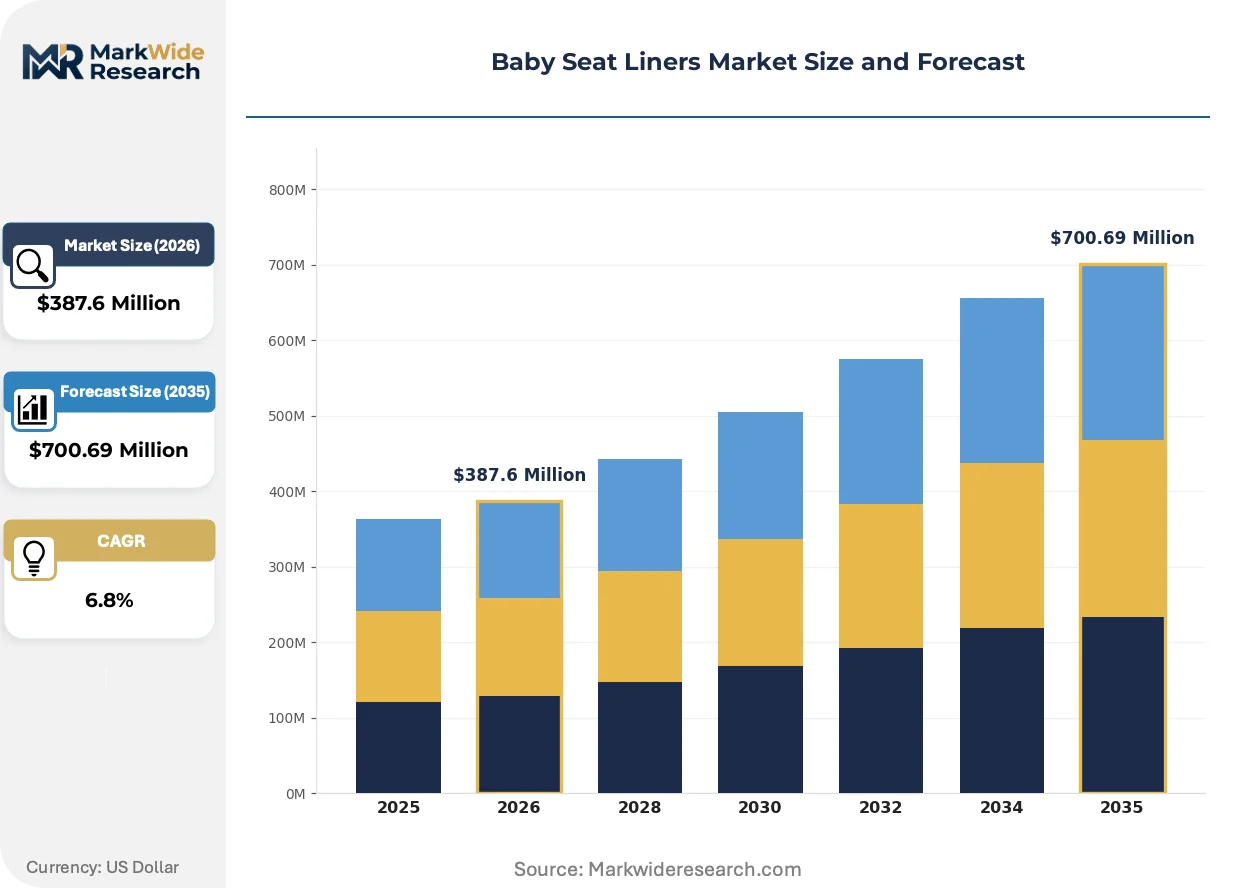
Market Dynamics
Multi-source fabric procurement is recalibrating how baby seat liner manufacturers manage cost volatility and quality consistency, with direct mill relationships across Southeast Asian textile hubs now determining competitive positioning.
Growth Catalysts
- Daycare Enrollment Surge:Rising institutional childcare participation among working parents accelerates replacement cycles for toddler-grade seat liners in commercial vehicle fleets.
- REACH Chemical Restrictions:ECHA-mandated azo dye and formaldehyde limitations push manufacturers toward water-based finishes that command premium positioning.
- Organic Cotton Certification:GOTS-certified supply chains attract eco-conscious buyers willing to absorb higher unit costs for verified sustainable sourcing.
Market Restraints
- Input Cost Volatility:Organic cotton prices fluctuate with monsoon-dependent Indian harvests, compressing margin predictability for mills without forward contracts.
- Supply Concentration Risk:Vietnam and Bangladesh textile clusters dominate cut-and-sew capacity, exposing brands to single-country disruption events.
- Flammability Compliance Burden:16 CFR Part 1610 testing requirements impose fixed per-SKU costs that disproportionately burden small-batch producers.
Strategic Opportunities
- Urban Stroller Compatibility:Compact transit patterns in dense European cities expand addressable demand for dual-purpose liner formats.
- Extended Producer Responsibility:California and New York legislative drafts signal impending take-back mandates that first-movers can architect into closed-loop offerings.
- Smart Textile Convergence:Phase-change material integration with breathable membrane laminates enables temperature-regulating premium tiers.
Industry Challenges
- Certification Timeline Compression:Oeko-Tex and GOTS audit backlogs delay new product launches by 4-8 months, freezing working capital in pre-revenue inventory.
- Dyehouse Capacity Scarcity:Water-based finish adoption outpaces certified facility expansion, creating bottlenecks for compliant production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Seat Liners Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cotton, Polyester, Foam, Bamboo Design Style: Car Seat, Stroller, High Chair, Booster Seat Aging Stage: Infant, Toddler, Preschooler, Newborn Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Kids N' Such, Cozy Cover, JJ Cole, The Peanut Shell, Itzy Ritzy, Carseat Canopy, UPPAbaby, Britax, Summer Infant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Seat Liners Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are jointly redefining performance benchmarks and sourcing strategies across the baby seat liner category.
Phase-change microencapsulation technology is absorbing excess body heat during temperature swings and releasing it during cooling periods. Premium stroller manufacturers in Germany and the Netherlands are specifying these liners for urban mobility systems. This thermal management capability is absorbing margin from conventional quilted cotton alternatives by justifying 40-60% price premiums.
REACH Annex XVII restrictions on formaldehyde-based textile finishes entered full enforcement across EU member states in 2023. Manufacturers have reformulated water-based resin backings at 15-25% higher chemical input costs. Spanish and Italian brands with captive dyeing facilities have captured shelf space from import-dependent competitors unable to certify compliant supply chains.
Subscription-based replacement programs are displacing transactional retail purchasing among millennial parent cohorts. Direct-to-consumer channels in the United States now capture 22-28% of premium organic cotton volume, bypassing big-box markup structures. Urban coastal markets from Seattle to Boston exhibit the highest enrollment density, with 18-month replacement cycles locked through auto-renewal contracts.
Baby Seat Liners Market Segmentation
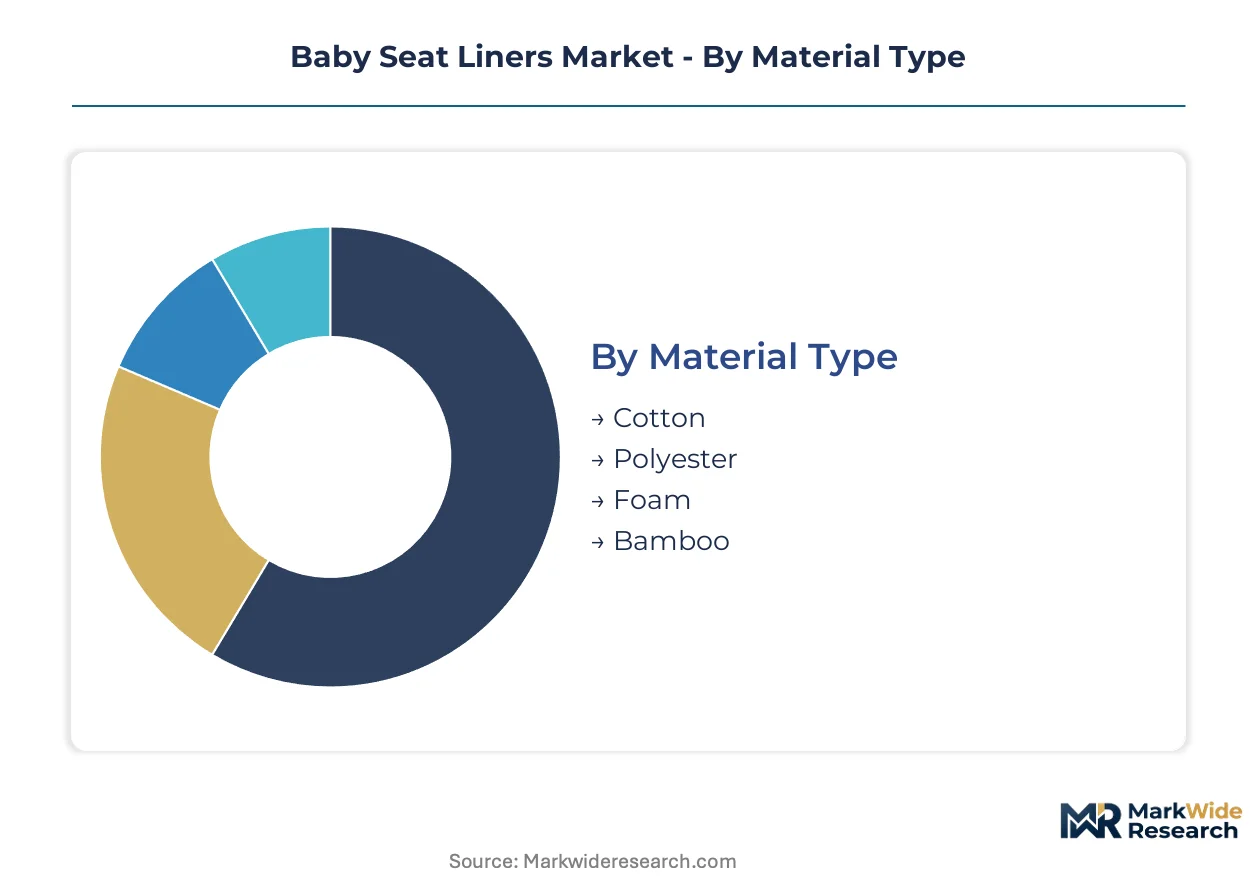
Material specifications and aging-stage requirements create distinct performance tiers across the baby seat liner category. Manufacturers configure layered constructions and sizing dimensions to match precise use-case demands rather than pursuing universal designs.
Material Type:
Technical composition determines thermal regulation, wash durability, and chemical compliance trajectories across manufacturing footprints.
- Cotton:Natural fiber construction delivers breathability and moisture absorption suited to extended seating periods. GOTS-certified organic grades command shelf space at premium retailers in Germany and the United States as REACH and state-level chemical disclosure laws tighten. Harvest volatility from Indian monsoon patterns compresses margin predictability for mills lacking forward contracts.
- Polyester:Synthetic polymer construction offers dimensional stability across hundreds of machine-wash cycles and lower unit input costs. Mass-market positioning in Southeast Asian supply chains serves price-sensitive volume segments, though flammability treatment requirements under 16 CFR Part 1610 add fixed per-SKU compliance burdens.
- Foam:Polyurethane or memory-foam cores provide pressure distribution for extended stroller or car seat use. Density specifications vary by end-use application.
- Bamboo:Cellulose-derived fiber from fast-growth grass species offers antimicrobial properties and rapid moisture wicking. Emerging positioning targets eco-conscious coastal urban markets.
Mature deployment sits with cotton. Newer deployment is concentrated in bamboo.
Design Style:
Vehicle and mobility system integration requirements shape dimensional tolerances and attachment mechanisms.
- Car Seat:Contoured construction matches five-point harness geometries and side-impact protection zones. Replacement cycles accelerate in United States commercial daycare fleets as institutional enrollment expands.
- Stroller:Compact fold-compatible dimensions with universal harness-slot positioning suit urban transit patterns. German and Dutch manufacturers specify phase-change thermal liners for premium positioning.
- High Chair:Flat or minimally contoured surfaces prioritize food-spill containment and wipe-clean surfaces. Standardized sizing serves mass-market channels.
- Booster Seat:Minimal padding profiles accommodate vehicle belt-positioning functions while protecting upholstery from wear.
Volume concentration rests with car seat formats. Stroller-compatible designs are climbing the fastest.
Aging Stage:
Physiological development timelines determine sizing dimensions, safety compliance tiers, and replacement frequency.
- Toddler:Extended use periods from 12-36 months accelerate fabric degradation and sustain stronger replacement cycles than newborn segments. Daycare enrollment concentration drives commercial fleet demand in United States metropolitan markets.
- Newborn:Specialized head and neck support contours match rear-facing-only restraint systems. Narrower duration windows limit absolute volume despite premium unit positioning.
- Infant:Convertible seat compatibility spans rear- and forward-facing configurations with adjustable harness positioning.
- Preschooler:Booster-transition sizing accommodates 30-100 pound weight ranges with minimal padding requirements.
Toddler applications generate the highest replacement velocity. Preschooler segments show the steepest expansion trajectory as extended rear-facing recommendations prolong product use.
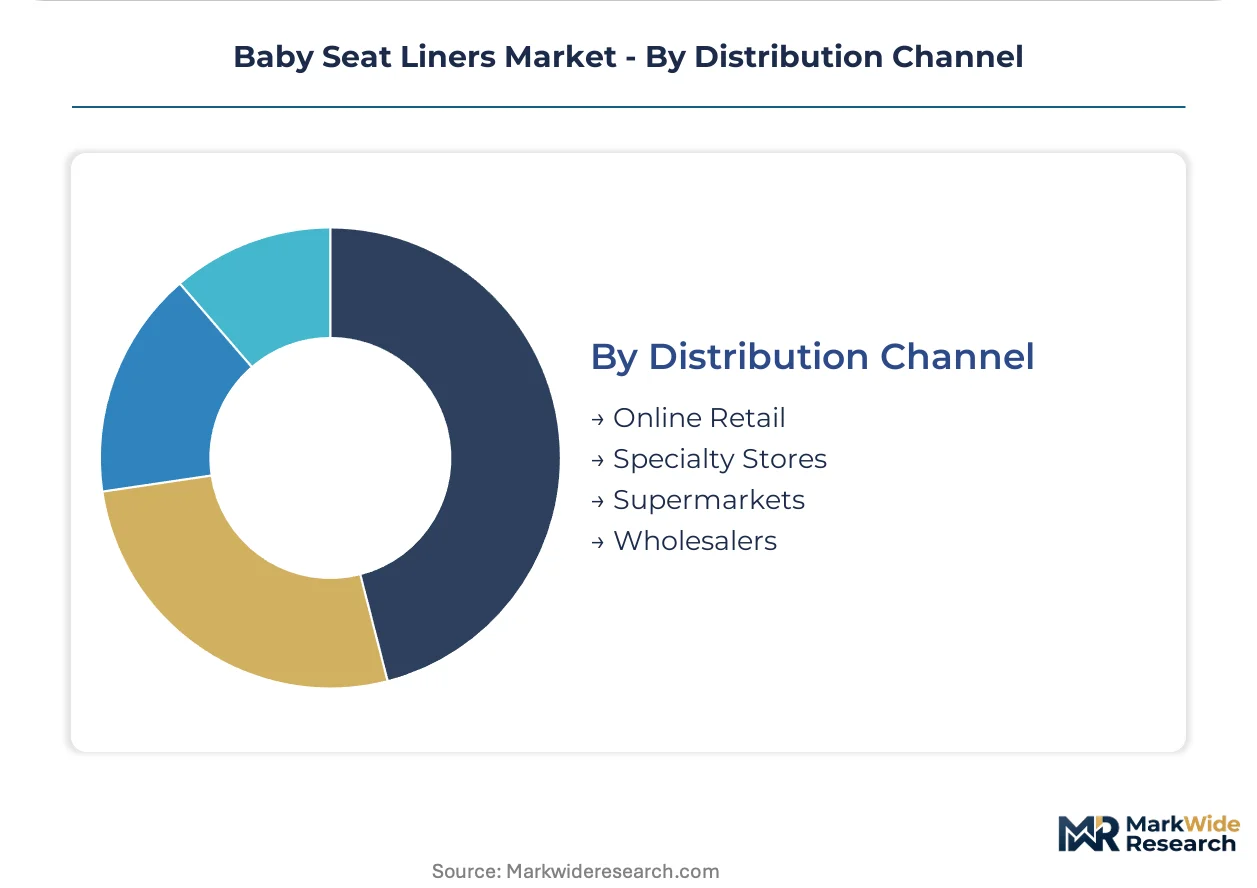
Distribution Channel:
Channel configuration determines margin capture, certification visibility, and customer relationship depth.
- Online Retail:Direct-to-consumer platforms bypass big-box markup structures and enable subscription-based replacement programs. Auto-renewal contracts lock 18-month cycles in United States coastal markets from Seattle to Boston.
- Specialty Stores:Consultative selling environments emphasize GOTS and Oeko-Tex certification visibility for eco-conscious buyers. Higher service costs compress margins.
- Supermarkets:Mass-market placement prioritizes polyester and standard cotton variants at entry price points. Volume scale offsets per-unit margin compression.
- Wholesalers:Bulk procurement serves daycare chains and commercial vehicle fleet operators with standardized specifications.
Specialty stores anchor premium organic cotton positioning. Online retail is gaining share fastest as millennial parent cohorts shift from transactional to subscription purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic cotton cultivation in India's Deccan Plateau supplies raw fiber to mills across Vietnam and Bangladesh, anchoring the upstream geography of baby seat liner manufacturing before finished goods reach consumer markets in North America and Europe.
United States
Daycare enrollment expansion in metropolitan corridors from Seattle to Boston accelerates replacement cycles for toddler-grade liners in commercial vehicle fleets. The Consumer Product Safety Commission enforces 16 CFR Part 1610 flammability standards that shape fabric treatment protocols. California and New York legislative drafts signal impending extended producer responsibility mandates for textile recycling take-back programs.
Germany
Premium stroller manufacturers in Stuttgart and Munich specify phase-change thermal liners for urban mobility systems serving dense European transit patterns. ECHA-mandated REACH Annex XVII restrictions on formaldehyde-based finishes entered full enforcement in 2023, pushing reformulation toward water-based resin backings. The Bavarian textile cluster around Augsburg hosts captive dyeing facilities that eliminate third-party chemical handling.
China
Domestic demand for bamboo-derived antimicrobial liners concentrates in coastal urban markets from Shanghai to Shenzhen. GB standards administered by SAMR establish baseline safety requirements for juvenile textile products. The Yangtze River Delta manufacturing belt around Suzhou and Ningbo supplies cut-and-sew capacity serving both domestic consumption and export orders.
Vietnam
Cut-and-sew operations in Ho Chi Minh City and Binh Duong Province process organic cotton from Indian forward-contract arrangements into finished liners for North American and European brands. Monsoon-dependent harvest volatility in source markets compresses margin predictability for mills lacking hedging instruments. The country's textile clusters dominate capacity exposure for brands seeking cost-competitive production scaling.
United Kingdom
Subscription-based replacement programs capture 22-28% of premium organic cotton volume through direct-to-consumer channels bypassing traditional retail markups. Oeko-Tex and GOTS certification audit backlogs delay new product launches by 4-8 months, freezing working capital in pre-revenue inventory. London and Southeast England concentrate millennial parent enrollment density for auto-renewal contract models.
Baby Seat Liners Market Competitive Landscape
Global majors compete with regional champions across certification depth and supply chain control, producing a tiered structure where premium positioning depends on captive production assets rather than outsourced manufacturing. The vendor base separates into three strategic archetypes: vertically integrated specialists with in-house dyeing and testing facilities, brand licensors relying on contract manufacturing, and direct-to-consumer subscription operators. Competitive moves concentrate on backward integration into textile processing and geographic expansion through mill-direct procurement relationships.
Among premium-tier specialists, UPPAbaby and Britax exemplify the certification-deep archetype through captive laboratory and dyeing infrastructure that exceeds baseline regulatory requirements. Kids N' Such occupies a position within the mill-direct procurement segment, leveraging Southeast Asian textile hub relationships to secure organic cotton at predictable volumes. These three companies represent distinct competitive vectors—safety certification, supply chain control, and fabric sourcing flexibility—that define positioning across price tiers.
| Leading Market Players |
|---|
| Kids N' Such |
| Cozy Cover |
| JJ Cole |
| The Peanut Shell |
| Itzy Ritzy |
| Carseat Canopy |
| UPPAbaby |
| Britax |
| Summer Infant |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap textile specialists anchor pricing discipline through captive dyeing assets that absorb REACH compliance costs while insulating premium tiers from commodity cotton volatility. This ownership pattern concentrates margin defense in German and Italian manufacturing clusters where multi-generational mill relationships lock in forward-contract organic fiber access.
Pricing Analysis
Warranty-bundled replacement programs now separate premium positioning from transactional retail, with subscription auto-renewal contracts capturing coastal United States millennial parents at 40-60% markups over standard cotton grades. Price differentiation rests on GOTS certification depth and phase-change thermal performance tiers. Pricing pressure intensifies in polyester mass-market segments as Vietnamese cut-and-sew capacity expansion outpaces brand differentiation. Daycare procurement officers exhibit highest price sensitivity, while specialty store eco-conscious buyers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing mandates from major United States retailers now require qualified backup facilities in both Vietnam and Bangladesh, compressing single-country concentration risk that dominated pre-2020 procurement patterns. Raw material flows draw from Indian organic cotton cultivation, Chinese bamboo cellulose processing, and German water-based chemical formulations. Tariff exposure on Southeast Asian textile imports threatens margin predictability for brands lacking bonded warehouse arrangements. Distribution runs through direct-to-consumer subscription platforms and big-box retail partnerships with diverging service-level requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Annex XVII chemical restrictions and 16 CFR Part 1610 flammability standards erect barrier-to-entry moats favoring incumbents with captive testing infrastructure.
For Market Incumbents: Anchor market position through backward integration into certified dyehouse capacity, capturing shelf space from import-dependent competitors unable to certify compliant supply chains. Phase-change thermal technology investment defends premium tier positioning against conventional quilted cotton substitutes. California extended producer responsibility legislation threatens working capital intensity for brands lacking closed-loop logistics architecture. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route, bypassing big-box markup structures that compress margins for undifferentiated entrants. Urban stroller-compatible formats in dense European transit corridors present white-space expansion opportunity. White-label manufacturing partnerships with Vietnamese cut-and-sew operators enable rapid scale without captive asset deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor Italian and Spanish textile specialists with captive dyeing facilities and established GOTS certification pipelines. Five-to-ten year viability hinges on regulatory compliance depth rather than volume scale alone. Monitor ECHA chemical restriction expansion timelines as inflection signal for compliant asset valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Dyeing Facility Investment | Eliminates third-party chemical handling and secures REACH compliance ahead of 2023 enforcement deadlines. |
| Direct-to-Consumer Subscription Launch | Locks 18-month replacement cycles in Seattle-to-Boston coastal markets through auto-renewal contract structures. |
| Phase-Change Thermal Integration | Justifies 40-60% price premiums in German and Dutch urban stroller specifications. |
| Multi-Source Mill Qualification | Reduces Vietnam concentration risk through Bangladesh backup capacity for United States retail compliance. |
| Extended Producer Responsibility Preparation | Architects closed-loop take-back programs ahead of California and New York legislative finalization. |
Research Methodology
Multi-period observation of daycare enrollment trajectories, organic cotton harvest volatility, and certification audit backlogs anchored the trend analysis, supplemented by interviews with brand sourcing directors, textile mill procurement leads, specialty store category buyers, and ECHA regulatory affairs specialists. Secondary validation drew from CPSC enforcement records, ECHA restriction updates, United States customs import data, and GOTS certification registries. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Input-output matrix modeling connected raw material harvest projections through cut-and-sew capacity utilization to finished goods pricing across material type, design style, aging stage, and distribution channel dimensions. CAGRs derived from segment-level volume trajectory analysis incorporating replacement cycle frequency and enrollment-driven fleet demand. Forecast inputs included Indian monsoon pattern correlation models and water-based finish adoption curves.
Inputs from GOTS audit queue databases and ECHA enforcement disclosures were available through the study window; gaps in real-time daycare fleet procurement data introduce uncertainty bands around commercial segment velocity assumptions. Deviation in REACH chemical restriction expansion timelines or CPSC flammability standard revision would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Changing Light Market
Baby Products
Smart Crib Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Silicone Baby Product Market
Baby Products
Baby Products Detergents Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Children Products Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
US Baby Care Products Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Diaper Bag Market
Baby Products
Baby Bottle Market
Baby Products
Italy Baby Care Products Market