
 North America Baby Bottle Market | 2026-2036
North America Baby Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Baby Bottle Market Intelligence
Health-conscious millennial parents is bifurcating demand away from traditional price-sensitive buyers toward premium, safety-validated feeding systems. Comotomo Inc. differentiates through medical-grade silicone construction and breast-like design architecture. Newell Brands Inc. leverages its Dr. Brown's portfolio to sustain dominance in anti-colic venting technology across hospital and retail channels. Pigeon Corporation anchors its North American position with Japanese-engineered peristaltic nipple systems that command loyalty among lactation consultants.
A baby bottle is a handheld feeding vessel, typically 4–9 ounces in capacity, manufactured from food-grade polymers, borosilicate glass, or platinum-cured silicone, featuring a vented nipple assembly designed to deliver formula or expressed breast milk while minimizing air ingestion and colic risk. The primary commercial purpose is safe, measured infant nutrition delivery across home, clinical, and childcare environments. Plastic bottles retain volume leadership but face margin compression as BPA-free and anti-colic design features capture premium positioning and faster growth. Glass and silicone segments are expanding fastest in specialty retail and direct-to-consumer channels where material transparency commands price premiums.
The FDA governs food-contact substance safety under 21 CFR, while California's Proposition 65 and New York's emerging chemical disclosure laws create state-level compliance layers that manufacturers must navigate for market access. The Consumer Product Safety Commission enforces mechanical integrity and choking hazard standards that shape product testing protocols. Stakeholders must monitor evolving state chemical restrictions and hospital procurement shifts toward vented, clinically validated designs as the primary demand determinants.
Market Dynamics
Millennial and Gen-Z parent preferences for anti-colic venting and BPA-free materials are compressing margins on conventional plastic bottles while elevating clinically validated designs to premium positioning. This demand bifurcation is forcing manufacturers to reconfigure material sourcing and certification pipelines.
Growth Catalysts
- FDA 21 CFR food-contact standards:Federal safety mandates create baseline compliance barriers that validate premium pricing for certified manufacturers while filtering out low-cost imports.
- Hospital procurement protocols:Clinical validation requirements for vented feeding systems are pulling anti-colic designs into neonatal care units and post-discharge recommendations.
- California Proposition 65 chemical disclosure:State-level transparency mandates accelerate material transitions toward glass and platinum-cured silicone alternatives.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and Tritan copolyester resin prices fluctuate with crude oil markets, compressing margins on volume plastic bottle production.
- Single-source silicone supply concentration:Medical-grade silicone raw material production clusters in Southeast Asian contract manufacturers, creating geographic vulnerability for North American brands.
- Extended FDA premarket notification timelines:510(k) clearance requirements for novel venting mechanisms delay product launches by 12-18 months versus conventional designs.
Strategic Opportunities
- Direct-to-consumer subscription models:Recurring revenue platforms bypass retail margin compression while capturing lifetime value through nipple stage progression and replacement cycles.
- Canadian provincial healthcare reimbursement:Ontario and British Columbia expanding coverage for medically prescribed anti-colic feeding systems creates public payer channel access.
- Smart bottle sensor integration:Convergence of microfluidic flow measurement with Bluetooth temperature monitoring enables data-driven feeding analytics for lactation consultants.
Industry Challenges
- Biocompatibility testing capacity constraints:ISO 10993 cytotoxicity and sensitization study backlogs at contract laboratories extend product development cycles.
- Legacy molding equipment retooling costs:Transitioning from conventional injection molding to liquid silicone rubber processing requires seven-figure capital deployment per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Baby Bottle Market |
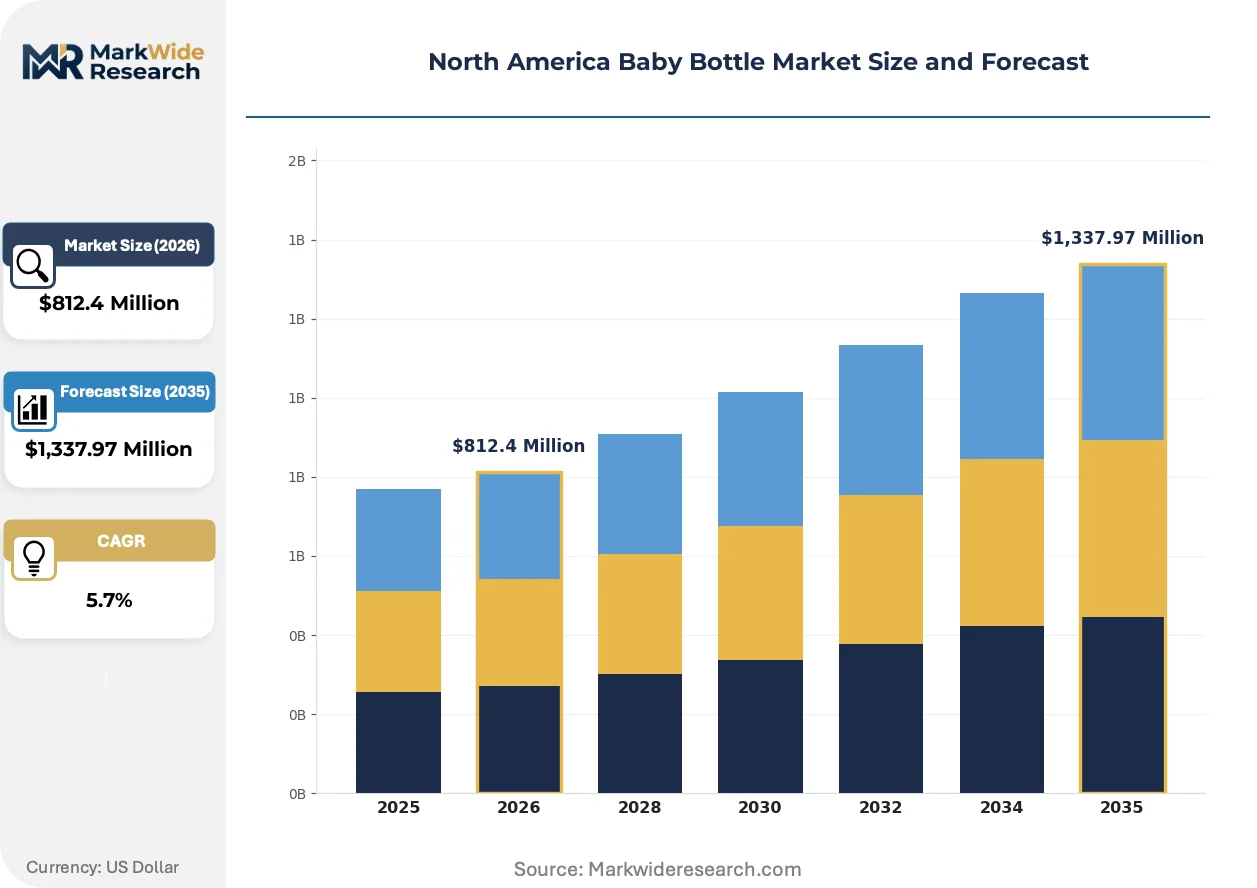
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,337.97 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Silicone, Stainless Steel Design Feature: Anti-Colic, Wide Neck, BPA-Free, Squeeze Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies End User: Parents, Caregivers, Hospitals, Childcare Centers |
| Companies Covered | Pigeon Corporation, Kiinde LLC, Newell Brands Inc., Nanobebe, Lifefactory, Munchkin Inc., Comotomo Inc., NUK, Handi-Craft Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Baby Bottle Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure mandates are restructuring competitive advantage around verifiable safety credentials rather than brand heritage alone. The convergence of clinical validation requirements with parent digital research behaviors is compressing traditional marketing channels.
Platinum-cured medical-grade silicone is bifurcating the premium segment from commodity plastics through breast-like texture and thermal stability. Lactation consultants and postpartum doulas are accelerating recommendations of silicone systems for combination feeding transitions. This material shift is compressing volume share for conventional polypropylene while enabling 40-60% price premiums in specialty retail.
California's Proposition 65 warning label requirements and New York's emerging chemical disclosure legislation are mandating supply chain transparency down to additive and catalyst levels. Manufacturers must now document bisphenol, phthalate, and heavy metal content across tier-two and tier-three suppliers. Smaller brands lacking compliance infrastructure are exiting these state markets, consolidating shelf presence among vertically integrated producers.
Parents are conducting pre-purchase research through lactation consultant networks and hospital discharge packet recommendations rather than retail aisle browsing. This trust-based discovery model displaces traditional advertising and big-box merchandising for first-time buyers. Urban coastal metros and Sun Belt cities exhibit the strongest consultant-channel influence, with Canadian markets showing parallel behavior through midwifery associations.
North America Baby Bottle Market Segmentation
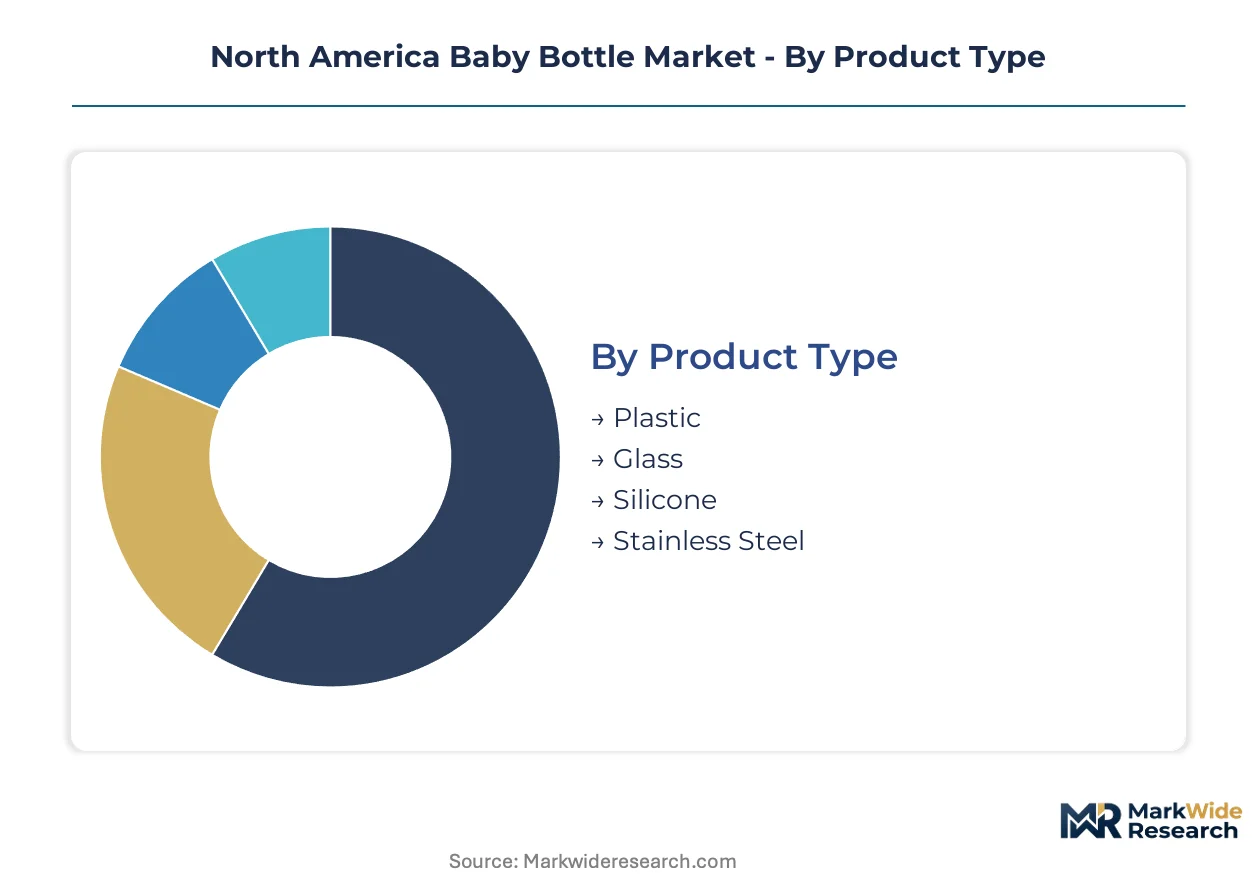
Material composition and design architecture determine regulatory compliance pathways and pricing power across the North America baby bottle market. Each segment category reflects distinct procurement behaviors between hospital systems, retail channels, and direct-to-consumer platforms.
Product Type:
FDA 21 CFR food-contact substance classifications and California Proposition 65 disclosure mandates create divergent compliance burdens across material categories, reshaping manufacturer sourcing strategies and channel access.
- Plastic:Polypropylene and Tritan copolyester formulations dominate hospital procurement and mass retail volumes. FDA premarket notification requirements for novel polymer blends compress margins while filtering out import competition. Sun Belt metropolitan hospitals and urban coastal retail chains anchor demand concentration.
- Glass:Borosilicate construction satisfies Proposition 65 transparency mandates without warning labels. Canadian provincial markets and California specialty retailers command 40-60% price premiums for thermal stability and chemical inertness. Ontario and British Columbia midwifery associations accelerate recommendations.
- Silicone:Medical-grade platinum-cured alternatives bypass petrochemical feedstock volatility entirely.
- Stainless Steel:Emerging niche for extended thermal retention in outdoor and travel applications.
Plastic handles the majority of throughput; silicone is expanding most quickly on share.
Design Feature:
Clinical validation requirements and parent digital research behaviors concentrate demand around functional performance claims rather than aesthetic differentiation.
- Anti-Colic:Vented nipple assemblies with internal or external venting mechanisms require ISO 10993 biocompatibility testing and 510(k) clearance timelines. Hospital neonatal care units and post-discharge recommendation protocols in Texas, Florida, and California pediatric networks drive procurement concentration.
- BPA-Free:Baseline compliance threshold mandated by FDA food-contact regulations since 2012. State-level chemical disclosure laws in New York and California extend verification requirements to bisphenol analogs and catalyst residues.
- Wide Neck:Facilitates formula preparation and cleaning access for combination feeding parents.
- Squeeze:Soft-wall construction enables flow control for preterm or low-tone infants.
Anti-colic configurations capture premium positioning; BPA-free claims have commoditized into baseline hygiene factors.
Distribution Channel:
Channel selection determines margin structure and customer lifetime value capture through replacement cycle management.
- Online Retail:Direct-to-consumer subscription platforms bypass retail margin compression while capturing nipple stage progression revenue. Urban coastal metros and Canadian direct-ship markets concentrate traffic through lactation consultant affiliate referrals.
- Supermarkets:Mass retail placement in Walmart, Target, and Kroger chains sustains volume for conventional plastic formats. Shelf space allocation favors established brands with vertical compliance documentation.
- Specialty Stores:Buy Buy Baby and independent boutiques command material transparency premiums.
- Pharmacies:CVS and Walgreens capture emergency replacement and travel-size demand.
Supermarkets handle the majority of throughput; online retail is climbing the fastest on share.
End User:
Procurement authority and reimbursement pathways segment demand between clinical validation requirements and convenience-driven purchasing.
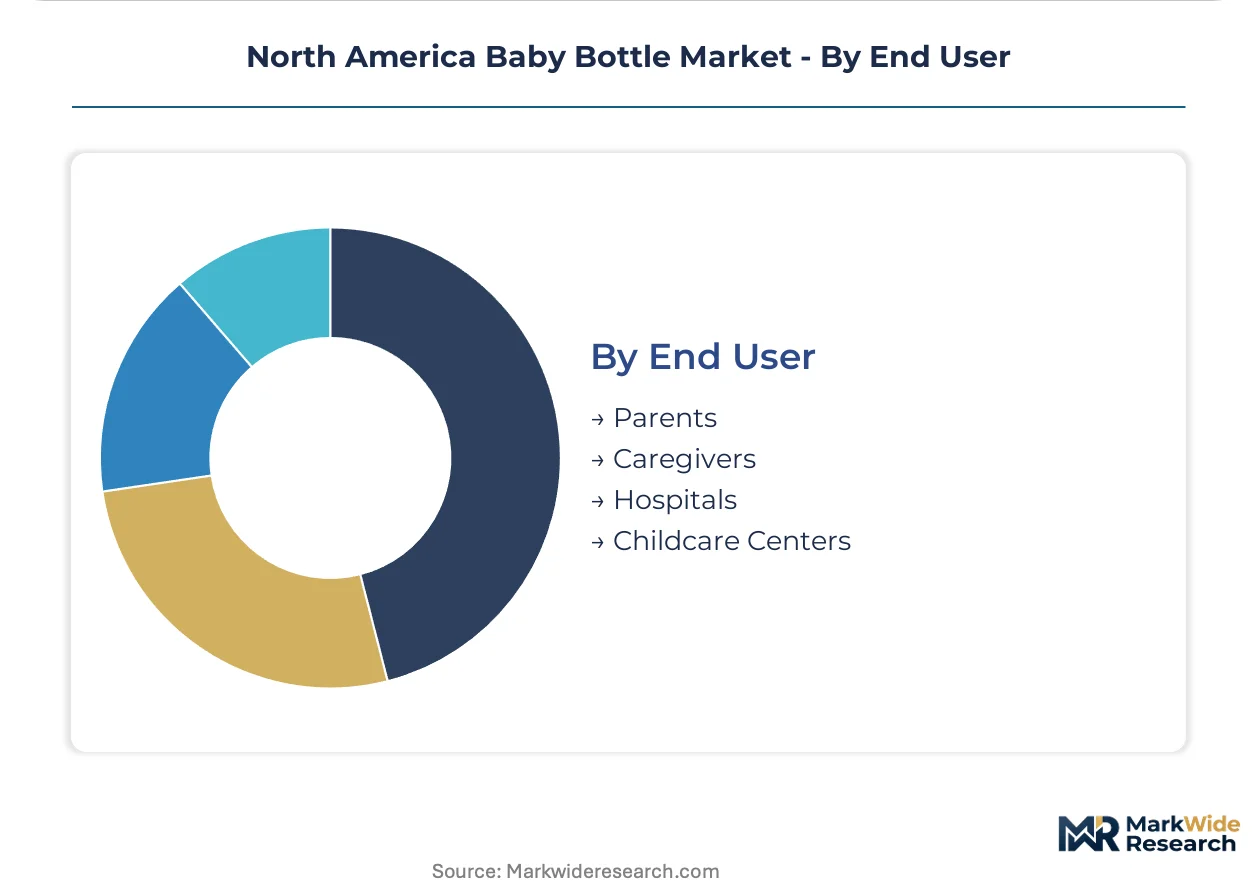
- Hospitals:Neonatal intensive care units and maternity wards require vented, clinically validated designs with documented air reduction metrics. Group purchasing organizations and discharge packet inclusion drive brand stickiness through lactation consultant recommendations.
- Parents:First-time millennial and Gen-Z buyers conduct pre-purchase research through consultant networks rather than retail browsing. Urban coastal metros and Sun Belt cities exhibit strongest digital discovery behaviors.
- Caregivers:Grandparents and extended family prioritize familiarity and retail accessibility over feature complexity.
- Childcare Centers:State licensing requirements mandate dishwasher-safe, durable construction for multi-infant environments.
Parents handle the majority of throughput; hospitals are gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American consumer goods distribution, channeling imported feeding systems into West Coast retail networks while FDA-regulated warehousing clusters along the I-5 corridor validate compliance documentation.
United States
Urban coastal metros and Sun Belt cities concentrate millennial parent demand for anti-colic and BPA-free designs. FDA 21 CFR food-contact standards filter import competition while validating premium pricing for certified domestic manufacturers. Texas and Florida pediatric networks drive hospital procurement consolidation for vented feeding systems.
Canada
Ontario and British Columbia provincial healthcare reimbursement programs expand coverage for medically prescribed anti-colic feeding systems. Health Canada PMRA regulations align with FDA standards while midwifery associations accelerate glass and silicone recommendations. Toronto and Vancouver specialty retail channels command material transparency premiums.
Mexico
Northern border states leverage maquiladora manufacturing infrastructure for plastic component production serving US retail chains. Mexican health regulator COFEPRIS maintains alignment with FDA food-contact standards. Monterrey and Tijuana industrial parks concentrate injection molding capacity for polypropylene bottle assemblies.
North America Baby Bottle Market Key Industry Players
Concentration sits with diversified consumer goods conglomerates and specialized infant feeding manufacturers. The market structure balances established brand portfolios against medical-grade material specialists. Three archetypes dominate: vertically integrated polymer processors, clinical validation-focused venting technology developers, and direct-to-consumer silicone specialists. Capacity expansion and portfolio diversification represent the dominant competitive moves.
Among diversified consumer goods portfolios, Newell Brands Inc. and Pigeon Corporation exemplify scale-driven market presence. Comotomo Inc. occupies a position within the medical-grade silicone specialist tier. These three entities represent the competitive spectrum from mass retail distribution through clinical channel validation to premium direct-to-consumer positioning.
| Leading Market Players |
|---|
| Pigeon Corporation |
| Kiinde LLC |
| Newell Brands Inc. |
| Nanobebe |
| Lifefactory |
| Munchkin Inc. |
| Comotomo Inc. |
| NUK |
| Handi-Craft Company |
| Others |
Cost & Logistics Intelligence
Medical-grade silicone substitution for conventional polypropylene is redrawing supplier geography toward Southeast Asian contract manufacturers while compressing margins on legacy plastic formats and enabling 40-60% price premiums for certified alternatives. This material transition simultaneously elevates FDA 510(k) clearance costs and fragments procurement leverage across tier-two additive suppliers.
Pricing Analysis
Volume-discount tiering structures separate hospital GPO contracts from retail shelf pricing and direct-to-consumer subscription rates. Three-tier pricing stratification across premium medical-grade silicone, mid-tier BPA-free plastics, and economy polypropylene reflects certification grade and clinical validation status. Cost compression in conventional plastic segments intensifies as petrochemical feedstock volatility squeezes contract manufacturer margins. First-time millennial parents exhibit lowest price sensitivity when lactation consultants validate anti-colic claims, while grandparents and extended family caregivers drive economy tier volume.
Supply Chain Analysis
Inventory lead times for medical-grade silicone extend 16-20 weeks versus 4-6 weeks for domestic polypropylene molding, constraining working capital flexibility for premium product lines. Raw material production clusters in Thailand, Malaysia, and China, with platinum-cured silicone catalysts sourced from German specialty chemical suppliers. Single-source vulnerability concentrates in Southeast Asian contract manufacturers serving multiple North American brands simultaneously. Distribution runs through the Port of Los Angeles-Long Beach complex into West Coast retail networks, with FDA-regulated warehousing validating compliance documentation along the I-5 corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
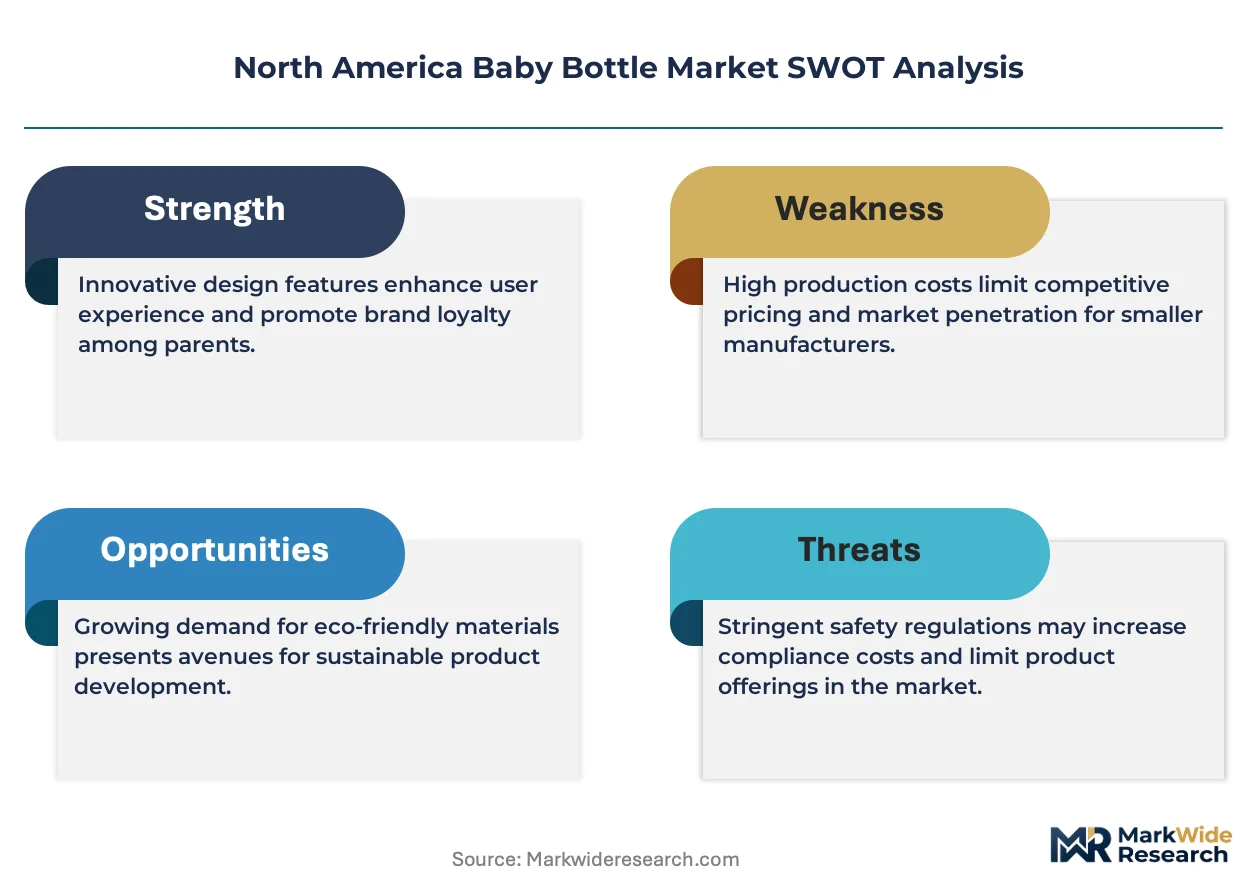
The North America baby bottle market operates as a defensive-moat arena where FDA 510(k) clearance timelines and clinical validation protocols create 12-18 month barriers against unqualified entrants. Regulatory entrenchment rewards incumbent investment in biocompatibility testing infrastructure and hospital procurement relationships.
For Market Incumbents: Consolidate hospital GPO contract positions through expanded ISO 10993 testing capacity and neonatal care unit validation studies. Defensive moves should prioritize backward integration into platinum-cured silicone compounding to offset Southeast Asian supply concentration, while simultaneously locking shelf space at Buy Buy Baby and Target through vertical compliance documentation that filters import competition. Threats from direct-to-consumer silicone specialists require preemptive subscription platform launches. For New Entrants and Emerging Players: Differentiate on material transparency and Proposition 65 compliance documentation rather than feature innovation. The most penetrable white space sits in Canadian provincial reimbursement channels, where Ontario and British Columbia coverage expansion for medically prescribed anti-colic systems creates public payer access without incumbent saturation. A go-to-market angle anchored in midwifery association endorsements bypasses retail margin compression. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed clinical validation platforms that have cleared FDA 510(k) pathways but lack direct-to-consumer scale. Long-term viability over a 5-10 year window hinges on subscription revenue capture and nipple stage progression economics. Acquisition targets should demonstrate hospital discharge packet inclusion rates above category median. The signal to watch is Health Canada PMRA alignment with FDA standards accelerating cross-border reimbursement harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Recurring revenue platforms capture lifetime value through nipple replacement cycles and bypass retail margin compression. |
| ISO 10993 Biocompatibility Certification | Hospital procurement protocols require documented cytotoxicity and sensitization testing for neonatal care unit access. |
| Backward Integration into Silicone Compounding | In-house platinum-cured production reduces Southeast Asian supply concentration vulnerability and accelerates R&D iteration. |
| Provincial Reimbursement Strategy | Ontario and British Columbia coverage expansion for medically prescribed anti-colic systems opens public payer channels. |
| Smart Bottle Sensor Integration | Bluetooth temperature monitoring and microfluidic flow measurement enable data-driven feeding analytics for lactation consultants. |
Research Approach
Operator-level perspectives from brand managers at infant feeding manufacturers, category buyers at Target and Walmart, lactation consultants in Texas and California pediatric networks, hospital GPO contracts managers, and silicone compounding specialists anchored the qualitative base. Secondary validation drew from FDA 510(k) premarket notification databases, Health Canada PMRA device listings, California Proposition 65 warning label registries, Nielsen retail audit data, and customs import records. Bottom-up demand modeling triangulated against top-down market sizing across material segments and distribution channels.
Sensitivity analysis tested forecast outputs against petrochemical feedstock volatility scenarios, FDA premarket timeline variations, and provincial reimbursement expansion rates across the analysis window. Segmentation dimensions modeled included material composition, design feature architecture, distribution channel structure, and end-user procurement authority. CAGRs derived from historical volume trajectories, replacement cycle frequencies, and demographic birth rate projections. Industry-specific inputs incorporated hospital discharge recommendation rates and lactation consultant referral network penetration.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity, stable Southeast Asian silicone supply, or continued millennial parent premium willingness would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway durations and material substitution elasticities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Pregnancy Products Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
Baby Bottle Warmers Market
Baby Products
France Baby Care Products Market
Baby Products
Italy Baby Care Products Market
Baby Products
Baby Cradles Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Global Baby Mattresses Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Baby Powder Market
Baby Products
Baby Bottle Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Stroller Rental Market
Baby Products
Baby Wet Wipes Market