
 Baby Playpens Market | 2026-2036
Baby Playpens Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Playpens Market Analysis
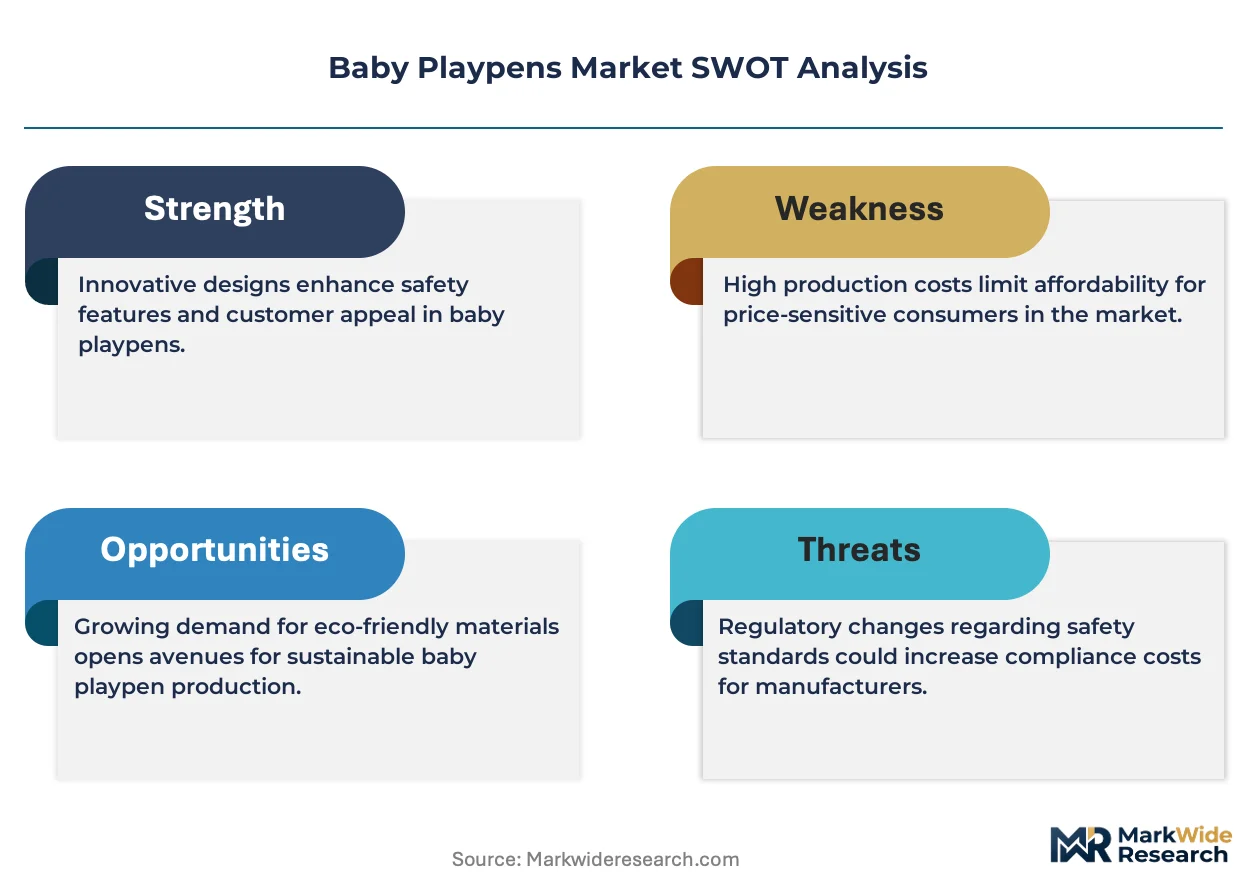
Aluminum tubing is pivoting away from heavier steel frames in mid-tier and premium playpen construction, cutting unit shipping weights and reducing raw material cost volatility. Graco leverages its North American distribution network to sustain volume leadership in big-box retail channels. BABYBJORN differentiates through Scandinavian design credentials and Oeko-Tex certification, commanding price premiums in direct-to-consumer sales. Evenflo anchors its position with value-engineered foldable systems distributed through mass-market e-commerce platforms.
A baby playpen is a freestanding enclosure with vertical panels or mesh sides, typically measuring between 28 and 36 inches in height, designed to confine infants and toddlers within a bounded safe zone during unsupervised periods. The structure employs hinged joints, locking mechanisms, and padded floor mats to prevent tipping, entrapment, or hard-surface contact. Foldable and portable configurations lead volume sales due to apartment-dwelling parents and travel-oriented lifestyles, while fabric-over-metal construction captures expanding margin pools as consumers prioritize lightweight durability over basic plastic models. Wood-frame variants occupy a niche position among sustainability-focused buyers despite higher price positioning and maintenance requirements.
The United States Consumer Product Safety Commission enforces mandatory standards for structural integrity, entrapment hazards, and chemical content in juvenile products, compelling manufacturers to maintain third-party testing protocols. The European Union's REACH regulation and General Product Safety Directive impose parallel constraints on phthalate content and small-part choking risks, shaping material choices for export-oriented suppliers. ASTM International and ISO 8124 provide supplementary voluntary benchmarks that brands adopt to signal quality assurance across multiple jurisdictions. Stakeholders must monitor evolving chemical restriction lists and state-level disclosure requirements in California and New York to anticipate compliance cost shifts and sourcing adjustments.
Market Dynamics
The United States Consumer Product Safety Commission's updated entrapment and chemical-content mandates are forcing material substitutions across the supply chain, compressing margins for manufacturers reliant on legacy mesh and untreated fabrics.
Growth Catalysts
- REACH chemical restrictions:The European Union's phthalate bans and small-part choking-risk standards are accelerating adoption of certified fabric-over-metal construction in export-oriented production facilities.
- Aluminum tubing substitution:Lighter frame materials are cutting shipping weights for direct-to-consumer fulfillment, enabling compact parcel delivery that mesh-and-steel designs cannot match.
- Daycare procurement concentration:Early childhood education facilities are consolidating vendor relationships around foldable systems that withstand institutional cleaning protocols and daily reconfiguration cycles.
Market Restraints
- Raw material volatility:Aluminum price swings and fabric coating chemical shortages are squeezing mid-tier manufacturers without long-term supply contracts or backward integration into textile finishing.
- Guangdong-Dongguan supply concentration:Overreliance on Pearl River Delta manufacturing clusters creates vulnerability to regional power rationing, port congestion, and labor cost inflation.
- Wood-frame durability ceiling:Sustainability-focused niche products face moisture-warping limitations that prevent penetration beyond climate-controlled urban households.
Strategic Opportunities
- India household formation:Rising nuclear-family urbanization in Tier-2 cities is creating first-time buyer segments with no existing brand loyalty and price elasticity for portable safety equipment.
- Subscription rental models:Equipment-as-a-service platforms targeting travel-oriented parents are bypassing retail markup structures and capturing recurring revenue from temporary-use occasions.
- Oeko-Tex certification convergence:Voluntary textile safety standards are becoming de facto procurement filters for premium direct-to-consumer channels, rewarding early certifiers with shelf-space advantages.
Industry Challenges
- Third-party testing bottlenecks:CPSC-mandated laboratory validation queues are extending product launch timelines, straining working capital for seasonal inventory builds.
- Multi-jurisdiction labeling complexity:California's Proposition 65 disclosure requirements and New York's emerging chemical transparency rules demand SKU-specific packaging variations that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Playpens Market |
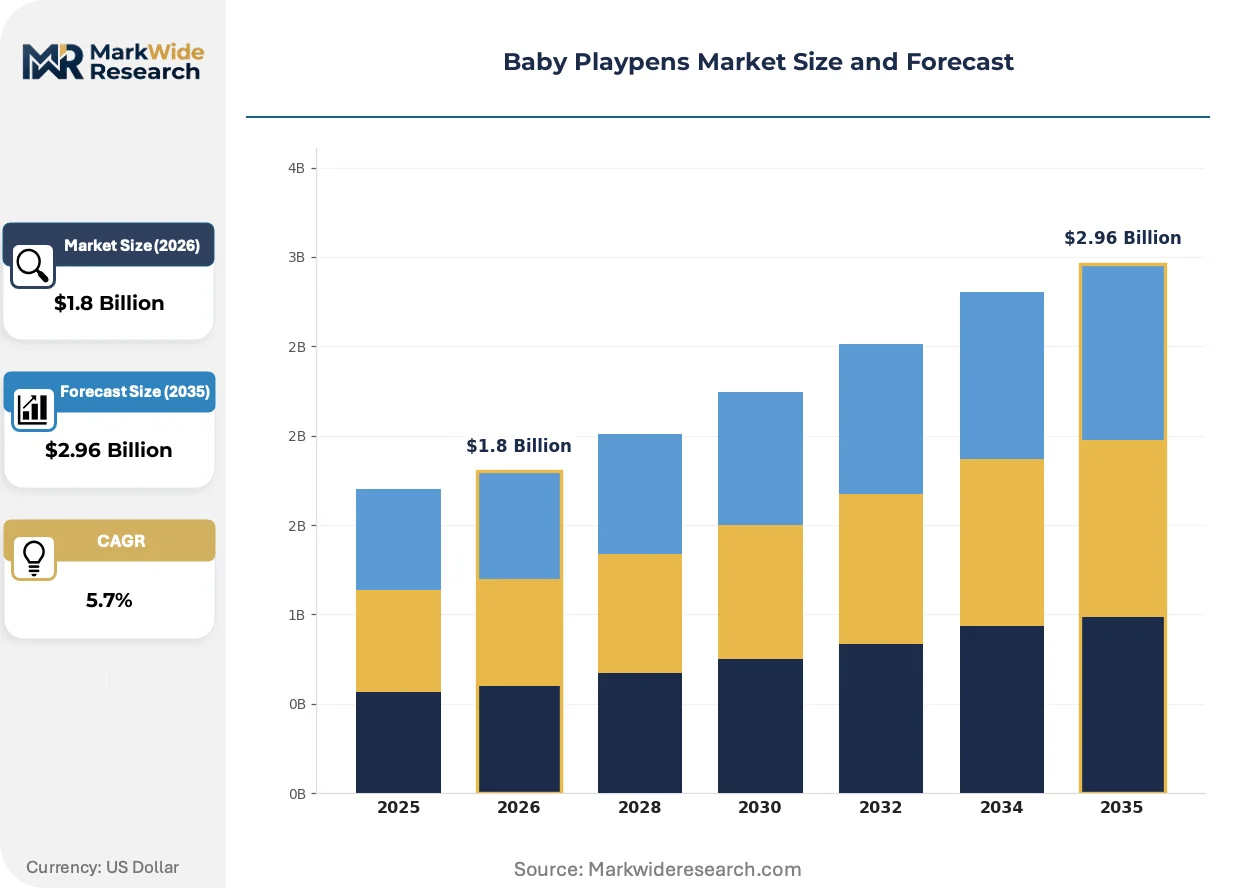
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Portable, Indoor, Outdoor Material: Plastic, Wood, Fabric, Metal Size: Small, Medium, Large, Extra Large Target Age Group: 0-6 Months, 6-12 Months, 1-2 Years, 2-3 Years |
| Companies Covered | UPPAbaby, Maxi-Cosi, 4moms, Skip Hop, BABYBJORN, Graco, Bugaboo, Dorel Juvenile, Evenflo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Playpens Market Emerging Trajectories
Fabric chemistry and frame metallurgy are converging with fulfillment logistics to redefine what constitutes a premium playpen, while regulatory fragmentation across major economies is multiplying compliance engineering costs.
Non-toxic flame-retardant fabric treatments are consolidating position in premium product lines as the functional replacement for conventional mesh. Daycare procurement officers and safety-conscious direct-to-consumer buyers are specifying certified textile surfaces at accelerating rates. This material shift is consolidating supplier power among chemical-coating specialists with existing juvenile-product testing relationships, squeezing pure-play frame manufacturers.
REACH substance restriction lists are expanding coverage of flame-retardant chemistries, forcing European-market suppliers to maintain dual formulation inventories. Manufacturers serving both United States and European Union destinations face divergent permissible compound portfolios. Export-oriented Chinese production facilities are responding by segmenting assembly lines by destination jurisdiction, adding fixed-cost overhead per geography.
Direct-to-consumer channel preference is displacing big-box retail discovery for first-time parents. Millennial and Gen-Z buyers are researching certification marks and comparative safety ratings through social video platforms before purchase. This behavioral shift concentrates most visibly in United States coastal metropolitan markets, where apartment-dwelling households prioritize delivery convenience over in-store assembly assistance.
Baby Playpens Market Segmentation
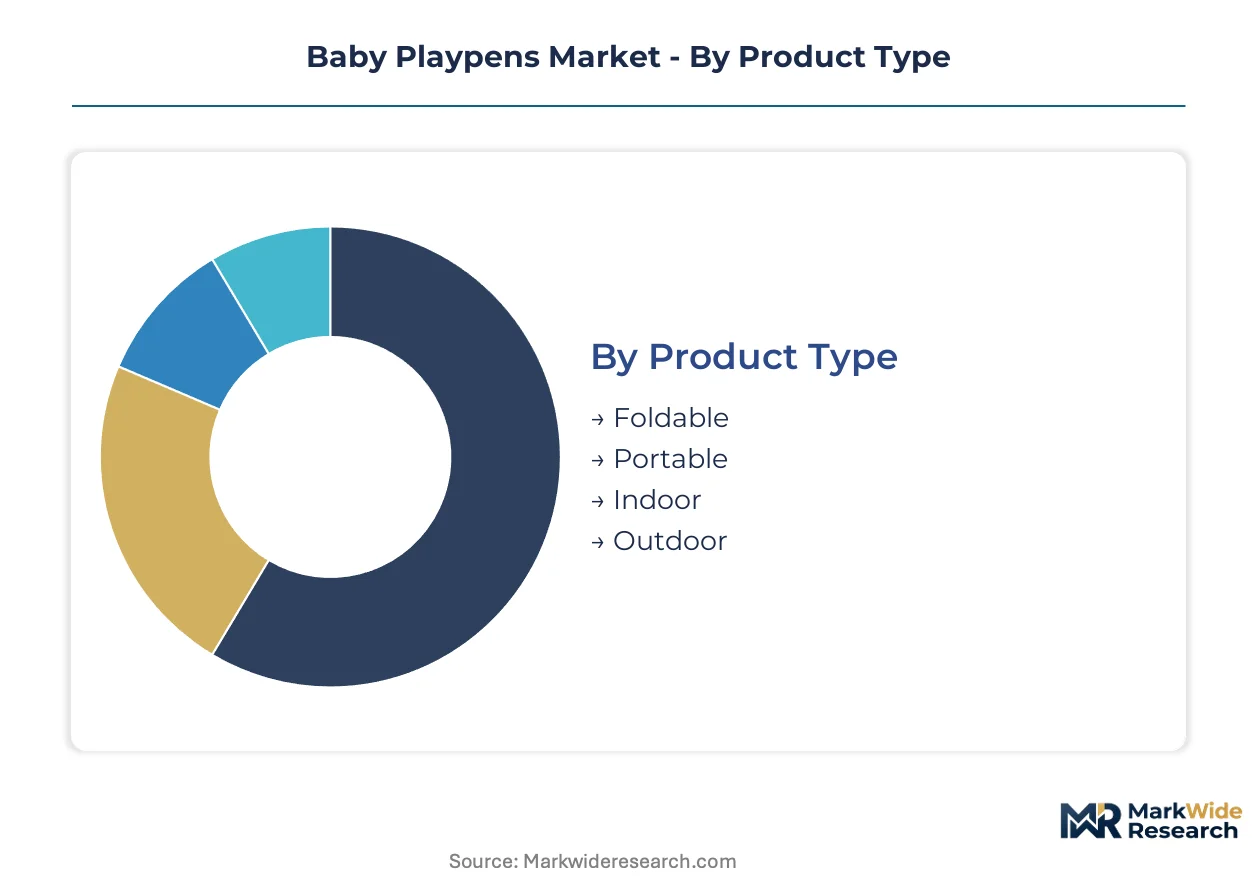
Segmentation in baby playpens reveals divergent purchasing logics across use cases and household constraints. Material choices and portability requirements separate premium direct-to-consumer buyers from mass-market retail purchasers.
Product Type:
Buyers in this category separate by mobility requirements and dwelling constraints rather than income alone.
- Foldable:Hinged joint systems with collapsible frames enable rapid breakdown for storage in compact urban apartments. Daycare centers in the United States specify these for daily reconfiguration cycles between activity periods and cleaning protocols.
- Portable:Lightweight assemblies under 15 pounds with carrying cases target travel-oriented parents and grandparents. Airlines' checked-baggage policies and hotel room dimensions constrain acceptable packed dimensions, favoring fabric-over-metal construction.
- Indoor:Fixed-base designs with padded floor mats prioritize stability over mobility for permanent nursery installation.
- Outdoor:UV-resistant fabrics and rust-proofed frames withstand patio exposure and lawn moisture.
Foldable systems lead volumes today; portable configurations are gaining share fastest.
Material:
Cost tiers and certification requirements divide this category between commodity suppliers and premium positioning.
- Plastic:Injection-molded polypropylene panels dominate entry-level retail through mass-market e-commerce platforms. Guangdong-Dongguan manufacturing clusters supply these at lowest unit cost, though REACH phthalate restrictions constrain export-oriented production.
- Metal:Aluminum tubing has displaced steel in mid-tier and premium lines, cutting shipping weights for direct-to-consumer fulfillment. CPSC entrapment mandates favor tubular designs with welded joint integrity over snap-fit plastic alternatives.
- Fabric:Oeko-Tex certified textile surfaces treated with non-toxic flame retardants command price premiums in Scandinavian and North American direct-to-consumer channels.
- Wood:Sustainability-focused buyers in climate-controlled urban households accept moisture-warping limitations for aesthetic positioning.
Plastic leads volumes today; metal is climbing the fastest.
Size:
Floor space availability and multi-child households drive differentiation in this dimension.
- Small:Compact footprints under 25 square feet fit studio apartments and temporary containment needs.
- Medium:Standard configurations balance play area with furniture clearance in typical suburban bedrooms.
- Large:Extended panels accommodate twins and sibling pairs, concentrating demand in United States multi-child households.
- Extra Large:Institutional-scale systems serve daycare common areas and early childhood education facilities with 10+ child capacity requirements.
Medium leads volumes today; large is expanding most quickly.
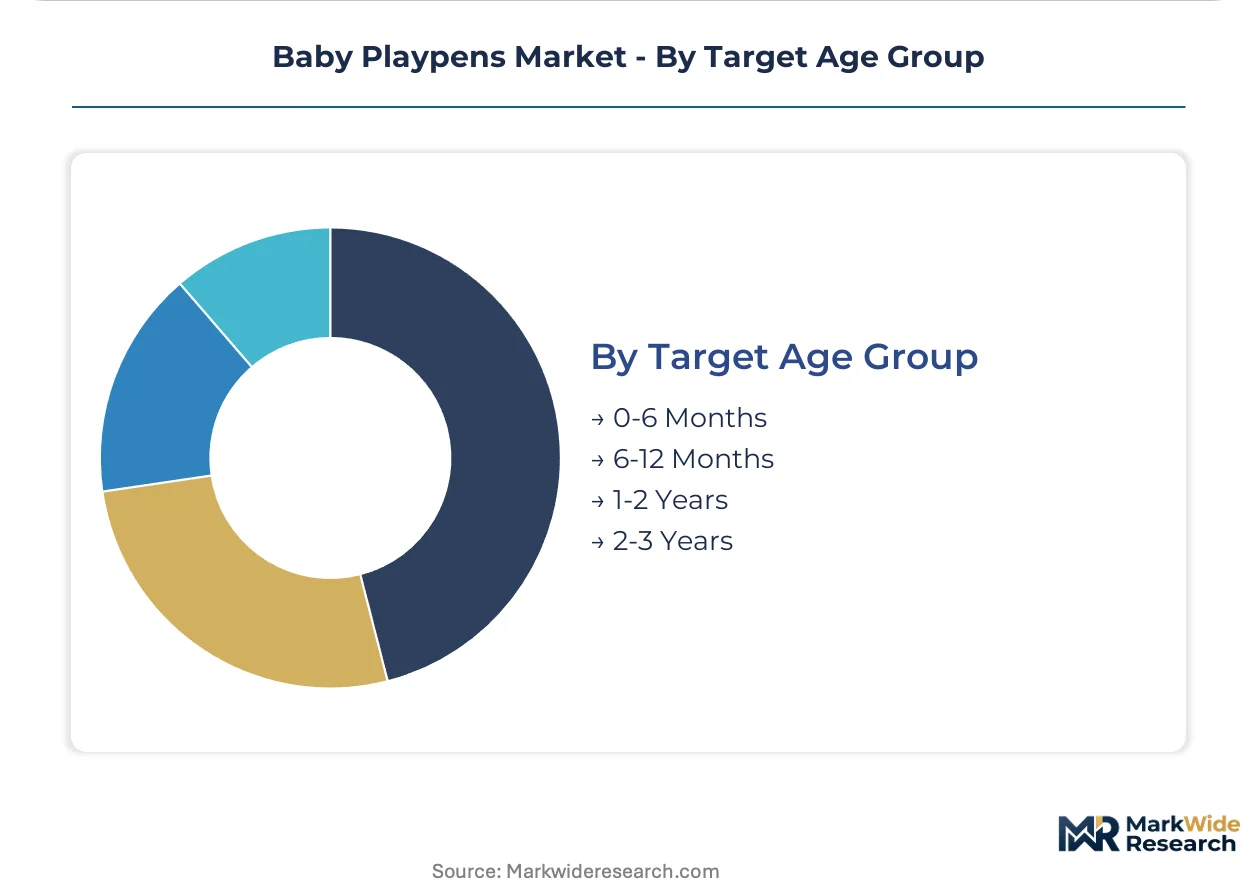
Target Age Group:
Developmental milestones and safety hazards segment buyers by child capability rather than calendar age alone.
- 0-6 Months:Low-profile designs with breathable mesh sides address suffocation risk and limited mobility. Bassinet-integrated playpens concentrate in this bracket.
- 6-12 Months:Pull-to-stand capability demands reinforced top rails and anti-tip bases. CPSC structural integrity testing intensifies for this mobility transition phase.
- 1-2 Years:Active walkers require taller panels and secure latching mechanisms. This bracket generates highest replacement frequency as families upsize from infant configurations.
- 2-3 Years:Climbing attempts necessitate heavier base weights and smooth interior surfaces without foothold protrusions.
6-12 months leads volumes today; 1-2 years is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pearl River Delta manufacturing clusters anchor global playpen production capacity, with Guangdong-Dongguan facilities supplying fabric-over-metal assemblies to export markets. Demand fragmentation across major economies shapes distinct procurement patterns and regulatory compliance requirements.
United States
Daycare procurement concentration and direct-to-consumer channel expansion drive volume. The Consumer Product Safety Commission enforces mandatory entrapment and chemical-content standards through third-party laboratory validation. Domestic distribution networks in North Carolina and Ohio facilitate rapid fulfillment to big-box retail channels.
China
Rising middle-class household spending on infant safety equipment concentrates demand in Tier-1 cities. The State Administration for Market Regulation implements GB standards for juvenile product structural integrity. Manufacturing gravity sits in Dongguan and Shenzhen, where aluminum tubing fabrication and fabric chemical-coating capabilities cluster.
Germany
REACH substance restrictions and Oeko-Tex certification preferences shape premium-tier procurement. The Federal Institute for Risk Assessment monitors phthalate content in textile-contact products. Industrial concentration in Bavaria and Baden-Württemberg supports specialized textile finishing for export-oriented suppliers.
India
Nuclear-family urbanization in Tier-2 cities creates first-time buyer segments without established brand loyalty. The Bureau of Indian Standards maintains voluntary safety benchmarks for portable child containment devices. Mumbai and Delhi-NCR distribution hubs serve emerging retail and e-commerce channels.
United Kingdom
Apartment-dwelling households prioritize foldable configurations for space-constrained nurseries. The Office for Product Safety and Standards enforces the General Product Safety Directive for imported juvenile equipment. Logistics concentration in the Midlands supports parcel-delivery optimization for direct-to-consumer brands.
Baby Playpens Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents extend from core strollers and car seats into adjacent containment categories. The vendor base stratifies across three tiers: multinational juvenile product conglomerates with diversified brand portfolios, Scandinavian design specialists commanding certification premiums, and value-engineered mass-market suppliers competing on fulfillment speed. Two strategic archetypes predominate: integrated manufacturers controlling aluminum tubing and fabric finishing in-house, and brand licensors outsourcing production to Pearl River Delta contract assemblers. Geographic expansion into Indian and Southeast Asian distribution channels and Oeko-Tex certification convergence represent the dominant competitive vectors.
Within the multinational conglomerate tier, Graco and Evenflo exemplify scale-driven positioning through North American retail penetration and mass-market e-commerce fulfillment. BABYBJORN anchors the premium Scandinavian design archetype, leveraging Oeko-Tex certification to command price premiums in direct-to-consumer channels. These three companies represent distinct strategic postures without overlapping target segments.
| Leading Market Players |
|---|
| UPPAbaby |
| Maxi-Cosi |
| 4moms |
| Skip Hop |
| BABYBJORN |
| Graco |
| Bugaboo |
| Dorel Juvenile |
| Evenflo |
| Others |
Supply Flow & Price Mechanics
Daycare procurement concentration in the United States is compressing unit economics toward contract-based volume pricing, while direct-to-consumer channels sustain premium positioning through certification bundling. This buyer bifurcation rewards manufacturers with dual-channel capability and punishes pure-play mass-market suppliers facing aluminum and fabric-coating cost volatility.
Pricing Analysis
Aluminum tubing and certified fabric treatment costs pass through to end prices at divergent rates across channel tiers. Three-tier pricing structure across premium, standard, and economy levels separates Oeko-Tex certified direct-to-consumer offerings from mass-market foldable systems. Price differentiation rests on certification grade and geographic delivery cost, with coastal metropolitan buyers absorbing fulfillment premiums for parcel convenience. Pricing pressure stems from raw material volatility squeezing mid-tier manufacturers without long-term supply contracts. Mass-market e-commerce purchasers exhibit highest price sensitivity, while daycare procurement officers prioritize durability and cleaning-protocol compliance over unit cost.
Supply Chain Analysis
Freight cost optimization is driving aluminum tubing fabrication and fabric chemical-coating consolidation in Dongguan and Shenzhen, with finished assemblies shipping direct-to-consumer via parcel networks. Supply concentrates in China for frame metallurgy and textile finishing, with secondary metalworking in Vietnam and distribution warehousing in the United States. Raw material dependencies draw from aluminum billets, polypropylene resins, and flame-retardant chemical formulations. Single-source vulnerability in Guangdong-Dongguan manufacturing clusters exposes brands to regional power rationing and port congestion. Distribution runs through big-box retail fulfillment centers for mass-market tiers and direct parcel delivery for premium direct-to-consumer brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in baby playpens hinges on aluminum substitution economics and Oeko-Tex certification premiums capturing safety-conscious household spending. Manufacturers controlling both frame fabrication and textile finishing in-house extract differential returns versus outsourced competitors.
For Market Incumbents: Deepen backward integration into aluminum tubing extrusion and fabric chemical-coating to defend against raw material volatility and third-party testing bottlenecks. Consolidate vendor relationships with daycare procurement officers through institutional cleaning-protocol guarantees. Prioritize dual-jurisdiction formulation capabilities to serve divergent United States CPSC and European Union REACH requirements without SKU fragmentation.
For New Entrants and Emerging Players: Social video platform discovery routes offer lowest customer acquisition cost for millennial and Gen-Z first-time parents researching certification marks before purchase. Target India Tier-2 city nuclear families with no existing brand loyalty and price elasticity for portable safety equipment. Deploy subscription rental models for travel-oriented parents to bypass retail markup structures and capture recurring revenue from temporary-use occasions.
For Investors and Strategic Acquirers: Juvenile product conglomerates with diversified brand portfolios are the most active acquirer in this space, seeking adjacent containment category extensions from core strollers and car seats. Acquisition target archetype: integrated manufacturers controlling aluminum tubing and fabric finishing in-house with existing Oeko-Tex certification. Watch for CPSC laboratory validation queue extensions as inflection indicator for working capital strain among seasonal inventory-dependent competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Oeko-Tex Certification Investment | Certification convergence in direct-to-consumer channels rewards early adopters with shelf-space advantages against uncertified competitors. |
| Backward Integration into Aluminum Tubing | In-house extrusion capability insulates margins from commodity price swings and reduces unit shipping weights for parcel fulfillment. |
| Dual-Jurisdiction Production Lines | Segmented assembly by destination geography manages divergent CPSC and REACH chemical restrictions without packaging SKU fragmentation. |
| Direct-to-Consumer Channel Launch | Parcel delivery optimization captures apartment-dwelling millennial buyers prioritizing convenience over big-box retail assembly assistance. |
| Subscription Rental Model Development | Equipment-as-a-service platforms bypass traditional retail markups and generate recurring revenue from travel-oriented temporary-use occasions. |
Methodological Framework
Direct dialogue with product development executives at juvenile goods manufacturers, procurement officers at United States daycare chains, fabric chemical-coating specialists, and logistics directors at Pearl River Delta export facilities grounded qualitative findings. Secondary validation drew from CPSC enforcement databases, REACH substance restriction updates, United States customs import records, and ASTM International voluntary standard revisions. Bottom-up and top-down triangulation reconciled channel-specific volume estimates with aggregate market sizing.
Bottom-up modeling built product-type, material, size, and target age group segmentation across the analysis window, with cross-validation against top-down macroeconomic indicators. CAGRs derived from historical shipment trajectories, channel shift assumptions, and regulatory compliance cost imputation. Forecast inputs incorporated aluminum price volatility scenarios, daycare procurement consolidation rates, and direct-to-consumer adoption curves by metropolitan market density.
The model assumes a particular technology adoption path; alternative pathways for non-toxic flame-retardant fabric chemistry would alter the outlook if REACH restrictions accelerate faster than CPSC mandates. Forecasts reflect documented assumptions about raw material pass-through elasticity and channel mix stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
China Maternity Goods Market
Baby Products
Baby Seat Liners Market
Baby Products
North America Baby Bottle Market
Baby Products
Global Baby Mattresses Market
Baby Products
Baby Nipple/Teat Market
Baby Products
Baby Nose Suckers Market
Baby Products
Baby Feeding Accessories Market
Baby Products
France Baby Care Products Market
Baby Products
Netherlands Baby Care Products Market
Baby Products
Puppy Teething Toys Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Personal Care Products Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Global Baby Play Mats Market
Baby Products
Portable Cribs Market
Baby Products
Global Smart Connected Baby Monitors Market