
 Baby Pacifier Market | 2026-2036
Baby Pacifier Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Pacifier Market Intelligence
Specialty baby retail is rewriting how pacifier brands reach parents. MAM Babyartikel GmbH leverages its German manufacturing base to sustain premium positioning across European pharmacies. Koninklijke Philips N.V. competes through hospital-channel relationships that anchor its Avent line in neonatal units. Pigeon Corporation differentiates via Asian market specialization, particularly in Japanese drugstore networks where it controls shelf placement.
A baby pacifier is a nipple-shaped device, typically molded from medical-grade silicone or natural rubber latex, designed to satisfy an infant's sucking reflex and provide soothing between feedings. Silicone variants dominate volume due to heat resistance and odor neutrality, while orthodontic designs command margin premiums for their dentist-endorsed palate-friendly shapes. Latex retains share in European specialty stores where parents seek biodegradable alternatives. Functional design types lead growth as ergonomic shield shapes and adjustable airflow features address safety concerns.
FDA regulates pacifier material safety and choking-hazard dimensions under 16 CFR Part 1511, while the EU's General Product Safety Directive and EN 1400 standard govern European market access through chemical migration limits and mechanical testing protocols. Compliance with these frameworks shapes R&D spending and determines which suppliers can serve hospital procurement channels. Stakeholders must monitor evolving chemical restriction lists and pediatric dental association guidance to anticipate which material and design combinations will retain channel access.
Market Dynamics
Orthodontic silicone pacifier demand is restructuring competitive positioning as FDA material guidance and pediatric dental association endorsements converge to favor medical-grade polymer designs over conventional latex alternatives.
Growth Catalysts
- 16 CFR Part 1511 compliance:FDA dimensional and material safety standards are expanding hospital procurement eligibility for certified silicone designs, opening neonatal unit channels previously restricted to latex suppliers.
- Heat-resistant polymer technology:Medical-grade silicone variants tolerate repeated sterilization cycles without degradation, satisfying infection-control protocols in clinical settings and premium retail positioning.
- German pharmacy retail concentration:MAM Babyartikel GmbH and European specialty manufacturers leverage established pharmacy distribution to sustain margin premiums through dentist-endorsed orthodontic positioning.
Market Restraints
- Natural rubber latex supply volatility:Hevea brasiliensis plantation yields in Southeast Asia fluctuate with climate patterns, creating input cost instability for biodegradable-focused European specialty producers.
- EN 1400 testing burden:EU chemical migration limits and mechanical testing protocols impose extended certification timelines that exclude smaller manufacturers from pharmacy and hospital channels.
- Silicone raw material concentration:Medical-grade silicone precursor supply clusters among Asian petrochemical processors, creating geographic dependency risk for Western brand owners.
Strategic Opportunities
- Japanese drugstore network expansion:Pigeon Corporation's shelf-placement control demonstrates untapped capacity for Asian-market specialized distribution models in secondary urban centers.
- Adjustable airflow mechanism innovation:Ergonomic shield designs with variable ventilation address suffocation risk concerns while creating patentable differentiation against commodity competitors.
- Biodegradable polymer R&D:Latex alternatives derived from plant-based elastomers could capture European eco-conscious parent segments under EU Green Deal circular-economy incentives.
Industry Challenges
- Pediatric dental certification timelines:Orthodontic design claims require multi-year clinical validation studies with pediatric dentistry associations before marketing authorization.
- Legacy latex manufacturing retooling:Established European producers face capital-intensive equipment conversion to silicone injection molding for FDA-eligible hospital contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Pacifier Market |
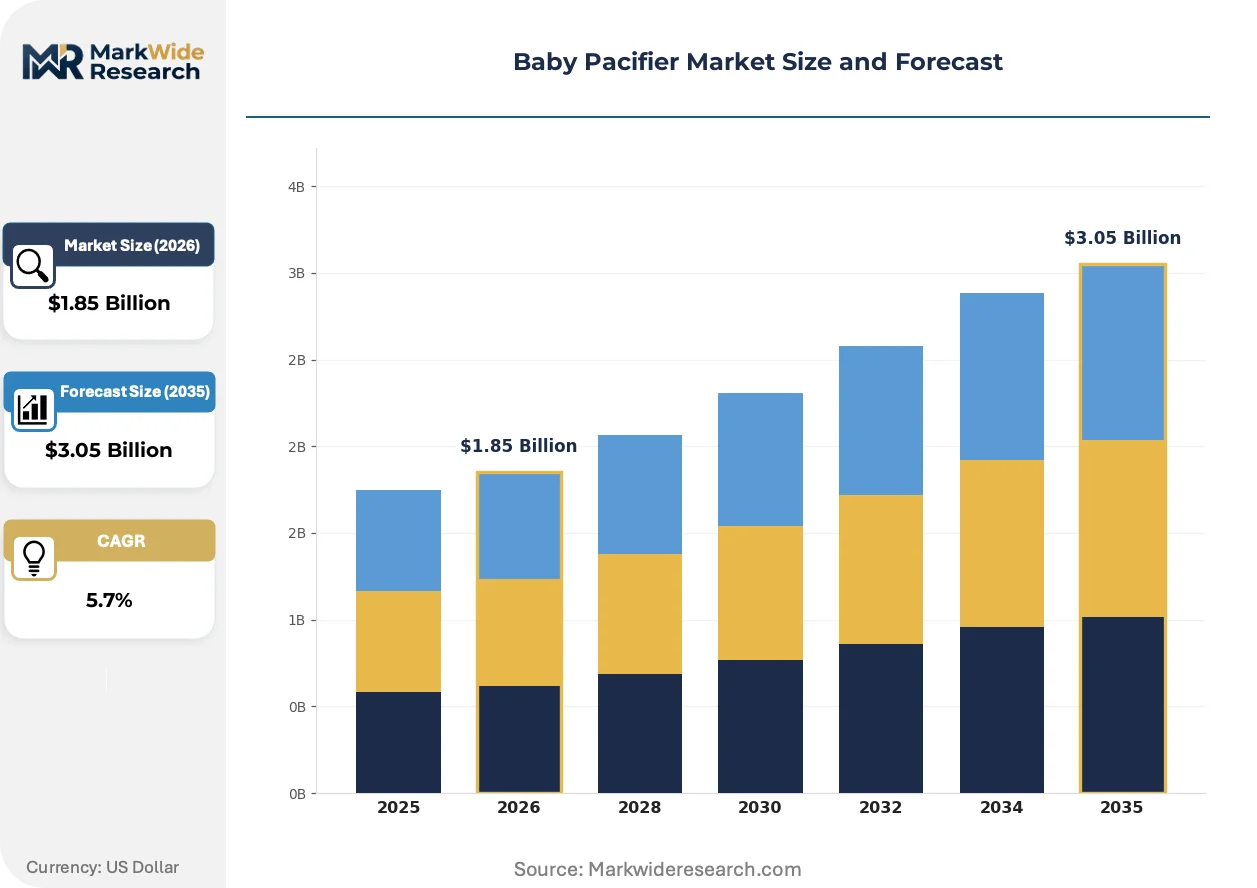
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Latex, Orthodontic, Standard Design Type: Decorative, Functional, Adjustable, Ergonomic Age Group: Newborns, Infants, Toddlers, Preemies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Newell Brands, Natursutten, Koninklijke Philips N.V., The Natural Baby Company, Doddle & Co, MAM Babyartikel GmbH, Baby Shusher LLC, Pigeon Corporation, Mayborn Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Pacifier Market Strategic Shifts & Innovations
Material science convergence with clinical endorsement requirements is redefining product development priorities. Manufacturers now balance polymer performance against regulatory pre-certification investment.
Smart sensor integration for sucking-pattern monitoring is migrating from experimental wearable devices into premium pacifier accessories. Neonatal researchers at university medical centers are piloting pressure-sensitive silicone nipples for early feeding-ability assessment. This technology is migrating from clinical diagnostic equipment into consumer-accessible wellness products, compressing the boundary between medical device and retail baby care.
REACH chemical restriction list expansion is forcing reformulation of plasticizer additives across European supply chains. ECHA substance-of-very-high-concern designations now cover several legacy softening compounds common in shield manufacturing. German and French regulators are accelerating substitution mandates, pushing manufacturers toward bio-based plasticizers ahead of compliance deadlines.
Subscription-based replenishment models are disrupting traditional pharmacy and big-box retail purchase patterns. Direct-to-parent digital platforms now offer orthodontic-size progression programs tied to infant development milestones. This channel innovation concentrates in North American urban markets where parent time scarcity and pediatrician recommendation engines drive platform loyalty.
Baby Pacifier Market Segmentation
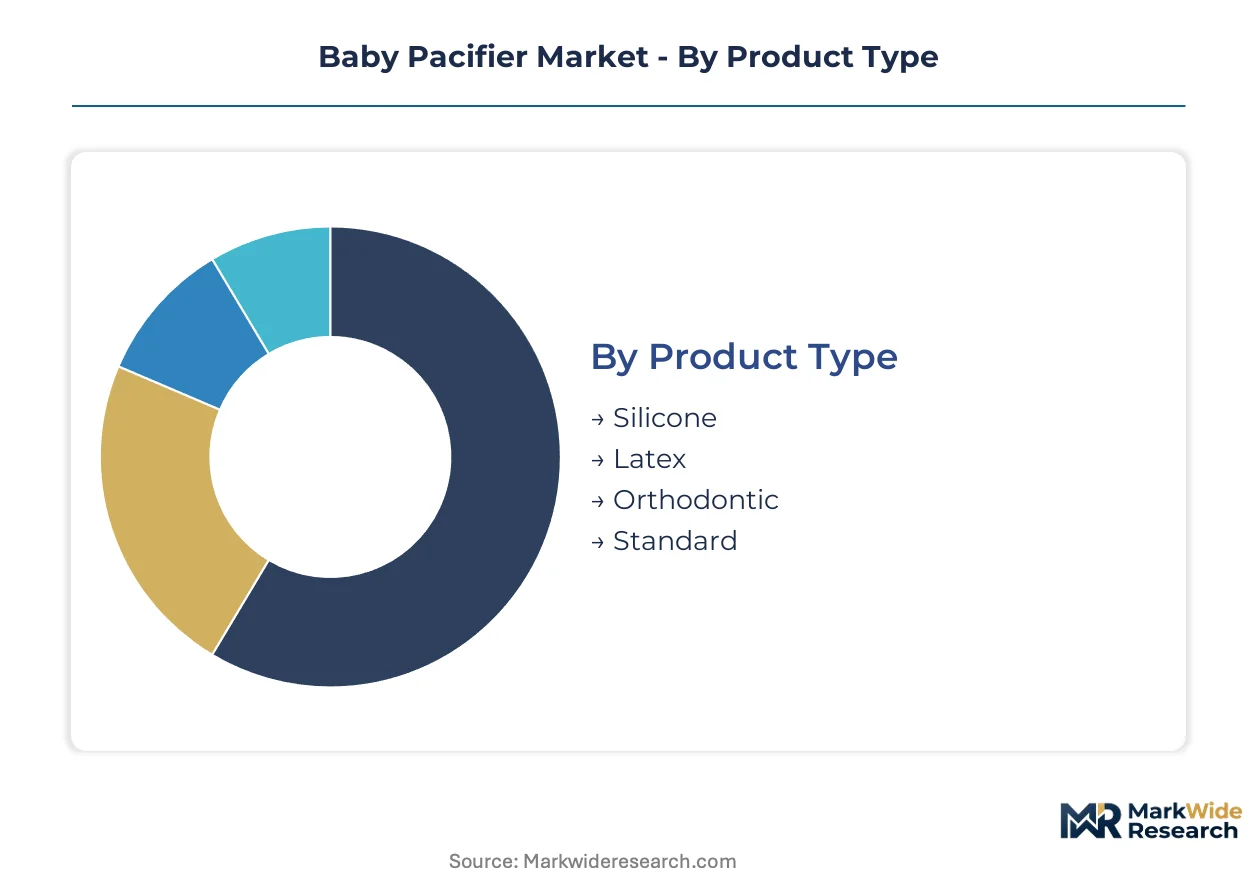
Pacifier segmentation reveals how material science, developmental physiology, and retail channel economics intersect to create distinct value pools. Manufacturers must align product portfolios across four critical dimensions to capture hospital procurement contracts, pharmacy premium positioning, and direct-to-parent digital channels.
Product Type:
Use-case spectrum spans clinical sterilization tolerance to biodegradable disposal preferences, with material properties determining channel eligibility and margin structure.
- Silicone:Medical-grade polymer formulations withstand repeated autoclave cycles without degradation, satisfying infection-control protocols in neonatal units. Heat resistance and odor neutrality drive hospital procurement concentration in the United States, where FDA 16 CFR Part 1511 compliance anchors premium positioning.
- Latex:Natural rubber derived from Hevea brasiliensis plantations offers biodegradability that resonates with European eco-conscious parents. Supply volatility from Southeast Asian climate patterns creates input cost instability, constraining volume expansion despite pharmacy channel loyalty in Germany.
- Orthodontic:Dentist-endorsed palate-friendly shapes command margin premiums through clinical validation claims. Pediatric dental association certifications require multi-year studies, creating barriers to competitive entry.
- Standard:Conventional nipple designs serve price-sensitive mass retail segments with minimal R&D overhead.
The dominant share belongs to Silicone, while Orthodontic is closing the gap fastest.
Design Type:
Cost tier differentiation separates patent-protected innovation from commodity replication, with functional features commanding hospital and pharmacy premiums.
- Functional:Ergonomic shield shapes and adjustable airflow mechanisms address suffocation risk concerns while creating defendable intellectual property. Neonatal researchers pilot pressure-sensitive variants for feeding-ability assessment, compressing boundaries between medical device and retail wellness product.
- Ergonomic:Variable ventilation designs with adjustable airflow mechanisms target safety-conscious parents through demonstrable risk reduction. Patentable differentiation shields margins against commodity competitors in saturated retail environments.
- Decorative:Aesthetic customization drives gift-market purchases and social media shareability without functional premium.
- Adjustable:Modular sizing systems accommodate infant development progression, supporting subscription replenishment models.
Functional designs capture the steepest expansion trajectory as clinical endorsement requirements reshape R&D priorities.
Age Group:
Application specificity determines nipple flow rates, shield dimensions, and safety testing protocols across developmental stages.
- Newborns:Smallest shield sizes and slowest flow rates serve hospital discharge kits and first-time parent purchases. Preemie-adjacent sizing overlaps with neonatal intensive care requirements.
- Infants:Mid-range dimensions dominate volume as parents establish soothing routines between feedings.
- Toddlers:Larger shields and orthodontic pressure distribution address extended use concerns raised by pediatric dental guidelines.
- Preemies:Specialized dimensions for low-birth-weight infants require dedicated manufacturing lines and clinical validation studies.
Infant-stage products hold the dominant share, while Toddler-focused orthodontic designs are gaining share fastest.
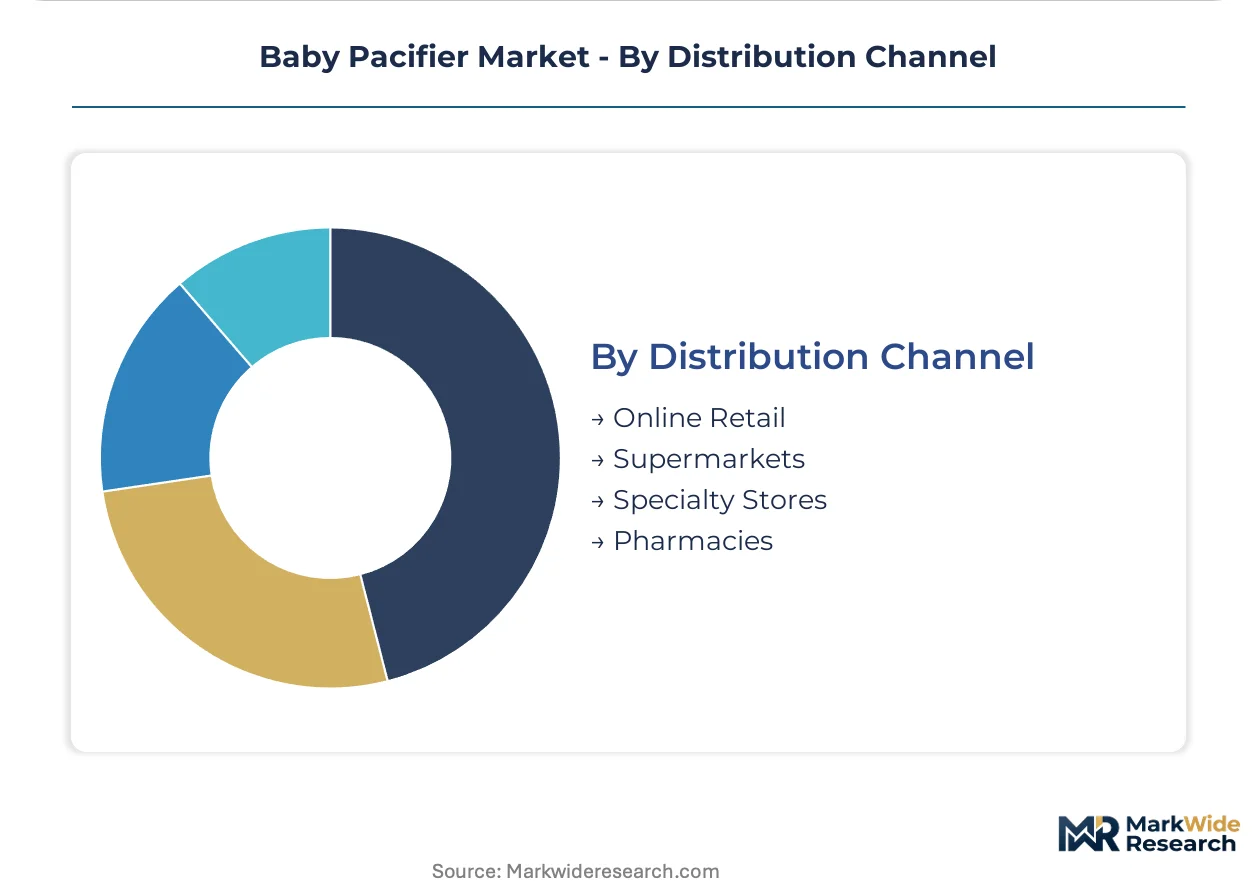
Distribution Channel:
Customer type and geography concentration determine margin capture, with pharmacy and hospital channels sustaining premium positioning against mass retail erosion.
- Pharmacies:German and French pharmacy networks anchor MAM Babyartikel GmbH's premium positioning through dentist-endorsed displays and trained staff recommendations. EU Green Deal circular-economy incentives accelerate bio-based plasticizer substitution mandates.
- Specialty Stores:Curated assortments with clinical endorsement signage support orthodontic premium pricing in urban centers.
- Online Retail:Direct-to-parent platforms with subscription-based replenishment models disrupt traditional purchase patterns in North American metropolitan markets.
- Supermarkets:Price-competitive mass retail concentrates standard-design volume with thin margins.
Pharmacies retain the dominant share, while Online Retail is expanding most quickly through pediatrician recommendation engines and milestone-tied replenishment programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA material guidance and EU Green Deal circular-economy incentives are redirecting procurement patterns toward certified silicone designs across hospital and pharmacy channels.
United States
Hospital discharge kits and neonatal unit procurement anchor silicone pacifier volume as infection-control protocols favor heat-resistant medical-grade polymers. FDA 16 CFR Part 1511 compliance requirements filter supplier eligibility for clinical channels. Boston and Minneapolis medical device clusters concentrate manufacturing partnerships with pediatric dental researchers.
Germany
Pharmacy network loyalty sustains premium positioning for orthodontic designs endorsed by pediatric dentistry associations. EU REACH chemical migration limits and EN 1400 mechanical testing standards shape R&D investment priorities. Bavaria's specialty manufacturing base supports MAM Babyartikel GmbH's dentist-recommended product lines through trained pharmacy staff.
Japan
Drugstore network shelf-placement control drives brand concentration in urban centers where parent time scarcity favors trusted recommendations. METI product safety standards and PMDA medical device classifications influence material selection for clinical-adjacent retail positioning. Tokyo and Osaka metropolitan areas concentrate premium pacifier distribution through established pharmacy chains.
China
Domestic manufacturing scale supports both export supply and emerging middle-class retail demand for orthodontic silicone variants. NMPA medical device registration requirements and GB standards for infant products determine import eligibility for foreign brands. Yangtze River Delta petrochemical processors supply medical-grade silicone precursors to Western brand owners.
France
ANSM pharmaceutical product oversight and ECHA substance-of-very-high-concern designations accelerate bio-based plasticizer substitution in shield manufacturing. Paris and Lyon pharmacy networks maintain curated assortments with clinical endorsement signage. EU Green Deal incentives push manufacturers toward biodegradable alternatives ahead of compliance deadlines.
Baby Pacifier Market Key Industry Players
On the supply side, the industry is structured around three distinct tiers: hospital-procurement specialists, pharmacy-premium incumbents, and mass-retail commodity suppliers. Strategic archetypes include clinical-channel anchors leveraging neonatal unit relationships, European pharmacy-network defenders with dentist endorsement positioning, and Asian-market specialists controlling drugstore shelf placement. Dominant competitive moves center on backward integration into medical-grade silicone supply and geographic licensing partnerships to bypass regulatory certification timelines.
Among the named participants, Koninklijke Philips N.V. and MAM Babyartikel GmbH occupy positions as archetype anchors for hospital and pharmacy channels respectively, while Pigeon Corporation exemplifies Asian-market specialization through drugstore network control.
| Leading Market Players |
|---|
| Newell Brands |
| Natursutten |
| Koninklijke Philips N.V. |
| The Natural Baby Company |
| Doddle & Co |
| MAM Babyartikel GmbH |
| Baby Shusher LLC |
| Pigeon Corporation |
| Mayborn Group Limited |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta petrochemical clusters anchor medical-grade silicone precursor capacity, translating upstream concentration into asymmetric pricing power for orthodontic-certified designs against commodity latex alternatives.
Pricing Analysis
Certification level (FDA-grade vs. EN 1400-compliant vs. uncertified) creates the primary spread between hospital-procurement premiums and mass-retail commodities. Three-tier pricing structure separates neonatal-unit silicone from pharmacy-channel orthodontic and supermarket standard designs. Cost compression in latex tiers intensifies because Hevea brasiliensis supply volatility from Southeast Asian climate patterns. Hospital procurement committees demonstrate lowest price sensitivity; mass-retail parents in emerging markets show highest.
Supply Chain Analysis
Contract-manufacturing concentration rests with German specialty molders (MAM Babyartikel GmbH captive operations), Chinese medical-device EMS providers, and Japanese precision polymer processors. Raw material dependencies center on medical-grade silicone precursors from Zhejiang petrochemical complexes, natural rubber latex from Thai and Indonesian plantations, and bio-based plasticizers under EU Green Deal substitution mandates. Single-source vulnerability concentrates in Asian silicone precursor supply. Distribution runs through pharmacy networks in Germany, hospital procurement in the United States, and drugstore chains in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment programs for orthodontic-size progression represent the fastest-expanding recurring-revenue layer, outpacing hardware unit growth in North American metropolitan markets.
For Market Incumbents: Build certification moats through multi-year pediatric dental association clinical validation studies that lock hospital and pharmacy channel access. Deepen backward integration into medical-grade silicone precursor supply to insulate margin from Asian petrochemical price volatility. Defend against direct-to-parent digital platforms by anchoring Avent-line relationships in neonatal discharge kit protocols. For New Entrants and Emerging Players: Mid-market orthodontic designs without legacy latex manufacturing retooling burdens represent the most penetrable entry point for FDA-compliant hospital contracts. Secondary urban Japanese drugstore networks offer shelf-placement opportunities where Pigeon Corporation concentration leaves gaps. Pursue geographic licensing partnerships to bypass EN 1400 certification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-parent platforms with pediatrician recommendation engines and milestone-tied replenishment programs. Long-term viability favors acquisition targets with pharmacy-network control in EU markets facing REACH chemical restriction acceleration. Monitor ECHA substance-of-very-high-concern designation velocity for inflection signals in shield manufacturing reformulation costs. Quarterly review of certification backlog lengths and raw material substitution timelines is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Multi-year pediatric dental association studies lock hospital procurement eligibility against commodity competitors. |
| Backward Integration into Silicone Precursors | Captive supply from Yangtze River Delta processors insulates margin from Asian petrochemical concentration risk. |
| Subscription Platform Launch | Milestone-tied replenishment models concentrate parent loyalty in time-scarce North American metropolitan markets. |
| Biodegradable Polymer R&D | Plant-based elastomer development captures EU Green Deal circular-economy incentives ahead of compliance deadlines. |
| Pharmacy Network Expansion | Trained staff recommendations in German and French channels sustain premium positioning against mass retail erosion. |
Research Approach
Operator-level perspectives from neonatal unit procurement managers, pharmacy category buyers, pediatric dental researchers, and medical-device regulatory affairs leads anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) filings, EN 1400 certification databases, hospital GPO contract disclosures, and EU REACH substance restriction lists. Bottom-up unit economics across material-grade tiers reconciled with top-down category spending estimates from pharmacy and drugstore retail audit data.
Scenario-bracketing around silicone supply disruption, latex climate volatility, and regulatory acceleration shaped projection ranges across the analysis window. Segmentation dimensions modeled include material type, design functionality, age-group specificity, and distribution channel economics. CAGRs derived from infant birth-rate trajectories, orthodontic endorsement penetration curves, and channel-shift elasticity parameters. Forecast inputs incorporated REACH chemical restriction velocity and pediatric dental certification backlog lengths.
Practitioners should monitor ECHA substance-of-very-high-concern designation announcements, Southeast Asian Hevea brasiliensis yield reports, and FDA guidance updates on material safety for early signals. Forecasts reflect assumptions on certification timeline stability and raw material substitution feasibility. Quarterly review of hospital procurement contract renewal rates and direct-to-parent platform subscriber retention is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Asia-Pacific Baby Care Products Market
Baby Products
Postpartum Products Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Cradles Market
Baby Products
Crib Mattress Market
Baby Products
Baby Nose Suckers Market
Baby Products
Baby Care and Mother Care Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
France Baby Care Products Market
Baby Products
Feeding Bra Market
Baby Products
Tissue and Hygiene Market
Baby Products
Baby Bottle Market
Baby Products
Baby Gift Basket Market
Baby Products
India Baby Care Products Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Portable Cribs Market