
 Global Baby Pajamas and Sleepwears Market | 2026-2036
Global Baby Pajamas and Sleepwears Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baby Pajamas and Sleepwears Market Analysis
The baby pajamas and sleepwears category is restructuring around a widening gap between certified organic premium lines and price-driven commodity basics. Carter's, Inc. leverages its vertical manufacturing network to dominate North American shelf space and e-commerce fulfillment. The Gap, Inc. anchors its position through integrated baby-to-toddler sizing architectures that reduce customer churn. H&M Group competes on speed-to-market with trend-responsive micro-collections that refresh sleepwear assortments monthly.
Baby pajamas and sleepwears encompass fitted and loose garments engineered for infant thermoregulation, constructed from flame-resistant or snug-fitting natural and synthetic textiles meeting specific TOG warmth ratings and breathability thresholds. Cotton-dominant sleepsuits retain the largest volume share due to parental familiarity and laundering durability, though bamboo-derived fabrics are capturing margin-rich premium positioning through moisture-wicking and hypoallergenic performance claims. Online retail channels are accelerating fastest among distribution pathways, as direct-to-consumer platforms bypass wholesale markups and capture first-party data on sizing and repeat purchase cycles.
Regulatory frameworks including the US Consumer Product Safety Commission's flammability standards, the EU's REACH chemical restrictions, and OEKO-TEX certification protocols collectively elevate compliance costs while filtering out informal suppliers. These standards reshape procurement decisions by mandating third-party testing for phthalates, flame retardants, and fiber content disclosures across export-bound production. Stakeholders must monitor evolving chemical ban lists and sizing standardization movements to anticipate which manufacturing bases will retain market access versus face exclusion.
Market Dynamics
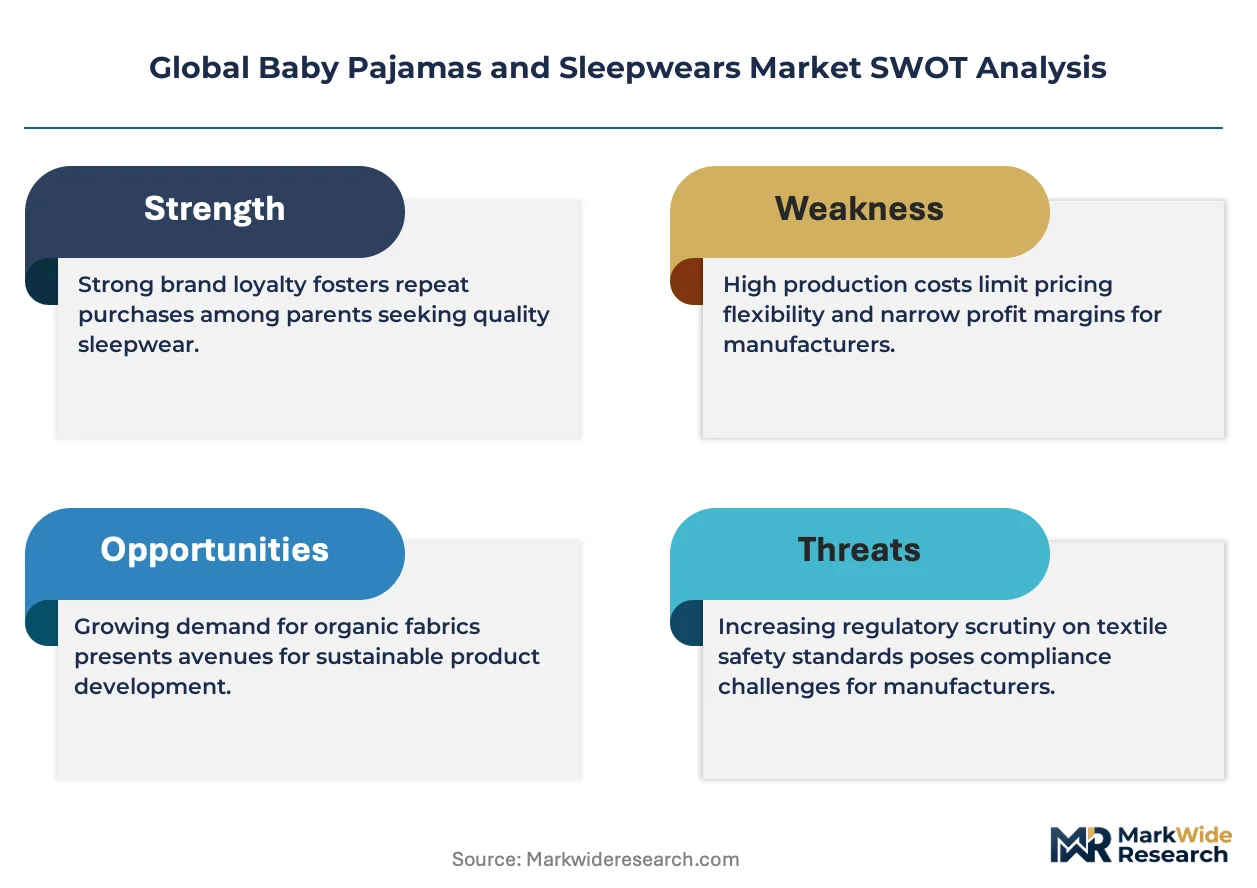
The baby pajamas and sleepwears market is bifurcating around thermoregulation certification and chemical compliance, with REACH and OEKO-TEX standards forcing suppliers to choose between premium positioning and exit. This regulatory compression is accelerating consolidation among vertically integrated manufacturers while fragmenting commodity production across informal clusters.
Growth Catalysts
- REACH chemical restrictions:The EU's phased bans on azo dyes and formaldehyde-based finishes are redirecting procurement toward certified organic cotton suppliers in Turkey and Portugal, creating first-mover advantages for compliant manufacturers.
- Bamboo viscose processing:Closed-loop lyocell production methods are reducing water intensity by half versus conventional viscose, attracting sustainability-focused millennial buyers in Germany and the Netherlands.
- Direct-to-consumer platforms:First-party data capture on sizing accuracy and repeat purchase cycles is enabling subscription-based replenishment models that lock in lifetime value across the zero-to-twenty-four-month segment.
Market Restraints
- Organic cotton fiber premiums:GOTS-certified cotton commands forty to sixty percent price premiums over conventional grades, compressing margins for mid-tier brands unable to pass through costs.
- Concentrated flame-retardant chemistry:Decabromodiphenyl ether supply chains cluster in China's Shandong province, creating single-point vulnerability for US-bound sleepwear meeting CPSC flammability standards.
- TOG rating standardization gaps:Inconsistent thermal resistance testing methodologies between AATCC and ISO protocols force dual certification costs for exporters serving both North American and European markets.
Strategic Opportunities
- India's organized retail expansion:Reliance Retail and DMart are building dedicated baby apparel sections in tier-two cities, creating shelf space for labeled sleepwear brands displacing unbranded local production.
- Smart textile integration:Phase-change material microencapsulation is converging with NFC-enabled care label authentication, opening premium positioning for temperature-monitoring infant garments.
- Brazil's import tariff rationalization:The country's textile sector tax exemptions under the Reintegra program are reducing landed costs for certified organic sleepwear entering through São Paulo's free trade zones.
Industry Challenges
- GOTS certification timelines:The eighteen-to-twenty-four-month farm-to-factory traceability audit cycle delays product launches and ties up working capital in pre-certified inventory.
- Legacy ERP integration:Small-batch sustainable manufacturers struggle to connect Shopify Plus storefronts with existing SAP installations, creating order-fulfillment bottlenecks during demand spikes.
- Size grading standardization:Discrepancies between ASTM D6860 US sizing and EN 13402 European measurements force duplicate pattern development for cross-border assortments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baby Pajamas and Sleepwears Market |
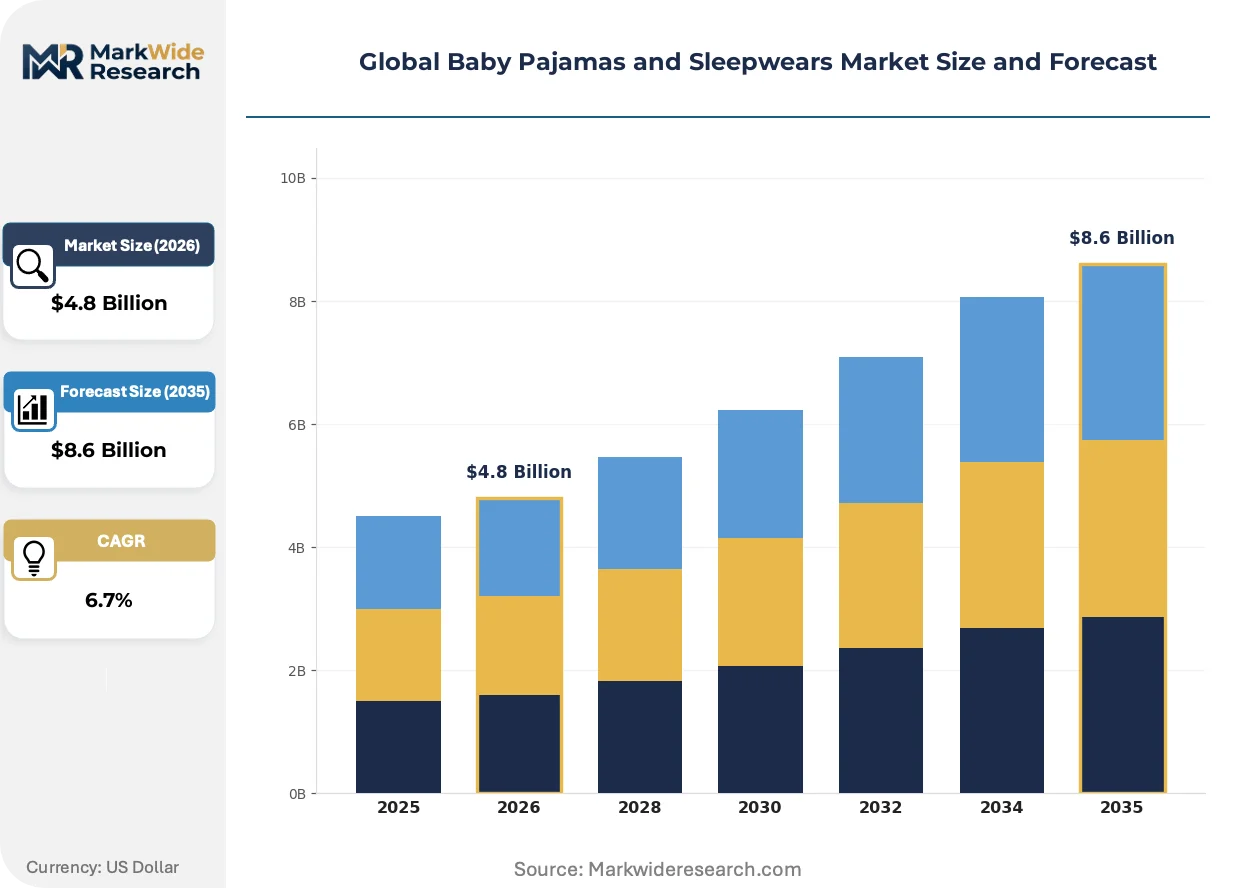
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pajamas, Sleepsuits, Gowns, Sleep Bags Material: Cotton, Polyester, Bamboo, Fleece Age Group: Infants, Toddlers, Newborns, Preschoolers Distribution Channel: Online Retail, Department Stores, Specialty Stores, Discount Stores |
| Companies Covered | Carter's, Inc., The Gap, Inc., H&M Group, PVH Corporation, Inditex S.A., The Children's Place, Inc., Nike, Inc., The Walt Disney Company, Under Armour, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baby Pajamas and Sleepwears Market Emerging Trajectories
Material science and distribution architecture are reshaping competitive positioning in infant sleepwear. Three developments are compressing traditional lead times while elevating performance claims around safety and comfort.
Phase-change material microencapsulation is modularizing thermal management in infant garments. Outlast Technologies' licensed paraffin-wax beads absorb excess body heat during sleep onset and release it during temperature drops. Premium brands in Scandinavia and Japan are adopting this for newborn collections priced at triple standard cotton equivalents. The technology is modularizing the traditional layered-sleepwear category into single-garment solutions that reduce parental purchase frequency.
ECHA's 2023 restriction proposal on per- and polyfluoroalkyl substances is forcing reformulation of water-repellent finishes across EU-bound production. Industrial laundries in Portugal and Romania are phasing out C6 fluorocarbon treatments in favor of bio-based wax emulsions. Sleepwear exporters to Germany and France face retesting costs exceeding fifteen thousand euros per SKU, with smaller suppliers consolidating compliance through shared laboratory consortia.
Subscription replenishment models are displacing episodic gifting as the dominant purchase occasion. First-time parents in urban China and South Korea are enrolling in twelve-month sizing-progression programs that auto-ship three-month size increments. This behavioral shift concentrates demand forecasting accuracy with platform operators, compressing wholesale margins for traditional department store buyers in Shanghai and Seoul.
Global Baby Pajamas and Sleepwears Market Segmentation
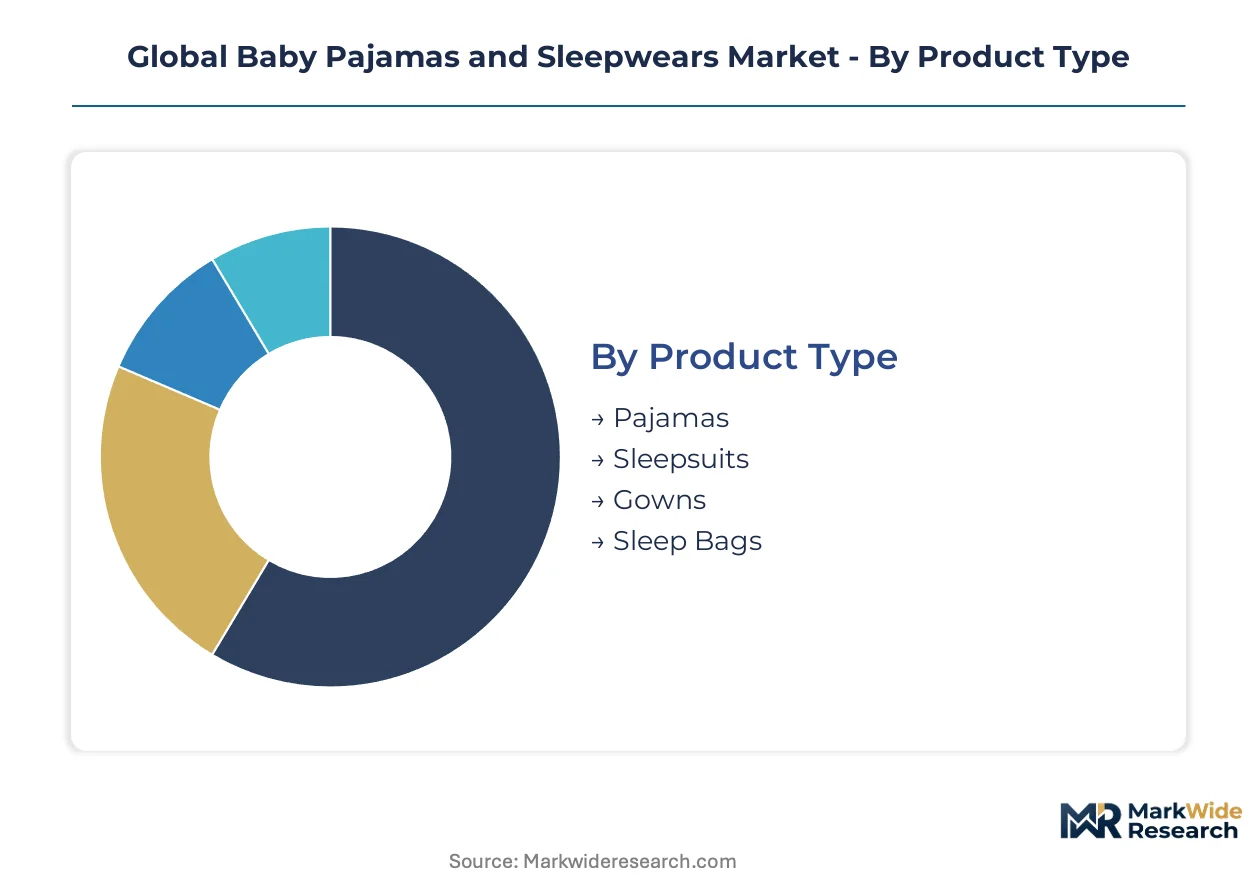
Segmentation in infant sleepwear reveals how thermoregulation requirements, chemical compliance tiers, and channel economics partition demand across distinct purchasing behaviors. Material certifications and sizing architectures determine margin capture, while distribution pathways separate subscription-driven replenishment from episodic gifting occasions.
Product Type:
Garment engineering specifications define the thermoregulation-performance axis, with TOG ratings and flame-resistance standards segmenting the category into distinct functional tiers.
- Sleepsuits:One-piece fitted garments dominate volume through integrated foot coverage and snap closures that simplify nighttime diaper changes. Cotton-dominant constructions meeting CPSC snug-fit standards capture the largest installed base in the United States, though European demand is shifting toward GOTS-certified organic variants as ECHA restrictions on formaldehyde-based finishes tighten.
- Sleep Bags:Sleeveless wearable blankets eliminate loose bedding hazards while standardizing thermal resistance across the zero-to-twenty-four-month segment. Scandinavian and Japanese parents pay triple cotton-equivalent prices for Outlast phase-change material microencapsulation that modulates infant body temperature through paraffin-wax bead technology.
- Pajamas:Two-piece separates accommodate toddler mobility and toilet-training transitions, with elasticized waistbands and tagless constructions reducing sensory irritation.
- Gowns:Open-bottom designs facilitate umbilical-cord healing in the first weeks of life, concentrated in hospital gift-shop and registry channels.
Sleepsuits lead on scale; sleep bags lead on momentum.
Material:
Fiber chemistry and processing certifications stratify procurement costs and end-market access, with REACH and OEKO-TEX compliance filtering supplier participation.
- Cotton:Conventional and organic grades retain the largest volume share due to parental laundering familiarity and durability through repeated washing cycles. GOTS-certified cotton commands forty-to-sixty percent premiums over conventional grades, compressing mid-tier brand margins.
- Bamboo:Viscose and lyocell processing variants are expanding most quickly through moisture-wicking and hypoallergenic performance claims. Closed-loop lyocell methods reduce water intensity by half versus conventional viscose, attracting millennial buyers in Germany and the Netherlands.
- Polyester:Flame-resistant inherent fibers meet US CPSC flammability standards without chemical treatments, though microplastic shedding concerns limit European adoption.
- Fleece:Synthetic pile constructions provide lightweight warmth for winter layering, concentrated in discount-store seasonal assortments.
Cotton leads on scale; bamboo leads on momentum.
Age Group:
Physiological development stages determine sizing standardization, safety regulation applicability, and purchase frequency cadence.
- Infants:The zero-to-twelve-month segment concentrates the strictest flammability and chemical compliance requirements, with TOG-rated thermal management driving premium positioning. Subscription replenishment models auto-shipping three-month size increments are displacing episodic gifting in urban China and South Korea.
- Toddlers:Twelve-to-thirty-six-month sizing accommodates mobility transitions and toilet-training needs, with two-piece pajama separates gaining share.
- Newborns:First-month sizing emphasizes umbilical-cord accommodation and swaddle-compatible designs, concentrated in hospital discharge and registry channels.
- Preschoolers:Two-to-five-year sizing overlaps with children's sleepwear categories, with character licensing and seasonal patterns driving purchase decisions.
Infants lead on scale; toddlers lead on momentum.
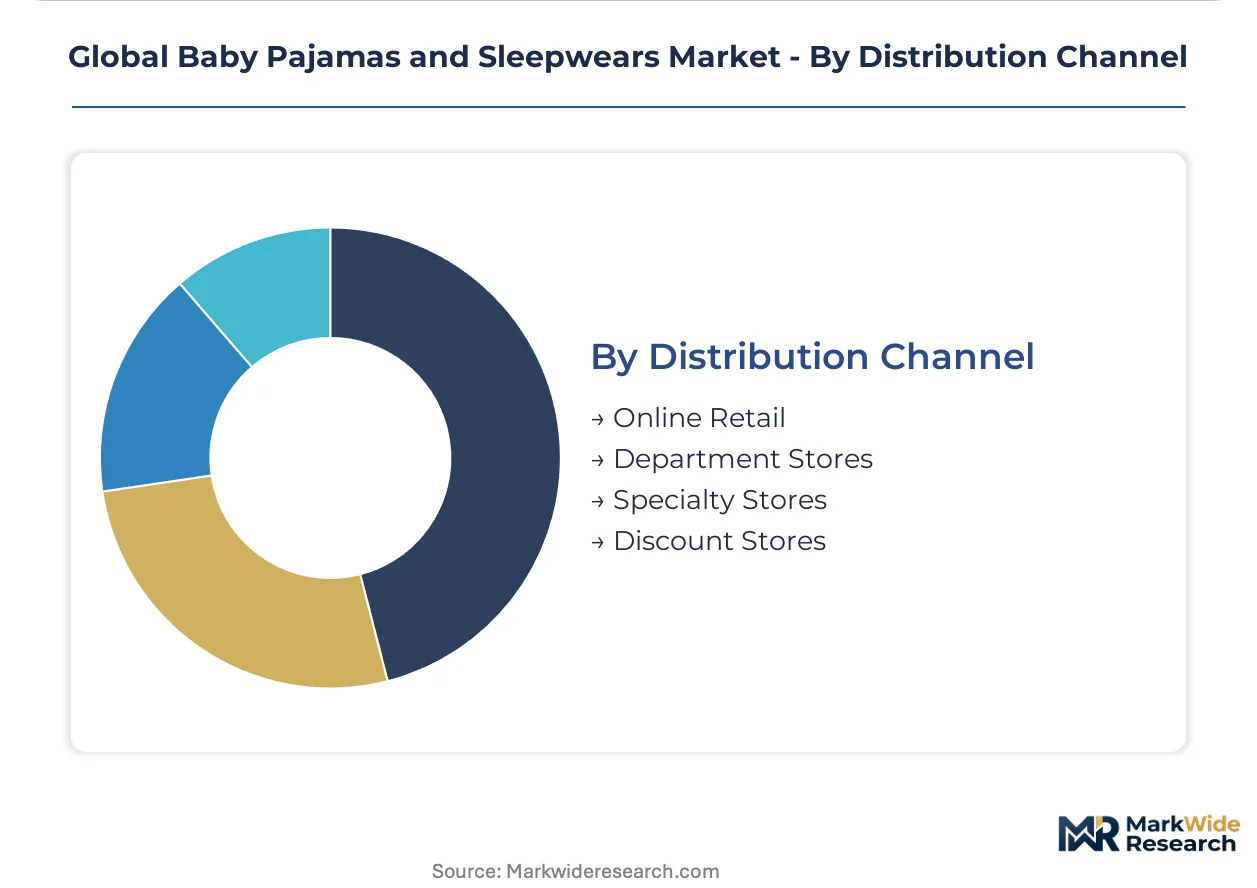
Distribution Channel:
Channel economics separate first-party data capture from wholesale margin structures, with fulfillment speed and sizing accuracy determining customer retention.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups while capturing sizing and repeat-purchase cycle data. Shopify Plus storefronts integrated with ERP systems enable subscription-based replenishment models that lock in lifetime value.
- Specialty Stores:Curated assortments with certified organic positioning and fitting services command premium pricing in urban Germany, France, and Japan.
- Department Stores:Integrated baby-to-toddler sizing architectures reduce customer churn through registry continuity, though wholesale margins are compressing as platform operators concentrate demand forecasting accuracy.
- Discount Stores:Price-driven commodity basics serve budget-conscious segments, with private-label sourcing from Turkey and Bangladesh displacing informal local production.
Online retail leads on scale; specialty stores lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial parent talent clusters in Shanghai, Munich, and São Paulo anchor demand forecasting for premium infant sleepwear, while compliance specialists concentrate in Brussels and Washington DC to navigate tightening chemical regulations.
United States
Subscription replenishment models auto-shipping three-month size increments are displacing episodic gifting among urban first-time parents. The US Consumer Product Safety Commission enforces flammability standards that mandate snug-fit specifications or flame-resistant treatments. Carter's vertical manufacturing network dominates North American shelf space from its Atlanta headquarters and e-commerce fulfillment centers.
Germany
Millennial buyers in Berlin and Munich pay triple cotton-equivalent prices for Outlast phase-change material microencapsulation in newborn collections. ECHA's 2023 restriction proposal on per- and polyfluoroalkyl substances forces reformulation of water-repellent finishes, with industrial laundries in Portugal and Romania phasing out C6 fluorocarbon treatments. Specialty stores in Hamburg and Frankfurt command premium pricing through certified organic positioning and fitting services.
China
Middle-class households in Shanghai and Shenzhen upgrade from unbranded to labeled baby apparel, concentrating demand in tier-one and tier-two cities. SAMR and GB standards govern textile safety and fiber content disclosures for domestic consumption and export production. Direct-to-consumer platforms in Hangzhou and Shenzhen bypass wholesale markups while capturing first-party data on sizing accuracy.
India
Reliance Retail and DMart build dedicated baby apparel sections in tier-two cities, creating shelf space for labeled sleepwear brands. BIS certification requirements and DGFT import regulations shape procurement decisions for export-bound production. Textile clusters in Tiruppur and Ludhiana pivot from commodity basics to GOTS-certified organic cotton to access European markets.
Brazil
Import tariff rationalization under the Reintegra program reduces landed costs for certified organic sleepwear entering through São Paulo's free trade zones. ANVISA governs chemical safety in infant textiles alongside Mercosur technical regulations. Middle-class parents in São Paulo and Rio de Janeiro shift from informal local production to branded sleepwear as organized retail expands.
Global Baby Pajamas and Sleepwears Market Vendor Landscape
Top-tier vendors anchor premium organic and mass-market segments, while mid-tier specialists and private-label suppliers compete on speed-to-market and compliance certification. The market structure favors vertically integrated manufacturers with captive supply chains over fragmented commodity assemblers. Three archetypes dominate: multinational apparel conglomerates with baby-to-toddler sizing architectures, fast-fashion platforms with monthly micro-collection refreshes, and sustainability-focused direct-to-consumer brands. Consolidation accelerates through strategic partnerships for shared laboratory compliance and capacity expansion in certified organic cotton processing.
Among North American-headquartered retailers, Carter's, Inc. and The Children's Place, Inc. represent scale-driven archetypes with integrated manufacturing networks, while Stockholm-based H&M Group exemplifies speed-to-market positioning through trend-responsive assortment architectures.
| Leading Market Players |
|---|
| Carter's, Inc. |
| The Gap, Inc. |
| H&M Group |
| PVH Corporation |
| Inditex S.A. |
| The Children's Place, Inc. |
| Nike, Inc. |
| The Walt Disney Company |
| Under Armour, Inc. |
| Others |
Supply Flow & Price Mechanics
Millennial and Gen Z procurement preferences for GOTS-certified organic cotton are forcing suppliers to absorb forty-to-sixty percent fiber premiums or exit the mid-tier, compressing margins and accelerating consolidation among vertically integrated manufacturers with captive Turkish and Portuguese spinning capacity.
Pricing Analysis
Bundled subscription replenishment services separate from unbundled transactional gifting purchases across the zero-to-twenty-four-month segment. Three-tier pricing structure across premium Outlast phase-change collections, standard GOTS-certified organic lines, and economy conventional cotton basics differentiates by certification grade and thermoregulation performance. Pricing pressure stems from ECHA chemical restrictions forcing fifteen-thousand-euro-per-SKU retesting costs onto EU-bound exporters. Discount-store buyers exhibit highest price sensitivity; Scandinavian specialty-store purchasers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with decabromodiphenyl ether flame-retardant chemistry clustered in China's Shandong province for US CPSC-compliant sleepwear. Finished garment assembly concentrates in Bangladesh, Vietnam, and India; organic cotton fiber draws from Turkey and Portugal. Tariff exposure runs through Brazil's Reintegra program rationalization and potential Mercosur adjustments. Distribution runs through direct-to-consumer platforms capturing first-party sizing data alongside traditional wholesale department-store and specialty-store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as millennial parents in Shanghai, Munich, and São Paulo upgrade from unbranded to certified organic labeled sleepwear with full chemical traceability.
For Market Incumbents: To counter subscription-platform disintermediation, Carter's and The Gap should deepen backward integration into GOTS-certified organic cotton processing in Turkey and Portugal while locking hospital-discharge registry channels through integrated baby-to-toddler sizing architectures that reduce churn. For New Entrants and Emerging Players: Launch via direct-to-consumer Shopify Plus storefronts with closed-loop lyocell bamboo processing narratives targeting millennial buyers in Germany and the Netherlands, white-space opportunities exist in India's tier-two cities where Reliance Retail and DMart are expanding dedicated baby apparel sections. For Investors and Strategic Acquirers: Asymmetric upside sits with sustainability-focused direct-to-consumer brands possessing captive GOTS certification and ERP-integrated fulfillment systems; long-term viability favors acquirers of compliant mid-tier manufacturers facing working-capital strain from eighteen-to-twenty-four-month farm-to-factory traceability audit cycles. Watch ECHA's evolving PFAS restriction implementation as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Investment | Eighteen-to-twenty-four-month traceability audits lock in European market access against REACH chemical restrictions. |
| Direct-to-Consumer Platform Launch | Shopify Plus storefronts capture first-party sizing data enabling subscription replenishment models in urban China. |
| Backward Integration into Organic Cotton | Captive Turkish and Portuguese spinning capacity insulates against forty-to-sixty percent fiber premium volatility. |
| Phase-Change Material Licensing | Outlast Technologies partnerships command triple cotton-equivalent pricing in Scandinavian and Japanese newborn collections. |
| Hospital Registry Channel Expansion | Discharge gift-shop placement locks in lifetime value through integrated sizing progression architectures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at Reliance Retail and DMart, supply planners at vertically integrated manufacturers, and sustainability certification auditors with secondary validation against customs records, OEKO-TEX and GOTS certification databases, and SEC 10-K filings from publicly traded apparel conglomerates. Bottom-up SKU-level demand modeling and top-down macroeconomic anchoring provided triangulation.
Comparable-period anchoring tied projection assumptions to historical reference periods across the analysis window. Segmentation dimensions modeled included product type, material certification tier, age group physiology stage, and distribution channel economics. CAGRs derived from regression-based growth rate calibration incorporating TOG rating standardization gaps, chemical compliance timeline delays, and subscription-model adoption curves as infant sleepwear-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA PFAS restriction acceleration or CPSC flammability standard revision. Forecasts reflect documented assumptions on millennial premium-upgrade propensity and organic cotton fiber premium persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Nose Suckers Market
Baby Products
Italy Baby Care Products Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Global Baby Play Mats Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Mexico Baby Care Products Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby Powder Market
Baby Products
Baby Playpens Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Baby Bouncers Market
Baby Products
Baby Walker Market
Baby Products
Baby Pacifier Market
Baby Products
Baby Shoes Market