
 Home Care Packaging Market | 2026-2036
Home Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Home Care Packaging Market Intelligence
Asset-light leasing models for filling equipment is fragmenting competitive entry barriers in home care packaging. Amcor plc leverages its global film manufacturing footprint to sustain cost advantages across flexible formats. Sonoco Products Company anchors its position through rigid container specialization in laundry and surface care segments. Mondi plc differentiates via paperboard-based solutions that align with retailer sustainability mandates.
Home care packaging encompasses primary and secondary containment systems engineered from plastics, paperboard, glass, or metal, typically incorporating barrier coatings, dispensing closures, or resealable mechanisms to preserve product integrity and enable controlled consumer use. Flexible packaging leads volume share in liquid detergents and fabric softeners due to lightweight logistics and shelf-ready formats, while rigid containers dominate concentrated pod and tablet segments where structural protection commands premium positioning. Eco-friendly features represent the fastest-growing feature category as EU Green Deal compliance and extended producer responsibility schemes reshape procurement specifications across European retail channels.
EPA regulations on volatile organic compound emissions from household products directly influence barrier material specifications and adhesive selections in North American packaging lines. REACH restrictions on phthalates and bisphenol derivatives within Europe constrain plasticizer options, pushing converters toward bio-based polymer validation. Stakeholders must monitor evolving EPR fee structures and recyclability labeling requirements as these frameworks increasingly determine market access and contract eligibility across major economies.
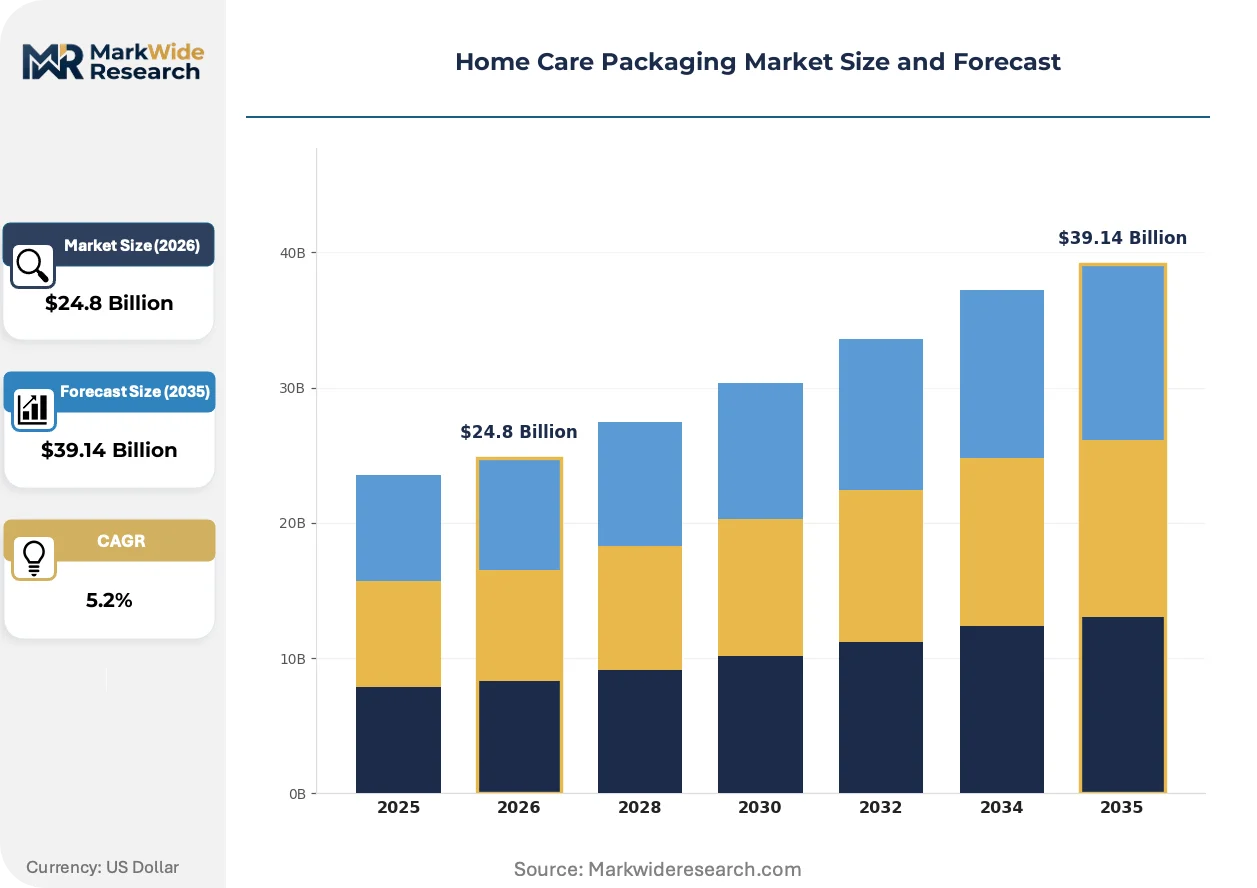
Market Dynamics
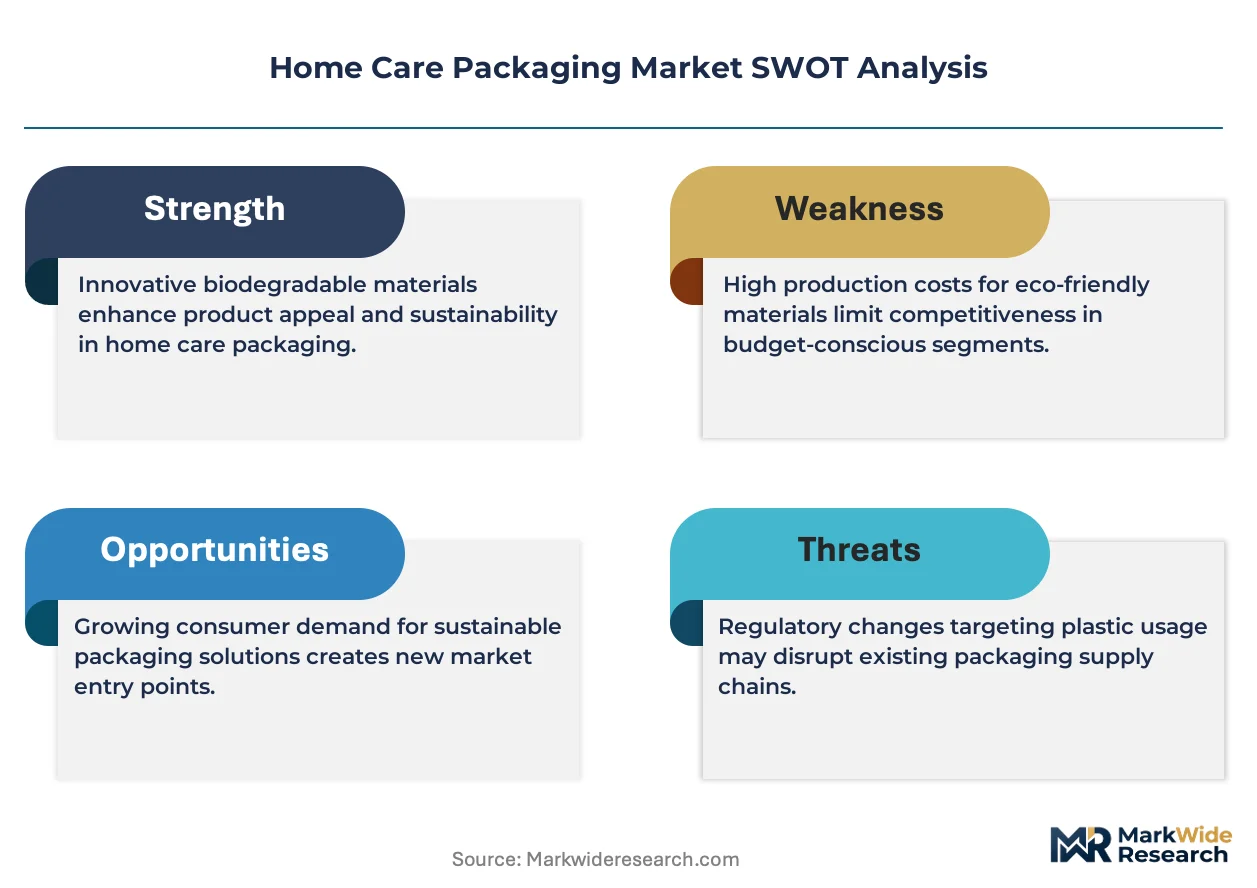
Extended producer responsibility schemes in Germany, France, and California are forcing converters to redesign material stacks and absorb compliance fees into contract pricing, compressing margins for non-integrated suppliers.
Growth Catalysts
- EU Green Deal packaging mandates:Germany's national implementation of the Packaging Act requires minimum recycled content thresholds, pulling post-consumer resin into flexible film specifications.
- Concentrated pod formats:Water-reduced detergent tablets and unit-dose laundry pods are driving demand for rigid barrier containers with child-resistant closures.
- China's dual carbon goals:Provincial regulators in Jiangsu and Guangdong are accelerating local brand owner adoption of lightweight flexible pouches to cut logistics emissions.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock swings tied to Gulf Coast petrochemical capacity constrain margin predictability for blow-molded bottle converters.
- Monoclonal barrier film supply:Five specialized coextrusion lines in Germany and Austria control global supply of high-oxygen-barrier films for bleach applications.
- Multi-material lamination complexity:Adhesive bonding between polyethylene and aluminum foil layers complicates mechanical recycling streams and raises EPR fee exposure.
Strategic Opportunities
- India's organized retail expansion:Reliance Retail and DMart are scaling private-label home care lines that require shelf-ready secondary packaging formats.
- Paperboard bottle convergence:Molded fiber barriers combined with thin-film liners are opening rigid container applications previously locked by HDPE and PET.
- Refill station channel emergence:Unpackaged bulk detergent dispensing in UK and Dutch supermarkets is creating demand for durable reusable primary containers.
Industry Challenges
- Barrier coating formulation talent:Solvent-free adhesive chemists and bio-based polymer scientists command premium compensation in European labor markets.
- Legacy filling line retrofit costs:Converting from rigid bottle to flexible pouch formats requires capital-intensive changeover of capping and labeling stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Care Packaging Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.14 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Labels, Resealable Pouches Material: Plastic, Paperboard, Glass, Metal Feature: Eco-Friendly, Child-Resistant, Tamper-Evident, Multi-Functional End User: Households, Retailers, Distributors, Manufacturers |
| Companies Covered | Amcor plc, Sonoco Products Company, Ball Corporation, AptarGroup Inc., Silgan Holdings Inc., Winpak Ltd., Mondi plc, ProAmpac LLC, DS Smith plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Care Packaging Market Strategic Shifts & Innovations
Material science advances and channel-specific format requirements are fragmenting the once-standardized packaging specification landscape, forcing converters to maintain parallel production capabilities.
Monomaterial polyethylene films with enhanced oxygen barrier properties are migrating from niche organic detergent lines to mainstream fabric softener applications. Unilever and Henkel procurement teams are qualifying these structures for European volume contracts. The shift is migrating from pilot-scale trials to full production runs, compressing demand for legacy multilayer laminates that require specialized recycling infrastructure.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorinated coatings from paperboard laundry packaging by 2025. ECHA's Substances of Very High Concern list is forcing converters to validate silicone and bio-wax alternatives. Surface care wipes and dryer sheet cartons in France and Benelux markets are most affected, with retailers rejecting non-compliant stock-keeping units from shelf resets.
Direct-to-subscription refill models are bypassing traditional retail shelf placement entirely. Grove Collaborative and Blueland ship concentrated tablets in minimal protective wraps, eliminating secondary corrugated shippers. This pattern concentrates in US coastal metropolitan markets where last-mile logistics density supports recurring delivery economics.
Home Care Packaging Market Segmentation
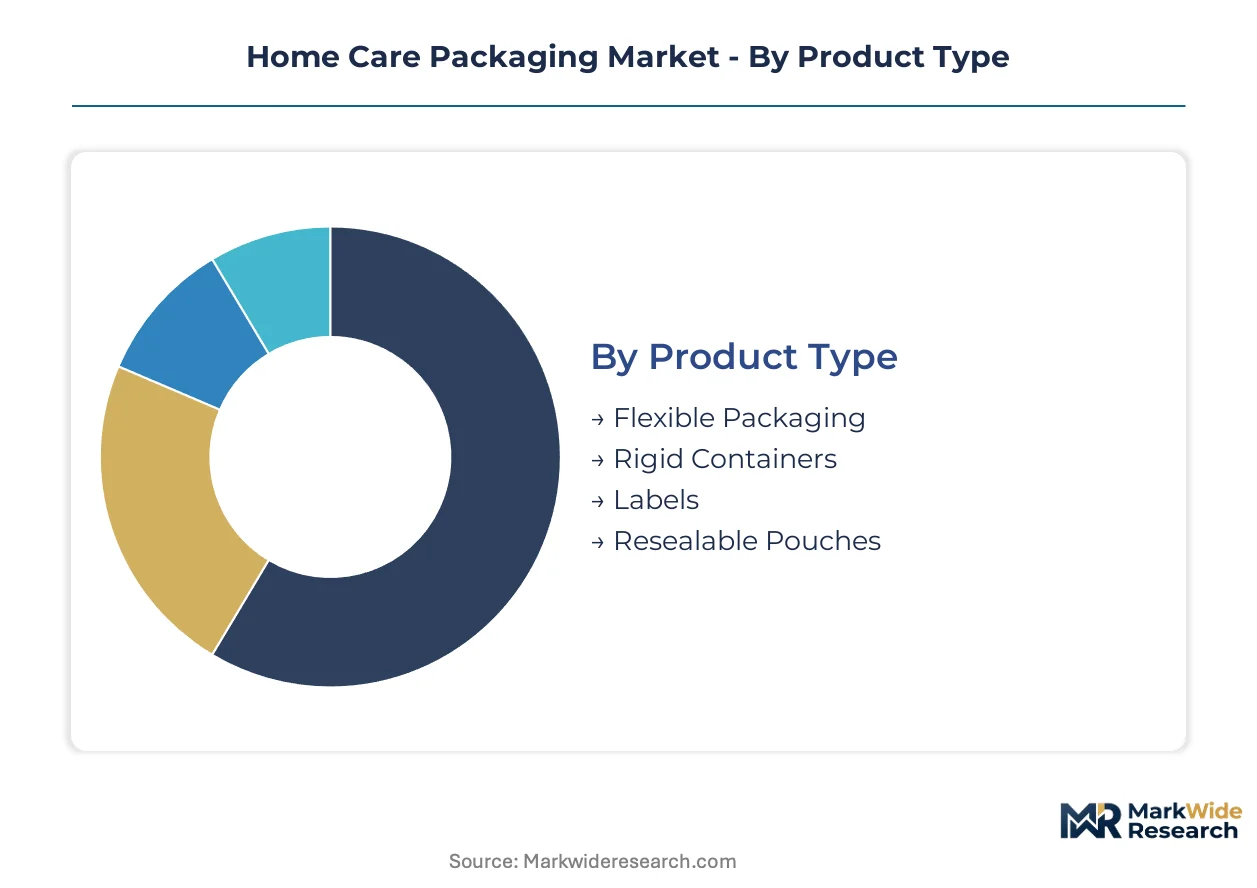
Home care packaging procurement patterns diverge sharply across product formats, material specifications, and end-user requirements. Brand owners now specify packaging architectures that reconcile shelf differentiation with EPR compliance fees and reverse logistics obligations.
Product Type:
Mature formats dominate volume positions while emerging structures capture sustainability-driven substitution demand.
- Flexible Packaging:Multi-layer films and stand-up pouches constructed from polyethylene or polypropylene substrates deliver lightweight logistics and shelf-ready merchandising. German and Chinese brand owners are qualifying monomaterial PE films for fabric softener and liquid detergent applications to satisfy EU Green Deal recycled content mandates and provincial dual carbon targets.
- Rigid Containers:Blow-molded HDPE bottles and injection-molded tubs provide structural protection for concentrated pods, tablets, and bleach formulations. Demand concentrates in North American laundry pod segments where child-resistant closures and oxygen barrier specifications command premium positioning against flexible alternatives.
- Labels:Pressure-sensitive and shrink-sleeve formats carry regulatory disclosures, barcodes, and brand messaging on primary containers.
- Resealable Pouches:Zip-lock and slider mechanisms extend product shelf life for bulk detergent refills and surface care wipes.
Flexible packaging retains volume leadership; rigid containers hold the steepest expansion curve as pod formats proliferate.
Material:
Cost tier stratification separates commodity feedstocks from specialty substrates facing regulatory displacement.
- Plastic:Polyethylene terephthalate, high-density polyethylene, and polypropylene constitute the baseline cost tier across blow-molded bottles and flexible films. REACH restrictions on phthalates and bisphenol derivatives are constraining plasticizer selection in European converter operations.
- Paperboard:Folding cartons and molded fiber containers serve secondary packaging and emerging primary bottle applications. Retailer sustainability mandates in France and Benelux are accelerating silicone and bio-wax barrier validation as fluorinated coatings face ECHA Substances of Very High Concern delisting.
- Glass:Premium positioning in artisanal surface care and decorative fragrance segments where chemical inertness and aesthetic weight justify logistics cost premiums.
- Metal:Aerosol cans and tinplate containers preserve volatile formulations in insecticide and polish applications requiring pressure resistance.
Plastic maintains absolute volume dominance; paperboard is climbing the fastest on EPR fee arbitrage and retailer specification shifts.
Feature:
Application context determines which functional attributes command procurement priority and price premium.
- Eco-Friendly:Post-consumer recycled content, bio-based polymers, and recyclable monomaterial constructions. EU extended producer responsibility schemes in Germany and France are embedding minimum recycled thresholds into contract eligibility.
- Child-Resistant:Push-and-turn closures, pinch grips, and blister formats preventing accidental ingestion of concentrated pods and bleach tablets. EPA regulations on household product safety drive specification in US laundry segments.
- Tamper-Evident:Breakable rings, shrink bands, and induction seals protecting product integrity through distribution.
- Multi-Functional:Integrated measuring dispensers, spray triggers, and ergonomic grips enhancing consumer handling efficiency.
Eco-friendly features are gaining share fastest on regulatory pull; child-resistant specifications retain defensive premium positioning.
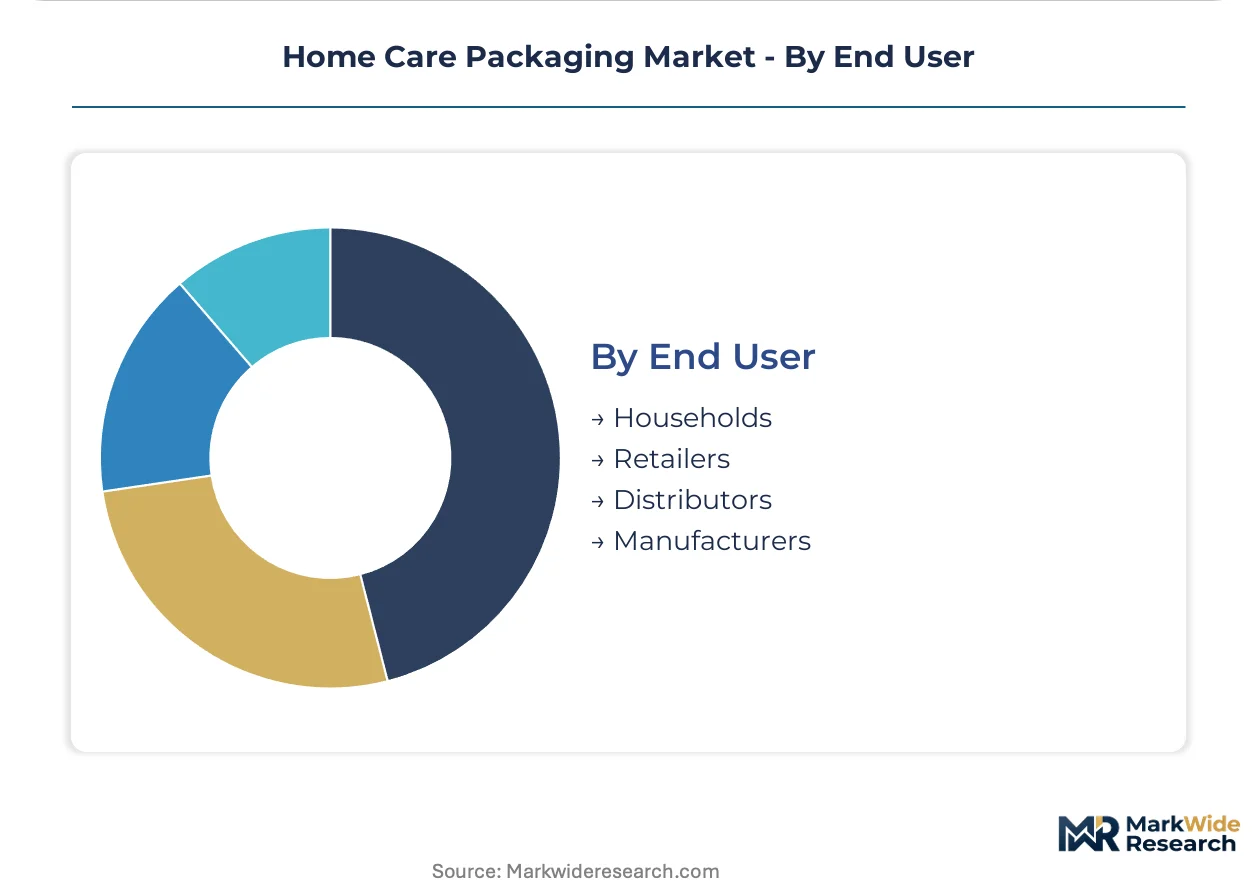
End User:
Customer type segmentation reveals divergent packaging specification authority and volume concentration.
- Households:Individual consumers purchasing through retail and direct-to-subscription channels. Grove Collaborative and comparable refill models ship concentrated tablets in minimal protective wraps, eliminating secondary corrugated for coastal metropolitan delivery density.
- Retailers:Supermarket and hypermarket chains imposing private-label specifications and sustainability compliance. Reliance Retail and DMart in India are scaling shelf-ready secondary packaging requirements for organized home care lines.
- Distributors:Wholesale and institutional supply intermediaries handling bulk formats for hospitality and facility management sectors.
- Manufacturers:Contract packers and brand owner filling operations specifying primary container compatibility with legacy line equipment.
Households drive absolute volume; retailers are expanding specification authority fastest through EPR mandate compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging mandates and extended producer responsibility schemes are redirecting procurement flows across major economies. Germany's Packaging Act and California's EPR implementation are accelerating material transitions. China's dual carbon targets are reshaping logistics formats in key manufacturing provinces.
Germany
Flexible film converters in North Rhine-Westphalia are qualifying monomaterial polyethylene structures for fabric softener contracts. The national Packaging Act mandates minimum recycled content thresholds, pulling post-consumer resin into specifications. Industrial clusters around Düsseldorf and Cologne host specialized coextrusion capacity for high-barrier laundry applications.
United States
EPA regulations on volatile organic compound emissions from household products influence barrier material selections in blow-molded bottle production. California's extended producer responsibility scheme forces converters to absorb compliance fees into contract pricing. Gulf Coast petrochemical capacity ties resin price volatility to converter margin predictability.
China
Provincial regulators in Jiangsu and Guangdong are accelerating local brand owner adoption of lightweight flexible pouches. The dual carbon goals framework cuts logistics emissions through format substitution. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta supports scale economies for pouch converters.
France
ECHA's Substances of Very High Concern list is eliminating fluorinated coatings from paperboard laundry packaging by 2025. REACH restrictions on per- and polyfluoroalkyl substances force silicone and bio-wax barrier validation. Retailers in Paris and Lyon markets are rejecting non-compliant stock-keeping units from shelf resets.
India
Reliance Retail and DMart are scaling private-label home care lines requiring shelf-ready secondary packaging formats. The PLI scheme for manufacturing supports organized retail expansion in Maharashtra and Gujarat. Mumbai and Ahmedabad industrial corridors are attracting flexible packaging investments for detergent and surface care segments.
Home Care Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent packaging format requirements. The market exhibits tiered consolidation where global film manufacturers hold cost advantages in flexible formats while rigid container specialists defend premium positioning in pod and tablet segments. Three archetypes dominate: integrated resin-to-film converters, rigid barrier specialists, and paperboard sustainability-focused suppliers. Competitive moves center on backward integration into recycled resin streams and geographic expansion into EPR-mandated markets.
Among integrated packaging conglomerates, Amcor plc and Mondi plc occupy positions aligned with retailer sustainability mandates through film manufacturing scale and paperboard-based solutions respectively. Sonoco Products Company exemplifies the rigid container specialist archetype, anchoring its market presence through structural protection formats in laundry and surface care segments. These three companies represent the dominant strategic configurations: global film footprint leverage, paperboard barrier differentiation, and rigid format specialization.
| Leading Market Players |
|---|
| Amcor plc |
| Sonoco Products Company |
| Ball Corporation |
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Winpak Ltd. |
| Mondi plc |
| ProAmpac LLC |
| DS Smith plc |
| Others |
Cost & Logistics Intelligence
Resin price volatility tied to Gulf Coast petrochemical capacity determines both margin compression in blow-molded bottle tiers and converter sourcing strategies across flexible film specifications. Brand owners absorb EPR compliance fees into contract pricing, forcing tier spreads that separate integrated resin-to-film suppliers from non-integrated converters.
Pricing Analysis
Certification level against EU Green Deal recycled content mandates creates the primary spread between premium monomaterial PE film contracts and standard multilayer laminate pricing. Pricing stratifies across premium, standard, and economy tiers where post-consumer resin thresholds, barrier performance ratings, and child-resistant closure complexity differentiate quotes. Cost compression in standard flexible formats is intensifying because German and French EPR schemes embed compliance fees into base material costs. Private-label retailers at Reliance Retail and DMart exhibit highest price sensitivity, while concentrated pod brand owners in North America accept premium positioning for oxygen barrier rigid containers.
Supply Chain Analysis
Specialized coextrusion capacity in Germany and Austria holds dominant position for high-oxygen-barrier films serving bleach applications. Raw material flows draw from Saudi Arabian and US Gulf Coast ethylene feedstock, Jiangsu province biaxially oriented PP film, and recycled resin streams through Düsseldorf industrial clusters. Single-source vulnerability concentrates in the five specialized barrier film lines controlling global bleach packaging supply. Distribution runs through converter-direct contracts with Henkel and Unilever procurement teams, supplemented by tier-two private-label supply to organized retail chains in India and European supermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized solvent-free adhesive chemists and bio-based polymer scientists command compensation premiums that outstrip available talent pools, constraining converter R&D velocity and widening capability gaps between integrated and non-integrated suppliers.
For Market Incumbents: Pre-empt emerging monomaterial PE qualification demands by securing captive post-consumer resin streams through backward integration into German and Austrian recycling infrastructure. Anchor contract renewals with Unilever and Henkel procurement teams by guaranteeing EU Green Deal compliance thresholds ahead of 2025 enforcement dates. Capacity addition in Jiangsu province flexible pouch lines captures China's dual carbon logistics substitution before provincial mandates harden. For New Entrants and Emerging Players: India's organized retail corridor through Maharashtra and Gujarat presents the most penetrable white-space for shelf-ready secondary packaging formats serving Reliance Retail and DMart private-label expansion. Paperboard-based primary bottle applications in France and Benelux offer second entry point as ECHA fluorinated coating bans force silicone and bio-wax barrier validation. A direct-to-subscription refill model targeting UK and Dutch supermarket bulk dispensing stations bypasses incumbent retail shelf placement entirely. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors integrated resin-to-film converters with established post-consumer resin qualification pathways. Long-term viability centers on suppliers capable of absorbing EPR fee structures into operational scale rather than passing through cost volatility. Acquisition target archetype: mid-cap flexible film converters in North Rhine-Westphalia with monomaterial PE pilot capacity and existing Henkel or Unilever contract relationships. Monitor ECHA Substances of Very High Concern list expansion as inflection indicator for paperboard barrier coating substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial PE Film Qualification | Unilever and Henkel procurement teams are migrating volume contracts from multilayer laminates to recyclable single-substrate structures. |
| Post-Consumer Resin Integration | Germany's Packaging Act mandates minimum recycled thresholds, pulling PCR into flexible film specifications and favoring integrated converters. |
| Paperboard Barrier Validation | ECHA fluorinated coating bans by 2025 force silicone and bio-wax alternatives for laundry packaging in France and Benelux markets. |
| Flexible Pouch Capacity Expansion | Jiangsu and Guangdong provincial regulators accelerate lightweight format adoption under China's dual carbon goals framework. |
| Refill Station Channel Development | UK and Dutch supermarket bulk dispensing creates demand for durable reusable primary containers bypassing traditional retail placement. |
Research Approach
A standing panel of procurement directors at Unilever and Henkel, flexible film plant managers in North Rhine-Westphalia, organized retail category buyers at Reliance Retail and DMart, and EPR compliance officers in German and French regulatory bodies provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Green Deal implementation documents, ECHA Substances of Very High Concern registry updates, China's provincial dual carbon policy releases, and SEC filings of listed packaging converters. Bottom-up volume modeling across flexible film, rigid container, and paperboard format segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed low, base, and high cases around EPR fee trajectory uncertainty, resin price volatility bands, and monomaterial PE adoption speed across the projection horizon. Segmentation dimensions modeled included product format, material substrate, functional feature tier, and end-user channel. CAGRs derived from historical volume elasticities against GDP and consumer expenditure indices, with industry-specific inputs capturing EU Green Deal compliance cost pass-through rates and China's logistics emission reduction targets.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by non-integrated converters or rapid EPR fee escalation beyond modeled thresholds would shift outcomes substantially. Quarterly review of ECHA SVHC list updates, German Packaging Act enforcement actions, and Jiangsu province flexible pouch adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Gift Basket Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Baby Wipes Market
Baby Products
Mexico Baby Care Products Market
Baby Products
Baby Slings Market
Baby Products
Smart Bottle Warmers Market
Baby Products
Baby Bedding Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby Pacifier Market
Baby Products
Portable Cribs Market
Baby Products
Baby Sleepsuits Market
Baby Products
Baby Playpens Market
Baby Products
Crib Mattress Market
Baby Products
Global Baby Carriers Market