
 Children Products Market | 2026-2036
Children Products Market Size, Share, and Industry Trends Forecast 2026-2036
Children Products Market Insights
Asset-light licensing and royalty-based manufacturing is narrowing the capital barrier for new entrants in toys and apparel. Hasbro leverages its entertainment IP portfolio to sustain revenue without owning production capacity. The Lego Group anchors premium positioning through in-house molding precision and controlled resin sourcing. Mattel competes across multiple price tiers through differentiated brand architecture spanning dolls, vehicles, and infant products.
Children products encompass goods engineered for physical safety, developmental appropriateness, and ergonomic fit from birth through adolescence, with mandatory compliance to flammability standards, small-part restrictions, and phthalate limits depending on intended age. These items serve parental purchasers seeking functional utility, educational stimulation, and emotional engagement for dependent minors. Toys and nursery items capture margin concentration where safety certification creates defensible positioning, while online retail reshapes channel economics by collapsing geographic inventory constraints. Clothing segments face faster inventory cycles tied to seasonal sizing and licensed character refresh rates.
FDA oversees pacifier and feeding product standards in the United States, while the EU Toy Safety Directive and REACH govern chemical migration limits and mechanical safety across European member states. China's SAMR enforces GB standards for plastics and coatings in domestically sold nursery equipment, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must monitor evolving chemical restriction lists and digital privacy rules targeting connected toys to preserve market access and brand trust.
Market Dynamics
Millennial parents now drive purchasing through mobile-first discovery channels, compressing traditional retail gatekeeper roles and forcing manufacturers to rebuild demand generation around social proof and direct-to-consumer fulfillment infrastructure.
Growth Catalysts
- REACH chemical migration limits:European compliance mandates are accelerating substitution of legacy plasticizers with bio-based alternatives, creating premium positioning for certified suppliers.
- Connected toy ecosystems:Embedded sensors and companion apps are extending product lifecycles through subscription content models and parental engagement dashboards.
- Middle-class household formation:Urbanization in São Paulo, Mumbai, and Chengdu is concentrating demand for safety-certified nursery equipment and educational toys.
Market Restraints
- Petrochemical feedstock volatility:ABS and polypropylene resin costs swing with crude oil benchmarks, squeezing margin predictability for molded plastic toys and feeding accessories.
- Single-source molding capacity:Precision injection tooling for interlocking bricks concentrates in southern China, creating geographic supply vulnerability.
- Phthalate restriction fragmentation:Divergent state-level bans in California, Washington, and Maine multiply testing burdens beyond federal CPSIA baselines.
Strategic Opportunities
- Rural India distribution gaps:kirana store networks and regional e-commerce platforms remain underserved for mid-tier apparel and basic nursery furniture.
- EU Green Deal circularity mandates:Extended producer responsibility schemes reward take-back programs and recyclable mono-material designs with reduced compliance fees.
- AI-powered personalization:machine learning recommendation engines are converging with AR try-on features to reduce return rates for sized apparel and footwear.
Industry Challenges
- GB standards certification timelines:China's SAMR testing protocols for domestic nursery equipment create 4-6 month market entry delays for new product launches.
- Licensing agreement renegotiation cycles:entertainment IP renewal terms are compressing from five-year to three-year windows, forcing portfolio churn and inventory risk.
- Legacy ERP integration:direct-to-consumer fulfillment requires real-time inventory visibility that conflicts with wholesale-focused enterprise systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Products Market |
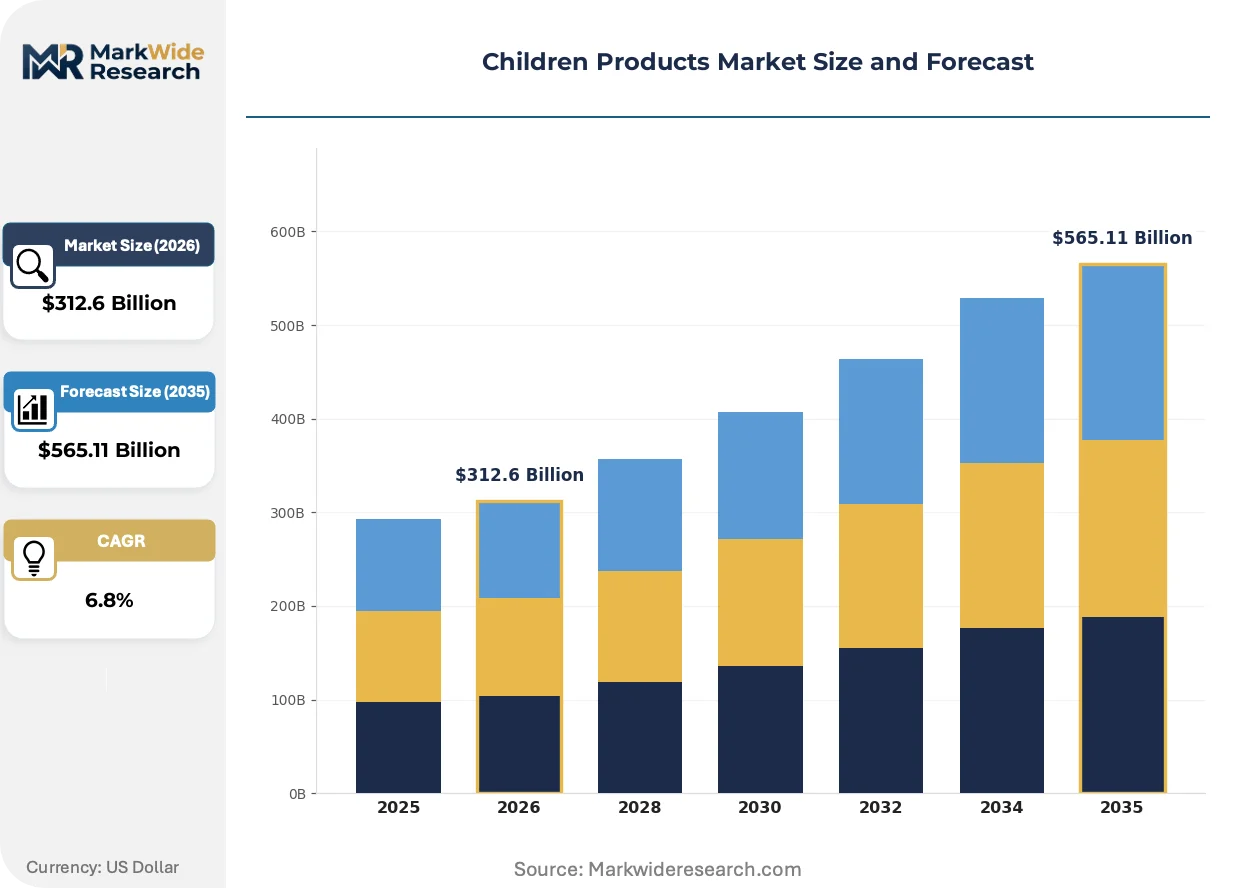
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toys, Clothing, Nursery Items, Books Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Discount Stores Age Group: Infants, Toddlers, Preschoolers, Teenagers Material: Plastic, Fabric, Wood, Metal |
| Companies Covered | Procter & Gamble, Artsana (Chicco), Johnson & Johnson, Hasbro, Pigeon Corporation, The Lego Group, Bandai Namco Holdings, Kimberly-Clark, Mattel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Products Market Trends and Innovations
Product engineering and channel economics are simultaneously transforming as safety science advances and parental purchase journeys fragment across platforms.
Plant-derived resins derived from sugarcane and corn starch are migrating from niche premium positioning into mainstream toy construction. European retailers and North American boutique chains are adopting these materials at pace to preempt regulatory tightening. This shift is compressing cost premiums for bio-based alternatives while forcing conventional petrochemical suppliers to defend volume through price aggression.
EU Toy Safety Directive 2009/48/EC amendments are tightening sound level limits and expanding chemical prohibition lists to cover endocrine disruptors. Manufacturers must redesign acoustic components in electronic toys and reformulate coatings to maintain CE marking access. German and French market surveillance authorities are conducting the most aggressive enforcement, with non-compliant shipments facing port detention.
Subscription box curation is displacing aisle-based discovery for developmental toys and age-graded apparel. Millennial parents in coastal US metros and London are prioritizing convenience and expert selection over individual product research. This channel compression is concentrating buying power with platform operators who negotiate exclusive SKUs and demand data-sharing from participating brands.
Children Products Market Segmentation
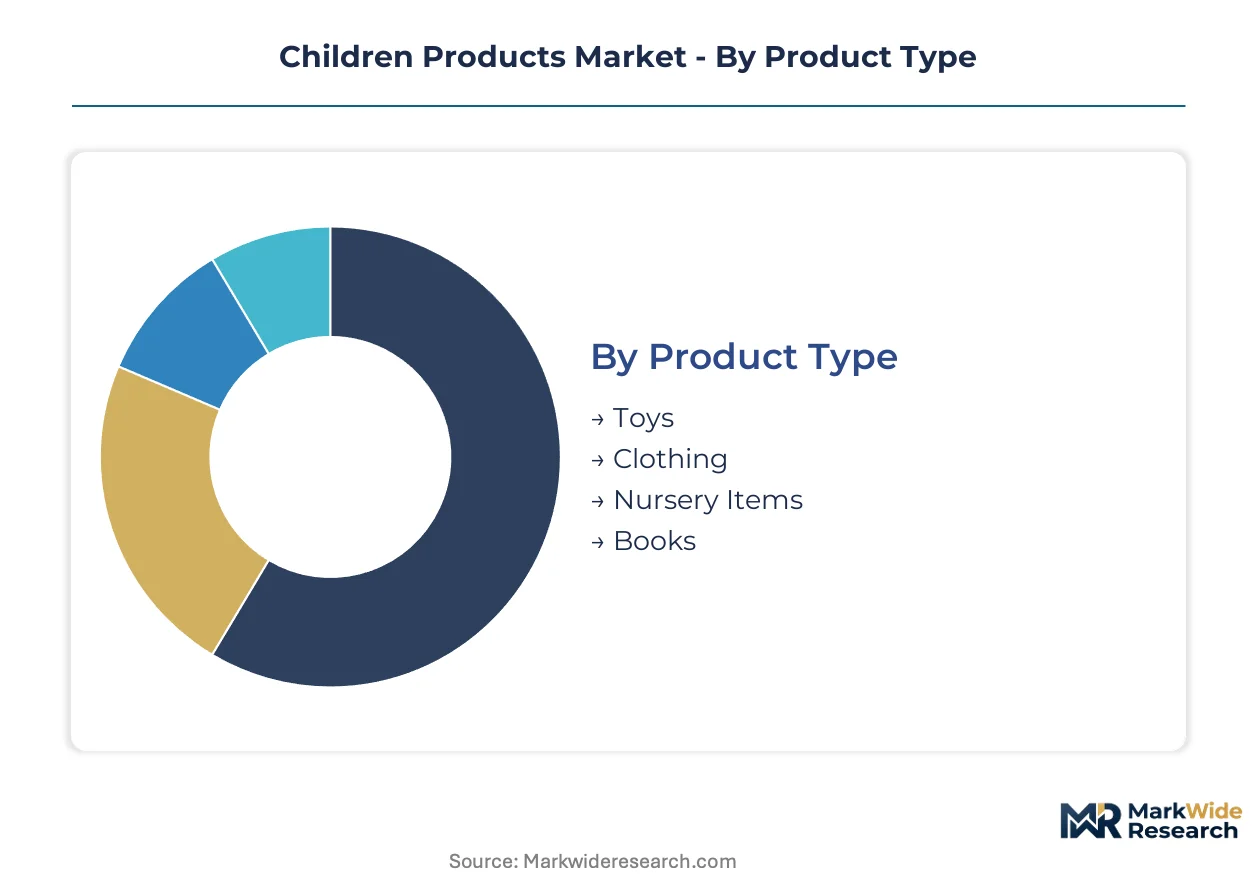
Children products demand fragments across developmental stages, material safety profiles, and channel economics. Manufacturers must align certification requirements and margin structures to specific segment characteristics rather than treating the market as uniform.
Product Type:
Mature segments dominate revenue concentration while emerging categories reshape growth trajectories through technology integration and premium positioning.
- Toys:Construction sets, electronic learning devices, and licensed character merchandise comprise the revenue core. Safety-certified interlocking bricks and STEM-aligned robotics kits concentrate demand in urban China and Germany, where REACH chemical compliance and parental education spending intersect.
- Clothing:Sized apparel from newborn to adolescent spans seasonal refresh cycles and licensed character tie-ins. Cotton-synthetic blends and organic certifications compete on margin in North American and European markets, with fast-fashion pressure compressing inventory turns.
- Nursery Items:Cribs, feeding accessories, and monitoring equipment carry the highest safety certification burdens. FDA and EU Toy Safety Directive compliance costs favor established suppliers with dedicated testing infrastructure.
- Books:Board books through young adult fiction serve literacy development and entertainment. Educational publishers and character licensing drive format innovation, with digital subscription models disrupting traditional retail distribution.
Toys retain volume leadership; Nursery Items hold the steepest expansion curve.
Distribution Channel:
Channel economics stratify by customer acquisition cost and inventory velocity, with digital platforms capturing margin from legacy retail gatekeepers.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators collapse geographic constraints. Millennial parents in São Paulo and Mumbai drive mobile-first discovery, with subscription curation models gaining traction for developmental toy assortments.
- Specialty Stores:Boutique retailers and category-focused chains deliver expert curation and safety assurance. Premium positioning in London, New York, and Tokyo justifies higher price points through staff training and exclusive SKU access.
- Supermarkets:Mass-market grocery chains capture convenience-driven purchases for basic apparel and feeding accessories. Impulse placement and promotional pricing dominate, with private-label expansion compressing branded margin.
- Discount Stores:Value-oriented chains serve price-sensitive households in secondary cities and rural catchments. Simplified packaging and reduced SKUs align with procurement focused on volume throughput over brand equity.
Online Retail gains share fastest; Specialty Stores defend margin through differentiation.
Age Group:
Developmental appropriateness dictates safety standards, material specifications, and parental involvement intensity across the age spectrum.
- Infants:Products from birth to 12 months face the most stringent mechanical and chemical safety requirements. FDA-regulated feeding accessories and EU-compliant nursery equipment concentrate demand among first-time parents with elevated risk sensitivity.
- Toddlers:Mobility and oral exploration drive demand for durable, non-toxic construction toys and protective clothing. Phthalate-free plastics and reinforced seams address wear patterns in this high-activity cohort.
- Preschoolers:Educational stimulation and social play define this segment. STEM-aligned toys and character-licensed apparel capture parental spending focused on school readiness and peer engagement.
- Teenagers:Autonomous purchasing and digital-native preferences shift demand toward electronics, fashion, and experiential categories. Social proof and influencer endorsement displace parental gatekeeping in purchase decisions.
Infants anchor safety-certification spending; Preschoolers climb fastest on educational positioning.
Material:
Supply concentration and regulatory pressure on petrochemical feedstocks are accelerating material substitution across price tiers.
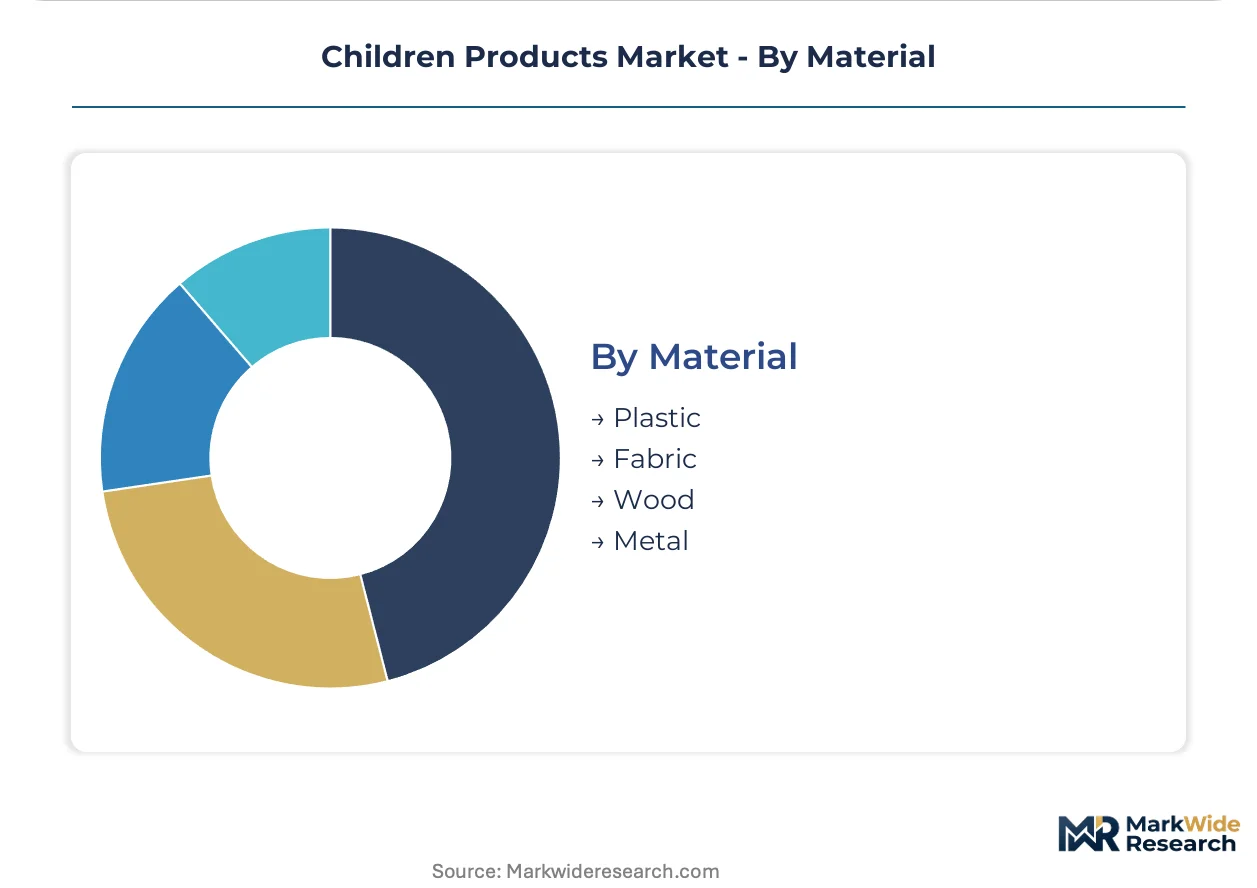
- Plastic:ABS and polypropylene dominate molded toys and feeding accessories. REACH chemical migration limits and state-level phthalate bans in California and Washington are accelerating bio-based resin adoption for CE-marked products.
- Fabric:Cotton, polyester blends, and technical textiles serve apparel and soft goods. Organic certification and recycled fiber content command premium positioning in European and North American markets.
- Wood:Sustainable forestry certifications and natural aesthetic appeal support premium nursery furniture and construction toys. EU Green Deal circularity mandates reward mono-material designs with reduced extended producer responsibility fees.
- Metal:Stainless steel and aluminum appear in feeding accessories, bicycles, and outdoor equipment. Durability and recyclability align with parental preferences for multi-child usage and environmental accountability.
Plastic maintains volume dominance; Wood expands most quickly on sustainability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial parents in Shanghai, Mumbai, and São Paulo concentrate purchasing power for safety-certified nursery equipment and educational toys, with regulatory divergence across jurisdictions fragmenting compliance strategies for multinational suppliers.
United States
First-time parents in coastal metros drive premium spending on FDA-regulated feeding accessories and organic cotton apparel. California, Washington, and Maine enforce state-level phthalate bans beyond federal CPSIA baselines, multiplying testing burdens for domestic suppliers. Los Angeles and New York City anchor specialty retail clusters where boutique chains curate exclusive SKUs for safety-conscious households.
China
Urban middle-class formation in Chengdu, Hangzhou, and Shenzhen concentrates demand for GB-certified nursery furniture and STEM-aligned construction toys. SAMR enforces extended testing timelines for domestically sold equipment, creating 4-6 month market entry delays that favor established suppliers with dedicated certification infrastructure. Yangtze River Delta manufacturing clusters supply precision-molded components for interlocking brick systems.
Germany
REACH chemical migration limits and EU Toy Safety Directive amendments drive substitution of legacy plasticizers with bio-based alternatives in molded toys and feeding accessories. Berlin and Hamburg host aggressive market surveillance authorities conducting port detention of non-compliant shipments. Bavarian retailers command premium positioning through staff-trained safety assurance and exclusive organic textile assortments.
India
Kirana store networks and regional e-commerce platforms in Maharashtra, Gujarat, and Karnataka remain underserved for mid-tier apparel and basic nursery furniture. BIS certification requirements for domestically manufactured plastics create compliance entry barriers that favor scaled suppliers. Mumbai and Delhi-NCR concentrate demand from dual-income households prioritizing educational stimulation and safety certification.
Brazil
São Paulo and Rio de Janeiro anchor demand for safety-certified nursery equipment as urban middle-class household formation accelerates. ANVISA regulates pacifier and feeding product standards, while state-level consumer protection agencies enforce mechanical safety for domestically sold toys. Southeast manufacturing clusters near Curitiba supply molded plastic components for regional toy assemblers.
Children Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. The market exhibits tiered consolidation with entertainment IP licensors, precision manufacturers, and hygiene-focused conglomerates occupying distinct competitive spaces. Three archetypes dominate: royalty-based IP monetizers, in-house molding specialists, and diversified safety-certification leaders. Capacity expansion in bio-based resins and strategic partnerships for direct-to-consumer fulfillment represent the dominant competitive moves reshaping positioning.
Within the entertainment IP tier, Hasbro exemplifies asset-light licensing strategies that sustain revenue without captive production capacity. The Lego Group occupies a position as the in-house molding specialist, anchoring premium positioning through controlled resin sourcing and precision manufacturing. Mattel represents diversified portfolio competition, spanning dolls, vehicles, and infant products across multiple price tiers. These three entities collectively illustrate the strategic divergence between licensing leverage, manufacturing control, and brand architecture breadth.
| Leading Market Players |
|---|
| Procter & Gamble |
| Artsana (Chicco) |
| Johnson & Johnson |
| Hasbro |
| Pigeon Corporation |
| The Lego Group |
| Bandai Namco Holdings |
| Kimberly-Clark |
| Mattel |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta molding clusters concentrate precision injection capacity for interlocking brick systems, translating geographic supply dominance into pricing power for certified toy manufacturers serving REACH-compliant European markets. Resin procurement contracts indexed to crude oil benchmarks transmit petrochemical volatility directly into margin structures, forcing tiered pricing responses across premium and economy product lines.
Pricing Analysis
Cost-plus contracts with polypropylene and ABS resin suppliers tie pricing to monthly crude oil indexation, creating margin compression when feedstock costs spike. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based formulations from conventional petrochemical alternatives, with certification grade and volume scale as the primary differentiation drivers. Pricing pressure stems from state-level phthalate testing burdens beyond federal CPSIA baselines, squeezing mid-tier suppliers. Value-oriented discount store buyers exhibit highest price sensitivity, while specialty retail purchasers prioritize safety assurance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for toy and nursery equipment importers. Manufacturing concentrates in China, Vietnam, and India for molded plastics, fabric assembly, and wood furniture respectively. Raw material dependencies center on petrochemical resins, organic cotton fibers, and FSC-certified timber. Single-source vulnerability persists in precision injection tooling for construction toys, where southern Chinese facilities control specialized interlocking brick molds. Distribution runs through direct-to-consumer platforms, specialty retail networks, and mass-market grocery chains with divergent margin expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription curation models for developmental toys and age-graded apparel represent a service-attach opportunity expanding faster than standalone hardware sales, as millennial parents prioritize convenience and expert selection over individual product research.
For Market Incumbents: Pre-empt bio-based resin substitution by securing captive supply agreements with sugarcane and corn starch derivative producers before REACH chemical mandates tighten further. Defend position by building dedicated GB standards certification infrastructure in China to compress SAMR testing timelines from six months to under ninety days. Channel control through exclusive SKU arrangements with subscription box platforms offers defensive moats against direct-to-consumer insurgents. For New Entrants and Emerging Players: Establish a beachhead in rural India kirana store networks and regional e-commerce platforms where mid-tier apparel and basic nursery furniture remain underserved. Target Maharashtra and Gujarat distribution gaps with simplified SKUs optimized for price-sensitive household procurement patterns. A direct-to-consumer fulfillment infrastructure bypassing wholesale ERP legacy systems enables faster inventory velocity than incumbent channel structures permit. For Investors and Strategic Acquirers: Long-term, this sits as a licensing-royalty play because entertainment IP monetization generates recurring revenue without production capacity ownership. Asset-light brand managers with controlled character portfolios and platform operator partnerships offer superior capital efficiency versus vertically integrated manufacturers. The signal to watch is compression of IP renewal terms from five-year to three-year windows, which forces portfolio churn and creates distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | Millennial parents in São Paulo and Mumbai drive mobile-first discovery, collapsing geographic inventory constraints. |
| Sustainability Repositioning | EU Green Deal circularity mandates reward take-back programs and recyclable mono-material designs with reduced compliance fees. |
| Premium Tier Introduction | REACH-certified bio-based alternatives command margin premiums in German and French markets with aggressive surveillance enforcement. |
| Distribution Channel Expansion | Rural India kirana networks remain underserved for mid-tier apparel and basic nursery furniture. |
| Brand Extension | STEM-aligned educational positioning captures parental spending focused on school readiness in urban China. |
Research Methodology
Desk research of customs trade records, SEC 10-K filings, and retail audit databases preceded structured interviews with toy brand managers, nursery equipment procurement leads at hospital systems, category buyers at specialty retailers, and supply planners at mass-market grocery chains. Bottom-up volume modeling across product type, distribution channel, age group, and material segments was cross-validated against top-down macroeconomic indicators and regulatory filing analysis.
Assumptions held fixed include REACH chemical migration limits and EU Toy Safety Directive enforcement intensity, while petrochemical feedstock costs and middle-class household formation rates in emerging markets were varied across sensitivity bands. Segmentation dimensions modeled encompass product type, distribution channel, age group, and material composition. CAGRs were derived from regression analysis against demographic and regulatory trend trajectories, with connected toy ecosystem adoption and bio-based resin substitution rates as industry-specific forecast inputs.
Stress conditions across crude oil price volatility, SAMR certification timeline extensions, and licensing agreement renegotiation cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and consumer preference stability that material shifts in trade policy or safety science could revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Bassinets Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Baby Swing Market
Baby Products
US Baby Care Products Market
Baby Products
Global Baby Product Market
Baby Products
Baby Nipple/Teat Market
Baby Products
India Baby Care Products Market
Baby Products
Japan Baby Care Product Market
Baby Products
Baby Playpens Market
Baby Products
Baby Stroller Market
Baby Products
Baby Care Products Market
Baby Products
Durable Juvenile Products Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Maternity Products Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
Baby Changing Station Market