
 Body Dryer Market | 2026-2036
Body Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Body Dryer Market Intelligence
Chinese OEM capacity for compact convection modules is pivoting toward European certification standards, reshaping component sourcing for finished-goods assemblers. Valiryo leverages its Basque manufacturing base to sustain CE-marked output for spa and residential channels across Western Europe. Haystack Dryers anchors the UK market through institutional contracts with NHS-affiliated care facilities. Full Body Dryer LLC competes in North America via direct-to-consumer distribution and ADA-compliant installation support.
A body dryer is an electrically powered air-drying appliance engineered to remove residual moisture from human skin after bathing, typically employing airflow velocities between 150 and 400 cubic feet per minute through wall-mounted or freestanding housings. Wall-mounted units dominate residential retrofits where floor space constraints dictate flush installation, while portable variants capture fastest uptake in rental properties and temporary wellness installations. Infrared technology commands premium positioning in spa end-user segments due to perceived therapeutic associations, though combination systems integrating convection and high-pressure air are gaining specification in commercial new-build projects where energy-recovery ventilation codes apply.
EPA WaterSense labeling and EU Ecodesign requirements are tightening minimum efficiency thresholds for bathroom appliances sold in the United States and European Union, effectively filtering uncertified imports from mass-market channels. Japan's METI enforces PSE electrical safety standards that add compliance layers for infrared and high-pressure air technologies entering that market. Stakeholders must monitor evolving harmonization between IEC 60335 household appliance safety standards and emerging national water-efficiency programs to anticipate which certification investments will unlock priority distribution channels.
Market Dynamics
Water-efficiency mandates from EPA WaterSense and EU Ecodesign are compressing demand for conventional towel systems while accelerating specification of automated drying appliances in hospitality and residential retrofit channels.
Growth Catalysts
- EPA WaterSense labeling:Mandatory efficiency thresholds in the United States are filtering uncertified imports and creating procurement preference for compliant body dryer systems in federal and commercial buildings.
- Spa and wellness centers:Infrared-equipped units command premium positioning in thermal therapy environments across Germany and Japan, where therapeutic associations drive replacement cycles.
- Wall-mounted convection modules:Compact form factors are capturing residential retrofit demand in aging-in-place bathroom renovations throughout the United States and Western Europe.
Market Restraints
- Copper and rare-earth magnet costs:Motor assembly inputs face price volatility that compresses margin structures for mid-tier assemblers sourcing from Chinese component suppliers.
- Single-source certification bottlenecks:PSE electrical safety testing capacity in Japan concentrates approval timelines for infrared and high-pressure air technologies entering that market.
- Towel system substitution:Low-cost textile rental services in budget hospitality chains delay capital conversion to fixed electrical appliances.
Strategic Opportunities
- ADA-compliant residential retrofits:United States aging-in-place renovations represent underpenetrated demand for grab-bar-integrated body dryer installations in multi-generational households.
- EU Ecodesign alignment:Chinese OEM capacity pivoting toward CE-marked output creates sourcing flexibility for Western European finished-goods assemblers seeking dual-certification products.
- Combination convection-infrared systems:Technology convergence is opening specification in commercial new-build projects where energy-recovery ventilation codes apply.
Industry Challenges
- Electrical contractor certification:Installation complexity with 240V hardwired units in North American residential retrofits requires specialized trade skills that constrain rollout velocity.
- Harmonization lag between IEC 60335 and national water-efficiency programs:Divergent testing protocols force manufacturers to maintain parallel certification inventories, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Dryer Market |
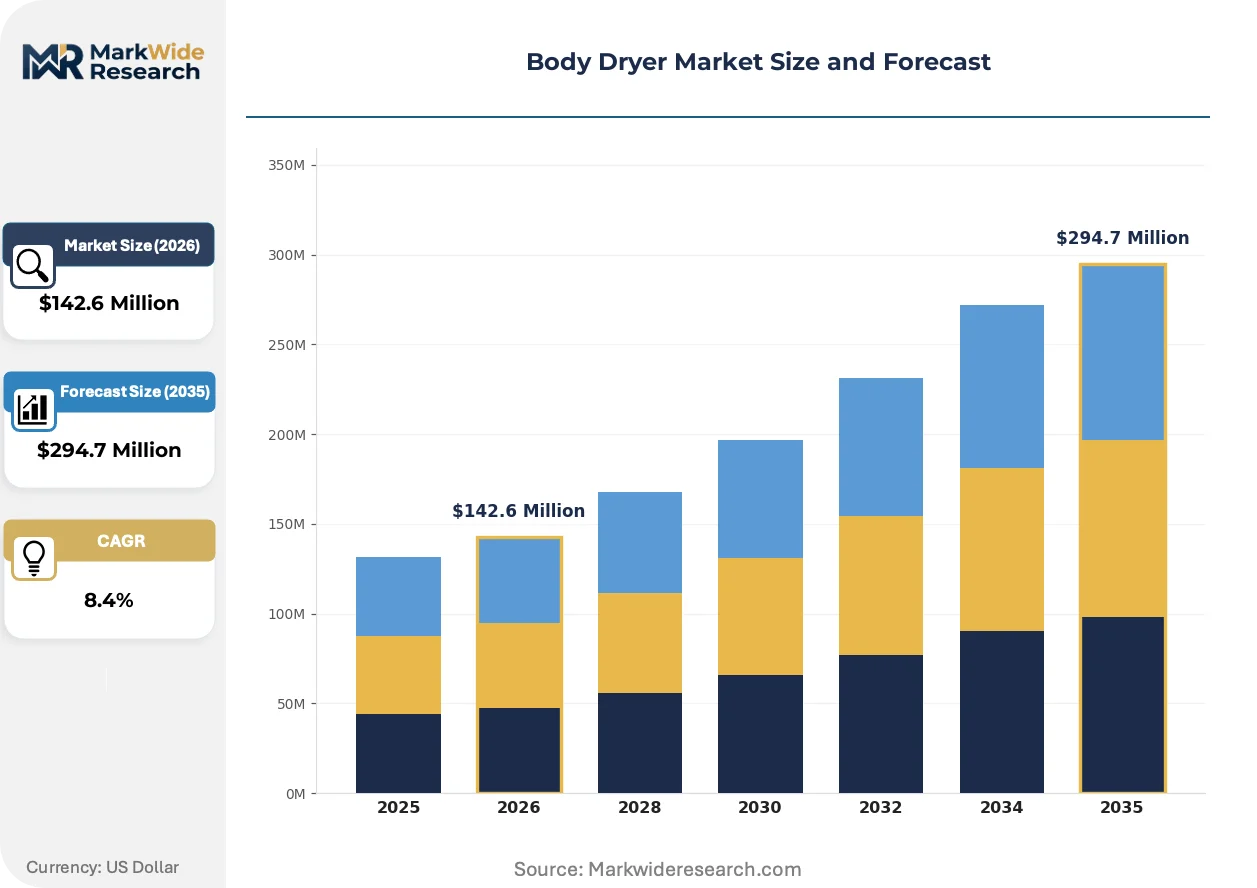
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $294.7 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Portable, Professional, Automated End User: Residential, Commercial, Institutional, Spa Technology: Infrared, Convection, High-Pressure Air, Combination Installation Type: Built-In, Free Standing, Integrated, Standalone |
| Companies Covered | Avant Innovations, Dolphy India Private Limited, Full Body Dryer LLC, Haystack Dryers, Kingkraft, Tornado Body Dryer, LLC, Valiryo, Orchids International, Regal Care Shower Trays Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Dryer Market Strategic Shifts & Innovations
Product architecture is fragmenting into modular subsystems that separate airflow generation from housing and control electronics, enabling configuration flexibility across residential and commercial channels.
Combination convection and high-pressure air systems are modularizing around interchangeable motor and heating cartridges that allow field technicians to upgrade performance tiers without full unit replacement. Luxury hotel operators in Germany and Japan are specifying these configurable platforms to standardize maintenance protocols across property portfolios. This architecture is compressing replacement part lead times while expanding aftermarket revenue capture for installation service providers.
EU Ecodesign requirements for bathroom appliances are tightening minimum efficiency thresholds and filtering uncertified imports from mass-market distribution channels in member states. Manufacturers must now submit full lifecycle energy consumption data to maintain CE marking validity. Commercial new-build specifications in France and the Netherlands are responding by mandating Ecodesign-compliant appliances in public facility tenders.
Facility managers in institutional care settings are consolidating vendor relationships around single-source contracts that bundle equipment, installation, and preventive maintenance. This purchasing pattern is displacing fragmented procurement across separate electrical, plumbing, and accessibility contractors. The United Kingdom's NHS-affiliated care facilities demonstrate this concentration most visibly, where multi-site operators negotiate enterprise pricing for standardized body dryer deployments.
Body Dryer Market Segmentation
Body dryer procurement splits sharply between fixed infrastructure investments and flexible equipment deployments. Understanding these divides clarifies where specification power sits with architects versus facility managers.
Product Type:
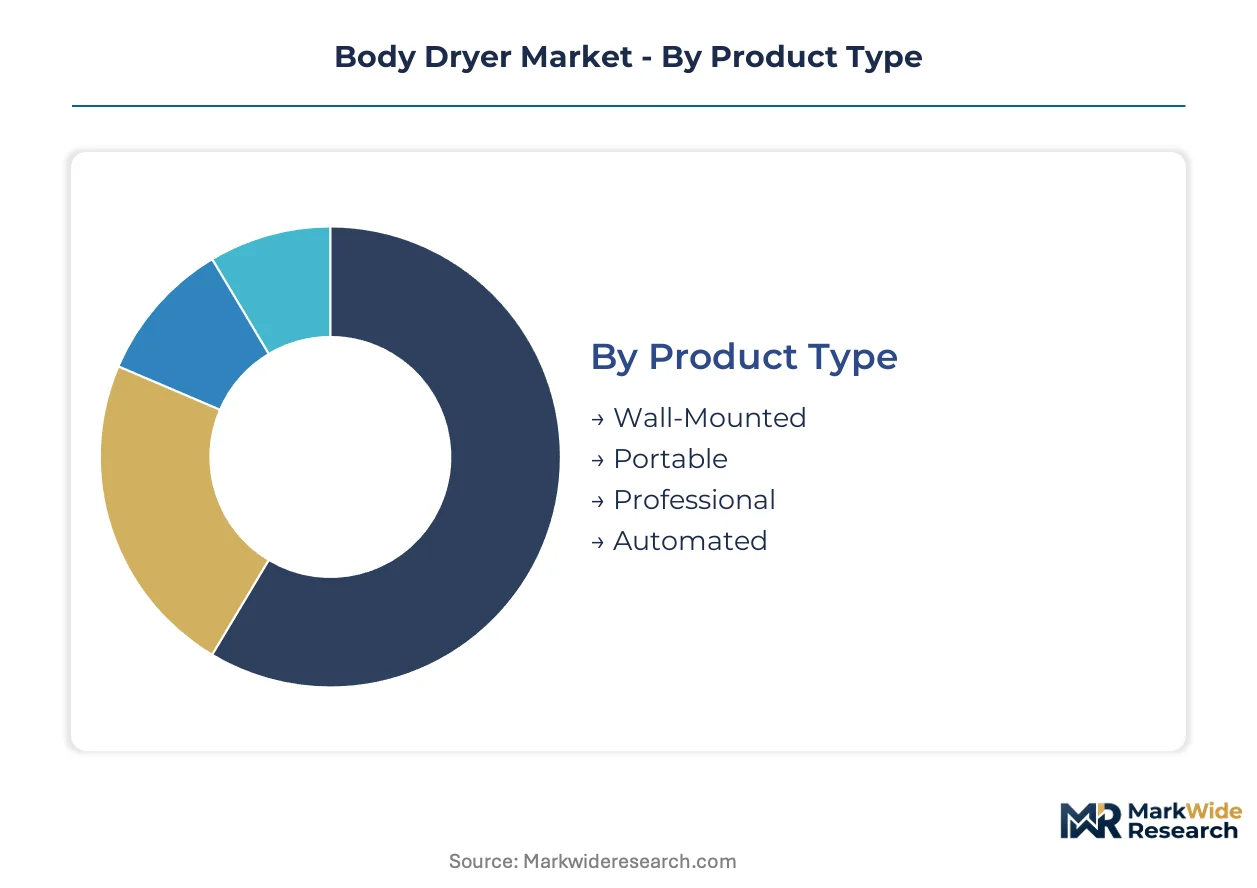
Wall-mounted units embed permanently into bathroom architecture, while portable variants serve temporary or rental applications without structural modification.
- Wall-Mounted:Flush-installation housings integrate with grab bars and ADA-compliant bathroom retrofits. Demand clusters in United States aging-in-place renovations where floor space constraints eliminate freestanding alternatives.
- Portable:Compact convection modules deploy without electrical hardwiring. Wellness centers in Germany and Japan specify these for temporary thermal therapy installations and seasonal capacity expansion.
- Professional:High-velocity units engineered for continuous-duty cycles in institutional settings.
- Automated:Sensor-activated systems with programmable drying protocols for premium hospitality environments.
Volume placements concentrate in wall-mounted configurations; the faster expansion belongs to portable systems.
End User:
Customer archetypes range from individual homeowners to enterprise procurement teams managing multi-site standardization.
- Residential:Individual households purchasing through retail channels or contractor specifications. Aging-in-place bathroom renovations in the United States drive retrofit demand for grab-bar-integrated installations.
- Commercial:Luxury hotel operators and wellness center chains in Germany and Japan specify infrared-equipped units for thermal therapy positioning.
- Institutional:NHS-affiliated care facilities in the United Kingdom consolidate vendor relationships around bundled equipment and maintenance contracts.
- Spa:Thermal therapy environments where perceived wellness associations justify premium equipment procurement.
Commercial hospitality generates the highest unit value; institutional channels are climbing the fastest as bundled procurement displaces fragmented contracting.
Technology:
Heating and airflow mechanisms determine energy efficiency profiles and regulatory compliance pathways across jurisdictions.
- Infrared:Radiant heat panels positioned for perceived therapeutic benefit. Spa end-user segments in Germany and Japan specify these for thermal therapy associations that accelerate replacement cycles.
- Convection:Forced-air heating through compact modules. Chinese OEM capacity pivots toward European certification standards, reshaping component sourcing for finished-goods assemblers.
- High-Pressure Air:Compressed airflow systems for rapid moisture removal in commercial new-build projects.
- Combination:Integrated convection and infrared subsystems with interchangeable motor cartridges. Field technicians upgrade performance tiers without full unit replacement, compressing maintenance lead times for luxury hotel operators.
Convection modules dominate current volume; combination systems show the steepest expansion trajectory where energy-recovery ventilation codes apply.
Installation Type:
Integration depth determines whether specification occurs during construction or through later retrofit, with significant implications for electrical contractor involvement.
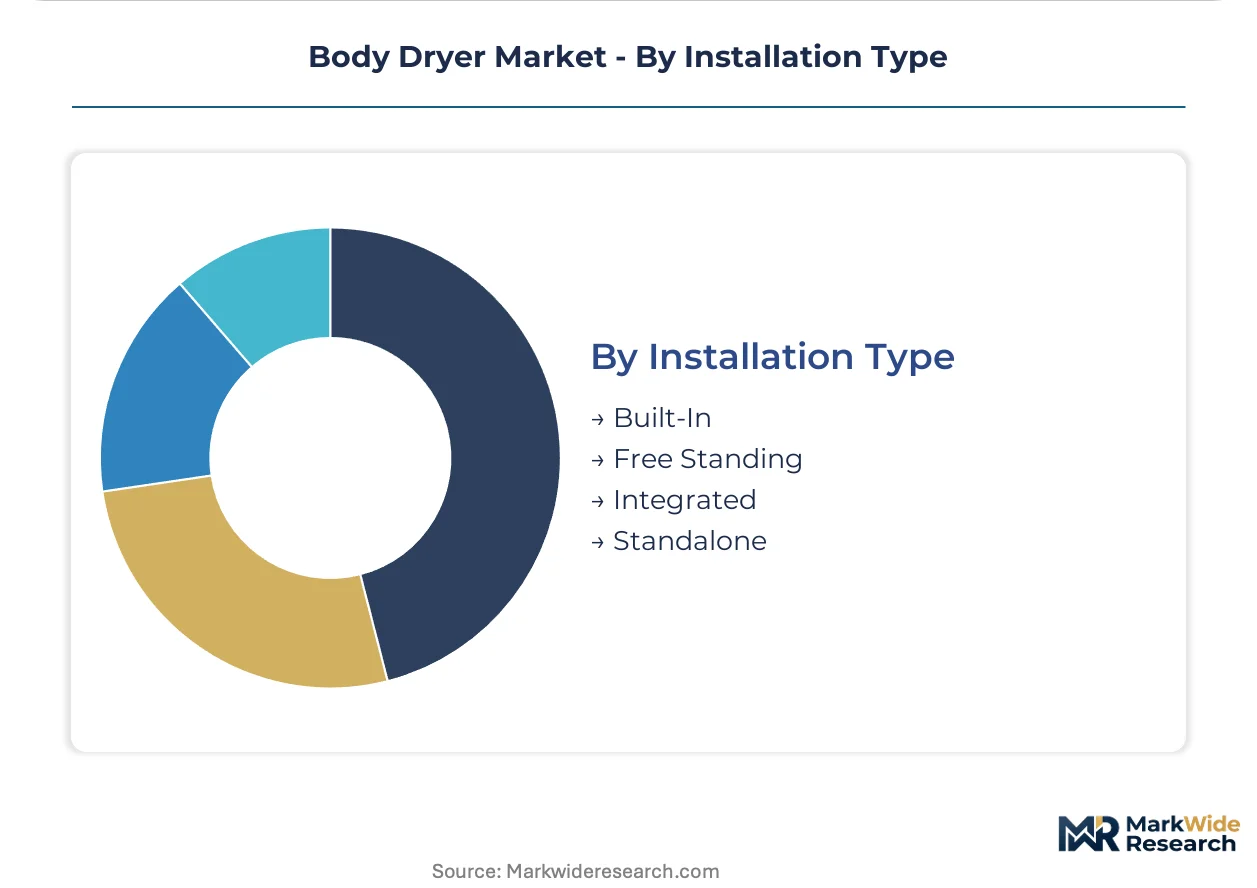
- Built-In:Units recessed into wall cavities during new construction or gut renovations. Specifications concentrate in commercial new-build projects where energy-recovery ventilation codes mandate appliance efficiency thresholds.
- Free Standing:Self-supporting housings requiring no structural modification. Rental properties and temporary wellness installations favor these for deployment flexibility.
- Integrated:Systems bundled with bathroom fixture suites for unified aesthetic and control interfaces.
- Standalone:Single-function units with independent power and control systems.
Built-in configurations anchor new construction specifications; free standing variants are gaining share fastest in rental and temporary deployment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and rare-earth magnet supply chains anchor manufacturing investment decisions across the United States, Germany, Japan, China, and the United Kingdom, with each market responding to distinct regulatory and demographic pressures.
United States
Aging-in-place bathroom renovations and ADA-compliant retrofits drive residential demand for wall-mounted installations. EPA WaterSense labeling mandates filter uncertified imports from federal procurement channels. Installations concentrate in Florida retirement communities and California multi-generational housing developments where grab-bar integration is standard specification.
Germany
Luxury hospitality construction and thermal therapy wellness centers specify infrared-equipped units for premium positioning. EU Ecodesign requirements tighten minimum efficiency thresholds for CE-marked appliances entering mass-market distribution. Manufacturing clusters in Bavaria and Baden-Württemberg assemble convection modules using Chinese OEM components recertified to European standards.
Japan
Spa operators and institutional care facilities replace conventional towel systems with automated drying appliances under water-efficiency targets. METI enforces PSE electrical safety standards that concentrate approval timelines for infrared and high-pressure air technologies. Tokyo and Osaka metropolitan areas lead retrofit penetration in hotel and senior care segments.
China
OEM capacity for compact convection modules pivots toward European and North American certification standards, reshaping component export flows. The country's national quality regulator enforces GB standards for household electrical appliances that domestic manufacturers must satisfy before accessing developed markets. Yangtze River Delta fabrication clusters supply motor assemblies and heating cartridges to Western European finished-goods assemblers.
United Kingdom
NHS-affiliated care facilities consolidate vendor relationships around bundled equipment and maintenance contracts. Institutional procurement displaces fragmented contracting across separate electrical, plumbing, and accessibility trades. Installations concentrate in Midlands and North England care home networks where multi-site operators negotiate enterprise pricing for standardized deployments.
Body Dryer Market Key Industry Players
Global majors compete with regional champions across certification expertise and distribution channel access. Market structure fragments across three tiers: CE-marked European specialists, North American direct-to-consumer operators, and Asian OEM fabricators supplying component modules. Two strategic archetypes dominate: vertically integrated manufacturers controlling motor and heating cartridge production, and assembly-focused firms sourcing standardized subsystems from contract suppliers. Competitive moves concentrate on dual-certification product development and preventive maintenance service bundling for institutional accounts.
Among Spain-based manufacturers, Valiryo S.L. exemplifies the European specialist archetype through its Basque production base and sustained CE-marked output. Full Body Dryer LLC occupies a position within the North American direct-to-consumer tier, while Haystack Dryers anchors UK institutional channel access. Kingkraft represents the care-sector specialization vector, and Tornado Body Dryer, LLC sits within the residential retrofit-focused segment. These five named entities illustrate geographic and channel diversification patterns without exhaustively cataloging market presence.
| Leading Market Players |
|---|
| Avant Innovations |
| Dolphy India Private Limited |
| Full Body Dryer LLC |
| Haystack Dryers |
| Kingkraft |
| Tornado Body Dryer, LLC |
| Valiryo |
| Orchids International |
| Regal Care Shower Trays Ltd. |
| Others |
Cost & Logistics Intelligence
EPA WaterSense procurement mandates in United States federal buildings are filtering uncertified imports and forcing suppliers to absorb certification costs, compressing margins for mid-tier assemblers while concentrating pricing power with dual-certified manufacturers.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier vendors from unbundled transactional competitors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and installation service inclusion. Price differentiation hinges on CE marking and PSE approval status, with fully certified units commanding substantial premiums. Pricing pressure stems from copper and rare-earth magnet cost volatility in motor assemblies. Institutional buyers in NHS-affiliated care facilities demonstrate lowest price sensitivity due to bundled procurement contracts, while budget hospitality chains remain highly sensitive.
Supply Chain Analysis
Dual-sourcing requirements from European finished-goods assemblers are forcing Chinese OEMs to maintain parallel certification inventories for CE-marked and domestic GB-standard outputs. Manufacturing concentrates in China, Germany, and the United States. Component sourcing draws from Yangtze River Delta motor clusters, Bavarian assembly plants, and Basque production bases. Copper windings and rare-earth permanent magnets constitute critical input dependencies. Single-source vulnerability concentrates in Japanese PSE testing capacity for infrared technologies. Distribution runs through electrical contractors in North American residential channels and direct institutional contracting in United Kingdom care sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PSE certification bottlenecks in Japan constrain infrared and high-pressure air technology throughput, propping pricing for approved suppliers across the projection horizon.
For Market Incumbents: Acquire captive motor assembly capacity to secure supply of rare-earth magnet components against Chinese OEM volatility. Consolidate certification expertise around dual CE-PSE marking to defend against emerging Asian competitors. Channel control through NHS-affiliated care facility maintenance contracts creates switching-cost barriers. For New Entrants and Emerging Players: EU Ecodesign requirements in France and the Netherlands open a window for Ecodesign-compliant convection modules in public facility tenders. White-space targets include ADA-compliant residential retrofits in Florida retirement communities and seasonal portable deployments in German wellness centers. Go-to-market through electrical contractor certification programs accelerates North American penetration. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists given captive component supply and dual-certification asset scarcity. Long-term viability favors manufacturers controlling upstream motor and heating cartridge production. Watch PSE approval timeline compression as the inflection signal for Japanese market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | CE and PSE marking unlocks European and Japanese distribution channels simultaneously. |
| Preventive Maintenance Bundling | NHS-affiliated care facilities consolidate procurement around single-source service contracts. |
| Modular Subsystem Development | Interchangeable motor cartridges enable field upgrades without full unit replacement. |
| ADA-Compliant Product Line | Grab-bar integration captures United States aging-in-place renovation demand. |
| Chinese OEM Recertification | CE-marked component supply reshapes sourcing flexibility for Western European assemblers. |
Research Approach
Trade databases, regulatory filing repositories, and customs export records formed the secondary backbone for this analysis. Primary interviews with electrical contractors, hotel procurement managers, NHS facilities directors, and spa operators validated demand-side assumptions. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, end user, technology, and installation type dimensions.
Historical trendline analysis identified inflection points in certification-driven procurement shifts and water-efficiency mandate adoption. Segmentation modeling incorporated product architecture, technology convergence patterns, and regional regulatory cluster variations. CAGRs derived from curve-fitting procedures applied to validated baseline data points. Key forecast inputs included EPA WaterSense penetration rates and EU Ecodesign compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for combination convection-infrared systems would alter the outlook if energy-recovery ventilation codes accelerate faster than projected. Forecasts reflect assumptions about PSE certification capacity expansion and copper price stabilization. Deviation in rare-earth magnet supply constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Germany Consumer Appliances Market
Appliances
UAE Microwave Ovens Market
Appliances
AI Washing Machine Market
Appliances
Qatar Microwave Ovens Market
Appliances
United States Washing Machine Market
Appliances
Digital Showers Market
Appliances
Portable Fridges Market
Appliances
Laundry Kiosk Market
Appliances
Small Electric Kettles Market
Appliances
China Washing Machine Market
Appliances
Electric Dryers Market
Appliances
Global Massage Chairs Market
Appliances
GCC Dishwashers Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Minibar Refrigerators Market
Appliances
Shared Shoe Washing Machine Market