
 Electrical Appliances Plastics Market | 2026-2036
Electrical Appliances Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Appliances Plastics Market Foresight
Asset-light leasing models for injection molding equipment are reshaping competitive entry in electrical appliances plastics, lowering capital barriers for mid-tier compounders serving appliance OEMs. BASF SE leverages its integrated styrenics chain to secure long-term supply contracts with white-goods manufacturers across Europe. SABIC anchors its position through high-heat polycarbonate grades engineered for induction cooktop housings and power-tool enclosures. Covestro AG differentiates via bio-attributed polycarbonate streams certified under ISCC PLUS for premium consumer electronics applications.
Electrical appliances plastics encompass engineered thermoplastics and thermosets formulated for dielectric strength, thermal stability, and flame retardancy in components ranging from circuit breaker housings to refrigerator liner films, typically specified to UL 94 V-0 or equivalent ignition-resistance standards and processed through injection molding at melt temperatures between 220°C and 320°C depending on base resin. These materials insulate live conductors, reduce appliance weight versus metal alternatives, and enable complex geometries that consolidate multi-part assemblies into single molded components. ABS and polycarbonate dominate material selection for visible consumer electronics housings where surface aesthetics and impact resistance carry premium specification weight, while nylon compounds capture share in power-tool and major-appliance segments requiring continuous-use thermal performance above 150°C. Injection molding remains the volume manufacturing backbone, though 3D printing is penetrating prototyping and spare-part production for legacy appliance lines where tool steel economics fail.
The EU Ecodesign Directive and REACH chemical restrictions are tightening permissible additive packages in flame-retardant formulations, forcing compounders to requalify halogen-free systems with appliance OEMs. FDA and UL standards in the United States govern food-contact and electrical-safety performance for plastics used in kitchen appliances and power tools, creating dual-certification burdens for suppliers serving transatlantic customers. China's GB standards and dual carbon goals are pushing domestic appliance manufacturers toward recycled-content resins, reshaping procurement criteria for plastics suppliers with verified post-industrial or post-consumer feedstock streams. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in formulations that satisfy one geography but fail another.
Market Dynamics
The EU Ecodesign Directive's tightening energy-efficiency and material-recovery mandates are forcing appliance OEMs to requalify entire polymer portfolios, compressing compounder lead times and concentrating procurement among integrated suppliers with certified halogen-free formulations.
Growth Catalysts
- REACH chemical restrictions:Halogen-free flame-retardant requalification is accelerating demand for specialized polymer grades that meet both ignition-resistance and environmental compliance thresholds in white-goods manufacturing.
- Induction cooktop OEMs:High-heat polycarbonate specifications for power-tool and cooking-appliance housings are pulling engineering resin volumes beyond traditional ABS substitution limits.
- Rhine-Ruhr manufacturing belt:Proximity sourcing from integrated compounders near appliance assembly plants is reducing logistics costs and customs exposure for German white-goods producers.
Market Restraints
- Styrene monomer volatility:ABS and polycarbonate feedstock costs swing with benzene-cracker margins, squeezing compounder margins during upstream petrochemical tightness.
- Tool steel economics:Legacy injection molding infrastructure requires six-figure capital commitments per cavity, blocking mid-tier compounders from multi-cavity appliance contracts.
- Regulatory divergence:UL 94 V-0 certification in the United States fails to satisfy REACH additive restrictions in Europe, forcing dual-formulation inventory for transatlantic suppliers.
Strategic Opportunities
- China's dual carbon goals:GB standards are pushing domestic appliance manufacturers toward verified post-industrial and post-consumer resin streams, creating first-mover advantage for suppliers with ISCC PLUS certification.
- 3D printing convergence:Fused deposition modeling for legacy appliance spare parts is bypassing tool steel economics entirely, opening service revenue from discontinued product lines.
- Bio-attributed polycarbonate:Premium consumer electronics brands are specifying mass-balance-certified resins for visible housings, commanding price premiums over conventional grades.
Industry Challenges
- Flame-retardant formulation chemists:The talent pool for halogen-free additive package development is thin across compounder R&D departments, extending requalification timelines with appliance OEMs.
- Dual-certification burden:FDA food-contact approval layered atop UL electrical-safety testing for kitchen-appliance plastics stretches validation cycles to 18-24 months.
- Legacy ERP integration:Mass-balance certification requires blockchain or equivalent chain-of-custody tracking that conflicts with established resin batching systems at older compounding facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Appliances Plastics Market |
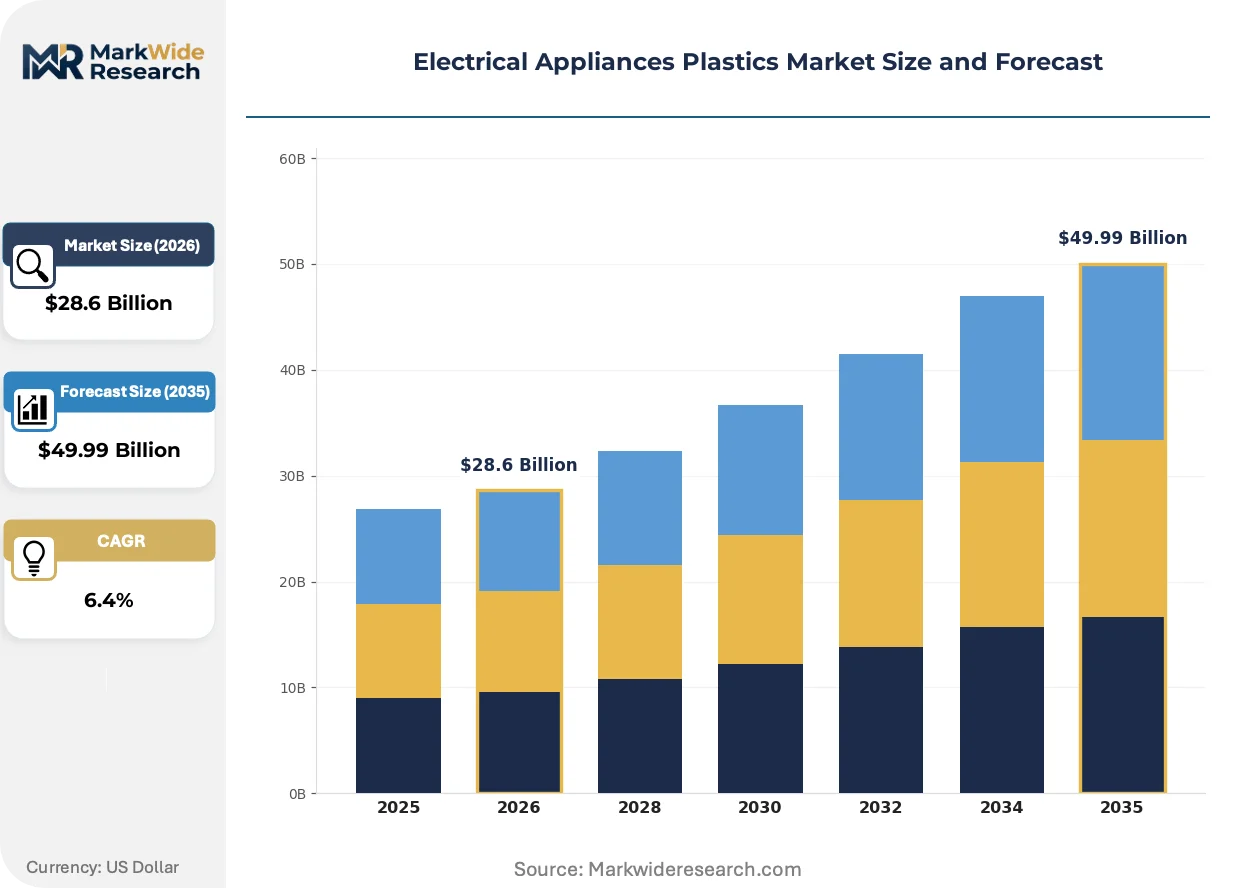
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Housings, Insulators, Connectors, Switches Application: Consumer Electronics, Major Appliances, Lighting, Power Tools Material: ABS, PC, Nylon, PVC Technology: Injection Molding, Extrusion, 3D Printing, Blow Molding |
| Companies Covered | INEOS Styrolution Group GmbH, BASF SE, SABIC, Covestro AG, LyondellBasell Industries Holdings B.V., LG Chem, ExxonMobil Corporation, Trinseo S.A., Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Appliances Plastics Market Shifts & Advancements
Material science and manufacturing process evolution are compressing the traditional trade-off between flame retardancy, mechanical performance, and aesthetic finish in appliance-grade polymers.
Halogen-free phosphorus-nitrogen flame-retardant systems are achieving UL 94 V-0 ratings at lower loadings than legacy brominated additives. European appliance OEMs are specifying these grades for visible housings where surface quality cannot tolerate plate-out or bloom. This chemistry shift is rendering obsolete the long-standing assumption that halogen-free formulations must sacrifice impact strength or color stability.
REACH restrictions on persistent organic pollutants are tightening permissible additive packages in electrical goods sold across the European Union. Compounders must now requalify entire color concentrate portfolios to exclude restricted substances, forcing reformulation of masterbatches that previously served multi-decade appliance platforms. Kitchen-appliance segments with food-contact surfaces face the steepest compliance burden under overlapping EFSA and ECHA jurisdictions.
Asset-light leasing models for injection molding equipment are penetrating mid-tier compounder strategy. Appliance OEM procurement teams are sourcing molded components from contract manufacturers who rent rather than own press capacity, fragmenting volume concentration among smaller suppliers. Germany's Mittelstand compounders are capturing share through this channel by offering certified resin-to-part solutions without capital-intensive captive molding operations.
Electrical Appliances Plastics Market Segmentation
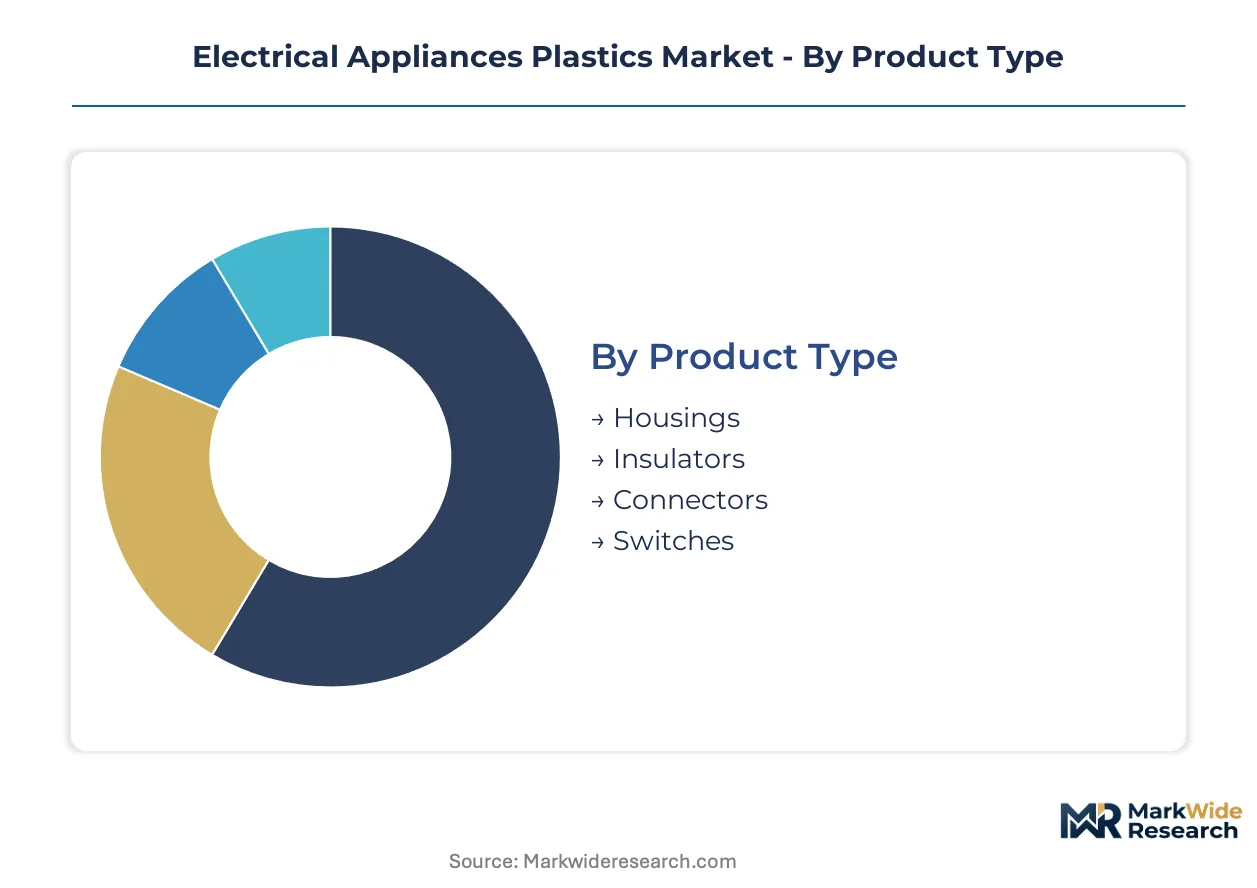
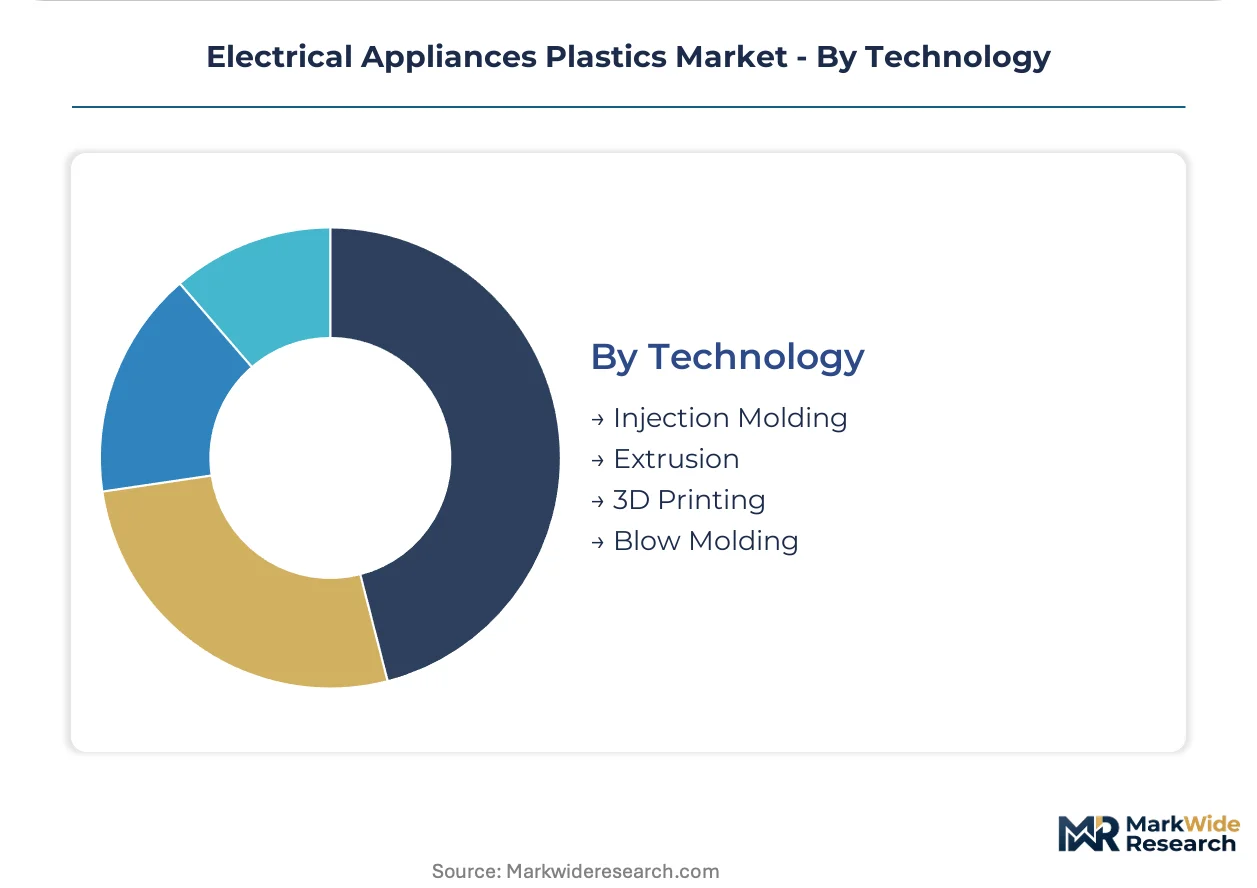
Segmentation in electrical appliances plastics reveals how material specifications, manufacturing processes, and end-use requirements fragment procurement decisions across appliance OEMs. Each dimension carries distinct certification burdens and supply chain configurations that compounders must navigate to secure volume contracts.
Product Type:
After-sales service intensity varies sharply across product types, with housings requiring cosmetic replacement parts decades post-sale while connectors demand minimal field servicing.
- Housings:Visible exterior shells formulated for UL 94 V-0 flame retardancy and surface aesthetics. German white-goods manufacturers specify these in high-heat polycarbonate for induction cooktops, driven by EU Ecodesign Directive material-recovery mandates. By volume, housings lead. By growth pace, insulators are climbing the fastest.
- Insulators:Dielectric components separating live conductors in circuit breakers and power distribution units. Demand concentrates in power-tool OEMs requiring continuous thermal performance above 150°C, constrained by REACH restrictions on halogenated additive packages.
- Connectors:Precision-molded interface components for internal wiring harnesses. These require tight dimensional tolerances and creep resistance under electrical load.
- Switches:Actuator housings and contact supports in control panels. Specifications prioritize arc resistance and mechanical cycle life over cosmetic finish.
Application:
Cost tier stratification separates premium consumer electronics from price-sensitive major appliance segments, with compounders calibrating resin grades and certification investments accordingly.
- Consumer Electronics:Premium visible housings where surface aesthetics and impact resistance command specification weight. Bio-attributed polycarbonate streams certified under ISCC PLUS are gaining traction among brands targeting sustainability positioning.
- Major Appliances:Refrigerator liners, dishwasher tubs, and washing machine drums requiring food-contact approval and chemical resistance. FDA compliance layered atop UL electrical-safety testing stretches validation cycles to 18-24 months for kitchen-appliance plastics.
- Lighting:Heat-resistant enclosures for LED drivers and fixture housings. Thermal management requirements pull specialized grades from integrated compounders.
- Power Tools:Nylon compounds capture dominant share here for continuous-use thermal performance and mechanical durability under vibration and impact loads.
Material:
Volume concentration favors commodity-engineered thermoplastics, while specialty grades extract margin premiums through certified supply chains and technical service bundling.
- ABS:Acrylonitrile-butadiene-styrene copolymers dominate consumer electronics housings for cost-effective impact strength and processability. Styrene monomer volatility squeezes compounder margins during upstream petrochemical tightness.
- PC:Polycarbonate resins engineered for high-heat applications including induction cooktop housings. SABIC anchors market position through specialized grades for visible appliance surfaces.
- Nylon:Polyamide compounds specified for power-tool and major-appliance segments requiring thermal performance above 150°C under continuous mechanical load.
- PVC:Polyvinyl chloride retains niche positions in wire insulation and gasketing where flexibility and cost minimization outweigh engineering performance requirements.
Technology:
Capital intensity separates process categories, with injection molding demanding six-figure cavity investments while additive manufacturing bypasses tool steel economics entirely.
- Injection Molding:Volume manufacturing backbone for complex geometries consolidating multi-part assemblies. Asset-light leasing models are penetrating mid-tier compounder strategy in Germany's Mittelstand.
- Extrusion:Continuous profile production for refrigerator liner films and wire insulation sheathing. Process economics favor high-volume, low-complexity geometries.
- 3D Printing:Fused deposition modeling penetrates prototyping and legacy appliance spare-part production where discontinued product lines fail tool steel economics.
- Blow Molding:Hollow-forming process for fluid reservoirs and air ducts in washing machines and dishwashers. Limited penetration versus injection molding in electrical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in engineered polymer compounds for appliance manufacturing, exporting specialized grades across the EU while importing commodity styrenics from Rotterdam and Antwerp terminals. China dominates resin throughput but remains a net importer of certified halogen-free formulations for premium white-goods export. The United States balances domestic ABS production with specialty polycarbonate imports for induction-cooktop OEMs.
Germany
White-goods manufacturers along the Rhine-Ruhr belt source flame-retardant housings from integrated compounders within 150-kilometer radii. REACH restrictions on halogenated additives force quarterly reformulation cycles at compounders serving Miele and Bosch production lines. The Ruhr industrial cluster concentrates mass-balance-certified polycarbonate compounding for premium consumer electronics brands.
China
Domestic appliance OEMs under GB standards accelerate procurement of ISCC PLUS-certified post-industrial resins for export-bound refrigerators. Dual carbon goals imposed by MEE tighten recycled-content verification requirements through 2030. The Yangtze River Delta hosts the densest concentration of compounders qualified for both EU Ecodesign and US UL 94 V-0 dual certification.
United States
Kitchen-appliance manufacturers face FDA food-contact approval layered atop UL electrical-safety testing, stretching validation cycles to 18-24 months. EPA oversight of persistent organic pollutants influences flame-retardant additive selection for dishwasher and refrigerator liner films. The Southeast manufacturing corridor from South Carolina to Tennessee attracts compounders seeking proximity to Whirlpool and GE Appliance assembly plants.
Japan
Power-tool OEMs in the Osaka-Kobe industrial zone specify nylon compounds for continuous-use thermal performance above 150°C. METI energy-efficiency standards for home appliances tighten material-recovery specifications, pulling specialized grades from domestic compounders. The Chubu region around Nagoya anchors high-heat polycarbonate development for induction-cooktop exports to European markets.
South Korea
Consumer electronics brands specify bio-attributed polycarbonate streams for visible housings targeting sustainability-positioned export segments. MFDS food-contact regulations intersect with KC electrical-safety marks for kitchen-appliance plastics, creating dual-certification complexity. The Seoul Capital Area concentrates compounding capacity serving Samsung and LG Electronics appliance divisions.
Electrical Appliances Plastics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin formulation and additive masterbatch supply. The vendor base organizes around three tiers: integrated petrochemical majors with captive styrenics chains, independent compounders leasing injection molding capacity, and regional distributors holding certified inventory for appliance OEM spot buying. Competitive moves concentrate on backward integration into bio-attributed feedstock sourcing and strategic partnerships with mass-balance certification bodies.
Among German-based integrated suppliers, BASF SE and Covestro AG occupy positions defined by certified polymer streams and Ecodesign Directive compliance depth. SABIC anchors the high-heat polycarbonate segment through specialized grades for visible appliance surfaces. These three exemplify how geographic proximity to Rhine-Ruhr manufacturing clusters combines with regulatory certification depth to secure long-term supply contracts.
| Leading Market Players |
|---|
| INEOS Styrolution Group GmbH |
| BASF SE |
| SABIC |
| Covestro AG |
| LyondellBasell Industries Holdings B.V. |
| LG Chem |
| ExxonMobil Corporation |
| Trinseo S.A. |
| Toray Industries, Inc. |
| Others |
Supply & Pricing Matrix
Rhine-Ruhr freight corridors linking Rotterdam-Antwerp petrochemical terminals to German compounding facilities transmit benzene-cracker margin volatility directly into appliance OEM procurement costs, concentrating pricing power among integrated suppliers with captive styrenics chains while fragmenting margin capture among toll compounders dependent on spot resin purchases.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the electrical appliances plastics market. Pricing stratifies across ISCC PLUS-certified premium grades, REACH-compliant standard formulations, and economy tiers with legacy halogenated additives. Cost compression in commodity ABS runs through styrene monomer volatility from European cracker turnarounds. Appliance OEM procurement teams exhibit highest price sensitivity in visible housing segments where aesthetic specifications command brand premiums, while power-tool manufacturers show lowest sensitivity for nylon compounds delivering thermal performance above 150°C.
Supply Chain Analysis
Export-control restrictions on advanced polymer additive technologies limit flows of proprietary phosphorus-nitrogen flame-retardant packages from German compounders to certain Asian markets. Supply concentrates in Germany, China, and South Korea for engineered thermoplastics, with benzene-derived styrenics and bisphenol-A feedstock dependencies creating upstream tethering to Rotterdam-Antwerp and Singapore-Jurong chemical hubs. Single-source vulnerability concentrates around halogen-free formulation chemists qualified for dual UL 94 V-0 and REACH certification. Distribution runs through integrated compounder-direct channels for volume appliance OEMs, with regional distributors holding certified inventory for spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German white-goods OEMs through procurement consolidation along the Rhine-Ruhr belt, forcing compounders to absorb certification costs and compress lead times to maintain volume allocation.
For Market Incumbents: Pre-empt margin erosion from asset-light leasing competitors by securing exclusive resin-to-part contracts with Miele and Bosch through embedded technical service teams. Backward integration into bio-attributed feedstock sourcing under ISCC PLUS certification creates defensible positioning against commodity ABS suppliers. Lock in multi-year supply agreements before REACH additive restrictions tighten further. For New Entrants and Emerging Players: Southeast Asian appliance manufacturing clusters in Vietnam and Indonesia present underpenetration for halogen-free polycarbonate grades as regional OEMs seek EU Ecodesign compliance for export-bound production. Target power-tool OEMs in Japan's Osaka-Kobe zone with nylon compounds certified for continuous-use thermal performance above 150°C. Establish toll compounding partnerships with established injection molders to bypass tool steel capital requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded appliance plastics divisions lacking REACH certification depth. Five-to-ten year viability favors compounders with mass-balance tracking infrastructure and proven dual-certification timelines under 18 months. Monitor EU Ecodesign Directive amendment cycles as inflection indicators for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Attributed Feedstock | Captures ISCC PLUS premiums from consumer electronics brands specifying mass-balance-certified housings. |
| Halogen-Free Formulation R&D Partnership | Addresses talent scarcity in phosphorus-nitrogen flame-retardant chemistry through university-compounder collaboration. |
| Asset-Light Injection Molding Leasing | Enables mid-tier Mittelstand compounders to serve appliance OEMs without six-figure cavity investments. |
| Dual Certification Fast-Track Program | Compresses FDA food-contact and UL electrical-safety validation cycles for kitchen-appliance plastics. |
| Legacy Spare-Part 3D Printing Service | Bypasses tool steel economics for discontinued appliance lines through fused deposition modeling capacity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings from petrochemical majors, Cefic industry reports, and appliance OEM procurement disclosures. Plant managers at German compounding facilities, procurement leads at Bosch and Miele, technical R&D directors from integrated suppliers, and distribution channel partners across the Rhine-Ruhr belt provided operational validation. Bottom-up volume modeling from resin throughput data triangulates against top-down value estimates from contract pricing intelligence.
Forecast inputs span grade tier, end-use application, certification level, and regional production hub across the projection horizon. CAGRs derive from segmented growth rate analysis calibrated to appliance production forecasts and regulatory implementation timelines. Styrene monomer price elasticity, REACH additive restriction phase-in schedules, and China's dual carbon goal compliance trajectories inform scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by commodity resin producers would shift outcomes through vertical price squeeze. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Rice Cooker Market
Appliances
UAE Microwave Ovens Market
Appliances
Refrigerator Door Seal Market
Appliances
Laundry Appliances Market
Appliances
Mexico Washing Machine Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Electric Fan Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
US Portable Washing Machines Market
Appliances
Toaster Ovens Market
Appliances
Colombia Laundry Appliances Market
Appliances
Smart Dishwasher Market
Appliances
Laundry Dryer Market
Appliances
Cooler Connected to the Mains Market
Appliances
Smart Connected Washing Machine Market