
 Smart Connected TV Market | 2026-2036
Smart Connected TV Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected TV Market Insights
Hospitality deployment is repositioning Smart Connected TV procurement toward managed-content solutions with centralized fleet control. Samsung Electronics leverages vertical integration from semiconductor foundries to finished displays, sustaining margin capture across the stack. LG Electronics differentiates through OLED panel chemistry leadership, dominating premium residential segments in North America and Europe. TCL anchors volume competitiveness through captive supply of LCD substrates from its CSOT division, competing aggressively in mid-tier global markets.
A Smart Connected TV integrates broadcast and broadband reception with an embedded operating system enabling over-the-top streaming, interactive services, and voice-controlled navigation through a minimum 4K resolution panel with HDR10 or Dolby Vision compliance. The device functions as the central display and compute node for residential and commercial entertainment ecosystems. LED and QLED product types currently occupy the largest installed base due to manufacturing scale and accessible price positioning, though OLED commands the premium margin pool where color accuracy and contrast ratio drive specification. AI-enabled technology integration is expanding fastest as on-device neural processing enables real-time upscaling, personalized content recommendation, and adaptive audio calibration without cloud dependency.
FCC equipment authorization requirements govern RF emissions and cybersecurity baseline compliance for US market entry, while CE marking under EU directives mandates energy efficiency labeling and restricted substance thresholds under RoHS. China's MIIT enforces GB standards for network access and content encryption modules, shaping product architecture for Asia-Pacific distribution. Stakeholders must monitor divergence between regional content licensing frameworks and hardware security mandates when allocating platform development resources.
Market Dynamics
Streaming service bundling is compressing hardware refresh cycles as households treat Smart Connected TVs as disposable compute nodes rather than decade-long investments. FCC digital standard updates and HDMI specification revisions accelerate replacement demand across residential and commercial segments.
Growth Catalysts
- HDMI 2.1 Specification Mandates:Broadcast infrastructure upgrades in the United States require backward-compatible display hardware, pulling forward enterprise procurement timelines for hospitality and education sectors.
- China:Domestic panel manufacturing capacity expansion at CSOT and BOE facilities reduces landed costs for Asia-Pacific distribution, enabling aggressive pricing in mid-tier segments.
- AI Neural Processing:On-device upscaling and adaptive audio calibration reduce cloud dependency, lowering latency for interactive gaming applications and driving specification upgrades.
Market Restraints
- Display Panel Concentration:South Korean and Chinese substrate suppliers control upstream LCD and OLED wafer supply, creating margin compression risk for finished goods assemblers.
- Content Licensing Fragmentation:Regional exclusivity agreements between streaming platforms and studios fragment software ecosystems, limiting cross-border hardware standardization.
- Input Cost Volatility:Rare earth element pricing for quantum dot phosphors and OLED emitter materials fluctuates with mining output from concentrated extraction zones.
Strategic Opportunities
- India:PLI scheme incentives for electronics manufacturing attract panel assembly investments, creating localized supply for price-sensitive household upgrades.
- Healthcare Waiting Room Deployment:Managed-content solutions with centralized fleet control penetrate outpatient clinic networks, expanding commercial addressable market beyond hospitality.
- Matter Protocol Convergence:Smart home interoperability standards enable cross-brand voice control integration, reducing platform lock-in friction for multi-device households.
Industry Challenges
- Firmware Security Certification:MIIT network access permits and FCC cybersecurity baselines require parallel testing protocols, extending product launch timelines by quarters.
- Legacy Hospitality Infrastructure:Property management system integration with proprietary coaxial distribution networks demands custom engineering for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected TV Market |
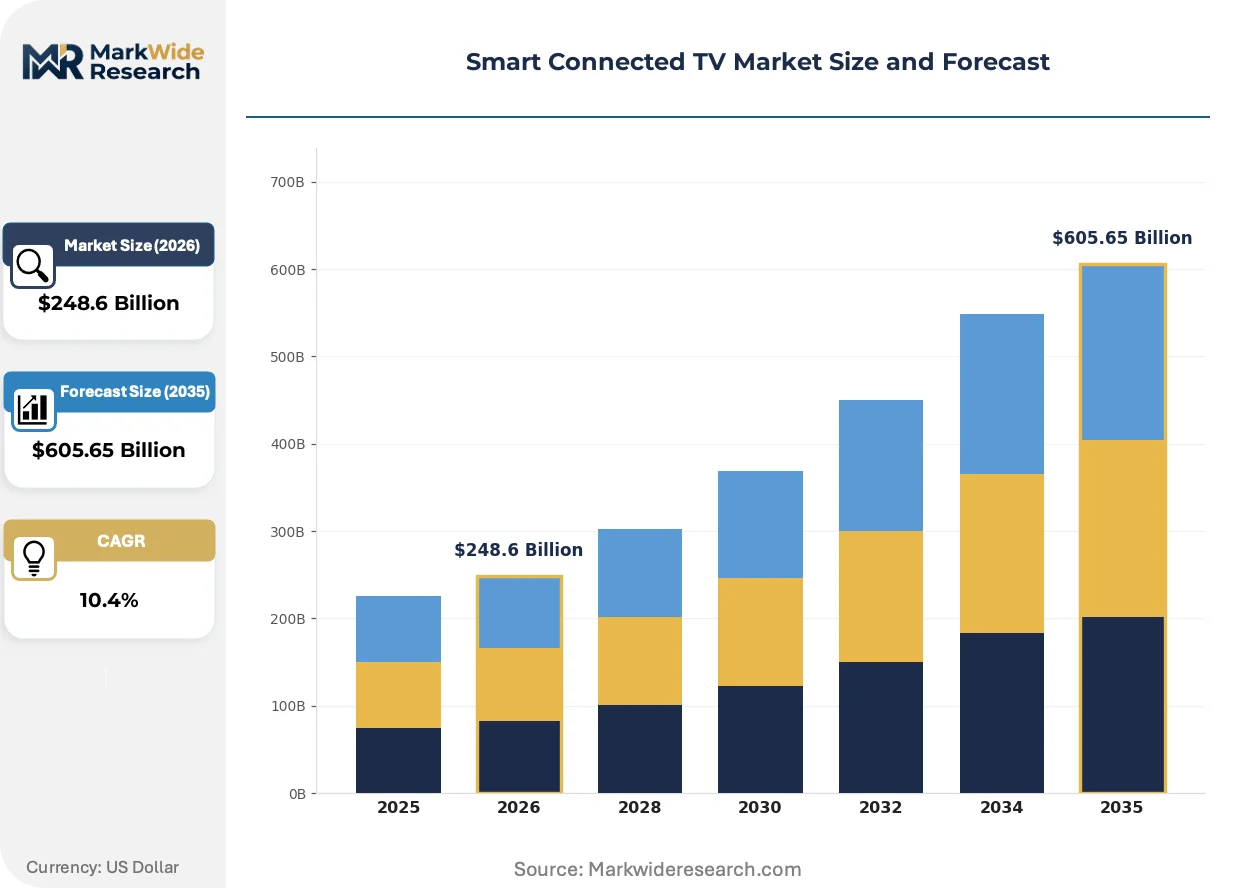
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $605.65 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, Mini-LED Technology: Streaming, Internet Protocol, Cloud-Based, AI-Enabled End User: Residential, Commercial, Hospitality, Educational Distribution Channel: Online Retail, Offline Retail, Wholesalers, Direct Sales |
| Companies Covered | Hisense, Xiaomi, Samsung Electronics, Vizio, Panasonic, LG Electronics, Sony Corporation, Skyworth, TCL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected TV Market Trends and Innovations
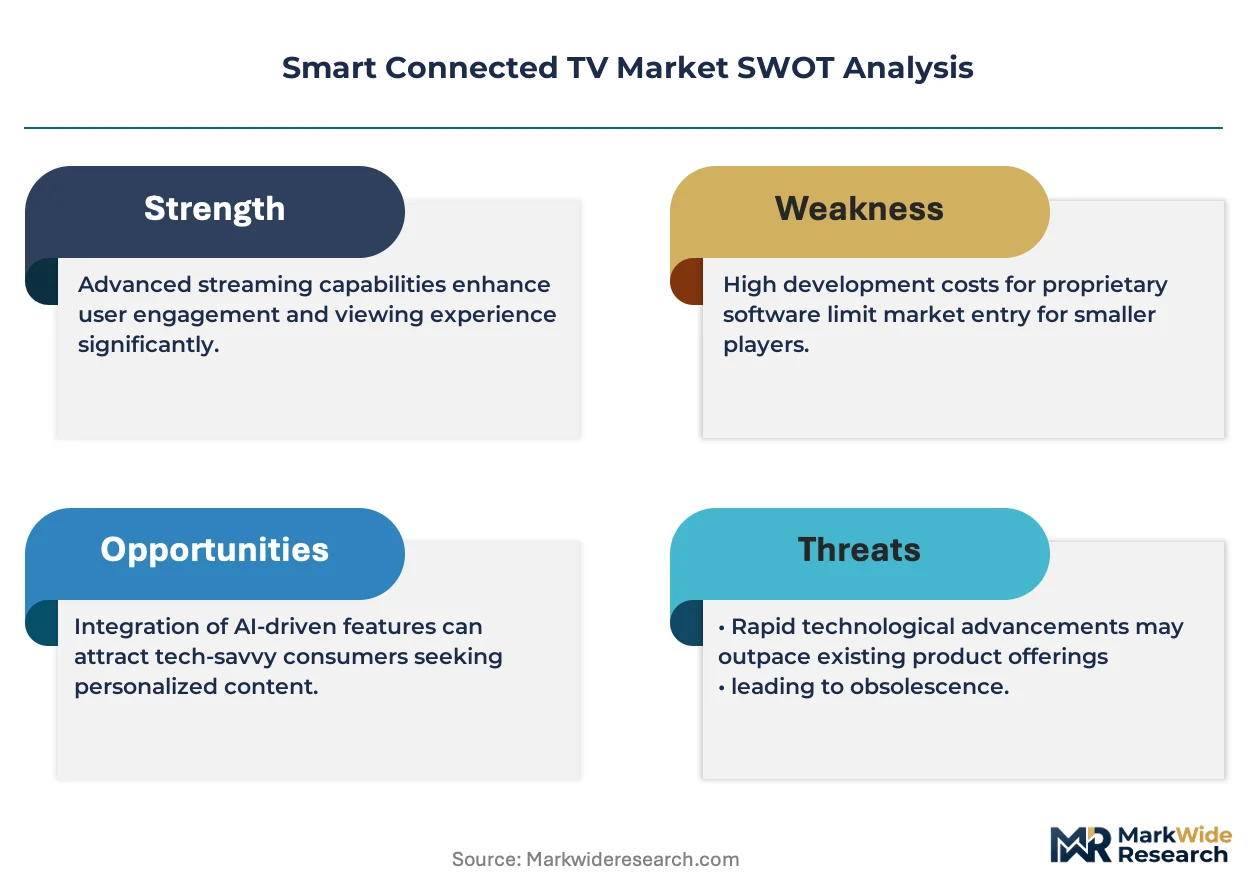
AI-enabled processing is migrating from cloud to edge, compressing the value chain between semiconductor foundries and finished display assembly. This shift reconfigures competitive advantage toward neural engine architecture and thermal management expertise.
MicroLED display technology is consolidating the premium residential segment as Samsung and Apple supplier partnerships drive manufacturing scale. Ultra-high-net-worth households in the United States and United Arab Emirates specify modular MicroLED walls above 100 inches, collapsing the distinction between television and architectural display. The technology is consolidating installation and calibration services into single-source provider relationships.
EU energy efficiency labeling under the Ecodesign Directive tightens standby power limits and mandates repairability scoring for displays above 32 inches. Manufacturers must redesign power supply architectures and publish spare parts availability timelines. Premium OLED product lines face the steepest compliance costs due to complex panel bonding processes that complicate field repair.
Commercial buyers in hospitality and healthcare are unbundling hardware procurement from content licensing, forcing manufacturers to compete on fleet management software rather than panel specifications alone. Managed service providers like Enseo and Sonifi displace traditional AV integrators in North American hotel deployments. This shift is most advanced in the United States, where property-level IT standardization enables centralized procurement at chain headquarters.
Smart Connected TV Market Segmentation
Smart Connected TV procurement patterns diverge sharply across display technologies, connectivity architectures, and deployment contexts. Hardware refresh cycles and platform ecosystem requirements reshape how each segment captures replacement demand from residential upgrades and commercial fleet renewals.
Product Type:
Upgrade cycles compress as households treat display hardware as disposable compute nodes rather than long-term investments, with panel chemistry and backlight architecture driving specification choices.
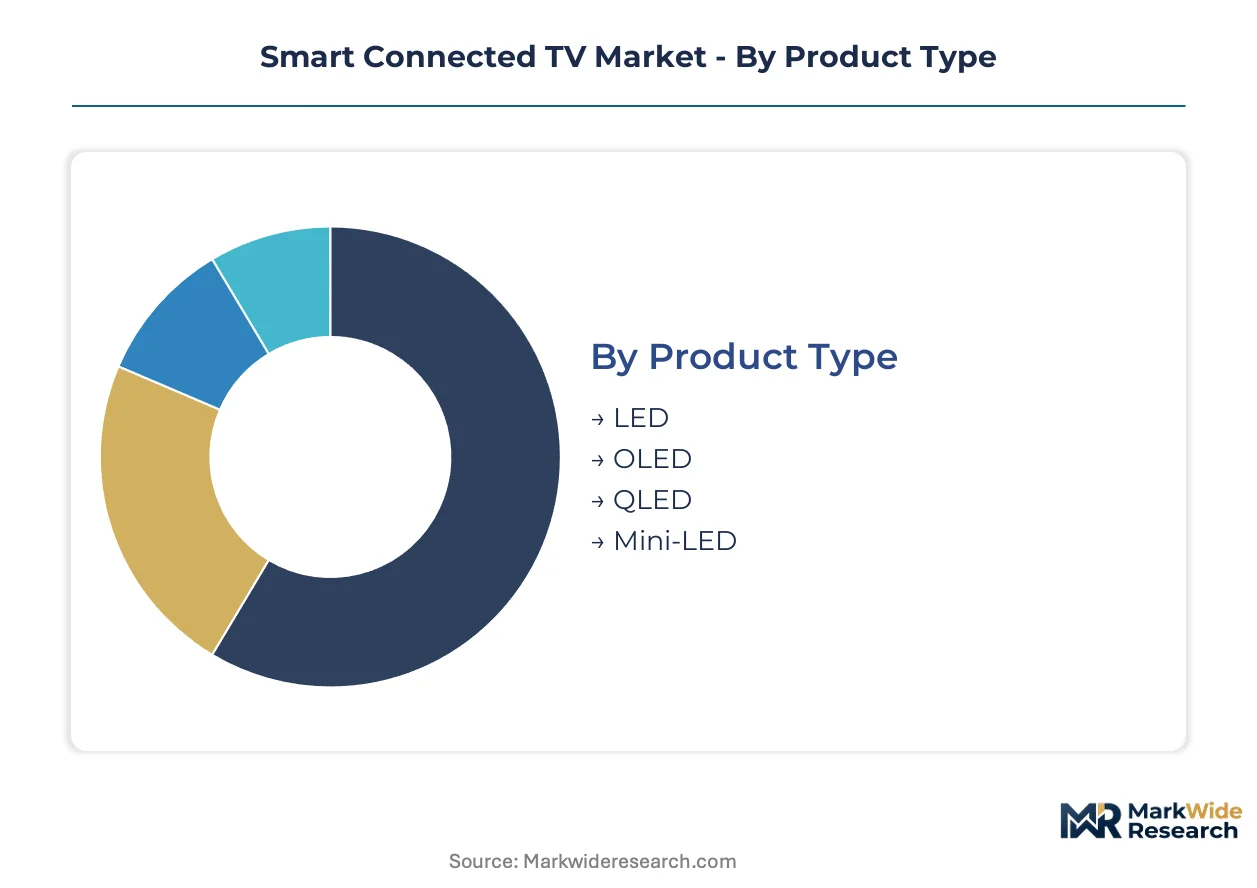
- LED:Edge-lit and direct-lit LCD configurations with quantum dot enhancement dominate volume production through manufacturing scale at Chinese fabs. Residential living rooms across India and Southeast Asia absorb the bulk of shipments as price-sensitive households prioritize screen size over contrast performance.
- OLED:Organic emitter stacks deliver self-emissive pixels with infinite contrast ratios and sub-millisecond response times. Premium residential segments in Germany, United Kingdom, and United States specify OLED for home cinema installations where color accuracy commands specification priority.
- QLED:Quantum dot film layers convert blue LED backlighting into narrow-spectrum primaries, achieving brightness levels above OLED limits for daylight-viewing environments.
- Mini-LED:Thousands of dimming zones enable localized contrast approaching OLED performance without burn-in risk, gaining traction in gaming-focused residential deployments.
LED sits at the top of the volume ranking, with Mini-LED climbing the fastest as backlight zone counts expand and manufacturing yields improve.
Technology:
Cost tier differentiation separates basic connectivity from intelligent processing capabilities, with neural engine integration commanding premium positioning.
- Streaming:Embedded applications for subscription video services require minimal processing overhead, saturating entry-level price bands where hardware margins compress to single digits.
- Internet Protocol:IP-based broadcast reception and multicast delivery enable operator-managed deployments in European cable markets, particularly France and Netherlands where hybrid broadcast-broadband standards prevail.
- Cloud-Based:Thin-client architectures offload computation to remote servers, reducing local hardware requirements but demanding persistent connectivity that limits deployment in bandwidth-constrained geographies.
- AI-Enabled:On-device neural processing units execute real-time upscaling, voice recognition, and adaptive audio calibration without cloud dependency, steepest expansion trajectory as gaming and interactive applications demand sub-50ms latency.
Streaming captures the largest installed base, while AI-Enabled expands most quickly as semiconductor foundries ship dedicated neural accelerators at consumer price points.
End User:
Application requirements dictate durability specifications, content management complexity, and fleet control architecture across deployment environments.
- Residential:Consumer-grade panels with standard warranty terms and streaming-centric software stacks account for the majority of unit shipments, concentrated in urban household formation corridors across China and United States.
- Commercial:Digital signage and corporate communication deployments prioritize brightness uniformity and extended operating hours, with procurement centralized through AV integrators and facilities management contracts.
- Hospitality:Managed-content solutions with centralized fleet control and property management system integration dominate hotel procurement, displacing traditional coaxial distribution in United States chain properties.
- Educational:Interactive whiteboard integration and device management at district scale drive K-12 and higher education specifications, with procurement timelines tied to fiscal year budget cycles.
Residential maintains volume leadership, with Hospitality gaining share fastest as managed service providers consolidate procurement at chain headquarters.
Distribution Channel:
Customer type and purchase scale determine channel selection, with enterprise procurement bypassing retail entirely while households fragment across physical and digital touchpoints.
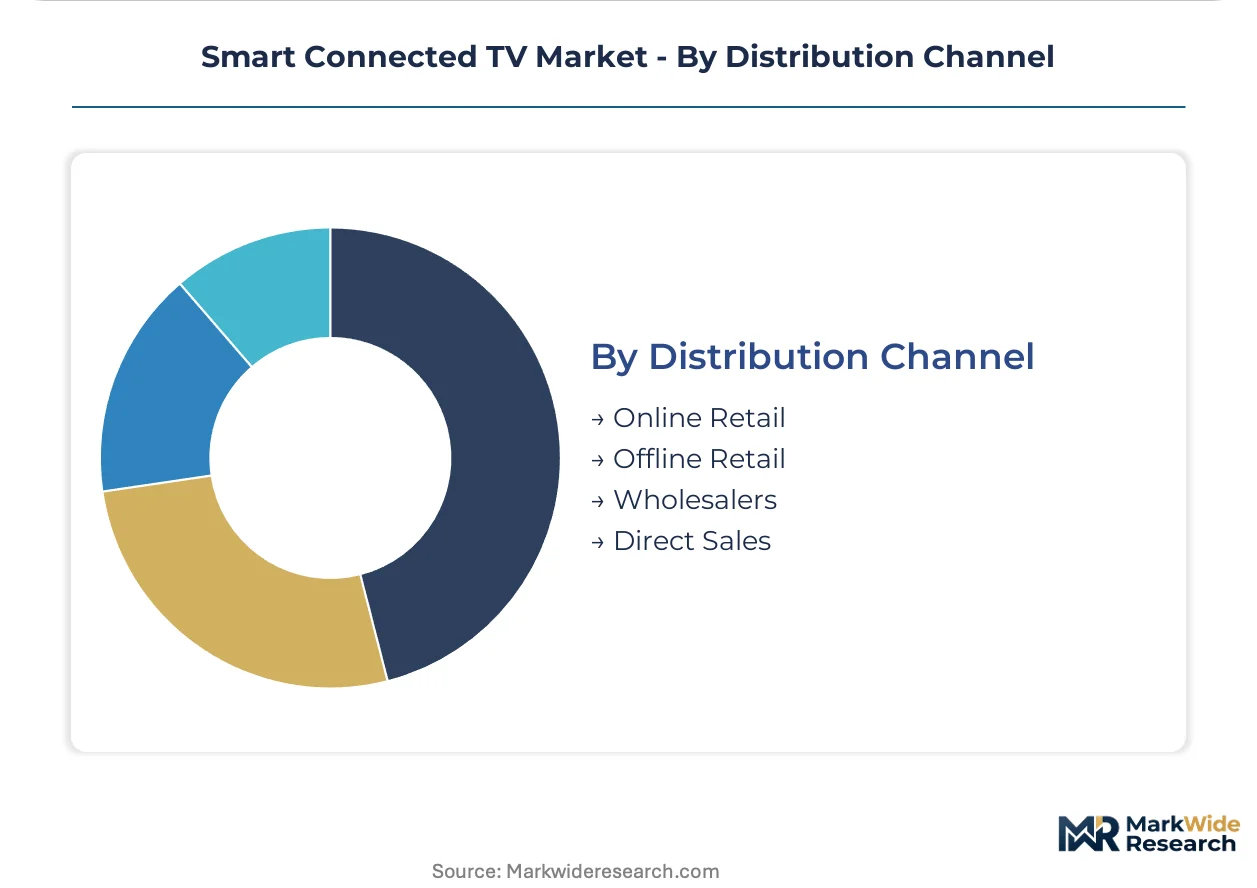
- Online Retail:E-commerce platforms capture consumer research and comparison shopping, with fulfillment logistics enabling screen sizes above 75 inches that challenge traditional retail inventory capacity.
- Offline Retail:Big-box electronics chains and manufacturer-owned flagship stores provide tactile evaluation for premium OLED and Mini-LED products where demonstration drives conversion.
- Wholesalers:Regional distributors aggregate volume for smaller retail chains and independent dealers, particularly in emerging markets where direct manufacturer presence remains limited.
- Direct Sales:Manufacturer field organizations manage enterprise and hospitality contracts with customized fleet management software and installation services bundled into multi-year agreements.
Online Retail leads transaction volume, with Direct Sales expanding most quickly as commercial buyers unbundle hardware from content licensing and demand integrated service relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where Smart Connected TV manufacturing concentrates, with compliance cost gaps between jurisdictions driving panel assembly migration and platform localization strategies.
United States
FCC equipment authorization mandates and HDMI 2.1 broadcast infrastructure upgrades accelerate hardware refresh cycles across hospitality and education sectors. The Inflation Reduction Act's energy efficiency incentives influence commercial procurement specifications. Austin and Silicon Valley clusters host streaming platform headquarters that shape content ecosystem requirements for North American hardware.
China
Domestic panel manufacturing capacity at CSOT and BOE facilities reduces landed costs and enables aggressive mid-tier pricing. MIIT network access permits and GB standards for content encryption modules enforce hardware architecture constraints. Yangtze River Delta manufacturing clusters integrate semiconductor foundries with finished display assembly for captive supply chain efficiency.
Germany
Premium residential demand for OLED home cinema installations concentrates in Munich and Berlin metropolitan corridors. EU Ecodesign Directive standby power limits and repairability scoring under RoHS compliance reshape power supply architectures. Stuttgart automotive supplier networks are pivoting thermal management expertise toward display panel applications.
South Korea
OLED emitter stack chemistry leadership anchors premium margin capture in global markets. Korean substrate suppliers control upstream wafer supply for both LCD and OLED technologies. Seoul-Suwon industrial corridor hosts vertically integrated semiconductor-to-display manufacturing complexes.
India
PLI scheme incentives for electronics manufacturing attract panel assembly investments serving price-sensitive household upgrades. BIS certification requirements and TRAI broadcast regulations shape product localization. Tamil Nadu and Karnataka industrial corridors are emerging as contract manufacturing hubs for Asia-Pacific distribution.
Smart Connected TV Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium residential markets consolidating around display technology leaders while volume tiers fragment across Chinese OEM networks. The vendor base organizes into three strategic archetypes: vertically integrated semiconductor-to-display conglomerates, panel-specialist brands with captive chemistry IP, and contract assemblers leveraging regional tariff engineering. Dominant competitive moves include foundry capacity reservations for neural accelerator supply and hospitality fleet management software acquisitions.
Among vertically integrated conglomerates, Samsung Electronics and LG Electronics occupy positions that exemplify full-stack margin capture from semiconductor fabrication through finished goods distribution. TCL represents the contract manufacturing archetype with captive LCD substrate supply from its CSOT division, anchoring mid-tier volume competitiveness. Hisense sits within the technology-licensing tier, leveraging QLED and laser display partnerships to diversify beyond conventional panel architectures.
| Leading Market Players |
|---|
| Hisense |
| Xiaomi |
| Samsung Electronics |
| Vizio |
| Panasonic |
| LG Electronics |
| Sony Corporation |
| Skyworth |
| TCL |
| Others |
Pricing and Supply Chain Analysis
Display panel substrate indices from Korean and Chinese wafer suppliers cascade through three pricing tiers, compressing margins for finished goods assemblers while concentrating value capture at the emitter chemistry and semiconductor foundry layers.
Pricing Analysis
Distributor margin layers separate premium OLED panels from economy LED configurations, with brand premiums and volume scale as the primary price differentiation drivers. Cost compression in mid-tier segments intensifies as Chinese fabs expand quantum dot film capacity. Residential households in India and Southeast Asia exhibit the highest price sensitivity, while ultra-high-net-worth buyers in the United States and United Arab Emirates prioritize specification over cost.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Seoul-Suwon, and Noida feed hub-and-spoke patterns into North American and European retail channels. The supply chain draws from concentrated OLED emitter material suppliers in South Korea and LCD substrate producers in China, with rare earth element volatility for quantum dot phosphors presenting persistent sourcing risk. Finished goods distribution runs through manufacturer-direct enterprise contracts for hospitality and healthcare fleets alongside e-commerce platforms for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where PLI scheme incentives in India undercut landed costs from China by 12-18% for Asia-Pacific distribution, rewarding assembly migration toward Tamil Nadu and Karnataka corridors.
For Market Incumbents: Hedge against OLED emitter supply concentration by securing multi-year wafer offtake agreements with Seoul-Suwon substrate suppliers. Channel control through direct sales organizations for hospitality fleet management software displaces retail margin erosion. Certification investment in MIIT network access permits and FCC cybersecurity baselines extends product launch timelines but locks out mid-tier competitors lacking parallel testing capabilities.
For New Entrants and Emerging Players: PLI scheme incentives in India open a window for contract manufacturing entry serving price-sensitive residential upgrades in South Asia. Healthcare waiting room deployments with managed-content solutions represent the most penetrable white-space segment beyond saturated hospitality chains. A go-to-market angle centered on Matter protocol interoperability reduces platform lock-in friction for multi-device households.
For Investors and Strategic Acquirers: Consolidation pressure builds where hospitality fleet management software capabilities fragment across hardware OEMs and pure-play service providers. Long-term viability favors targets with captive neural accelerator supply relationships and thermal management IP transferable to edge AI workloads. The signal to watch is property-level IT standardization velocity at North American hotel chains, which determines centralized procurement consolidation speed.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Accelerator Foundry Partnership | Samsung and Apple supplier relationships secure on-device AI processing capacity for real-time upscaling features. |
| Hospitality Fleet Management Acquisition | Managed service providers like Enseo displace traditional AV integrators through centralized content control platforms. |
| MicroLED Manufacturing Scale-Up | Modular wall installations above 100 inches collapse the distinction between television and architectural display categories. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu and Karnataka corridors attract panel assembly investments for Asia-Pacific price-sensitive segments. |
| EU Ecodesign Directive Compliance Redesign | Repairability scoring mandates reshape power supply architectures and spare parts availability timelines for premium OLED lines. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with display panel procurement directors, hospitality IT executives, semiconductor foundry planning officers, and streaming platform hardware ecosystem leads. Secondary validation draws from FCC equipment authorization filings, MIIT network access permit databases, EU Ecodesign Directive regulatory texts, and customs trade records for display panel substrate flows. Bottom-up shipment modeling and top-down value chain margin analysis triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include display technology chemistry, neural processing capability tier, end-use deployment context, and regional regulatory cluster. CAGRs derive from replacement cycle compression analysis and AI-enabled specification upgrade elasticity. Forecast inputs incorporate HDMI specification revision adoption curves and PLI scheme capacity buildout timelines without year-specific anchoring.
Revisions become necessary when rare earth element supply disruptions, streaming platform licensing fragmentation, or regional cybersecurity mandate divergence materialize beyond modeled scenarios. Forecasts reflect documented assumptions about panel manufacturing yield improvement trajectories and hospitality property management system integration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
North America Refurbished and Used Mobile Phones Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Europe Stylus Pen Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market