
 Asia-Pacific Refurbished and Used Mobile Phones Market | 2026-2036
Asia-Pacific Refurbished and Used Mobile Phones Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Refurbished and Used Mobile Phones Market Insights
Buyer concentration across Asia-Pacific's refurbished phone trade is rebalancing from informal street vendors toward organized online marketplaces and enterprise resellers. Flipkart Internet Private Limited anchors India's digital resale infrastructure through controlled logistics and quality verification protocols. Samsung Electronics Co., Ltd. competes in its own secondary market by extending certified refurbishment programs across multiple Asian markets. Back Market SAS navigates cross-border compliance complexity to position its marketplace model in Australia and Southeast Asia.
Refurbished and used mobile phones comprise pre-owned smartphones restored to functional working condition through battery replacement, component repair, software reset, and cosmetic grading against standardized quality tiers. These devices serve cost-conscious buyers seeking network-compatible hardware at reduced acquisition expense without factory-original warranty coverage. Refurbished units within the Product Condition dimension command premium pricing over used inventory due to verified component integrity and residual warranty terms. Online Marketplaces within Distribution Channel capture accelerating volume as platform authentication tools reduce information asymmetry between distant buyers and sellers.
India's BIS certification requirements and China's SAMR quality disclosure rules shape cross-border trade flows for refurbished devices entering formal retail channels. Australia's ACCC consumer guarantee framework and Japan's METI recycling directives impose distinct compliance burdens on importers and domestic refurbishers. Stakeholders must monitor divergence between national e-waste regulations and emerging right-to-repair mandates that could unlock captive refurbishment supply or restrict parts availability.
Market Dynamics
India's PLI scheme for electronics manufacturing is tightening quality benchmarks for refurbished device imports while simultaneously redirecting informal resale volumes into taxable channels. This regulatory pressure is compressing margins for unorganized traders and accelerating capital deployment into certified refurbishment infrastructure across Southeast Asian markets.
Growth Catalysts
- India's PLI scheme:Local manufacturing incentives raise import quality thresholds, forcing informal operators to upgrade testing protocols or exit formal retail channels entirely.
- 5G network expansion:Southeast Asian telecom operators bundle refurbished 5G-compatible devices with prepaid plans to capture price-sensitive subscribers upgrading from 2G/3G networks.
- Battery replacement automation:Vietnamese refurbishment clusters deploy robotic cell extraction systems that cut per-unit labor costs and extend device functional lifecycles.
Market Restraints
- Component supply concentration:OLED display and advanced camera module availability remains captive to original manufacturer allocation decisions, constraining refurbishment output for premium-tier devices.
- China's SAMR disclosure rules:Cross-border quality certification requirements create documentation friction that delays inventory turnover for marketplace sellers sourcing from Shenzhen trading hubs.
- Input cost volatility:Lithium-ion cell prices fluctuate with raw material spot markets, compressing margin predictability for battery replacement services.
Strategic Opportunities
- Enterprise fleet refresh cycles:Australian and Japanese corporate IT departments are formalizing buyback programs that channel decommissioned devices into certified resale pipelines.
- Right-to-repair mandates:Emerging legislation across multiple Asia-Pacific jurisdictions would unlock captive parts supply from original manufacturers currently restricting component access.
- Rural digital penetration:Indonesian and Philippine provincial markets remain underserved by organized resale infrastructure, presenting first-mover advantages for platform-based authentication services.
Industry Challenges
- Diagnostic technician scarcity:Certified repair capabilities lag demand growth across Vietnam and Indonesia, requiring training partnerships with original equipment manufacturers.
- Cross-border warranty enforcement:Marketplace platforms struggle to honor residual manufacturer warranties when devices transfer between jurisdictions with divergent consumer protection frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Refurbished and Used Mobile Phones Market |
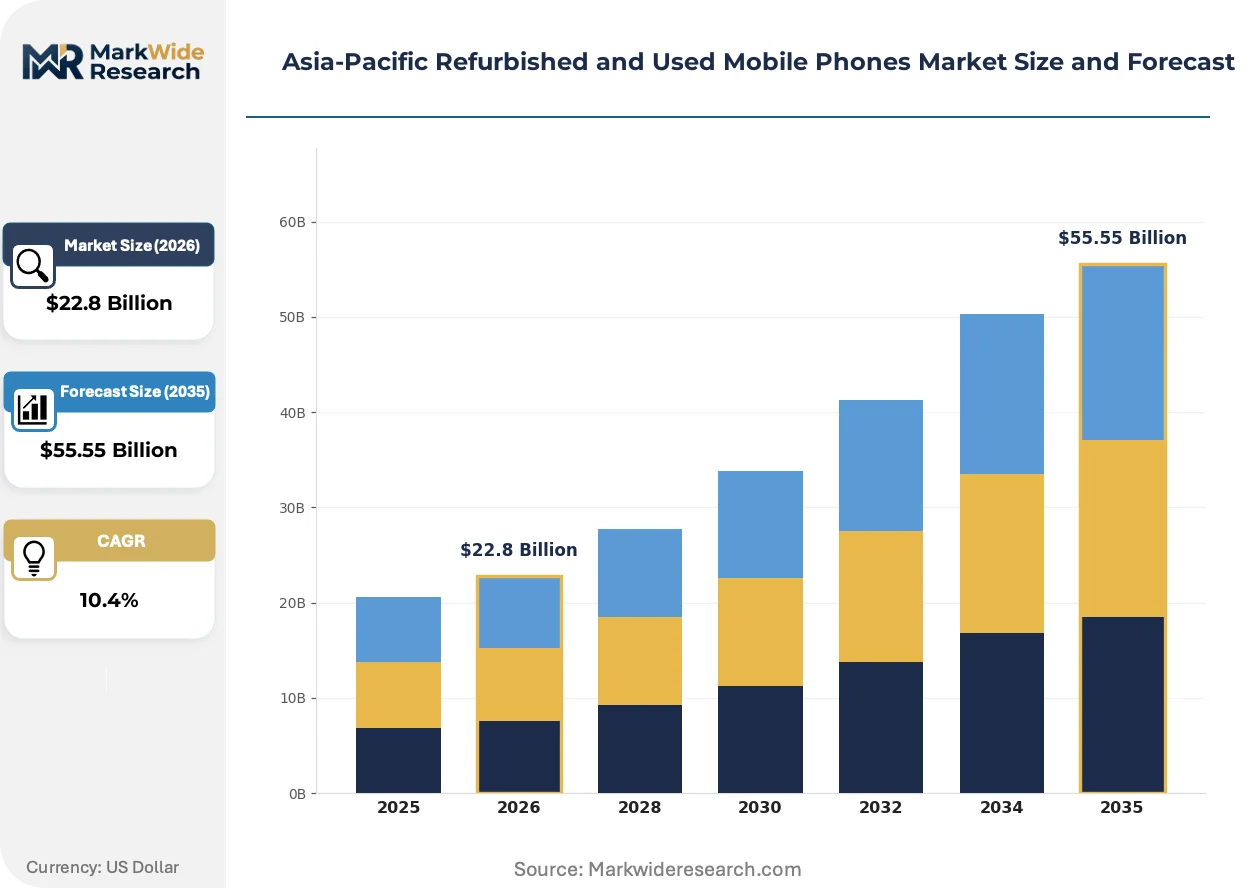
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $55.55 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Condition: Refurbished, Used, Like New, Damaged Brand: Apple, Samsung, Huawei, Xiaomi Distribution Channel: Online Marketplaces, Retail Stores, Direct Sales, Wholesalers Customer Type: Individual Consumers, Businesses, Resellers, Educational Institutions |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Xiaomi Corporation, Huawei Technologies Co., Ltd., Oppo Electronics Corp., Vivo Communication Technology Co., Ltd., Motorola Mobility LLC, Flipkart Internet Private Limited, Back Market SAS, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Refurbished and Used Mobile Phones Market Trends and Innovations
Platform-based authentication tools are compressing information asymmetry between distant buyers and sellers, fundamentally restructuring how trust is manufactured in secondary electronics markets. Three developments are accelerating this transformation.
Blockchain-based provenance tracking is unifying device history verification across fragmented supply chains. Southeast Asian marketplace operators deploy distributed ledger systems to record custody transfers, component replacements, and quality grading events. Individual consumers in Thailand and Malaysia now access immutable service records before purchase decisions, reducing return rates and enabling price premiums for documented refurbishment.
Australia's ACCC consumer guarantee framework is extending statutory warranty obligations to refurbished device importers. The regulator's enforcement actions against misleading "like new" claims are forcing marketplace sellers to standardize cosmetic grading terminology. Cross-border operators serving Australian buyers must now maintain domestic return infrastructure or face penalty exposure, raising competitive barriers for pure offshore sellers.
Enterprise procurement teams in Singapore and Hong Kong are unbundling device lifecycle management from traditional telecom contracts. Large employers now negotiate direct buyback arrangements with refurbishment specialists rather than accepting carrier trade-in valuations. This disintermediation captures residual value previously absorbed by network operators and redirects volume toward certified resale channels with transparent pricing mechanisms.
Asia-Pacific Refurbished and Used Mobile Phones Market Segmentation

Segmentation in Asia-Pacific's refurbished phone trade exposes where capital deployment, regulatory exposure, and margin capture concentrate. Condition grading and channel selection determine working capital intensity and compliance burden for operators across India, Vietnam, and Southeast Asian markets.
Product Condition:
Capital intensity escalates sharply from cosmetic-only processing to full component reconstruction. Battery replacement and motherboard repair demand the heaviest upfront tooling investment.
- Refurbished:Units undergo systematic component testing, battery replacement, and software restoration against standardized quality tiers. Indian BIS certification requirements and Vietnamese automation clusters drive demand toward certified refurbishment with verified warranty terms.
- Used:Devices sell as-is with minimal processing beyond data wipe and functional verification. Price-sensitive buyers across Indonesian and Philippine provincial markets absorb this inventory through informal street networks and unclassified online listings.
- Like New:Near-pristine returns from enterprise fleet cycles or buyer's remand. Minimal refurbishment cost supports premium positioning in Australian and Japanese formal retail channels.
- Damaged:Salvage-grade units sold for parts recovery or specialist repair. Shenzhen trading hubs and Ho Chi Minh City component markets absorb this flow for display and camera module extraction.
Most installed capacity flows through Refurbished. Expansion is steepest in Like New as enterprise buyback programs formalize.
Brand:
Brand segmentation maps directly to parts availability constraints and residual value retention. Proprietary component ecosystems determine refurbishment economics.
- Apple:Closed parts ecosystem and iOS device management restrictions limit third-party refurbishment scope. Australian ACCC enforcement and emerging right-to-repair pressures in South Korea and Japan are forcing component access concessions.
- Samsung:Certified refurbishment programs operate across multiple Asian markets with original manufacturer quality backing. Galaxy device volume supports dedicated refurbishment infrastructure in India and Vietnam.
- Huawei:Google Mobile Services absence reshapes resale value in markets dependent on Android app ecosystems. Domestic Chinese refurbishment channels absorb volume with HarmonyOS repositioning.
- Xiaomi:Aggressive pricing on new devices compresses secondary market premiums. Indian and Southeast Asian price-sensitive consumers drive volume through online marketplace flash sales.
Samsung and Apple dominate certified channel throughput. Xiaomi is gaining share fastest in unorganized resale penetration.
Distribution Channel:
Channel selection determines compliance exposure and customer acquisition cost structure. Platform authentication investments separate scalable operators from margin-compressed traders.
- Online Marketplaces:Platform-based verification tools and logistics integration reduce information asymmetry. Flipkart in India and regional platforms across Southeast Asia anchor volume with controlled quality protocols and return infrastructure.
- Retail Stores:Physical inspection enables immediate purchase decisions and cash transactions. Indian organized retail and Vietnamese electronics districts maintain foot traffic for condition-sensitive buyers.
- Direct Sales:Manufacturer-certified programs and enterprise fleet buyback arrangements capture residual value. Samsung's direct refurbishment channels and Australian corporate IT disintermediation drive this segment.
- Wholesalers:Bulk acquisition from enterprise refresh cycles and insurance salvage feeds downstream refurbishment. Shenzhen trading hubs and Singapore re-export operations concentrate cross-border wholesale flow.
Online Marketplaces capture the steepest volume growth. Retail Stores retain importance for rural Indonesian and Philippine market penetration.
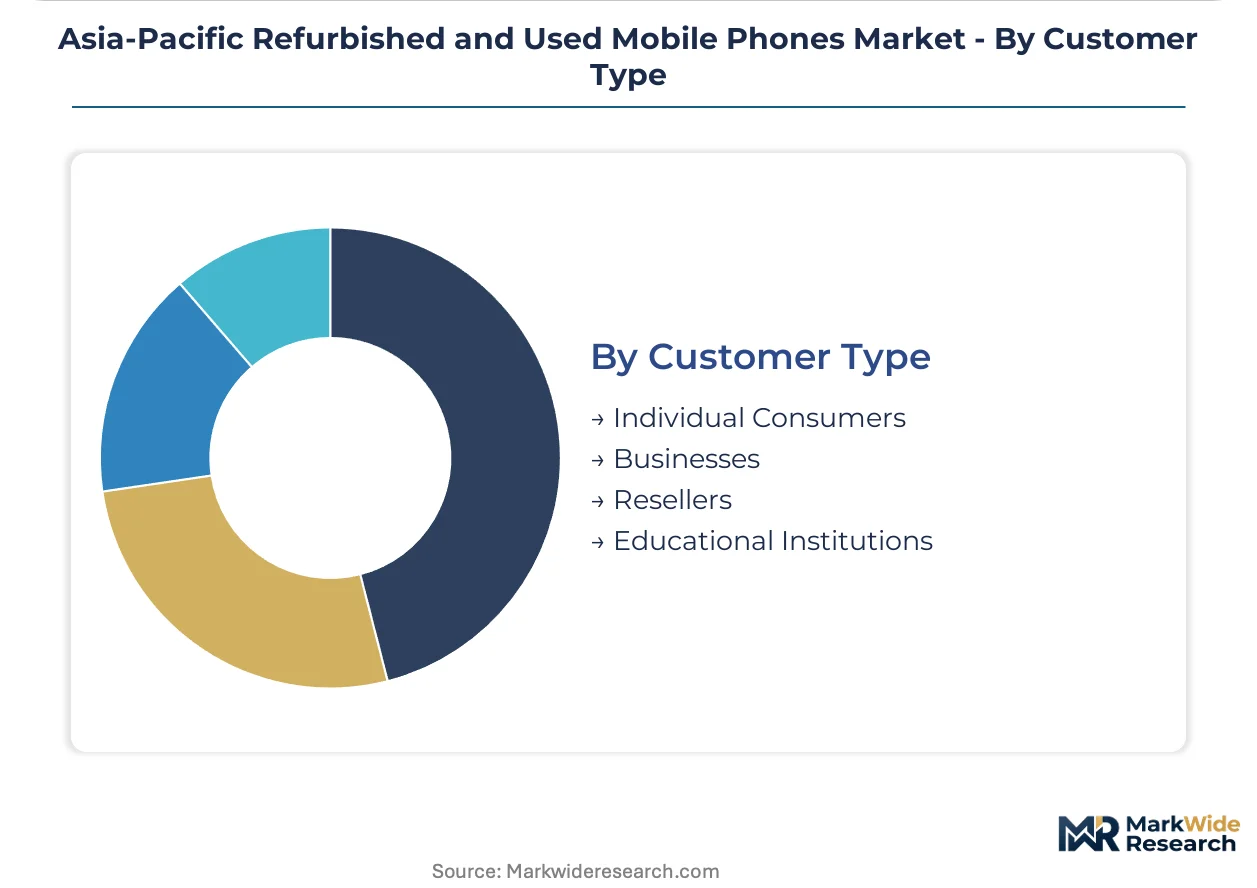
Customer Type:
End-user segmentation reveals diverging service requirements and price sensitivity profiles. Procurement formalization separates enterprise from consumer transaction patterns.
- Individual Consumers:Price-driven acquisition for personal use with variable warranty expectations. Southeast Asian smartphone penetration deepening and 5G network expansion in Indonesia and Philippines drive replacement demand.
- Businesses:Enterprise fleet management and employee device programs with standardized procurement requirements. Australian and Japanese corporate IT departments formalizing buyback arrangements redirect volume toward certified channels.
- Resellers:Intermediary traders operating across formal and informal channel boundaries. India's PLI scheme quality thresholds and China's SAMR disclosure rules are compressing margins for unorganized operators.
- Educational Institutions:Bulk procurement for student device programs with durability and support requirements. Indian state-level digital education initiatives and Australian tertiary sector fleet cycles generate concentrated demand.
Individual Consumers represent the largest addressable base. Businesses are formalizing procurement fastest with transparent pricing mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme quality thresholds diverge sharply from Vietnam's automation-driven refurbishment clusters, while Australia's ACCC enforcement creates distinct compliance architectures across the region.
India
Individual consumers in tier-2 and tier-3 cities drive volume as smartphone penetration deepens beyond metropolitan centers. The BIS certification requirements and PLI scheme for electronics manufacturing tighten import quality benchmarks and redirect informal resale into taxable channels. Refurbishment infrastructure concentrates in Delhi-NCR and Bengaluru, where organized players deploy controlled logistics and quality verification protocols.
Vietnam
5G network expansion by telecom operators bundles refurbished devices with prepaid plans to capture price-sensitive subscribers upgrading from legacy networks. Battery replacement automation through robotic cell extraction systems cuts per-unit labor costs and extends device functional lifecycles. Ho Chi Minh City hosts component markets that absorb salvage-grade units for display and camera module extraction.
Australia
Enterprise IT departments formalize buyback programs that channel decommissioned devices into certified resale pipelines with transparent pricing mechanisms. The ACCC consumer guarantee framework extends statutory warranty obligations to refurbished device importers and enforces standardized cosmetic grading terminology. Sydney and Melbourne anchor domestic return infrastructure requirements that raise competitive barriers for pure offshore sellers.
Japan
Corporate procurement teams disintermediate traditional telecom contracts to negotiate direct lifecycle management arrangements with refurbishment specialists. METI recycling directives impose distinct compliance burdens on domestic refurbishers and importers entering formal retail channels. The Kanto region around Tokyo concentrates enterprise fleet refresh cycles and certified refurbishment program deployment.
Indonesia
Provincial markets outside Java remain underserved by organized resale infrastructure, presenting first-mover advantages for platform-based authentication services. Rural digital penetration initiatives generate concentrated demand from educational institutions and price-sensitive consumers seeking network-compatible hardware. Surabaya and Makassar emerge as logistics nodes for archipelago-spanning distribution of verified refurbished inventory.
Asia-Pacific Refurbished and Used Mobile Phones Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Asia-Pacific's refurbished phone trade, producing a tiered structure where platform operators, original manufacturers, and cross-border marketplaces occupy distinct competitive positions. The vendor base spans electronics conglomerates with certified refurbishment programs, e-commerce platforms with controlled logistics infrastructure, and specialized marketplaces navigating cross-border compliance complexity. Three archetypes dominate: original equipment manufacturers extending secondary market services, domestic e-commerce platforms with quality verification protocols, and cross-border marketplace operators with authentication tooling. Competitive moves concentrate on strategic partnerships with telecom operators and geographic expansion through compliance-adapted marketplace models.
Among original equipment manufacturers, Apple Inc. and Samsung Electronics Co., Ltd. exemplify divergent approaches to secondary market participation, with the latter operating certified refurbishment programs across multiple Asian markets. Flipkart Internet Private Limited anchors India's digital resale infrastructure, while Back Market SAS occupies a position navigating cross-border compliance complexity in Australia and Southeast Asia. These three companies represent the spectrum from manufacturer-controlled certification to platform-mediated authentication.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Xiaomi Corporation |
| Huawei Technologies Co., Ltd. |
| Oppo Electronics Corp. |
| Vivo Communication Technology Co., Ltd. |
| Motorola Mobility LLC |
| Flipkart Internet Private Limited |
| Back Market SAS |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot indices cascading through battery replacement cost structures stratify refurbished device pricing across Asia-Pacific quality tiers. Vietnamese automation clusters compress labor-intensive processing expenses while India's BIS certification mandates elevate compliance premiums for formal channel inventory.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for battery replacement services as robotic cell extraction systems cut per-unit labor outlays. Three-tier pricing structure across certified refurbishment, verified used, and salvage-grade separates warranty-backed inventory from as-is provincial market listings. Cost compression in entry-tier devices intensifies because Xiaomi's aggressive new device pricing compresses secondary market premiums. Individual consumers across Indonesian and Philippine provincial markets exhibit highest price sensitivity, while Australian enterprise IT departments demonstrate lowest sensitivity due to residual value capture priorities.
Supply Chain Analysis
Cross-border freight cost volatility from Shenzhen trading hubs to Southeast Asian markets shapes inventory sourcing economics for marketplace operators. Component supply concentrates in China for OLED displays, South Korea for advanced camera modules, and Vietnam for battery cell assembly. Refurbishment output draws from lithium-ion cell availability, proprietary display allocations, and robotic tooling depreciation schedules. Single-source vulnerability runs through original manufacturer parts access restrictions. Distribution runs through online marketplace platforms with integrated logistics, organized retail chains, and direct manufacturer-certified channels.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific's refurbished phone trade functions as a regulatory compounder where India's PLI scheme quality thresholds and Australia's ACCC enforcement actions continuously elevate compliance barriers that concentrate margin capture among certified operators.
For Market Incumbents: Deploy certification infrastructure investments to capture margin compression forcing unorganized traders toward exit. Samsung's certified refurbishment programs and Flipkart's controlled logistics protocols demonstrate defensive positioning against informal channel displacement. Backward integration into battery cell testing equipment insulates against lithium price volatility eroding service margins.
For New Entrants and Emerging Players: Enter via platform-based authentication services targeting Indonesian and Philippine provincial markets underserved by organized resale infrastructure. Rural digital penetration initiatives generate concentrated demand from educational institutions seeking verified device procurement. Partner with Vietnamese automation clusters for cost-competitive refurbishment capacity.
For Investors and Strategic Acquirers: Asymmetric upside sits with refurbishment specialists possessing cross-border compliance capabilities and enterprise fleet buyback relationships. Long-term viability hinges on right-to-repair mandate progression unlocking captive parts supply from original manufacturers. Watch legislative advancement in South Korea and Japan as inflection indicators for component access liberalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | BIS compliance capabilities in India redirect informal volumes into taxable certified channels. |
| Robotic Automation Deployment | Vietnamese battery replacement clusters cut labor costs and extend device functional lifecycles. |
| Enterprise Fleet Buyback Program | Australian corporate IT disintermediation captures residual value previously absorbed by carriers. |
| Cross-Border Marketplace Expansion | Platform authentication tools reduce information asymmetry between distant buyers and sellers. |
| Right-to-Repair Coalition Participation | Legislative pressure on Apple and Samsung unlocks captive component supply for refurbishment. |
Research Methodology
Multiple input streams — executive interviews with refurbishment facility operators, platform engineering directors, and telecom procurement leads; secondary validation through BIS certification databases, SAMR disclosure filings, and ACCC enforcement records; plus customs trade flow analysis — were reconciled through bottom-up facility capacity assessments and top-down market size triangulation.
Historical shipment patterns were cross-referenced against panel input from marketplace operators and component suppliers across the projection horizon. Segmentation dimensions modeled include product condition tier, brand ecosystem, distribution channel type, and customer procurement formalization level. CAGRs were derived from installed base turnover rates and replacement cycle compression. Forecast inputs incorporated 5G network rollout timelines and PLI scheme incentive structures.
Inputs from regulatory filing databases and enterprise procurement disclosures were available through the study window; gaps in informal channel volume estimation introduce uncertainty bands around provincial market penetration rates. Forecasts reflect documented assumptions regarding certification adoption curves and automation deployment timelines. A model refresh is warranted upon material change in right-to-repair legislative progression or lithium carbonate price regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Europe Stylus Pen Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Tablet Market
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
PC Accessories Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Bluetooth Headphones Market