
 Europe Refurbished and Used Mobile Phones Market | 2026-2036
Europe Refurbished and Used Mobile Phones Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refurbished and Used Mobile Phones Market Insights
Modular warranty bundling with certified refurbishment is consolidating buyer choice around risk-assured transactions. Back Market leverages its pan-European marketplace infrastructure to standardize quality grading across borders. Swappie anchors its position through in-house diagnostic and repair operations in the Nordics. Apple sustains residual value premiums via proprietary parts authentication and authorized refurbishment protocols.
Europe refurbished and used mobile phones comprise pre-owned cellular devices that undergo diagnostic testing, component replacement, and software restoration to meet functional benchmarks such as minimum battery health thresholds and display pixel integrity; these units re-enter commercial circulation as lower-cost alternatives to new hardware, serving price-sensitive consumers and sustainability-focused organizations. Smartphones dominate volume throughput due to shorter replacement cycles and stronger residual value retention, while open-box inventory captures margin pools from buyer remorse returns with minimal refurbishment overhead. Online retail channels now lead transaction growth by collapsing geographic friction between centralized refurbishment facilities and dispersed end-users.
The EU Green Deal and Ecodesign for Sustainable Products Regulation mandate repairability scoring and standardized spare parts availability, compelling refurbishment operators to document component provenance and testing outcomes. CE marking requirements under the Radio Equipment Directive enforce electromagnetic compatibility and safety recertification for reactivated devices. Germany's national implementation of the EU Battery Regulation imposes collection and recycling obligations that feed secondary raw materials back into refurbishment supply chains. Stakeholders must track how forthcoming digital product passport mandates reshape traceability costs and competitive positioning across the value chain.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation is compressing device lifecycles and mandating repairability scoring, forcing refurbishment operators to restructure diagnostic protocols and component traceability systems across European supply chains.
Growth Catalysts
- EU Battery Regulation:Germany's national implementation imposes collection and recycling obligations that feed secondary raw materials back into refurbishment supply chains, lowering input costs for battery replacement programs.
- Enterprise fleet procurement:Field workforce deployments across logistics and utilities sectors are standardizing on certified refurbished smartphones to reduce capital expenditure on mobile device estates.
- Carrier trade-in infrastructure:German operators have built standardized grading and resale pipelines that normalize consumer acceptance of pre-owned devices through guaranteed buyback pricing.
Market Restraints
- Proprietary parts authentication:Manufacturer-controlled component verification systems restrict independent refurbishers from accessing genuine replacement modules, limiting repair depth for flagship devices.
- CE marking recertification:The Radio Equipment Directive requires electromagnetic compatibility and safety retesting for each reactivated unit, adding fixed compliance overhead that compresses margins on lower-value inventory.
- Residual value volatility:Rapid flagship release cycles from major OEMs accelerate depreciation curves for prior-generation devices, creating inventory risk for operators holding refurbished stock.
Strategic Opportunities
- Nordic sustainability premiums:Swedish and Finnish corporate procurement policies now mandate circular electronics purchasing, creating price-insensitive demand segments for certified refurbishment.
- Digital product passports:Forthcoming EU mandates for component provenance documentation will favor operators with existing traceability infrastructure, consolidating competitive position.
- Open-box inventory specialization:Buyer remorse returns with minimal refurbishment overhead represent untapped margin pools for operators able to secure direct relationships with major retailers.
Industry Challenges
- Diagnostic technician scarcity:Component-level repair expertise for modern smartphone architectures remains concentrated among specialized workforces, constraining scaling of in-house refurbishment operations.
- Software lock-in complexity:Factory reset protections and cloud activation locks require specialized bypass protocols that vary by manufacturer, extending processing timelines and increasing technical training burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refurbished and Used Mobile Phones Market |
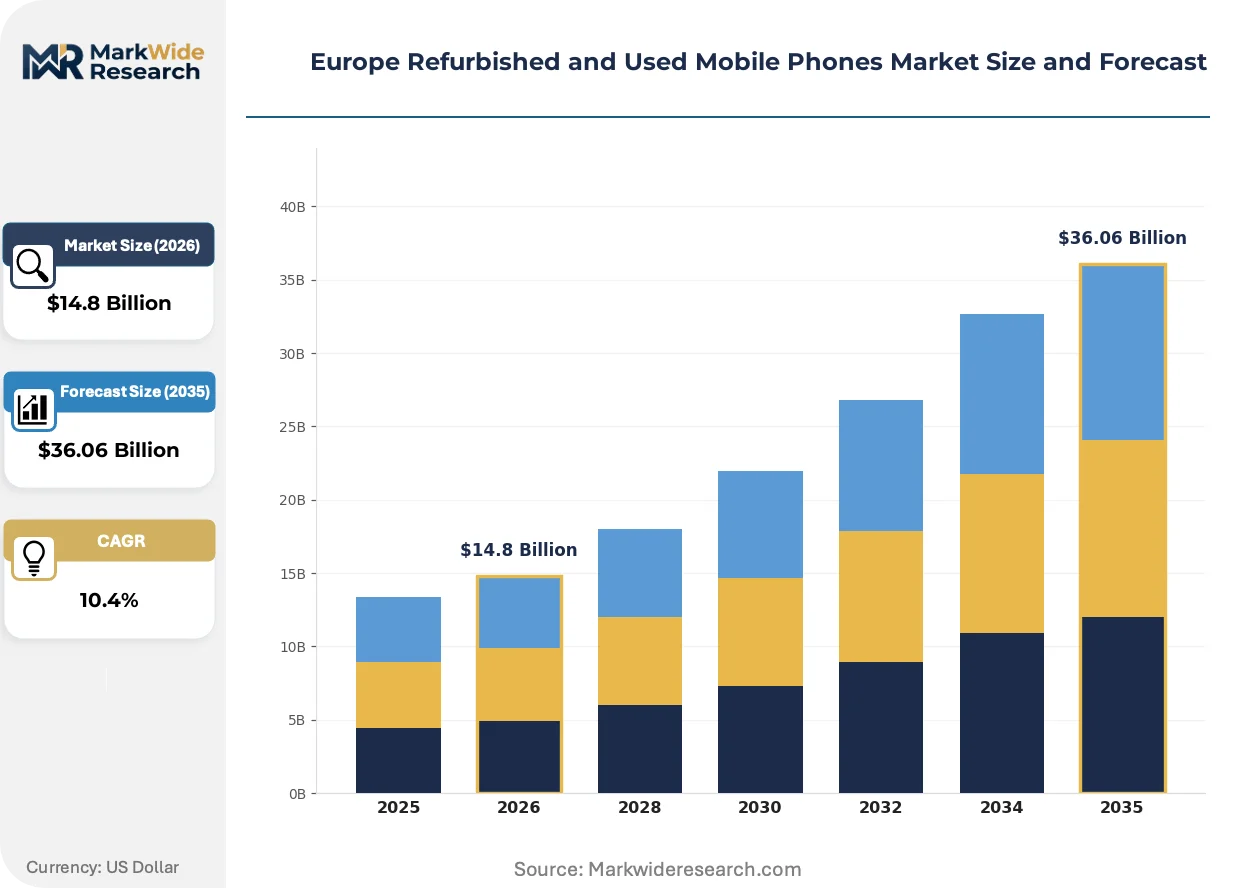
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $36.06 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Feature Phones, Phablets, Tablets Condition: Refurbished, Used, Open Box, Like New Sales Channel: Online Retail, Brick-and-Mortar Stores, Resellers, Auctions Warranty Type: Manufacturer Warranty, Third-Party Warranty, No Warranty, Limited Warranty |
| Companies Covered | Xiaomi, Back Market, Apple, Vodafone, Swappie, Samsung Electronics, Huawei, Deutsche Telekom, Google, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refurbished and Used Mobile Phones Market Trends and Innovations
Refurbishment value chains are restructuring around quality standardization and transparency mechanisms that reduce information asymmetry between sellers and buyers. Three developments are reshaping competitive positioning.
Automated diagnostic platforms are modularizing quality assurance workflows across European refurbishment facilities. These systems capture battery health metrics, display pixel integrity, and sensor functionality in standardized reports. Enterprise procurement teams now require such documentation for fleet purchases, compressing competitive differentiation around certification depth rather than price alone.
The EU Green Deal's repairability scoring mandates are forcing operators to document component provenance and testing outcomes in auditable formats. Industrial consequence includes accelerated investment in traceability software and supplier qualification programs. German refurbishment hubs are responding fastest, integrating digital passport readiness into existing quality management systems ahead of formal enforcement timelines.
Corporate sustainability officers are rewriting mobile device procurement specifications to prioritize circularity metrics over hardware novelty. Long-term leasing with embedded refurbishment clauses is displacing outright purchase in enterprise segments. This shift is most visible in Netherlands and Belgium, where field service organizations have piloted subscription models linking device refresh cycles to performance guarantees rather than calendar depreciation.
Europe Refurbished and Used Mobile Phones Market Segmentation
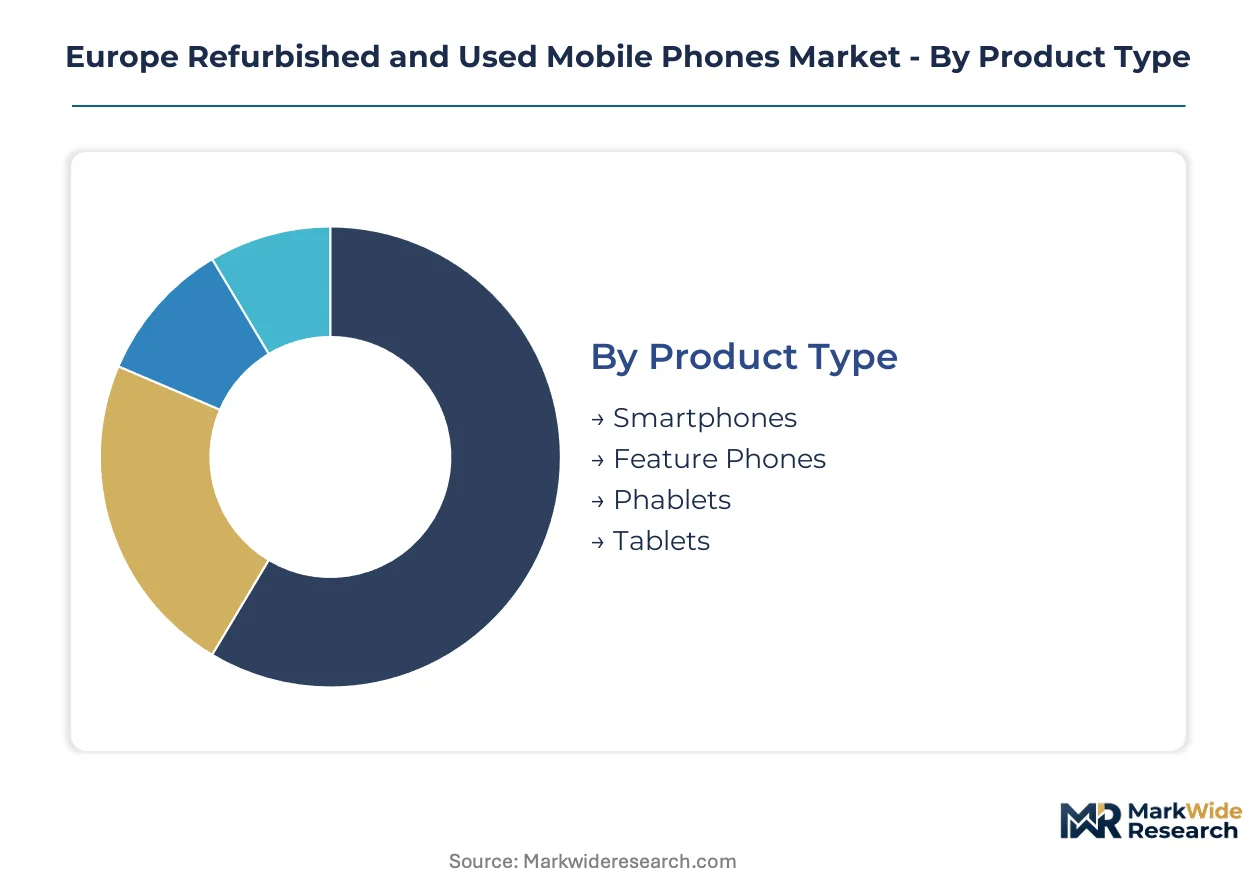
Segmentation in the Europe refurbished and used mobile phones market reveals distinct procurement patterns across buyer sophistication levels, risk tolerance thresholds, and channel preferences. Understanding these divides allows operators to align inventory grading, warranty bundling, and pricing architectures with specific demand pockets rather than treating secondary device markets as undifferentiated commodity flows.
Product Type:
Cost tier differentiation separates enterprise procurement teams from consumer bargain hunters and institutional bulk buyers across European markets.
- Smartphones:iOS and Android handsets with full touchscreen interfaces, app ecosystem compatibility, and cellular connectivity dominate refurbishment throughput. German logistics fleets and Nordic corporate sustainability programs concentrate procurement here, driven by residual value retention and standardized enterprise mobile device management compatibility.
- Tablets:Larger form-factor devices with WiFi or cellular connectivity serve field workforce documentation needs and education sector deployments. Dutch healthcare institutions and Belgian construction supervisors represent concentrated demand pockets, motivated by screen real estate requirements and lower per-unit capital outlay versus new hardware.
- Phablets:Hybrid devices with 5.5-inch-plus displays bridge smartphone portability and tablet utility. French independent contractors and Italian mobile professionals favor this segment for client presentation workflows.
- Feature Phones:Basic voice-and-text devices with limited internet functionality address digital minimalism preferences and elderly user accessibility requirements. Eastern European price-sensitive consumers and UK digital detox movements sustain residual demand.
Smartphones lead volumes today; tablets are gaining share fastest in enterprise fleet procurement.
Condition:
Margin structure varies dramatically based on refurbishment depth required and information asymmetry between seller and buyer.
- Refurbished:Units undergo diagnostic testing, component replacement, battery health restoration, and software reinstallation to meet functional benchmarks. Back Market's pan-European marketplace and Swappie's Nordic repair facilities concentrate supply here, responding to German consumer price sensitivity and corporate circular procurement mandates under EU Green Deal frameworks.
- Open Box:Buyer remorse returns with minimal handling, intact packaging, and near-original condition command premium pricing with negligible refurbishment overhead. Major German electronics retailers and French marketplace platforms source directly from OEM return pipelines, capturing margin pools unavailable to traditional refurbishers.
- Like New:Devices showing no visible wear and full functional performance trade at narrow discounts to new hardware. UK carrier trade-in programs and Spanish operator buyback schemes normalize consumer acceptance through guaranteed grading standards.
- Used:Pre-owned devices sold as-is without systematic refurbishment or quality certification. Peer-to-peer platforms and informal resale channels dominate, appealing to maximum price sensitivity and technology enthusiast self-repair capabilities.
Refurbished inventory commands the revenue base; open-box stock is climbing the fastest as retailer return pipeline access consolidates.
Sales Channel:
Geographic reach and buyer trust mechanisms determine channel selection across urban density gradients and rural dispersion.
- Online Retail:Marketplace platforms and direct-to-consumer websites collapse geographic friction between centralized refurbishment facilities and dispersed end-users. Back Market's standardized cross-border quality grading and Amazon Renewed's fulfillment infrastructure concentrate volume growth here, serving German and French consumers prioritizing convenience and warranty-backed transactions.
- Brick-and-Mortar Stores:Physical inspection opportunities and immediate possession drive urban consumer preference. German carrier stores with trade-in counters and UK high-street electronics retailers anchor this channel, particularly for first-time refurbished device buyers requiring tactile reassurance.
- Resellers:Independent merchants and B2B wholesalers aggregate inventory from multiple sources for redistribution to smaller retailers or institutional buyers. Italian regional distributors and Polish cross-border traders specialize in volume throughput to secondary markets.
- Auctions:Bulk liquidation of corporate fleet returns, insurance write-offs, and excess inventory occurs through specialized platforms. Belgian enterprise asset disposition firms and Netherlands-based circular economy brokers facilitate large-lot transactions to refurbishment operators.
Online retail leads transaction volumes currently; brick-and-mortar stores are expanding most quickly through carrier store network integration.
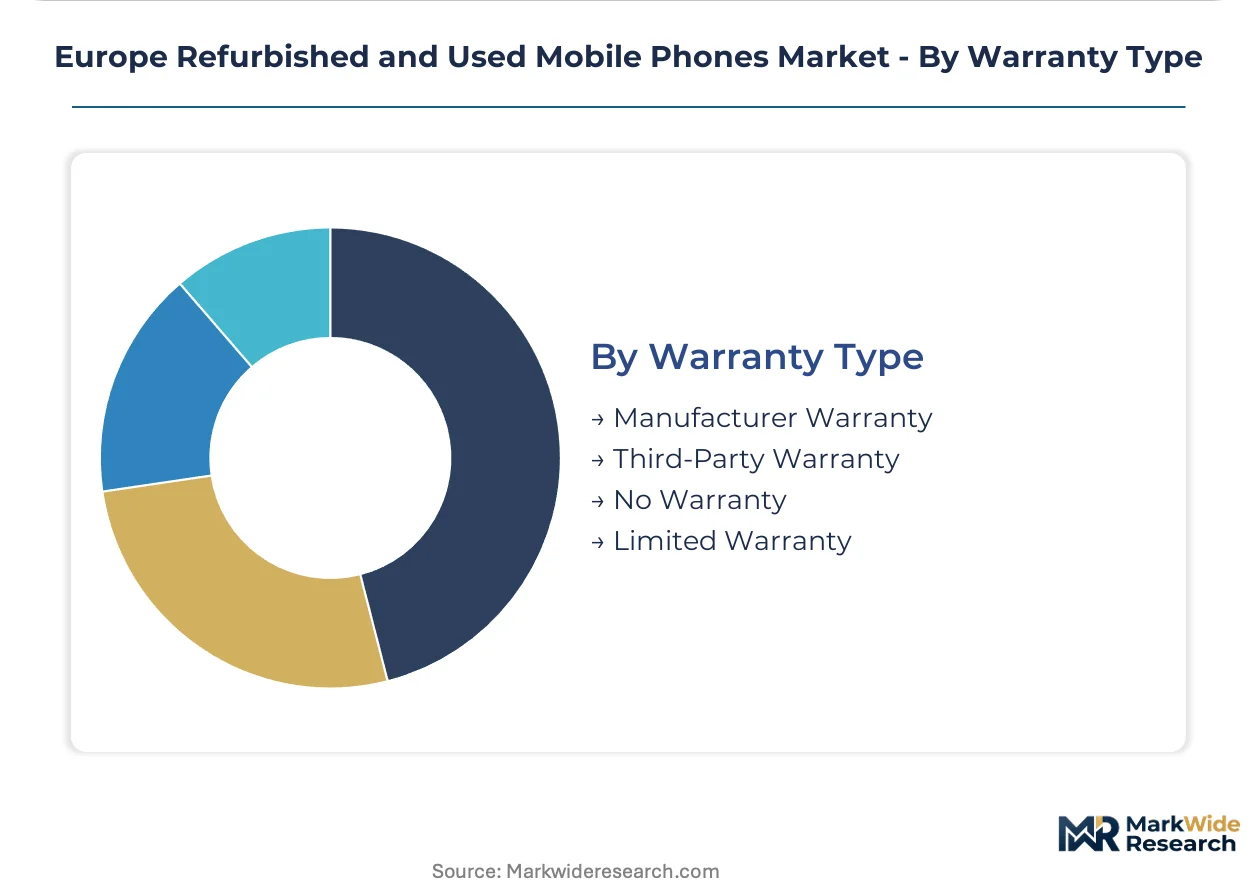
Warranty Type:
Risk transfer mechanisms and repair cost exposure shape buyer willingness to pay premium pricing for certified refurbishment.
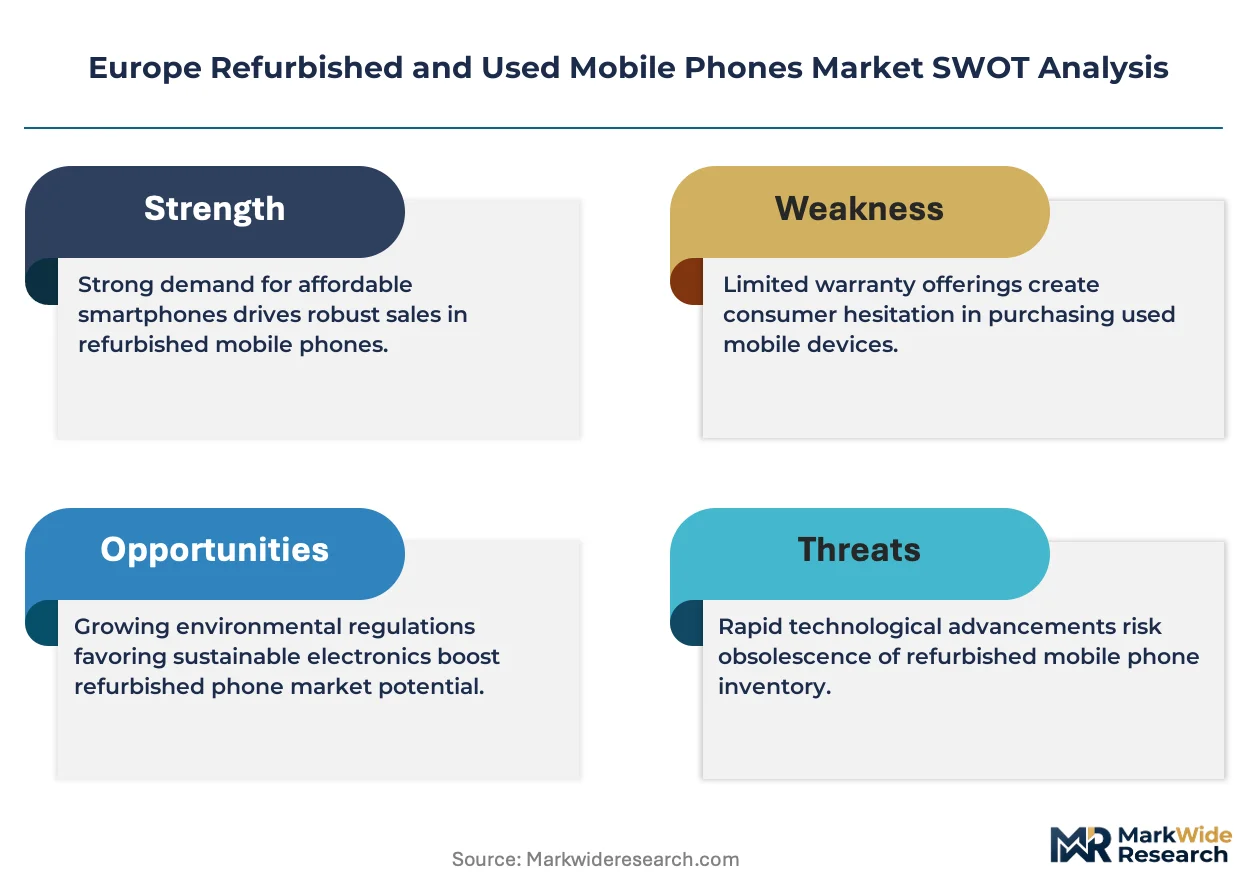
- Third-Party Warranty:Independent insurers and refurbishment operators provide coverage for functional defects and battery degradation. Back Market's marketplace-wide protection plans and Swappie's Nordic service guarantees concentrate buyer preference here, responding to German consumer risk aversion and corporate procurement compliance requirements.
- Manufacturer Warranty:OEM-backed coverage through authorized refurbishment programs commands pricing premiums and quality trust. Apple's certified pre-owned channel and Samsung's official refurbishment programs anchor this segment, leveraging proprietary parts authentication and residual value retention.
- Limited Warranty:Restricted coverage periods or excluded components reduce operator cost exposure while maintaining basic buyer protection. Smaller refurbishment hubs and regional marketplace sellers deploy this structure to compete on headline pricing.
- No Warranty:As-is transactions with buyer assumption of all functional risk enable maximum price discounting. Auction platforms and informal resale channels dominate, appealing to technically capable users and parts harvesters.
Third-party warranty coverage leads attachment rates today; manufacturer-backed programs are gaining share fastest through OEM channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secondary mobile device commerce took root in Germany during the early 2010s through carrier-led trade-in programs, then diffused across Nordic sustainability clusters and Western European corporate procurement networks. The regional map now reflects distinct national regulatory implementations of EU circular economy frameworks.
Germany
Enterprise fleet procurement from logistics operators and utility field crews drives certified refurbished smartphone volumes. The national implementation of the EU Battery Regulation imposes collection and recycling obligations that feed secondary raw materials into refurbishment supply chains. Berlin and Munich host dense clusters of diagnostic facilities serving pan-European marketplace platforms.
United Kingdom
Carrier trade-in infrastructure and high-street electronics retail normalize consumer acceptance of pre-owned devices through guaranteed grading standards. CE marking requirements under the Radio Equipment Directive enforce electromagnetic compatibility recertification for reactivated units. London anchors refurbishment operations targeting corporate sustainability mandates and education sector bulk purchasing.
France
Independent contractors and mobile professionals sustain demand for phablet-format devices bridging smartphone portability and tablet utility. The EU Green Deal's repairability scoring mandates compel operators to document component provenance in auditable formats. Paris-based marketplace platforms leverage standardized cross-border quality grading to serve price-sensitive consumer segments.
Netherlands
Field service organizations pilot subscription models linking device refresh cycles to performance guarantees rather than calendar depreciation. Corporate sustainability officers rewrite procurement specifications to prioritize circularity metrics over hardware novelty. The Randstad concentration supports refurbishment hubs integrating digital passport readiness ahead of formal EU enforcement timelines.
Sweden
Corporate procurement policies mandate circular electronics purchasing, creating price-insensitive demand segments for certified refurbishment. Nordic diagnostic and repair operations concentrate technical expertise for component-level smartphone architectures. Stockholm-based operators capture sustainability premiums through in-house quality assurance and extended warranty bundling.
Europe Refurbished and Used Mobile Phones Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and warranty-backed transaction structures. The vendor base organizes into three tiers: OEM-authorized refurbishment programs with proprietary parts authentication, pan-European marketplace platforms with standardized cross-border grading, and regional specialists with in-house diagnostic capabilities. Consolidation pressure is accelerating through direct retailer return pipeline access and traceability software investments.
Within the marketplace platform tier, Back Market exemplifies pan-European infrastructure deployment, while Swappie occupies a position among Nordic specialists with captive repair operations. Apple and Samsung Electronics anchor the OEM-authorized segment through residual value retention and proprietary authentication protocols. Deutsche Telekom and Vodafone represent carrier-integrated channels leveraging trade-in infrastructure for device circularity.
| Leading Market Players |
|---|
| Xiaomi |
| Back Market |
| Apple |
| Vodafone |
| Swappie |
| Samsung Electronics |
| Huawei |
| Deutsche Telekom |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price volatility cascades through European refurbishment supply chains, compressing margins on battery replacement programs while amplifying spreads between premium-certified and economy-grade inventory tiers. German operators absorb input cost shocks through backward integration into component harvesting networks, whereas independent refurbishers in Eastern Europe pass through volatility via dynamic spot pricing on secondary marketplaces.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes by risk tolerance and warranty attachment. Certification depth under CE marking protocols and residual battery health thresholds drive price differentiation between tiers. Cost compression in economy-grade inventory intensifies as OEM trade-in pipelines flood secondary channels with near-new devices. German logistics procurement teams exhibit lowest price sensitivity due to circularity compliance mandates, whereas Eastern European consumer segments maximize discount capture through peer-to-peer channels.
Supply Chain Analysis
Diagnostic technician scarcity in Poland, Romania, and Bulgaria constrains scaling of component-level repair operations across Central European refurbishment hubs. Battery cell supply draws from Chinese and South Korean manufacturers, while display module sourcing rests on Taiwanese and Vietnamese production clusters. Single-source vulnerability in proprietary parts authentication from Apple and Samsung limits repair depth for flagship devices. Distribution runs through pan-European marketplace platforms consolidating fragmented regional supply into standardized quality-graded inventory pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German sustainability premiums and Eastern European input cost bases defines viable expansion pathways. The EU Battery Regulation's collection mandates in Germany generate feedstock access advantages unavailable to operators in non-compliant jurisdictions.
For Market Incumbents: Anchor market position through captive control over retailer return pipelines and preemptive investment in digital product passport traceability infrastructure. OEM-authorized refurbishment programs threaten margin compression via proprietary parts authentication. Certification depth and warranty bundling remain the priority defensive levers against commoditization. For New Entrants and Emerging Players: Capture open-box inventory specialization opportunities through direct relationships with major German electronics retailers and French marketplace platforms. Nordic corporate sustainability mandates represent the most penetrable demand segment for certified refurbishment with embedded performance guarantees. Subscription-based device-as-a-service models offer differentiated go-to-market positioning against transactional competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with operators combining in-house diagnostic capabilities with pan-European marketplace infrastructure. Long-term viability across the analysis window favors consolidation plays targeting traceability software investments and cross-border quality standardization. Digital product passport enforcement timelines signal the critical inflection indicator for competitive positioning reset.| Strategic Initiative | Industry Significance |
|---|---|
| Retailer Return Pipeline Access | Direct sourcing from German electronics chains secures premium open-box inventory with minimal refurbishment overhead. |
| Traceability Software Investment | EU digital product passport mandates favor operators with auditable component provenance systems already deployed. |
| Diagnostic Technician Training Programs | Component-level repair expertise scarcity constrains scaling; captive workforce development locks in quality differentiation. |
| Subscription Model Pilot | Dutch field service organizations demonstrate viability of performance-linked refresh cycles displacing outright purchase. |
| Nordic Sustainability Certification | Swedish corporate procurement policies mandate circular electronics purchasing, creating price-insensitive demand capture. |
Research Methodology
Multiple input streams — primary interviews with refurbishment facility operators, marketplace platform executives, and carrier trade-in program managers; secondary validation through EU regulatory filings, customs trade data, and OEM sustainability disclosures; plus bottom-up facility capacity surveys — were reconciled against top-down demand modeling from enterprise procurement patterns and consumer price sensitivity indices.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include device condition tier, sales channel configuration, warranty attachment type, and national regulatory implementation cluster. CAGRs were derived from trend extrapolation moderated by saturation thresholds in enterprise fleet penetration and consumer acceptance normalization.
Flagship release cycle acceleration, EU repairability scoring enforcement delays, and lithium raw material price spikes are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on regulatory timeline adherence and residual value retention curves. Material deviation in named triggers warrants pause and re-evaluation of volume and value trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Kids Tablet Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Apple Accessories Market