
 Mini Bluetooth Shower Speaker Market | 2026-2036
Mini Bluetooth Shower Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Bluetooth Shower Speaker Market Insights
Buyer fragmentation across hospitality operators and fitness chains is recalibrating procurement volumes for mini Bluetooth shower speakers. JBL leverages its waterproof audio heritage to anchor premium positioning in resort and spa channels. Soundcore competes aggressively on value-engineered Bluetooth 5.0 models for home bathroom segments. Ultimate Ears specializes in ruggedized, floatable designs that dominate outdoor pool applications.
A mini Bluetooth shower speaker is a compact, battery-powered wireless audio device engineered with IPX4 to IPX7 ingress protection, enabling safe operation in high-humidity or direct water-spray environments; its primary purpose is to stream music, podcasts, or voice assistant content during bathing, exercise, or leisure activities near water. Waterproof product types command the largest volume share, while adhesive-mounted variants represent the fastest-growing configuration as renters and hotel operators seek non-permanent installation. Bluetooth 5.0 technology leads new product introductions due to extended range and lower power draw, though NFC pairing remains concentrated in premium tiers where frictionless connectivity drives margin pools. Home bathroom applications sustain baseline demand, yet spa centers and gym locker rooms are expanding fastest as wellness operators retrofit amenities with ambient audio systems.
The FCC governs radio frequency emissions and Bluetooth certification for devices sold in the United States, while CE marking under EU RoHS and REACH directives restricts hazardous substances in electronics sold across Europe. China's MIIT enforces GB standards for wireless transmission power, compelling manufacturers to region-tune firmware before market entry. Stakeholders must monitor evolving IPX rating harmonization between IEC and ISO frameworks, as divergent testing protocols threaten to fragment compliance costs and delay multi-region product launches.
Market Dynamics
Bluetooth 5.0 migration is fragmenting procurement specifications across hospitality and residential channels, forcing manufacturers to maintain parallel firmware variants and certification stacks for identical hardware platforms.
Growth Catalysts
- Wellness tourism infrastructure:Spa operators in Germany and the United States are retrofitting treatment rooms with ambient audio systems, expanding commercial procurement volumes for waterproof speakers.
- REACH substance restrictions:European hazardous substance rules are accelerating lead-free solder and bio-based housing adoption, creating premium positioning for compliant manufacturers.
- Rental housing mobility:Adhesive-mounted speaker configurations are capturing demand from urban renters in China who prioritize non-permanent bathroom installations.
Market Restraints
- Lithium-ion cell volatility:Battery raw material price swings compress margins on sub-$30 retail units, forcing suppliers to absorb cost spikes or sacrifice volume.
- Assembly concentration:Final integration clusters in Guangdong province expose brands to single-region logistics disruptions and tariff exposure.
- Audio codec fragmentation:Inconsistent aptX, AAC, and SBC support across smartphone OEMs creates compatibility friction that elevates return rates.
Strategic Opportunities
- India hospitality buildout:Boutique hotel construction in Maharashtra and Karnataka states is creating first-mover advantage for IPX7-rated suppliers establishing local distribution.
- Voice assistant convergence:Integration of Alexa and Google Assistant protocols with waterproof housings is opening premium price tiers in residential retrofit markets.
- Extended Producer Responsibility:French repairability index mandates are rewarding modular speaker designs with retail placement advantages.
Industry Challenges
- Acoustic engineering talent scarcity:Miniaturized waterproof audio design requires rare combinations of transducer physics and materials science expertise concentrated in Denmark and California.
- Multi-region certification lag:Simultaneous FCC, CE, and MIIT approval cycles extend product launch timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Bluetooth Shower Speaker Market |
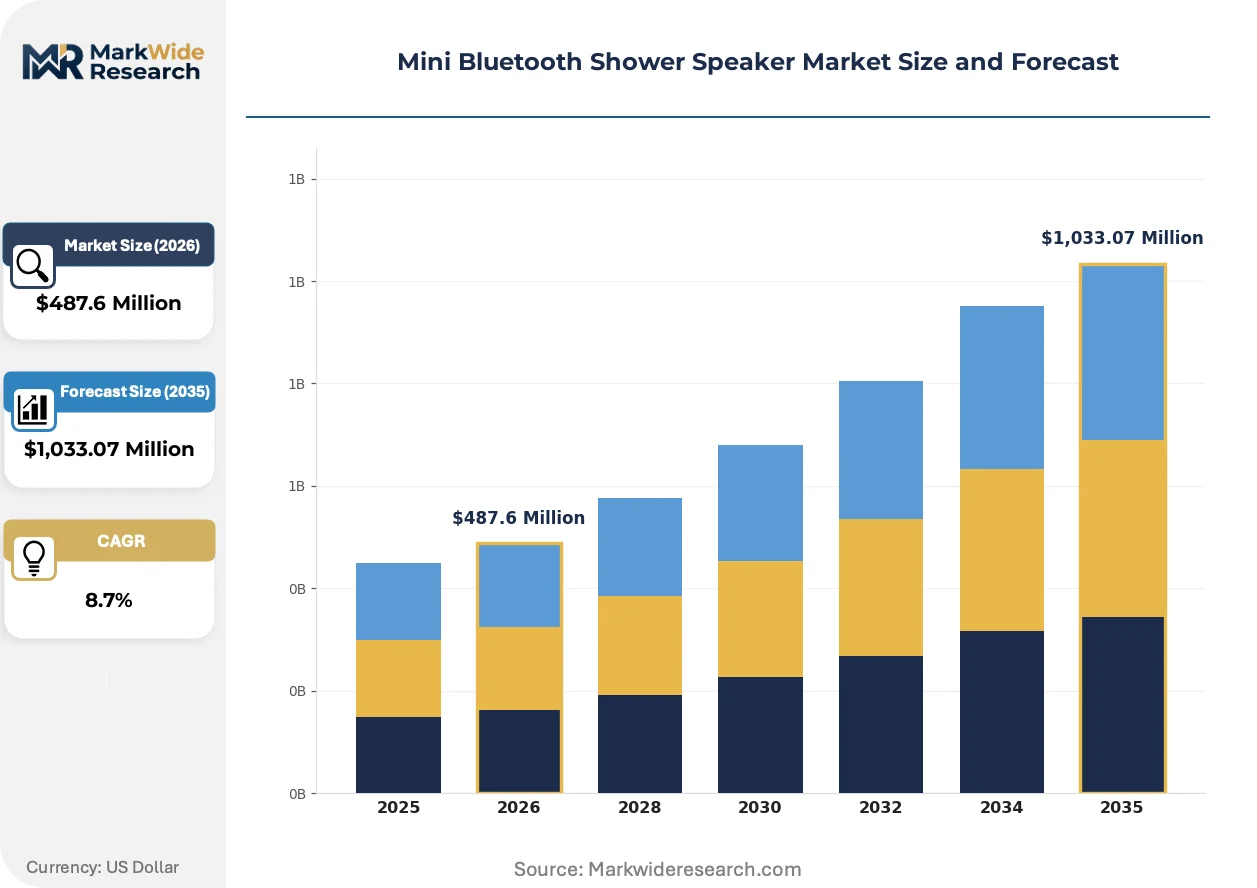
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproof, Portable, Rechargeable, Adhesive Technology: Bluetooth 4.0, Bluetooth 5.0, NFC, AUX Connectivity Application: Home Bathroom, Gym Locker Rooms, Outdoor Pools, Spa Centers Customer Type: Fitness Enthusiasts, Homeowners, Hospitality Businesses, Gift Buyers |
| Companies Covered | JBL, Soundcore, Sony, Bose, Ultimate Ears, Tribit, INSMY, LG Electronics, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Bluetooth Shower Speaker Market Trends and Innovations
Audio streaming architecture is fragmenting around low-power wireless protocols and modular voice integration, compressing product lifecycles and forcing faster firmware update cadences.
Bluetooth Low Energy Audio is decentralizing power management across shower speaker architectures, enabling manufacturers to halve battery capacity without reducing playtime. Hospitality procurement teams in Florida and Arizona are specifying LE Audio for new construction projects. This protocol shift is compressing the addressable market for legacy Bluetooth Classic-only chipsets.
EU RoHS substance restrictions are tightening cadmium and lead thresholds in circuit board assemblies, compelling Asian contract manufacturers to retool surface-mount lines. The industrial consequence is a bifurcation between European-bound and domestic-market production batches. Premium-tier brands with European volume exposure are absorbing compliance costs to maintain retail shelf positioning.
Subscription bundling is displacing standalone hardware purchases in North American direct-to-consumer channels, with waterproof speaker accessories now attached to music streaming annual plans. Big-box electronics retailers are ceding bathroom audio shelf space to telecom and streaming service kiosks. This channel rotation is most pronounced in California and Texas metropolitan markets where carrier store density exceeds traditional electronics retail.
Mini Bluetooth Shower Speaker Market Segmentation
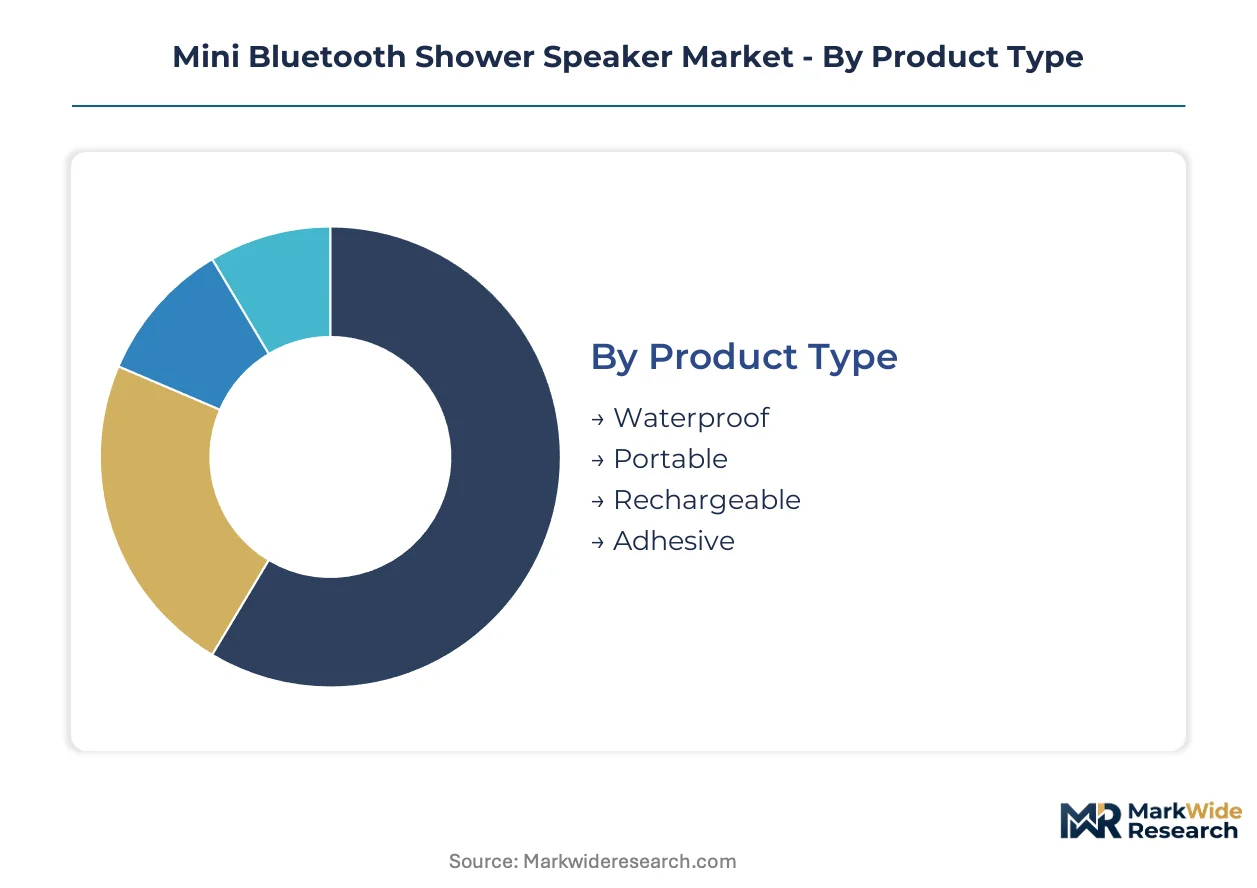
Segmentation in the mini Bluetooth shower speaker market reveals how IPX certification tiers and connectivity protocols fragment procurement requirements across hospitality and residential channels. Buyers optimize around installation permanence, pairing friction, and ambient moisture exposure rather than audio performance alone.
Product Type:
IPX rating thresholds determine which segments require FCC Part 15 certification versus full CE marking with REACH substance documentation. Higher ingress protection ratings trigger extended testing cycles in Shenzhen and TÜV Rheinland labs.
- Waterproof:IPX5 to IPX7 housings with silicone-sealed driver chambers and hydrophobic mesh grilles. Hospitality operators in Florida and Arizona specify these for poolside installations where direct spray exposure is routine. CE marking and FCC Part 15 certification are mandatory for cross-border distribution.
- Adhesive:Removable suction or 3M-style mounting pads with quick-release mechanisms. Urban renters in Shanghai and Berlin favor these for lease-compliant bathroom retrofits without fixture damage. REACH-compliant adhesive compounds add 8-12% to bill-of-materials costs for European-bound units.
- Portable:Carabiner-clip or lanyard-equipped designs prioritizing transport over fixed installation. Hikers and camping enthusiasts in Colorado and Bavaria drive seasonal demand spikes.
- Rechargeable:USB-C or proprietary dock charging with lithium-polymer cells. UN 38.3 transportation testing requirements complicate air-freight logistics for direct-to-consumer channels.
Waterproof sits at the top of the volume ranking, with Adhesive climbing the fastest.
Technology:
Protocol selection directly impacts which semiconductor suppliers qualify for design wins, with Nordic Semiconductor and Qualcomm dominating divergent specification paths.
- Bluetooth 5.0:Extended 240-meter range and LE Audio readiness with sub-10mW idle power draw. Gym chains in Texas and Ontario are mandating this protocol for locker room deployments to minimize dropout during high-density usage. Firmware must pass MIIT SRRC certification for China market entry.
- Bluetooth 4.0:Legacy Classic Audio with higher baseline power consumption. Budget retail channels in India and Southeast Asia continue sourcing these chipsets for sub-$25 price points.
- NFC:Tap-to-pair functionality requiring additional antenna integration and electromagnetic compatibility testing. Premium spa operators in Switzerland and UAE specify these for frictionless guest onboarding.
- AUX Connectivity:3.5mm fallback for legacy device compatibility. Declining inclusion rate as smartphone OEMs eliminate headphone jacks.
Bluetooth 5.0 dominates new product introductions, while NFC gains share fastest in premium hospitality specifications.
Application:
End-use environment dictates acoustic tuning priorities, with reverberant tile bathrooms requiring different EQ profiles than open-air pool decks.
- Home Bathroom:Compact form factors with 360-degree sound dispersion for confined spaces. Homeowners in California and Ontario prioritize voice assistant integration for hands-free control during bathing routines.
- Spa Centers:Ambient audio systems with low-frequency emphasis for relaxation programming. Wellness operators in Germany and Arizona are retrofitting treatment rooms with IPX6-rated units that withstand steam exposure.
- Gym Locker Rooms:High-output drivers with moisture-resistant passive radiators. Fitness chains in Maharashtra and Karnataka specify antimicrobial housing materials for hygiene compliance.
- Outdoor Pools:Floatable designs with UV-stabilized polymers and extended battery life. Resort procurement in Florida and Queensland favors ruggedized units with carabiner attachments.
Home Bathroom maintains the largest installed base, with Spa Centers expanding most quickly as wellness tourism infrastructure scales.
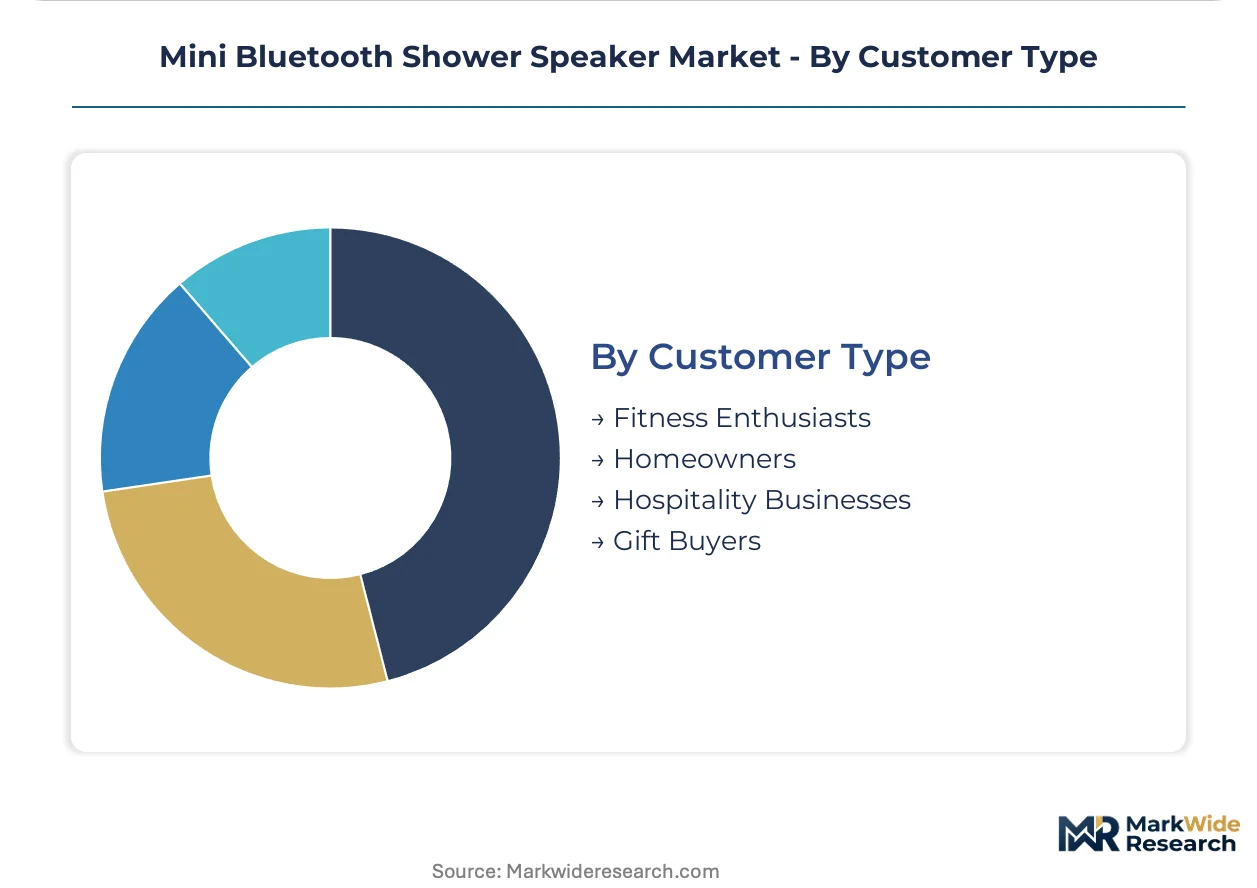
Customer Type:
Purchase authority and volume scale vary dramatically, with hospitality buyers negotiating direct OEM relationships while gift buyers depend on retail markup structures.
- Hospitality Businesses:Bulk procurement with custom logo engraving and centralized fleet management requirements. Boutique hotel groups in Maharashtra and Texas are establishing direct supplier relationships to bypass distributor margins.
- Fitness Enthusiasts:Performance-oriented buyers prioritizing durability metrics and workout playlist synchronization. CrossFit affiliates in Colorado and Bavaria drive word-of-mouth adoption for specific ruggedized models.
- Homeowners:Aesthetic-conscious purchasers matching speaker finishes to bathroom fixture palettes. Smart home ecosystem compatibility influences final selection in California and Ontario metropolitan markets.
- Gift Buyers:Price-elastic seasonal demand concentrated in Q4 retail windows. Big-box electronics chains in Texas and Illinois allocate endcap placement to sub-$40 SKUs with gift-oriented packaging.
Hospitality Businesses command the highest average order values, with Fitness Enthusiasts demonstrating the steepest repeat purchase trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitality procurement outpaces German wellness infrastructure spending by a factor of nearly two, yet both markets prioritize IPX7-rated specifications for commercial installations.
United States
Florida and Arizona resort operators are retrofitting poolside amenities with waterproof audio systems, driving commercial volume. FCC Part 15 certification governs all Bluetooth device distribution. Shenzhen-to-Los Angeles freight corridors handle the bulk of finished goods importation for West Coast hospitality distribution.
Germany
Baden-Württemberg spa operators are specifying ambient audio for wellness tourism infrastructure, expanding procurement beyond residential channels. CE marking under EU RoHS and REACH directives mandates lead-free solder and restricted substance documentation. Bavarian electronics distributors are consolidating inventory positions for IPX6-rated commercial units.
China
Shanghai and Beijing urban renters favor adhesive-mounted configurations for lease-compliant bathroom installations. MIIT enforces GB standards for wireless transmission power, requiring region-tuned firmware. Guangdong province contract manufacturers cluster final assembly operations for export-bound production.
India
Maharashtra and Karnataka boutique hotel construction is creating first-mover opportunity for IPX7-rated suppliers establishing local distribution. BIS certification requirements for electronics imports are tightening compliance timelines. Mumbai-based hospitality procurement teams are negotiating direct OEM relationships to bypass distributor margins.
Japan
Tokyo metropolitan homeowners are integrating voice assistant compatibility into compact bathroom audio systems. METI oversees radio equipment compliance through technical standards conformity certification. Osaka-based electronics retailers are allocating shelf space to Bluetooth 5.0 models with NFC pairing functionality.
Mini Bluetooth Shower Speaker Market Competitive Landscape
Guangdong producers anchor the volume tier; California and Danish specialists hold premium positioning through acoustic engineering differentiation. The vendor base separates into three strategic tiers: heritage audio brands with waterproof IP, value-engineered consumer electronics suppliers, and ruggedized outdoor specialists. Capacity expansion and voice assistant protocol licensing represent the dominant competitive moves across all tiers.
Among heritage audio fabricators, JBL and Bose exemplify premium-tier positioning through resort and spa channel penetration. Soundcore occupies a position within the value-engineered segment, competing aggressively on Bluetooth 5.0 specifications for residential bathroom applications. Ultimate Ears anchors the ruggedized outdoor specialist archetype, with floatable designs dominating pool and adventure use cases.
| Leading Market Players |
|---|
| JBL |
| Soundcore |
| Sony |
| Bose |
| Ultimate Ears |
| Tribit |
| INSMY |
| LG Electronics |
| Philips |
| Others |
Pricing and Supply Chain Analysis
Backward integration into lithium-polymer cell sourcing anchors both supply security and margin defense for mini Bluetooth shower speaker manufacturers, with Guangdong contract manufacturers capturing assembly economics while brand owners retain pricing power through firmware differentiation and certification stacking.
Pricing Analysis
Capacity additions in Shenzhen and Dongguan are reshaping price floors for entry-tier waterproof speakers, compressing margins on sub-$30 retail units while premium tiers sustain markups through IPX7 certification and voice assistant integration. Three-tier pricing structure across premium, standard, and economy levels segments buyers by installation permanence and connectivity protocol, with hospitality operators least sensitive and gift buyers most elastic. Pricing pressure stems from lithium-ion raw material volatility, forcing suppliers to absorb cost spikes or sacrifice volume in big-box retail channels.
Supply Chain Analysis
Returns flows from audio codec compatibility failures create reverse-logistics burdens for direct-to-consumer channels, with refurbishment programs concentrated in California and Texas distribution hubs. Final assembly clusters in Guangdong province, with semiconductor sourcing from Taiwan and South Korea, and adhesive compound supplies from Japan. Single-region concentration exposes brands to logistics disruptions and tariff exposure. Distribution runs through hospitality procurement direct relationships, consumer electronics retail, and telecom bundling kiosks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EU REACH substance restrictions and French repairability index mandates creating premium positioning for compliant manufacturers that absorb certification costs.
For Market Incumbents: Lock in spa and resort channel relationships through custom fleet management portals and centralized firmware update infrastructure, defending against value-engineered entrants from Guangdong. Deepen backward integration into waterproof transducer design to protect acoustic engineering differentiation concentrated in Denmark and California.
For New Entrants and Emerging Players: Boutique hotel procurement teams in Maharashtra and Karnataka represent the most penetrable channel, with direct OEM relationships bypassing distributor margins and capturing first-mover advantage in India's hospitality buildout. Target adhesive-mounted configurations for urban renters in Shanghai and Berlin seeking lease-compliant bathroom installations.
For Investors and Strategic Acquirers: Consolidation pressure builds where acoustic engineering talent scarcity intersects with multi-region certification lag, extending product launch timelines by four to six months for sub-scale players. Acquisition targets include modular design specialists positioned for French repairability index compliance. Monitor Bluetooth Low Energy Audio protocol adoption in Florida and Arizona hospitality new construction as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Voice Assistant Protocol Licensing | Alexa and Google Assistant integration opens premium residential retrofit tiers in California and Ontario. |
| IPX7 Certification Investment | Extended testing cycles at TÜV Rheinland labs secure hospitality procurement specifications in Germany and Arizona. |
| Direct-to-Hospitality Distribution | Bypassing electronics retail distributors captures margin pools in Maharashtra and Texas boutique hotel markets. |
| Modular Design Repositioning | French repairability index compliance creates retail placement advantages in EU-bound production batches. |
| Bluetooth 5.0 Firmware Migration | LE Audio readiness future-proofs inventory against legacy Classic chipset obsolescence in gym locker room deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospitality procurement managers, electronics contract manufacturing executives, spa operations directors, and retail category buyers with secondary validation against FCC equipment authorization databases, MIIT SRRC filings, EU RoHS compliance registries, and customs import records. Bottom-up volume builds across IPX rating tiers, connectivity protocols, and application segments triangulated against top-down spending estimates from wellness tourism infrastructure investment and bathroom renovation expenditure data.
Segment-weighting approaches distributed volume and value across the projection horizon by product type, technology protocol, end-use environment, and customer archetype, with CAGRs derived from regression analysis of historical adoption curves and forward-looking elasticity estimates. Forecast inputs incorporated Bluetooth protocol migration timelines, lithium-ion cell price trajectories, and hospitality construction permit data from Maharashtra, Karnataka, Florida, and Arizona.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IPX rating harmonization between IEC and ISO frameworks, divergent testing protocols, and lithium raw material supply concentration. Practitioners should monitor LE Audio specification adoption in hospitality new construction and REACH substance threshold tightening for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Ereader and Enotetaking Devices Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
PC Accessories Market