
 Wall Decor Market | 2026-2036
Wall Decor Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Decor Market Analysis
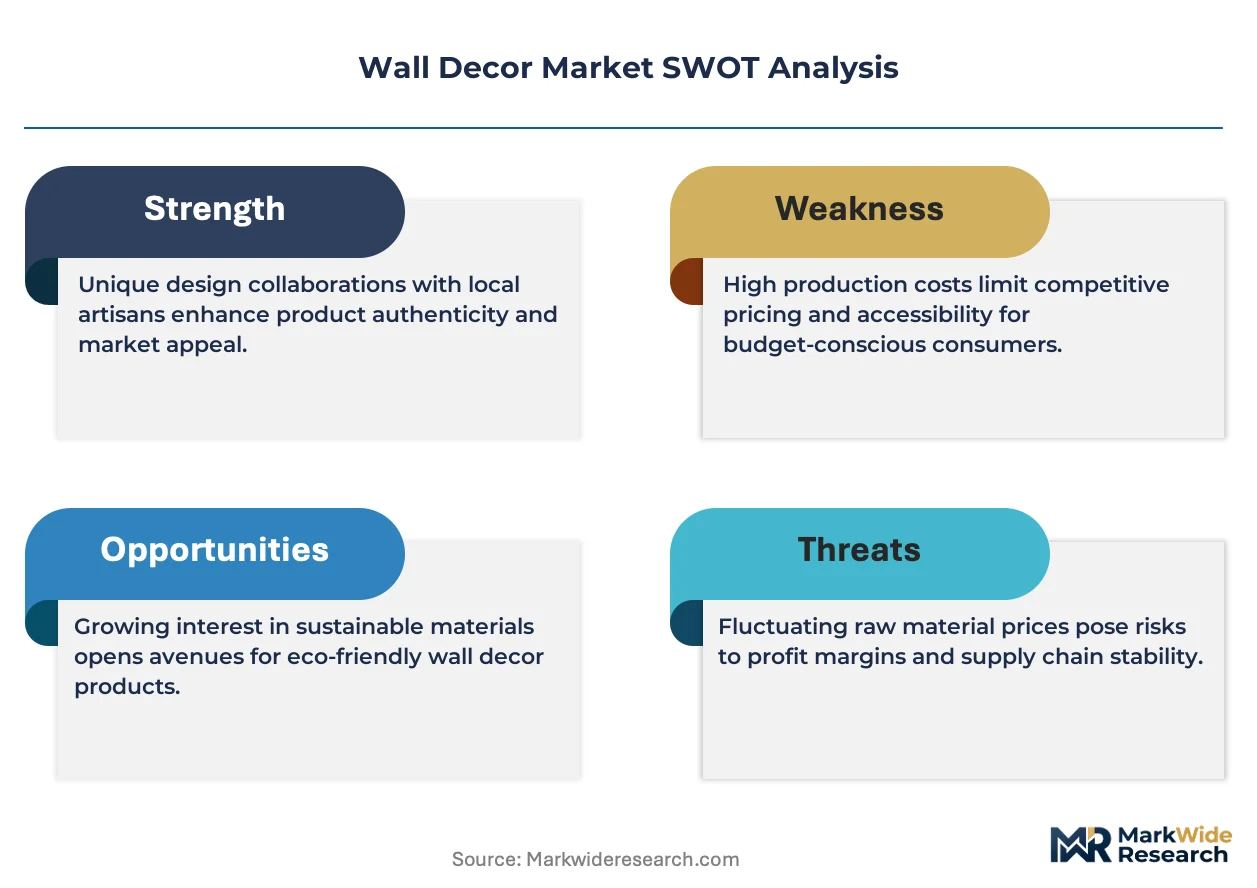
Artisan manufacturing labor in traditional frame and tapestry production is collapsing across Southeast Asian supplier bases. IKEA leverages its captive flat-pack logistics network to control cost structures in mass-market canvas prints. Wayfair Inc. competes through data-driven curation algorithms that reduce customer acquisition costs in online wall art. Williams-Sonoma Inc. anchors its premium positioning through direct relationships with limited-edition artists and museum licensors.
Wall decor encompasses two-dimensional and relief-mounted visual elements designed for permanent or semi-permanent installation on vertical interior surfaces, typically fabricated through digital printing on woven substrates, CNC-routed wood composites, or hand-finished metal patination processes, serving both aesthetic spatial transformation and acoustic dampening functions in built environments. Canvas prints dominate volume throughput due to scalable digital reproduction economics, while metal and acrylic segments concentrate margin pools through durability premiums in commercial hospitality fit-outs. The residential application category sustains baseline demand cyclicality tied to housing turnover rates, whereas hospitality deployment tracks hotel renovation pipelines and brand-standard refresh cycles.
The EPA regulates volatile organic compound emissions from paints, coatings, and adhesives used in wall decor manufacturing under 40 CFR Part 59, pushing suppliers toward water-based and UV-cured finishing systems. The EU Green Deal's embodied carbon reporting requirements through CSRD disclosure mandates are reshaping sourcing decisions for European retailers importing Asian-manufactured goods. California's Proposition 65 enforcement continues to drive reformulation of substrate treatments and metallic leaf applications for products entering the US West Coast distribution corridor. Stakeholders must monitor evolving extended producer responsibility frameworks for interior furnishings as jurisdictions begin piloting take-back programs for renovation waste streams.
Market Dynamics
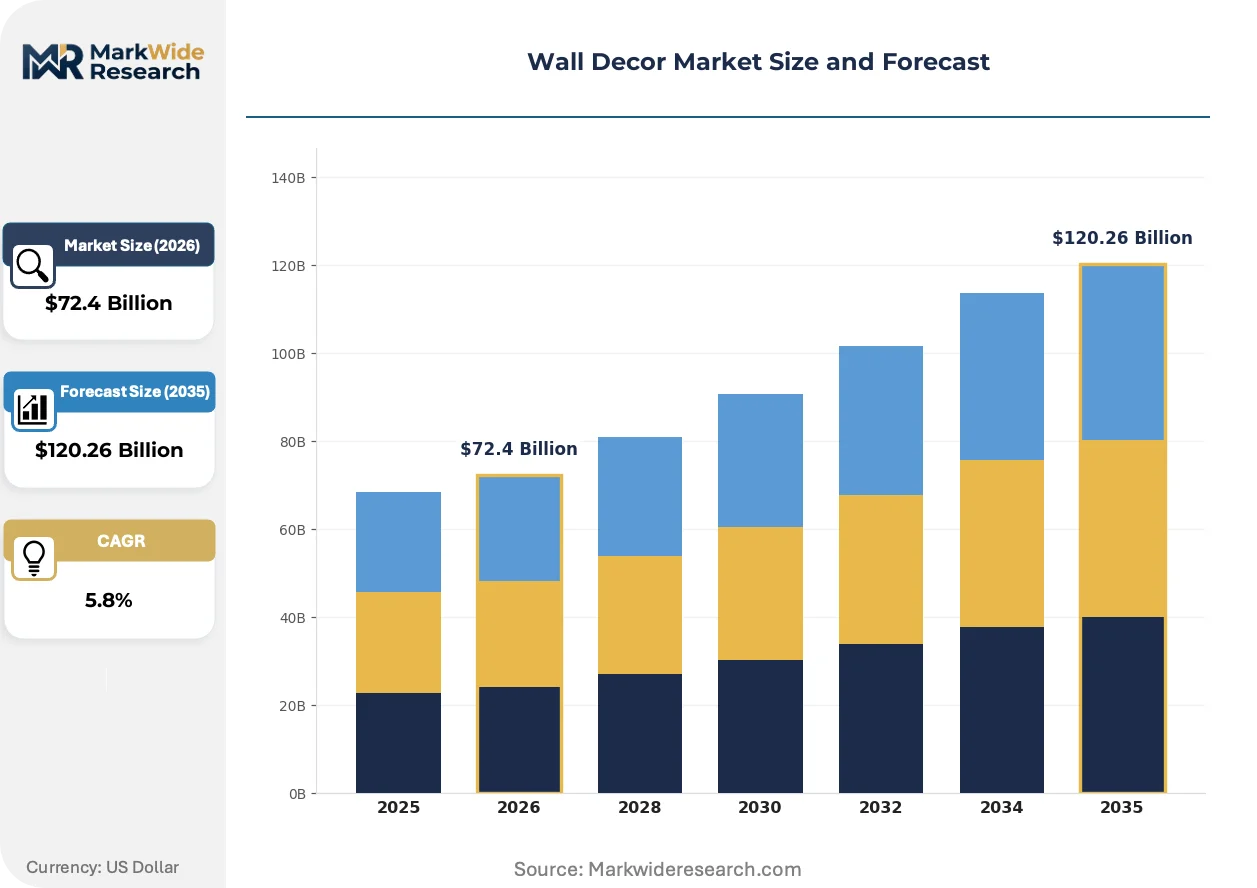
The wall decor market is compressing around two irreconcilable supply models: artisan-labor scarcity in Southeast Asian frame production versus IKEA's captive flat-pack logistics controlling mass-market canvas economics.
Growth Catalysts
- REACH compliance tightening:ECHA substrate chemical standards for imported wall products are forcing European retailers to reformulate supplier bases, accelerating certified-material sourcing premiums.
- Millennial residential renovation:Single-family housing completions in the United States sustain DIY retail channel velocity for semi-permanent installation products.
- Digital printing on woven substrates:Scalable reproduction economics for canvas prints are collapsing per-unit production costs below hand-finished alternatives.
Market Restraints
- Artisan labor collapse:Traditional frame and tapestry production in Vietnam and Indonesia faces generational skill attrition without mechanized replacement pathways.
- Input cost volatility:CNC-routed wood composites depend on Baltic birch plywood supply concentrated in Russian and Belarusian mill networks subject to trade restriction cascades.
- Substitution threat from acoustic panels:Felt and mineral wool vertical installations in commercial hospitality fit-outs are absorbing budget allocations previously directed toward decorative relief elements.
Strategic Opportunities
- CSRD disclosure mandates:EU Green Deal embodied carbon reporting requirements create first-mover advantage for retailers publishing verified Asian-manufactured goods footprint data.
- Extended producer responsibility pilots:Jurisdictions testing renovation waste take-back programs for interior furnishings open reverse-logistics service revenue streams.
- Acoustic dampening convergence:Metal patination processes combined with perforated substrate engineering address dual aesthetic and functional specifications in open-plan commercial spaces.
Industry Challenges
- Proposition 65 reformulation timelines:California enforcement of substrate treatment and metallic leaf disclosure requirements compresses product development cycles for West Coast distribution.
- Water-based finishing system validation:EPA 40 CFR Part 59 VOC compliance demands capital-intensive curing equipment upgrades without guaranteed performance parity with solvent-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Decor Market |
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $120.26 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canvas Prints, Wall Stickers, Framed Art, Tapestries Material: Wood, Metal, Fabric, Acrylic Style: Modern, Vintage, Rustic, Abstract Application: Residential, Commercial, Hospitality, Offices |
| Companies Covered | IKEA, Wayfair Inc., Target Corporation, Home Depot, Williams-Sonoma Inc., Ashley Furniture Industries, Bed Bath & Beyond Inc., Etsy Inc., Art.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Decor Market Emerging Trajectories
Three active transformations are compressing the wall decor value chain: manufacturing automation is displacing artisan labor pools, regulatory disclosure mandates are reshaping sourcing transparency requirements, and procurement consolidation is concentrating buyer power against fragmented supplier bases.
UV-cured digital printing on woven polyester-cotton substrates is displacing screen-printed canvas production in volume-tier wall art. Hospitality procurement teams in the United States are specifying these finishes for brand-standard refresh cycles exceeding 10,000-unit deployments. The technology is displacing hand-stretched canvas workshops across Guangdong and Zhejiang manufacturing clusters.
CSRD embodied carbon disclosure requirements through the EU Green Deal are mandating supply chain documentation for Asian-manufactured wall products entering European distribution. Retailers must now verify substrate provenance, adhesive chemistry, and finishing energy intensity across tier-two and tier-three suppliers. German and French buying offices are restructuring vendor qualification protocols to preempt audit failures.
Buyer concentration through data-driven curation platforms is compressing traditional wholesale margin structures. Online wall art aggregators now algorithmically match consumer preference signals to supplier inventory, collapsing the role of independent showroom intermediaries. This channel consolidation is most visible in United States residential renovation procurement, where millennial homeowners initiate purchase journeys through mobile-native interfaces rather than brick-and-mortar design centers.
Wall Decor Market Segmentation
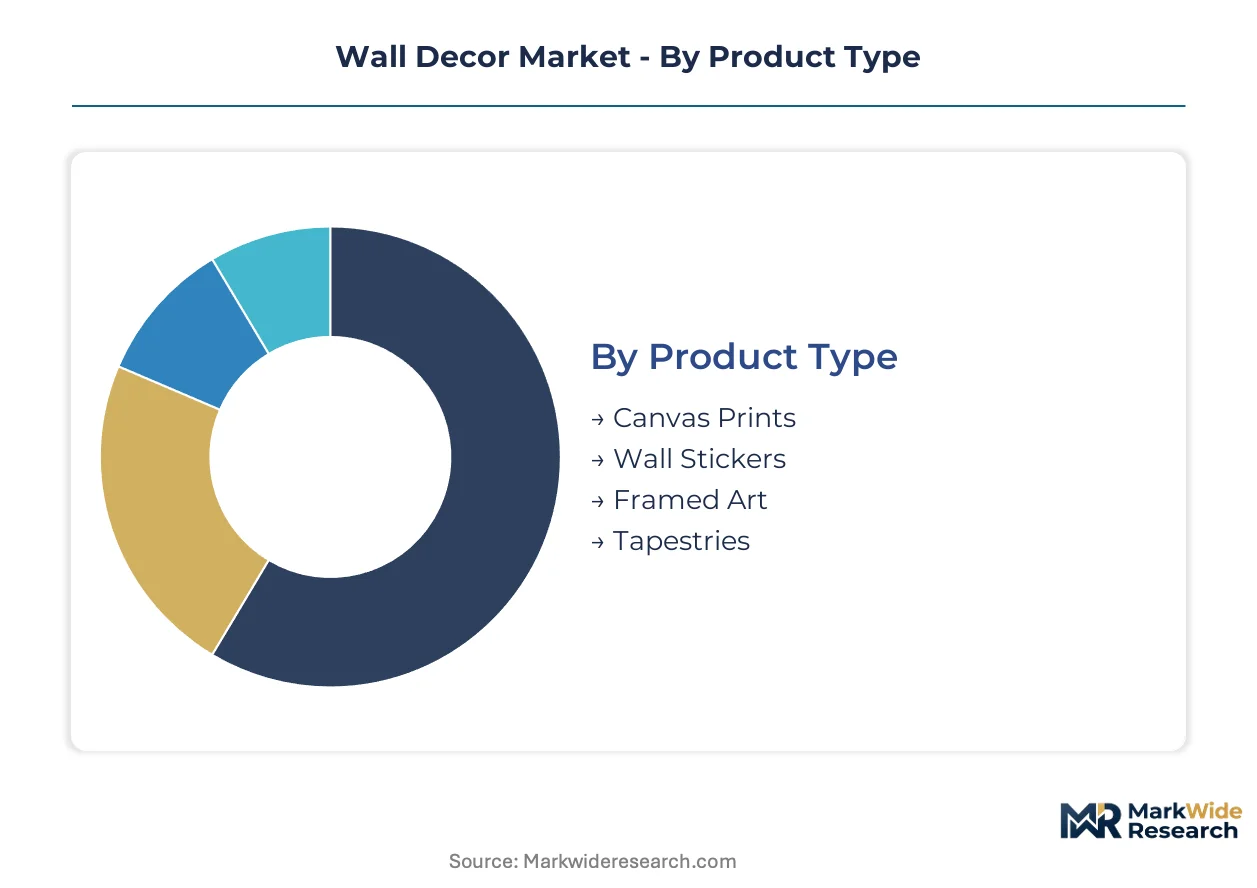
Segmentation in wall decor reveals divergent supply economics across product categories. Canvas prints and mass-market substrates scale through automated digital production, while hand-finished metal and limited-edition framed pieces depend on concentrated artisan labor pools in Vietnam and Indonesia.
Product Type:
Canvas prints and wall stickers flow predominantly through export-oriented manufacturing clusters in Guangdong and Zhejiang, while framed art and tapestries retain stronger domestic production footprints in European and North American ateliers.
- Canvas Prints:UV-cured digital printing on woven polyester-cotton substrates enables scalable reproduction economics. Demand concentrates in United States residential renovation channels where millennial homeowners favor semi-permanent installation products with sub-48-hour fulfillment.
- Wall Stickers:Pressure-sensitive adhesive vinyl with removable backing dominates entry-level price tiers. Export-led manufacturing from Dongguan printing clusters supplies North American big-box retail private labels facing compressed margin structures.
- Framed Art:Traditional mitered wood frames with hand-finished joinery face generational skill attrition in Southeast Asian supplier bases.
- Tapestries:Woven or printed textile wall hangings retain niche positioning through artisan production in Belgian and Portuguese mill networks.
Canvas prints command the established base. The steepest expansion runs through wall stickers.
Material:
Cost tier stratification separates premium durability metals and acrylics from volume-optimized wood and fabric substrates in procurement specifications.
- Wood:CNC-routed birch plywood and solid hardwood frames face supply concentration risk from Baltic mill networks subject to trade restriction cascades. Hospitality procurement in the United States specifies FSC-certified substrates for brand-standard refresh cycles.
- Metal:Hand-finished patination on aluminum and steel substrates commands durability premiums in commercial fit-outs. German and French buying offices prioritize REACH-compliant surface treatments for EU distribution.
- Fabric:Woven cotton and linen substrates for tapestries and canvas wraps scale through digital printing automation.
- Acrylic:Cast and extruded polymethyl methacrylate panels serve premium residential segments with moisture-resistant specifications.
Wood retains volume leadership across residential channels. Acrylic gains share fastest in coastal humidity markets.
Style:
Customer type differentiation separates mass-market algorithmic curation from curated designer collections in margin capture.
- Modern:Clean-line minimalism with neutral palettes dominates online aggregator platforms. Data-driven curation algorithms from United States mobile-native interfaces match preference signals to supplier inventory, collapsing traditional showroom intermediaries.
- Vintage:Reproduction antiqued finishes and period-frame profiles serve heritage property renovation in European capitals.
- Rustic:Distressed wood and farmhouse-inspired metalwork concentrate in Midwest United States residential markets.
- Abstract:Non-representational digital prints on canvas scale through reproduction licensing from museum collections.
Modern styling anchors platform economics. Abstract works expand most quickly through digital reproduction licensing.
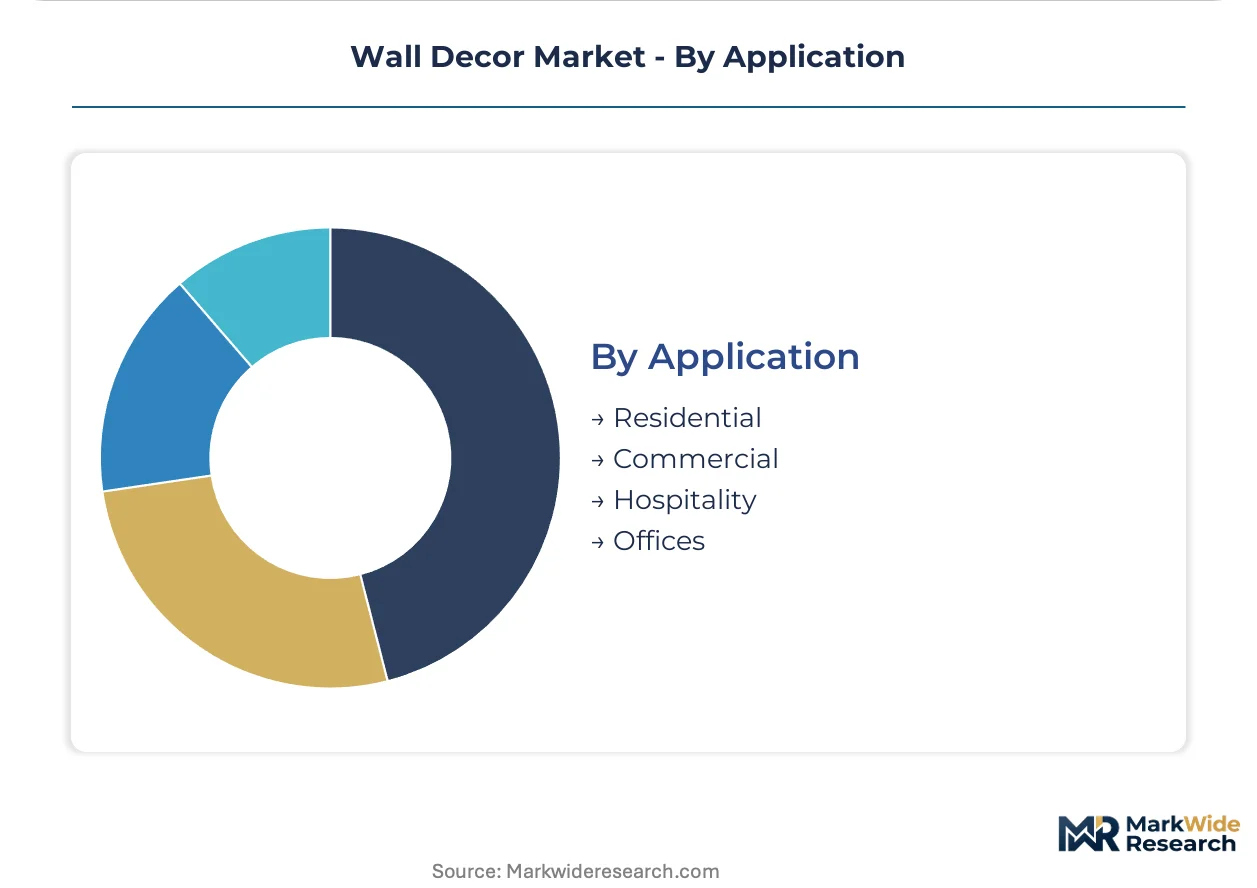
Application:
Volume maturity separates cyclical residential demand from specification-driven commercial procurement with extended replacement cycles.
- Residential:Single-family housing completions in the United States sustain DIY retail channel velocity. Millennial renovation spending drives semi-permanent installation uptake through big-box and online channels.
- Commercial:Corporate office fit-outs specify acoustic-dampening wall elements alongside decorative relief, absorbing budget allocations previously directed toward pure aesthetic installations.
- Hospitality:Hotel renovation pipelines and brand-standard refresh cycles exceeding 10,000-unit deployments specify UV-cured finishes for durability.
- Offices:Open-plan commercial spaces in urban United States markets demand dual-function metal patination with perforated substrate engineering for acoustic control.
Residential applications command the established base. Hospitality deployment shows the steepest expansion trajectory through renovation pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations under 40 CFR Part 59 shape manufacturing standards for wall decor entering the United States, the dominant geography for residential renovation demand and DIY retail channel velocity.
United States
Single-family housing completions and millennial homeowner renovation spending drive demand for canvas prints and semi-permanent installation products. California's Proposition 65 enforcement compels substrate treatment reformulation for West Coast distribution. Guangdong manufacturing clusters supply UV-cured digital printing capacity for big-box retail private labels.
Germany
ECHA REACH compliance mandates tighten chemical standards for imported wall products, forcing retailer supplier base reformulation. CSRD disclosure requirements through the EU Green Deal reshape sourcing documentation for Asian-manufactured goods. Buying offices in Frankfurt and Hamburg restructure vendor qualification protocols to preempt audit failures.
China
Dongguan and Zhejiang printing clusters dominate export-oriented manufacturing for canvas prints and wall stickers through automated digital production. MIIT industrial standards govern substrate quality for domestic distribution. Yangtze River Delta logistics hubs consolidate outbound shipment consolidation for North American and European retail channels.
France
EU Green Deal embodied carbon reporting requirements concentrate procurement scrutiny on substrate provenance and finishing energy intensity. Paris-based design ateliers retain domestic production footprints for hand-finished metal patination and limited-edition framed pieces. Lyon textile mills sustain niche tapestry weaving capacity for heritage property renovation.
Vietnam
Traditional mitered wood frame production faces generational artisan skill attrition without mechanized replacement pathways. Wood composite substrate manufacturing expands around Ho Chi Minh City industrial zones. Export dependency on Baltic birch plywood supply exposes producers to trade restriction cascades affecting Russian and Belarusian mill networks.
Wall Decor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in wall decor supply. Mass-market canvas economics concentrate around captive logistics networks and data-driven curation platforms, while premium positioning depends on direct artist relationships and museum licensing. Three archetypes dominate: flat-pack logistics integrators, algorithmic curation platforms, and artisan-network curators. Competitive moves center on backward integration into substrate manufacturing and exclusive content licensing for limited-edition releases.
Among North American retail platforms, Wayfair Inc. exemplifies data-driven curation archetypes that algorithmically match consumer preference signals to supplier inventory. IKEA anchors mass-market canvas economics through captive flat-pack logistics controlling cost structures. Williams-Sonoma Inc. occupies premium-tier positioning through direct relationships with limited-edition artists and museum licensors.
| Leading Market Players |
|---|
| IKEA |
| Wayfair Inc. |
| Target Corporation |
| Home Depot |
| Williams-Sonoma Inc. |
| Ashley Furniture Industries |
| Bed Bath & Beyond Inc. |
| Etsy Inc. |
| Art.com |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between North American big-box retailers and Guangdong printing clusters lock in UV-cured canvas capacity at fixed unit costs, stripping price visibility from spot-market buyers and compressing margin pools for non-integrated suppliers. This contract structure concentrates procurement power among data-driven platforms while fragmenting artisan-labor suppliers into price-takers without volume guarantees.
Pricing Analysis
Price spreads between Baltic birch plywood frames and Guangdong-manufactured canvas prints now exceed three-to-one on landed-cost basis. Three-tier pricing structure across premium hand-finished metal, standard UV-cured canvas, and economy pressure-sensitive vinyl reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because Dongguan clusters automate polyester-cotton substrate printing. Millennial homeowners in United States DIY channels exhibit highest price sensitivity, while hospitality procurement teams in commercial fit-outs prioritize durability premiums over unit cost.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta ports to Los Angeles-Long Beach corridor have destabilized container availability for wall sticker and canvas wrap shipments. Manufacturing gravity centers on China, Vietnam, and Indonesia, with raw material dependencies spanning Baltic birch plywood, woven polyester-cotton substrates, and REACH-compliant metal patination chemicals. Single-source vulnerability runs through Russian and Belarusian mill networks supplying wood composite substrates. Distribution runs through captive flat-pack logistics networks for mass-market canvas and independent freight forwarding for artisan-framed pieces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among data-driven curation platforms and big-box private label operators, fragmenting traditional wholesale intermediaries into margin-squeezed order-takers without algorithmic demand-forecasting capabilities.
For Market Incumbents: Shield core canvas print volumes through exclusive capacity reservations at Zhejiang UV-curing facilities, locking out emerging platform competitors from scalable reproduction economics. Deepen backward integration into woven substrate manufacturing to offset Baltic birch plywood supply disruption risks from trade restriction cascades. For New Entrants and Emerging Players: Lead with acoustic-dampening metal patination systems for open-plan commercial offices in urban United States markets, where dual-function specifications remain underpenetrated by pure decorative suppliers. Target hospitality renovation pipelines specifying 10,000-unit brand-standard refresh cycles with perforated substrate engineering that incumbent canvas printers cannot replicate. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive Guangdong manufacturing and direct United States retail relationships, positioned to capture CSRD disclosure premiums from European buyers. Watch for REACH compliance audit failures among Vietnamese frame producers as inflection signal for accelerated supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Captures margin pools from Baltic birch plywood supply disruption risks. |
| CSRD-Compliant Supply Chain Certification | Unlocks premium pricing from German and French buying offices under EU Green Deal mandates. |
| Acoustic-Dampening Product Line Extension | Addresses budget absorption by felt and mineral wool panels in commercial hospitality fit-outs. |
| Direct Artist and Museum Licensing Agreements | Defends premium positioning against algorithmic curation platforms in residential renovation channels. |
| Extended Producer Responsibility Pilot Participation | Generates reverse-logistics service revenue from jurisdiction-led renovation waste take-back programs. |
Methodological Framework
The analysis maps canvas print automation clusters, hand-finished metal ateliers, and acoustic-dampening substrate engineering segments, each validated through procurement directors at hospitality brand owners, category buyers at North American big-box retailers, and technical directors at Guangdong printing facilities. Primary interview data triangulates against customs records for Baltic birch plywood imports, EPA 40 CFR Part 59 enforcement disclosures, and EU CSRD filing drafts from major European distributors. Bottom-up unit economics from manufacturing clusters reconcile with top-down demand estimates from housing completion data and renovation spending surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, material grade, application end-use, and geographic regulatory cluster dimensions. CAGRs derive from segment-level growth rate reconciliation with macro housing turnover and hospitality renovation pipeline indicators. Forecast inputs incorporate REACH compliance cost pass-through assumptions and UV-curing equipment depreciation schedules.
Forecasts assume regulatory continuity in EPA VOC enforcement and EU Green Deal disclosure regimes; material policy shifts would require re-modeling. Supply chain disruption scenarios from Baltic mill trade restrictions and generational artisan labor attrition in Vietnam frame sensitivity bounds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Stained Glass Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
Door Handles Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
Fireplace and Stove Market