
 Asia-Pacific Interior Doors Market | 2026-2036
Asia-Pacific Interior Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Interior Doors Market Analytics
Carpentry and joinery labor pools across Vietnam and Indonesia is rotating toward prefabricated door assembly, reducing on-site fitting time and expanding addressable project scale. LIXIL Corporation leverages its integrated ceramics-to-interiors supply chain to sustain margin capture across Japan and Southeast Asia. Godrej Interio anchors residential demand in India through steel-reinforced security door variants. CenturyPly competes on laminated flush door cost structures while Greenlam Industries Ltd. differentiates via decorative veneer surface technologies.
Asia-Pacific interior doors are non-load-bearing portal assemblies, typically 35–45 mm thick, engineered for acoustic attenuation, fire containment, and spatial division within built environments. Manufacturing employs hot-press lamination for flush surfaces and CNC routing for panel profiles, with core materials ranging from hollow-cell particleboard to solid timber stiles. Wood-based panel doors retain volume leadership across residential channels, while PVC and metal-framed glass systems represent the fastest-growing material categories in commercial and hospitality fit-outs. Pre-hung installation formats command premium positioning in high-rise construction, whereas slab formats dominate renovation and custom architectural projects.
China's GB standards for formaldehyde emission in engineered wood products, India's BIS fire-resistance grading protocols, and Japan's JIS acoustic performance classifications collectively determine material eligibility and market access across the region. Compliance with these frameworks elevates R&D expenditure but simultaneously locks out uncertified imports, protecting domestic manufacturer positions. Stakeholders must monitor evolving green building code convergence between ASEAN member states and China's MEE enforcement trajectory to anticipate next-generation product specifications and certification requirements.
Market Dynamics
China's dual carbon goals and India's BIS fire-resistance mandates are redirecting capital toward low-emission cores and certified safety assemblies, compressing product development cycles and elevating compliance costs across the supply base.
Growth Catalysts
- GB formaldehyde standards:China's engineered wood emission protocols are accelerating hollow-cell particleboard replacement with soy-based adhesives and cross-laminated timber cores in residential construction.
- Prefabricated assembly:Vietnam's carpentry labor rotation toward factory-fit door systems is reducing on-site installation time and expanding project scale for hospitality developers.
- Tier-2 urbanization:India's secondary cities are absorbing steel-reinforced security door variants at volume as housing stock formalizes and mortgage penetration deepens.
Market Restraints
- Adhesive input volatility:Urea-formaldehyde resin prices fluctuate with natural gas feedstock costs, compressing margins for laminated flush door manufacturers in Indonesia.
- Core material concentration:Southeast Asian particleboard supply clusters in Thailand and Malaysia, exposing door assemblers to single-source disruption risk during monsoon logistics constraints.
- Acoustic performance ceiling:Current 35-45 mm thickness constraints limit STC ratings in high-rise residential towers, restricting penetration of premium sound-attenuation specifications.
Strategic Opportunities
- Vietnam industrial corridor:Manufacturing zones around Hai Phong and Binh Duong offer tariff-advantaged export platforms for PVC and metal-framed glass systems targeting ASEAN hospitality fit-outs.
- Pre-hung format expansion:High-rise construction in the Philippines is adopting factory-assembled frame-and-door units, reducing skilled labor dependency and accelerating floor-turn schedules.
- Green building convergence:ASEAN member states are harmonizing energy-efficiency codes with China's MEE trajectory, creating unified certification pathways for low-emission door systems across the region.
Industry Challenges
- CNC programming talent scarcity:Precision routing operations for decorative veneer profiles require specialized operators, with training pipelines lagging demand in India's manufacturing clusters.
- Fire-rating certification timelines:BIS laboratory capacity constraints extend fire-resistance testing queues to 14-18 weeks, delaying product launches for safety-core door variants.
- Legacy slab format integration:Renovation contractors resist pre-hung systems due to frame rough-opening incompatibility with existing masonry, forcing manufacturers to maintain dual product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Interior Doors Market |
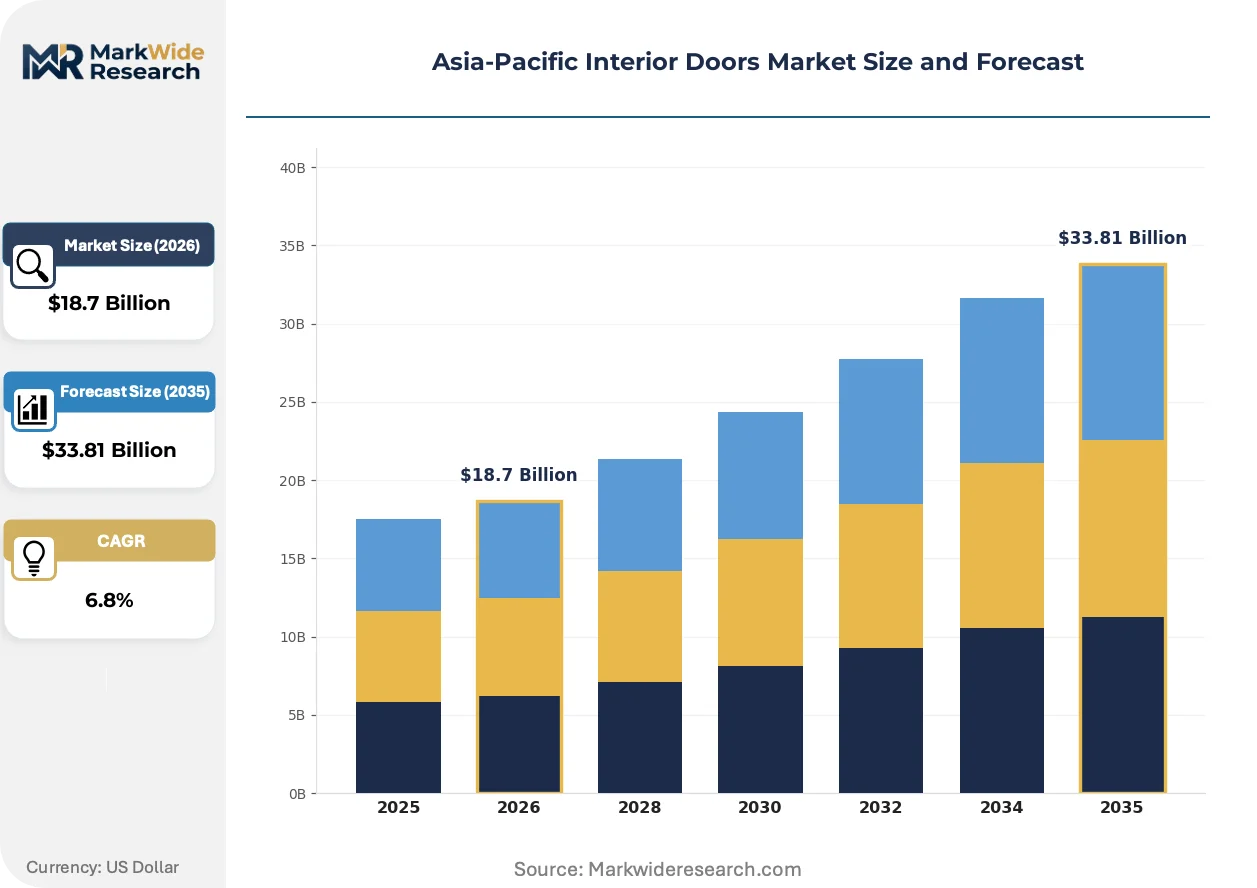
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Doors, Flush Doors, French Doors, Pocket Doors Material: Wood, PVC, Glass, Metal End User: Residential, Commercial, Hospitality, Institutional Installation Type: Pre-Hung, Slab, Bi-Fold, Sliding |
| Companies Covered | Godrej Interio, LIXIL Corporation, YKK AP, CenturyPly, Greenlam Industries Ltd., Duroply Industries Ltd., Durian Private Ltd., DAIKEN CORPORATION, Fenesta Building Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Interior Doors Market Evolving Landscape
Material science advances and regulatory tightening are converging to transform core compositions and surface technologies, while procurement patterns shift toward specification-driven consolidated purchasing.
Cross-laminated timber (CLT) door cores bonded with bio-based adhesives are displacing conventional particleboard in mid-rise residential towers across Japan and South Korea. Developers targeting JIS acoustic classifications specify CLT for its dimensional stability and mass-damping properties. The technology is displacing hollow-cell construction in premium segments where STC 45+ ratings command price premiums.
China's MEE enforcement of GB standards for formaldehyde emission is tightening material eligibility for engineered wood products entering commercial channels. Domestic manufacturers are retrofitting hot-press lines with low-emission resin systems to maintain market access. India's BIS fire-resistance grading protocols are simultaneously elevating testing requirements for safety-core assemblies, compressing the uncertified import segment.
Buyers in Southeast Asia's hospitality sector are consolidating door specifications under single-source procurement agreements, replacing fragmented project-by-project purchasing. Engineering firms specify certified pre-hung systems with embedded hardware to reduce site coordination complexity. This concentration is most visible in Vietnam's resort construction pipeline, where international operators mandate unified supplier qualification to accelerate commissioning timelines.
Asia-Pacific Interior Doors Market Segmentation
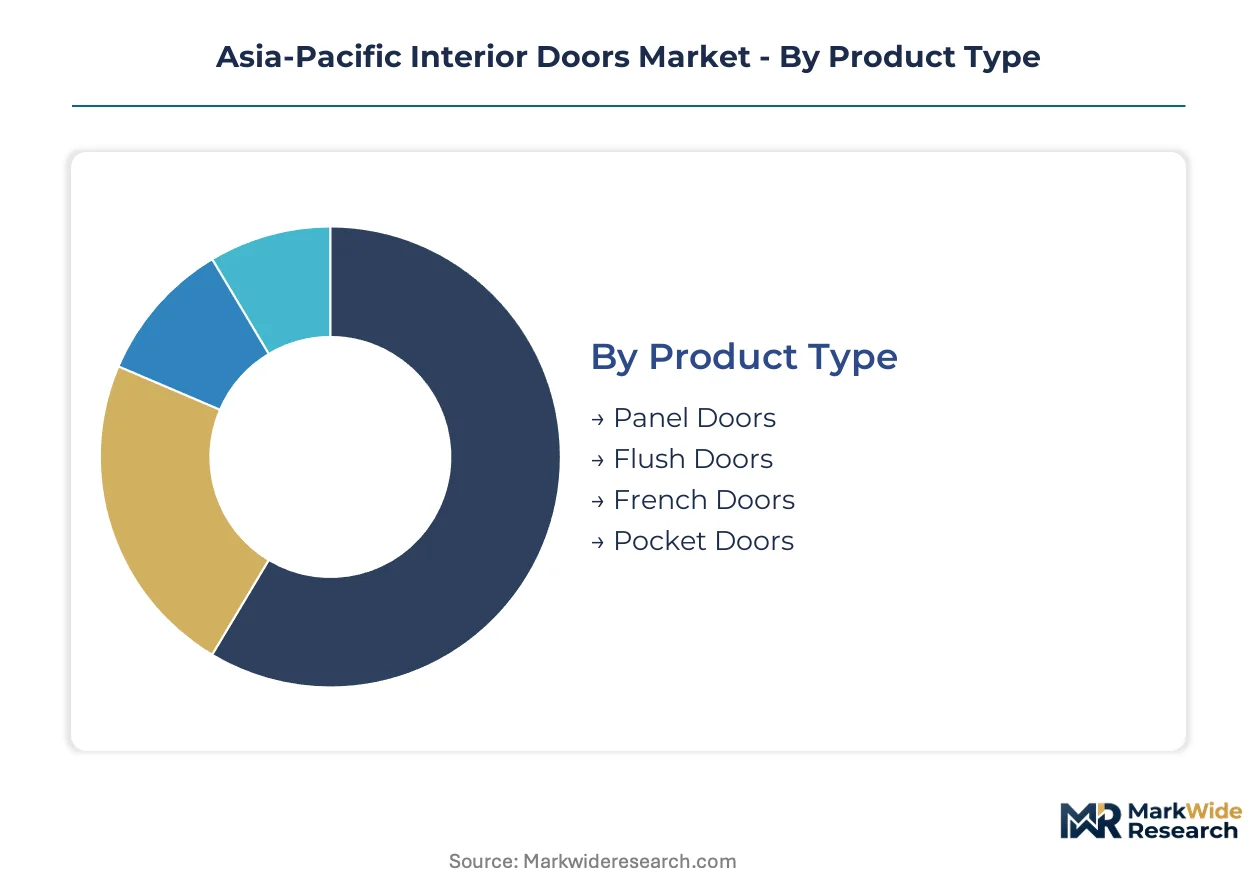
Interior door procurement across Asia-Pacific splits sharply between new construction channels favoring factory-assembled formats and renovation contractors sourcing loose slabs. Specification power concentrates with developers in high-rise residential and hospitality fit-outs, while distributors capture fragmented replacement demand.
Product Type:
Panel doors dominate residential distribution through builder merchants, while flush doors flow through project-direct channels for multi-unit housing.
- Panel Doors:Engineered stile-and-rail assemblies with raised or flat profiles, typically 40-45 mm thick with solid timber or MDF cores. Demand clusters in Japan's suburban housing and India's tier-2 cities where aesthetic customization commands premium positioning against standardized alternatives.
- Flush Doors:Flat-surface laminates bonded over hollow-cell or solid particleboard cores, manufactured via hot-press lamination. Vietnam's hospitality developers specify these for back-of-house and service corridors where cost control outweighs decorative investment.
- French Doors:Glazed double-leaf systems with divided lite patterns, common in premium residential renovations.
- Pocket Doors:Sliding assemblies recessed into wall cavities, specified for space-constrained urban apartments.
By volume, Flush Doors leads. By growth pace, Panel Doors is climbing fastest on premium residential demand.
Material:
Cost tiers separate procurement: wood commands project-direct premiums, PVC captures mid-market volume, metal and glass serve specification-driven commercial segments.
- Wood:Solid timber and engineered wood products including cross-laminated timber cores, hot-press laminated veneers, and finger-jointed stiles. China's GB formaldehyde emission standards are accelerating soy-based adhesive substitution in residential channels.
- PVC:Extruded polymer frames with honeycomb or foam cores, specified for moisture-resistant applications in Southeast Asian hospitality bathrooms and service areas.
- Glass:Tempered or laminated glazing in aluminum or steel frames, penetrating commercial fit-outs.
- Metal:Steel-reinforced or hollow-metal assemblies, concentrated in India's security-rated residential and institutional specifications.
Wood maintains the largest installed base. PVC is expanding most quickly on hospitality sector standardization.
End User:
Customer type determines specification complexity: institutional buyers mandate certified fire and acoustic ratings, while residential procurement splits between developer bulk and retail replacement.
- Residential:Single-family and multi-unit housing, spanning developer-specified new construction and homeowner-driven renovation. India's mortgage penetration in tier-2 cities is formalizing housing stock and absorbing steel-reinforced security variants.
- Commercial:Office and retail fit-outs requiring acoustic attenuation and rapid installation. Pre-hung formats reduce skilled labor dependency in Philippines high-rise construction.
- Hospitality:Hotels and resorts with unified procurement agreements and accelerated commissioning timelines. Vietnam's resort pipeline mandates single-source supplier qualification.
- Institutional:Healthcare, education, and government facilities requiring BIS fire-resistance certification and extended durability cycles.
Residential generates the highest absolute volume. Hospitality is gaining share fastest on consolidated procurement patterns.
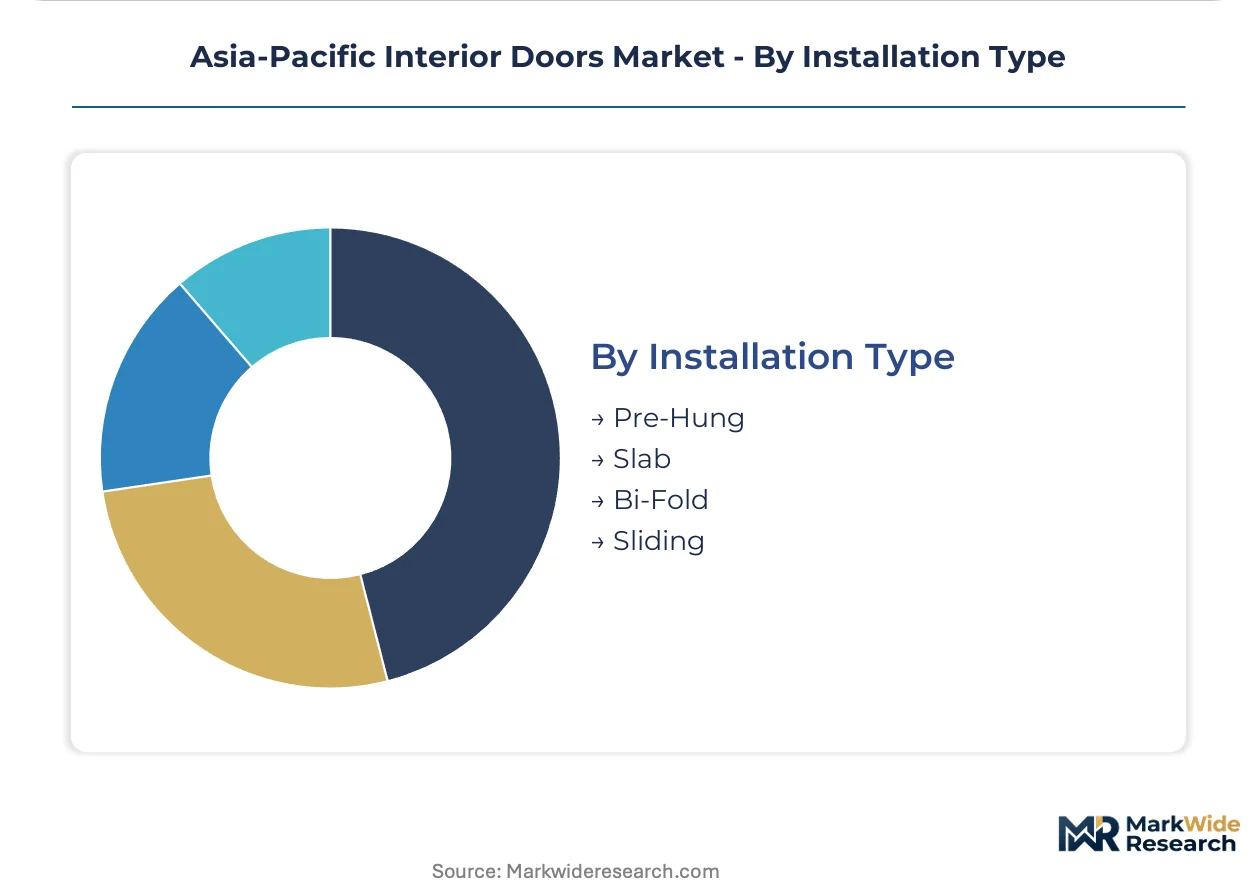
Installation Type:
Format selection hinges on labor availability and project schedule: pre-hung systems reduce site coordination where skilled carpentry is scarce, slab formats persist where frame rough-opening compatibility dominates.
- Pre-Hung:Factory-assembled frame, door, and hardware units delivered ready for rough-opening insertion. Philippines high-rise contractors adopt these to accelerate floor-turn schedules and reduce on-site fitting time.
- Slab:Door leaf only, requiring field-fabricated frames and hardware mortising. Renovation contractors across India and Indonesia prefer slabs for masonry compatibility with legacy openings.
- Bi-Fold:Hinged panel systems folding against wall planes, specified for closet and utility applications.
- Sliding:Top-hung or bottom-rolling systems for space optimization in compact urban units.
Slab formats retain volume leadership. Pre-Hung is expanding most quickly on high-rise construction adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands pricing premiums for JIS-certified acoustic assemblies while Vietnam captures volume through tariff-advantaged export platforms. This asymmetry reshapes manufacturer location decisions across the region.
China
MEE enforcement of GB formaldehyde emission standards is accelerating soy-based adhesive substitution in residential channels. Domestic manufacturers retrofit hot-press lines to maintain commercial channel access. Manufacturing clusters around Guangdong and Zhejiang provinces supply engineered wood cores for regional export.
Japan
JIS acoustic performance classifications drive specification of cross-laminated timber cores in mid-rise residential towers. METI building efficiency codes elevate mass-damping properties as a procurement criterion. Kanto region fabricators concentrate precision routing capacity for decorative veneer profiles.
India
BIS fire-resistance grading protocols compress the uncertified import segment while extending laboratory testing queues to 14-18 weeks. Mortgage penetration in tier-2 cities formalizes housing stock and absorbs steel-reinforced security variants. Maharashtra and Gujarat manufacturing clusters face CNC programming talent scarcity.
Vietnam
Hospitality developers around Hai Phong and Binh Duong industrial zones mandate single-source supplier qualification for accelerated commissioning timelines. Carpentry labor rotation toward factory-fit systems reduces on-site installation time. ASEAN tariff advantages position Vietnamese assemblers for regional hospitality fit-out exports.
South Korea
CLT door core adoption parallels Japan's JIS acoustic trajectory with MFDS-adjacent building material standards tightening emission benchmarks. Seoul Capital Area developers specify dimensional stability for high-rise residential STC ratings. Busan-Ulsan corridor manufacturers serve cross-border specification demand.
Asia-Pacific Interior Doors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific interior doors market. Integrated building materials conglomerates compete against specialized door fabricators and diversified interior solutions providers. Three archetypes dominate: ceramics-to-interiors supply chain integrators, plywood and laminate specialists, and security-focused metal reinforcement fabricators. Competitive moves concentrate on pre-hung format standardization for high-rise construction and low-emission core material certification for green building compliance.
Among Japan-based building materials conglomerates, LIXIL Corporation and DAIKEN CORPORATION exemplify supply chain integration archetypes spanning ceramics to interior assemblies. Godrej Interio anchors the India-centric security reinforcement segment. These three occupy positions across distinct competitive vectors—integrated supply chain control, low-emission material certification, and steel-reinforced safety core specialization—without overlapping direct contestation in identical specification tiers.
| Leading Market Players |
|---|
| Godrej Interio |
| LIXIL Corporation |
| YKK AP |
| CenturyPly |
| Greenlam Industries Ltd. |
| Duroply Industries Ltd. |
| Durian Private Ltd. |
| DAIKEN CORPORATION |
| Fenesta Building Systems |
| Others |
Value Network & Pricing Analysis
Soy-based adhesive substitution for urea-formaldehyde resins is redrawing procurement geography across the Asia-Pacific interior doors market, compressing margins for Indonesian laminated flush door manufacturers while elevating cost structures for Chinese exporters seeking GB standard compliance.
Pricing Analysis
The customization-premium spread separates configured-to-order panel doors with decorative veneer profiles from standard flush door slabs. Project-direct channels for pre-hung systems command premium positioning against distributor-sourced renovation slabs. Price differentiation hinges on JIS acoustic certification tier and fire-resistance rating grade. Cost compression in economy-tier particleboard doors is intensifying because of natural gas feedstock volatility. Hospitality developers in Vietnam exhibit lowest price sensitivity while India's tier-2 residential contractors drive volume at margin-thin price points.
Supply Chain Analysis
Port congestion on the Shanghai-Singapore trade lane is elevating inbound logistics costs for particleboard cores sourced from Thailand and Malaysia. Engineered wood supply concentrates in China, Thailand, and Malaysia, with hot-press lamination capacity clustering around Guangdong and Zhejiang provinces. Raw material dependencies include urea-formaldehyde resins, cross-laminated timber billets, and decorative veneer sheets. Single-source vulnerability in Southeast Asian particleboard exposes assemblers to monsoon-season disruption. Distribution runs through builder merchants for residential panel doors and project-direct specification for commercial pre-hung systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific interior doors market functions as a defensive-moat arena where BIS fire-rating certification entrenchment creates switching costs that lock institutional buyers into qualified supplier relationships.
For Market Incumbents: Secure BIS laboratory capacity reservations to compress fire-resistance testing queues from 14-18 weeks toward competitive lead times. Anchor positions in Vietnam's hospitality corridor through single-source procurement agreements with international resort operators. The threat of CLT core displacement in premium acoustic segments demands R&D investment in mass-damping surface technologies. For New Entrants and Emerging Players: BIS certification fast-track partnerships with Maharashtra and Gujarat testing facilities open institutional channel access currently blocked to uncertified imports. White-space targets include India's tier-2 steel-reinforced security door segment and Philippines high-rise pre-hung installation formats. The most penetrable geography is Vietnam's Binh Duong industrial zone where carpentry labor rotation toward factory-fit systems reduces incumbent installation-time advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated building materials conglomerates with captive ceramics-to-interiors supply chain control. Long-term viability over the next decade hinges on low-emission core material certification alignment with ASEAN green building code convergence. Acquisition target archetypes include precision routing specialists with CNC programming talent pipelines. The signal to watch is MEE enforcement trajectory on GB formaldehyde standards tightening material eligibility thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Hung Format Standardization | Philippines high-rise contractors adopt factory-assembled units to accelerate floor-turn schedules. |
| Low-Emission Core Certification | China's MEE enforcement of GB standards retrofits hot-press lines for commercial channel access. |
| CLT Core Manufacturing Scale-Up | Japan's JIS acoustic classifications drive specification for STC 45+ premium residential towers. |
| Single-Source Procurement Agreements | Vietnam's hospitality developers mandate unified supplier qualification for accelerated commissioning. |
| CNC Routing Talent Pipeline Development | India's manufacturing clusters face programming scarcity for decorative veneer precision operations. |
Research Methodology
A spread of perspectives from door manufacturing plant managers, hospitality procurement directors, BIS certification laboratory technicians, and builder merchant category buyers converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC filings of listed building materials conglomerates, ASEAN construction permit databases, and JIS acoustic performance testing registries. Bottom-up project pipeline enumeration triangulated against top-down construction spend allocation across residential, commercial, and hospitality end-use segments.
Segmentation dimensions modeled include product type, material composition, end-user category, and installation format across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves calibrated to regulatory enforcement schedules and mortgage penetration trajectories. Industry-specific forecast inputs incorporated CLT core adoption rates in Japan and South Korea, BIS fire-rating certification queue durations, and prefabricated assembly labor rotation patterns in Vietnam.
Decision-makers should treat outputs as directional under assumptions of sustained MEE enforcement continuity and ASEAN tariff structure stability; material deviation would warrant model refresh. Specific risk factors include adhesive input cost volatility, monsoon logistics disruption in Southeast Asian particleboard supply clusters, and BIS laboratory capacity constraints extending certification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
Removable Wallpaper Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Interior Design Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
Window Covering Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Door Handles Market