
 United States Mattress Market | 2026-2036
United States Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
United States Mattress Market Outlook
California's Title 17 flammability standards is rebalancing material sourcing across the industry, pushing manufacturers toward certified foam and barrier technologies. Tempur Sealy International leverages its vertically integrated domestic manufacturing to sustain margin control amid compliance shifts. Purple Innovation anchors its position through proprietary gel-grid engineering that differentiates against commodity foam rivals.
A mattress is a textile-based sleep support system constructed with layered foam, innerspring coils, latex, or hybrid assemblies, typically measuring between six and fourteen inches in thickness, designed to provide pressure relief and spinal alignment for residential or commercial end-users. The product type dimension shows memory foam and hybrid constructions capturing premium positioning as consumers prioritize pressure relief and temperature regulation over traditional innerspring units. Within distribution channels, online direct-to-consumer platforms now occupy the fastest-growing tier, while retail stores continue to dominate volume through white-glove delivery and trial-period services.
The Consumer Product Safety Commission enforces federal flammability standards under 16 CFR Part 1633, while state-level regulators such as California's Bureau of Electronic and Appliance Repair, Home Furnishings and Thermal Insulation administer stricter chemical disclosure rules that shape material selection and labeling requirements. The Federal Trade Commission monitors environmental marketing claims, constraining how brands communicate sustainability attributes to consumers. Stakeholders must monitor evolving chemical restriction proposals at the state level to anticipate reformulation costs and compliance timelines.
Market Dynamics
California's Title 17 flammability standards are compressing material sourcing options and forcing nationwide reformulation as manufacturers standardize to the strictest state rule rather than maintain dual SKUs.
Growth Catalysts
- Residential sleep system upgrades:Post-pandemic household formation and remote work normalization are accelerating mattress replacement cycles among suburban homeowners.
- Hospitality sector concentration in Texas and Florida:Hotel construction pipelines in Dallas, Houston, Orlando, and Miami are absorbing bulk orders from contract manufacturers.
- 16 CFR Part 1633 federal compliance:CPSC enforcement of open-flame standards continues validating certified barrier technologies and expanding addressable market for compliant producers.
Market Restraints
- Petrochemical feedstock volatility:Polyol and TDI pricing swings compress foam producers' margin predictability and complicate long-term contract bidding.
- Asian component concentration:Specialty fabric barriers and certain coil wire grades depend on concentrated overseas supply, exposing assemblers to tariff and logistics risk.
- Extended product lifecycles:Durable hybrid constructions with 10-year warranties are elongating replacement intervals versus traditional innerspring units.
Strategic Opportunities
- Direct-to-consumer platform expansion:White-glove delivery networks in secondary metros remain underdeveloped relative to coastal density, offering first-mover positioning.
- State-level chemical disclosure mandates:California's Bureau of Electronic and Appliance Repair, Home Furnishings and Thermal Insulation labeling rules create premium positioning for transparent supply chains.
- Smart-sensor integration:Convergence of pressure-mapping foams with sleep-tracking hardware opens subscription revenue models for recovery-focused athletic segments.
Industry Challenges
- Certified foam chemist scarcity:Formulation expertise meeting California TB 117-2013 and evolving state restrictions commands wage premiums that smaller assemblers struggle to match.
- Legacy ERP integration with omnichannel fulfillment:Wholesale-rooted manufacturers face system friction unifying retail floor, warehouse, and drop-ship inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Mattress Market |
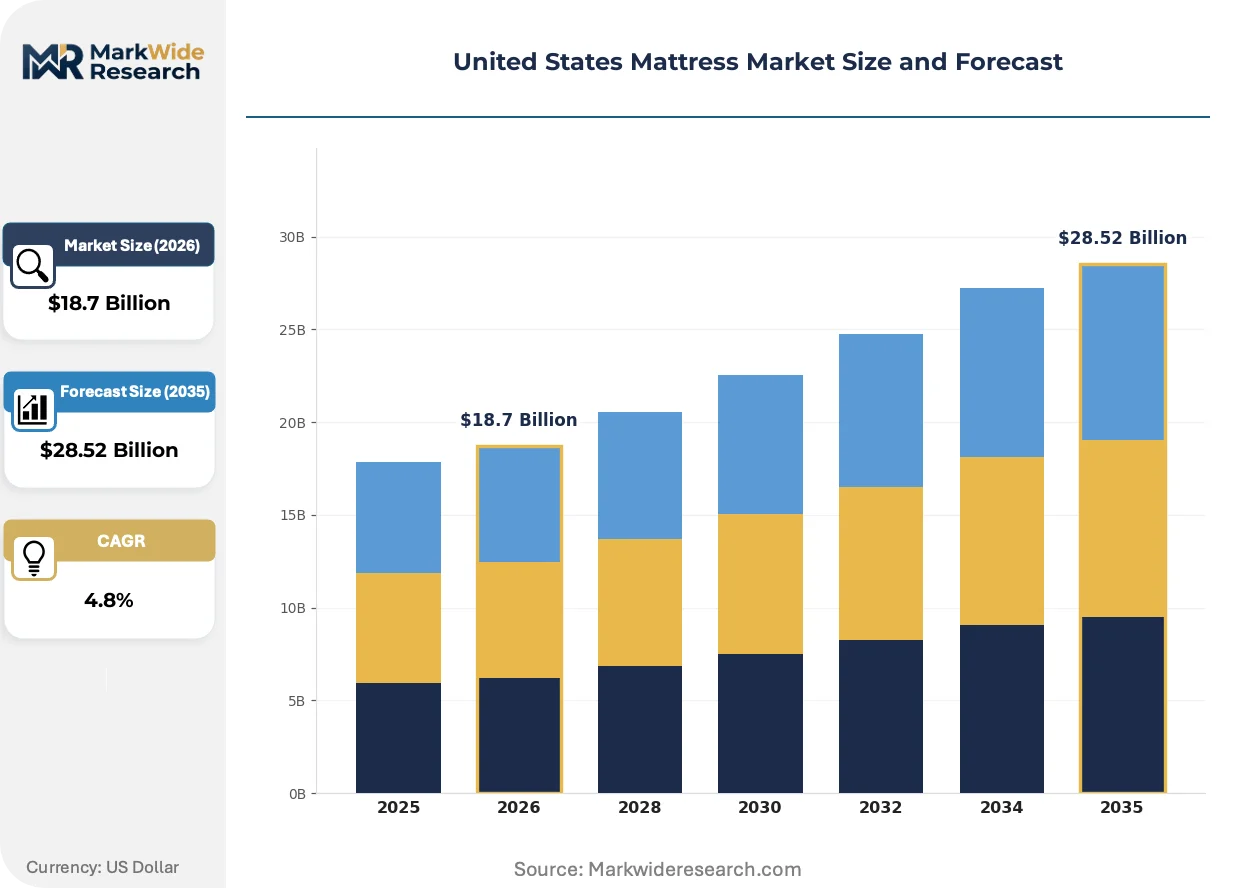
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid Customer Type: Residential, Hospitality, Healthcare, Education Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales Price Tier: Economy, Mid-range, Luxury, Premium |
| Companies Covered | Purple Innovation, Saatva, Tempur Sealy International, Casper Sleep, Brooklyn Bedding, Serta Simmons Bedding, Helix Sleep, Resident (Nectar), Sleep Number Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Mattress Market Strategic Shifts
Material science advances and channel restructuring are redrawing competitive boundaries, with sustainability verification and sleep-data capture emerging as distinct value-creation vectors.
Gel-infused open-cell foam is absorbing excess body heat and reducing surface temperature retention. Athletic recovery segments and warm-climate households are adopting these constructions fastest. The technology is absorbing market share from traditional memory foam by solving its core thermal complaint without sacrificing pressure relief.
California's Bureau of Electronic and Appliance Repair, Home Furnishings and Thermal Insulation continues tightening chemical disclosure thresholds under SB 1019. Manufacturers must now document flame retardant presence at component level, not finished product. Private-label suppliers serving California retailers are accelerating third-party testing investments to maintain shelf access.
Buyers now expect compressed roll-pack delivery with 100-night trial periods as table stakes, not premium add-ons. Traditional furniture galleries are unbundling white-glove service or absorbing its cost to match online-native competitors. This pattern concentrates in Sun Belt metros where new household formation and digital commerce penetration overlap most densely.
United States Mattress Market Segmentation
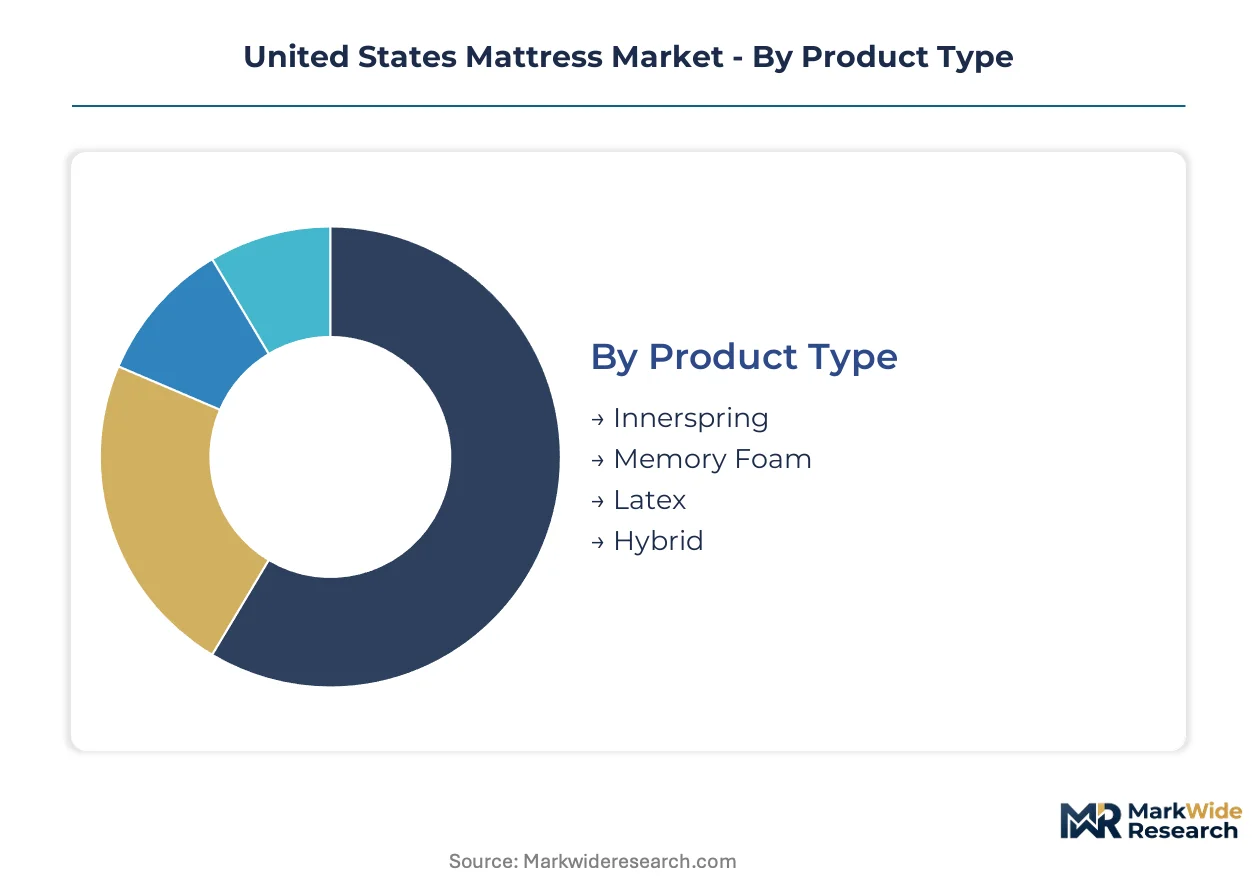
Segmentation in the United States mattress market reveals how construction methods, procurement patterns, and channel economics create distinct competitive arenas. Manufacturers must align production flexibility against the standardization pressures of contract hospitality and the customization demands of direct-to-consumer residential buyers.
Product Type:
Customization intensity spans from standardized coil assemblies to engineered foam formulations with proprietary chemistry.
- Innerspring:Steel coil support systems with varying wire gauges and coil counts deliver familiar bounce and airflow. Hospitality buyers in Texas and Florida specify these units for bulk procurement cost control and rapid room turnover durability.
- Memory Foam:Viscoelastic polyurethane formulations contour to body pressure points and isolate motion. Residential consumers upgrading sleep systems in suburban markets prioritize these constructions for pressure relief, though thermal retention remains a complaint driver.
- Latex:Natural or synthetic rubber foam derived from tapped sap or petrochemical polymerization. California's Bureau of Electronic and Appliance Repair labeling rules push disclosure requirements on latex sourcing claims.
- Hybrid:Coil base layers topped with foam or latex comfort systems combine support and contouring. These constructions command warranty extensions that elongate replacement cycles versus traditional innerspring units.
Most installed capacity flows through innerspring constructions. Expansion is steepest in hybrid configurations.
Customer Type:
Volume concentration versus margin capture separates contract-specified institutional buyers from discretionary residential purchasers.
- Residential:Individual households purchasing through retail or direct-to-consumer channels for primary or guest bedrooms. Remote work normalization has compressed replacement cycles among suburban homeowners establishing dedicated home offices and sleep spaces.
- Hospitality:Hotel, motel, and resort operators procuring standardized units in bulk. Construction pipelines in Dallas, Houston, Orlando, and Miami absorb substantial contract manufacturer output with white-glove installation requirements.
- Healthcare:Hospitals, long-term care facilities, and rehabilitation centers specifying pressure-relief surfaces. Medicare reimbursement codes influence foam density and cover material specifications for therapeutic mattresses.
- Education:University dormitories and boarding schools purchasing durable, cost-controlled sleep systems. Procurement concentrates in summer installation windows with compressed delivery timelines.
Residential channels generate the highest unit margins. Hospitality procurement is climbing the fastest as Sun Belt construction accelerates.
Distribution Channel:
Channel selection determines fulfillment infrastructure requirements and customer acquisition economics.
- Online:Direct-to-consumer platforms with compressed roll-pack logistics and trial-period guarantees. Secondary metro white-glove delivery networks remain underdeveloped relative to coastal density.
- Retail Stores:Furniture galleries and mattress specialty shops offering floor model testing and immediate delivery. Traditional galleries absorb white-glove service costs to match online-native competitors.
- Wholesalers:Regional distributors serving independent furniture retailers and hospitality procurement agents. Inventory visibility systems lag omnichannel integration requirements.
- Direct Sales:Manufacturer-owned showrooms and factory-direct outlets bypassing intermediary margins. These channels concentrate brand equity control in top-25 metro areas.
Retail stores still handle the greatest transaction volume. Online channels are expanding most quickly as digital commerce penetration deepens in Sun Belt markets.
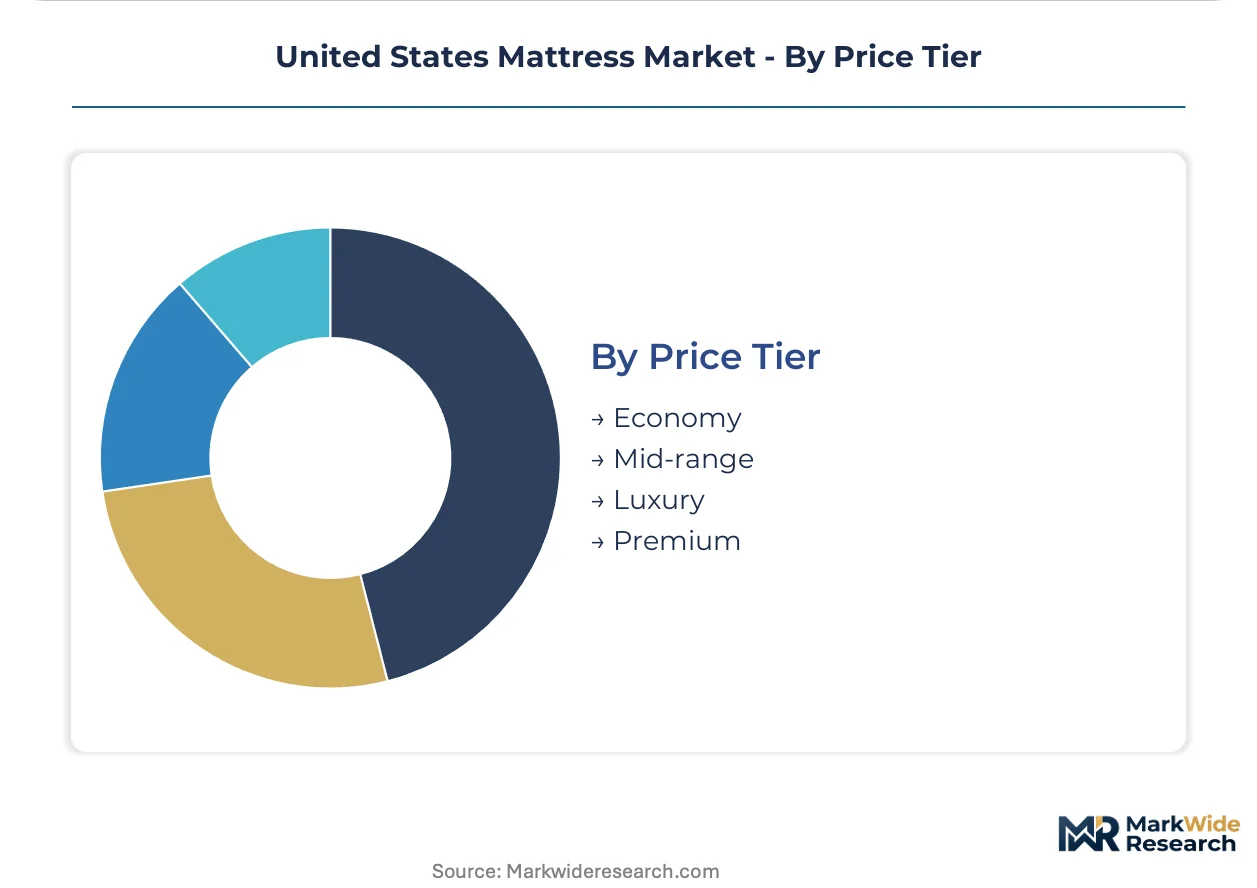
Price Tier:
Material specification and certification grade stratify accessible entry points from performance-premium positioning.
- Economy:Basic innerspring or low-density foam constructions with minimal warranty terms. Price-sensitive dormitory and budget hospitality procurement dominates this tier.
- Mid-range:Enhanced coil systems or gel-infused memory foam with 5-7 year warranties. California Title 17 compliance costs compress margins at this tier most severely.
- Luxury:Advanced hybrid assemblies with zoned support and temperature-regulating covers. Athletic recovery segments and warm-climate households adopt these constructions fastest.
- Premium:Proprietary foam chemistry, organic latex, or smart-sensor integration with extended warranties. Transparent supply chain documentation commands price premiums under state chemical disclosure mandates.
Mid-range units absorb the largest production volume. Premium tier expansion is accelerating as certified foam scarcity creates supply-constrained positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States mattress industry traces its modern scale to postwar suburban expansion and the 1956 invention of polyurethane foam production, which shifted manufacturing from regional coil shops to national chemical-integrated operations. Today, demand concentrates in Sun Belt metros while regulatory divergence between states reshapes material sourcing geography.
California
Los Angeles and San Francisco Bay Area households drive premium-tier demand for temperature-regulating and organic-certified constructions. The Bureau of Electronic and Appliance Repair, Home Furnishings and Thermal Insulation enforces SB 1019 chemical disclosure mandates that now require component-level flame retardant documentation. Manufacturers serving California retailers have consolidated testing and certification operations in Ontario and Fontana to minimize compliance latency.
Texas
Dallas-Fort Worth and Houston construction pipelines absorb bulk hospitality procurement for hotel flag deployments across the Interstate 35 and Interstate 10 corridors. The Texas Department of Licensing and Regulation maintains comparatively permissive chemical standards, allowing manufacturers to ship non-California-compliant SKUs into the state. Domestic foam pouring capacity has expanded in Sealy and Temple to serve regional contract manufacturers.
Florida
Orlando and Miami hospitality markets demand rapid-turnover durability specifications for resort and cruise line bedding refresh cycles. The Florida Department of Agriculture and Consumer Services regulates mattress labeling but defers to federal flammability baselines. Tampa and Lakeland have attracted warehouse and final-assembly operations targeting Caribbean and Latin American export channels through Port Miami and Port Everglades.
Illinois and Ohio Corridor
Chicago and Cleveland metropolitan areas retain legacy innerspring manufacturing infrastructure serving Midwest retail chains and institutional buyers. The Consumer Product Safety Commission's 16 CFR Part 1633 enforcement maintains uniform federal baselines across these states. Industrial clusters in Elkhart, Indiana and Dayton, Ohio specialize in coil wire forming and quilted panel assembly for branded OEM supply.
Pacific Northwest
Seattle and Portland consumers show elevated preference for natural latex and sustainably sourced materials, compressing margins for conventional foam suppliers. The Washington State Department of Ecology has advanced chemical restriction proposals that would exceed federal disclosure thresholds. Regional manufacturers in Tacoma and Eugene have invested in organic certification and transparent supply chain documentation to capture premium positioning.
United States Mattress Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure. Vertically integrated domestic manufacturers with captive foam pouring and coil forming operations sustain margin control against digital-native brands that outsource production to contract assemblers. Three archetypes dominate: established chemical-integrated incumbents, direct-to-consumer platform specialists, and private-equity-backed roll-up consolidators. Competitive moves concentrate on compressed logistics network expansion and proprietary material chemistry differentiation.
Among established integrated manufacturers, Tempur Sealy International and Serta Simmons Bedding exemplify scale-driven archetypes with domestic production footprints. Purple Innovation occupies a position within the technology-differentiated tier, leveraging proprietary gel-grid engineering against commodity foam alternatives. These three anchors illustrate how competitive positioning splits between manufacturing control and design-led brand equity.
| Leading Market Players |
|---|
| Purple Innovation |
| Saatva |
| Tempur Sealy International |
| Casper Sleep |
| Brooklyn Bedding |
| Serta Simmons Bedding |
| Helix Sleep |
| Resident (Nectar) |
| Sleep Number Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between California-compliant and standard SKUs splits pricing power along compliance lines, forcing manufacturers to absorb reformulation costs in mid-range tiers while capturing premiums in documented supply chains. This bifurcation reshapes both margin structures and sourcing geography as producers consolidate testing operations near West Coast distribution hubs.
Pricing Analysis
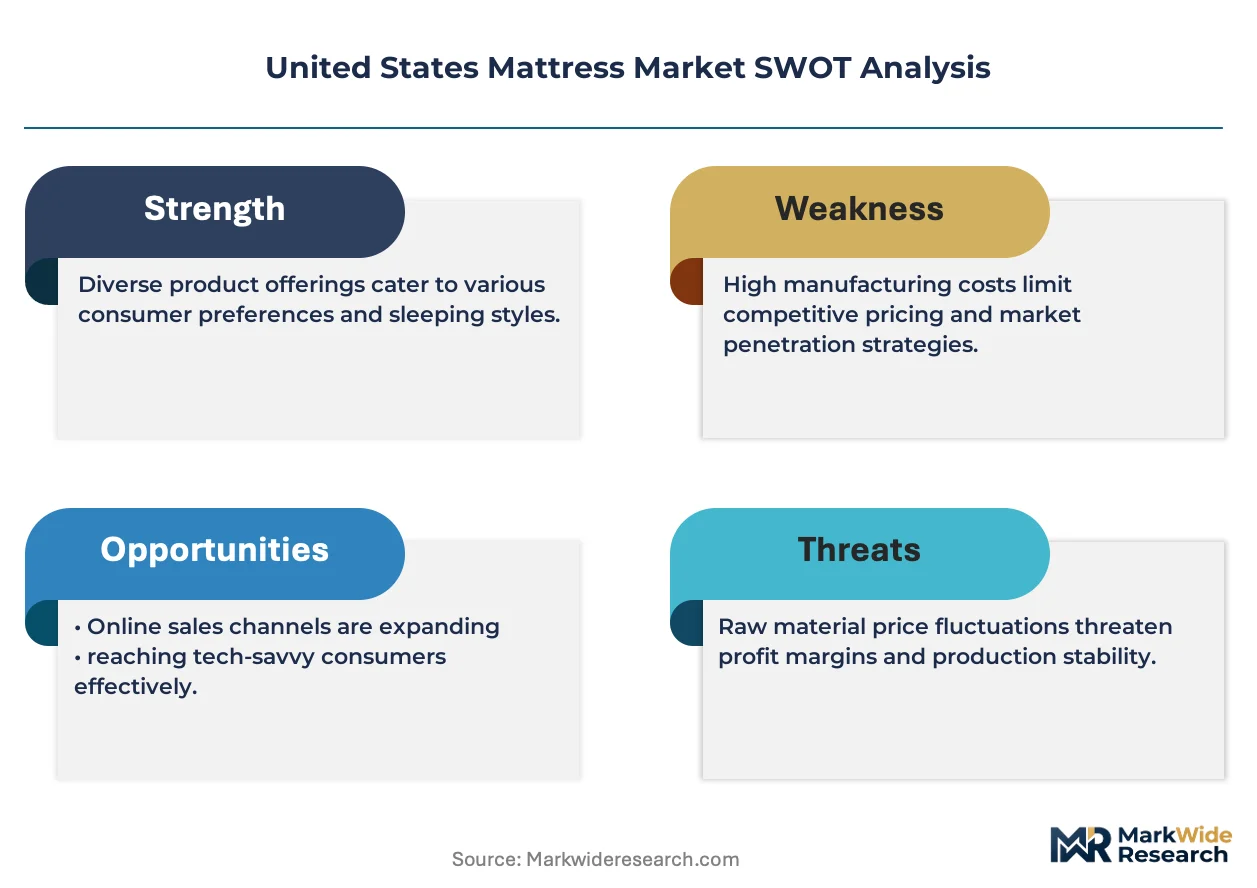
Three-tier pricing structure across premium, standard, and economy levels dominates transaction economics, with differentiation anchored in flame-retardant certification grade and white-glove delivery bundling. Pricing pressure stems from petrochemical feedstock volatility compressing foam producer margins, particularly in economy and mid-range tiers where buyers exhibit acute price sensitivity. Hospitality procurement in Texas and Florida demonstrates lowest price elasticity due to bulk contract structures, while residential online buyers comparison-shop aggressively.
Supply Chain Analysis
Regional distribution centers in Ontario, Fontana, Sealy, and Temple form a hub-and-spoke pattern serving coastal compliance zones and Sun Belt hospitality corridors. Raw material dependencies draw from China for specialty fabric barriers, South Korea for certain coil wire grades, and domestic petrochemical complexes for polyol and TDI feedstocks. Tariff exposure on Asian component imports creates supply chain risk, particularly for smaller assemblers lacking inventory buffers. Distribution runs through compressed roll-pack logistics for direct-to-consumer channels and white-glove networks for retail gallery fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States mattress market functions as a stable compounder, with residential sleep system replacement cycles providing predictable demand baselines even through economic softness.
For Market Incumbents: Acquire certified foam chemist capacity and captive barrier fabric production to defend against reformulation cost spikes and Asian supply disruption. Tempur Sealy International's vertically integrated domestic manufacturing provides a template for margin control amid California Title 17 compliance shifts. Prioritize ERP integration unifying retail floor, warehouse, and drop-ship inventory visibility to reduce omnichannel friction. For New Entrants and Emerging Players: Proprietary gel-grid or pressure-mapping foam technologies offer differentiation wedges against commodity memory foam rivals. Secondary metro white-glove delivery networks remain underdeveloped relative to coastal density, presenting first-mover positioning in Sun Belt markets where household formation and digital commerce penetration overlap. Launch through direct-to-consumer platforms with 100-night trial guarantees to match table-stakes expectations without legacy retail overhead. For Investors and Strategic Acquirers: Consolidation pressure builds where certified foam expertise concentrates among a handful of domestic pourers and barrier suppliers. The five-to-ten-year viability window favors platforms with transparent supply chain documentation capable of capturing California SB 1019 premium positioning. Target acquisition archetypes include regional contract manufacturers with hospitality relationships in Texas and Florida. Watch for state-level chemical restriction proposals beyond California as inflection indicators for accelerated reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Pouring | Captive polyol processing insulates margin control against TDI price swings and California compliance latency. |
| White-Glove Network Expansion | Secondary metro delivery density in Dallas-Fort Worth and Orlando captures hospitality procurement requiring rapid room turnover. |
| Smart-Sensor Platform Development | Pressure-mapping foams with sleep-tracking hardware open subscription revenue models for athletic recovery segments. |
| Third-Party Certification Investment | SB 1019 component-level documentation maintains shelf access among California retailers enforcing disclosure mandates. |
| Compressed Logistics Optimization | Roll-pack density improvements reduce last-mile costs for online channels competing on free delivery expectations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mattress manufacturer executives, hospitality procurement directors, foam chemists, retail category managers, and logistics operators with secondary validation. Sources included CPSC enforcement records, California Bureau of Electronic and Appliance Repair filings, customs trade data on polyol and fabric barrier imports, and SEC disclosures from publicly traded bedding companies. Bottom-up unit shipment modeling and top-down retail audit triangulation anchored value estimates.
Segment-weighting approaches distributed volume across product type, customer category, distribution channel, and price tier dimensions, with hybrid construction share and direct-to-consumer penetration treated as dynamic inputs across the projection horizon. CAGRs derived from replacement cycle analysis, household formation projections, and hospitality construction pipeline tracking. Forecast inputs incorporated petrochemical feedstock price correlation models and state-level regulatory adoption probability assessments.
The model holds under stable federal flammability enforcement and gradual state disclosure expansion; deviation in accelerated chemical restriction timelines or severe tariff escalation would shift reformulation cost assumptions and sourcing geography. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Latin America Mattress Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Bed Formers Market