
 Mattresses and Accessories Market | 2026-2036
Mattresses and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Mattresses and Accessories Market Foresight
Buyer concentration among hospitality chains and institutional procurement channels is expanding as hotels, senior living operators, and rental property managers consolidate purchasing through national contracts. Tempur Sealy International leverages its vertical manufacturing footprint to serve these volume buyers directly. Serta Simmons Bedding anchors its position through broad retail distribution and private-label partnerships. Sleep Number Corporation differentiates via adjustable air-chamber technology and direct-to-consumer channels.
Mattresses and accessories comprise sleep systems constructed from layered foam, coil, latex, or hybrid assemblies typically ranging from six to fourteen inches in thickness, designed to provide ergonomic support and pressure relief for residential and commercial end users. Memory foam formulations with open-cell structures and gel infusions dominate premium positioning due to contouring performance and thermal regulation advantages. The accessory category captures recurring revenue streams as mattress protectors and toppers carry shorter replacement cycles than core mattresses. Hybrid constructions combining innerspring support with foam comfort layers represent the fastest-growing product architecture as consumers seek balanced durability and pressure relief without the heat retention of all-foam designs.
The Consumer Product Safety Commission enforces federal flammability standards under 16 CFR Part 1633, while the EPA monitors volatile organic compound emissions from polyurethane foam production; California's Bureau of Household Goods and Services maintains additional upholstery and bedding safety requirements that de facto shape national product specifications. CertiPUR-US and OEKO-TEX certification programs increasingly function as market access filters for foam suppliers and finished goods importers. Stakeholders must monitor how state-level extended producer responsibility frameworks and chemical disclosure mandates reshape material sourcing decisions and manufacturing location strategies.
Market Dynamics
CertiPUR-US foam certification and evolving flammability standards under 16 CFR Part 1633 are forcing manufacturers to reformulate polyurethane chemistry and relocate production, compressing margins for uncertified suppliers while rewarding vertically integrated compounders.
Growth Catalysts
- Hospitality Procurement Consolidation:Hotel chains and short-term rental operators are aggregating sleep system purchases through national contracts, creating volume pull for standardized hybrid mattress specifications.
- 16 CFR Part 1633 Compliance:Federal open-flame mattress flammability standards are mandating barrier technologies and fire-resistant foam formulations, filtering out non-compliant imports.
- Gel-Infused Memory Foam:Open-cell viscoelastic formulations with thermal phase-change materials are capturing premium residential demand by solving heat retention complaints that plagued first-generation memory foam.
Market Restraints
- Polyether Polyol Volatility:Crude oil-linked feedstock costs for polyurethane foam production create margin compression that uncertified manufacturers cannot pass through to price-sensitive retail channels.
- Chinese Foam Concentration:Bulk polyurethane slabstock production clusters in Shandong and Zhejiang provinces, exposing finished goods importers to tariff volatility and ocean freight rate spikes.
- Innerspring Substitution Ceiling:Traditional coil systems retain cost advantages below $400 retail price points, limiting all-foam and hybrid penetration in economy-tier distribution.
Strategic Opportunities
- Senior Living Sleep Systems:Assisted living and memory care facilities are specifying pressure-relief surfaces with egress-friendly heights, creating dedicated procurement channels outside conventional retail.
- California SB 1015 Extended Producer Responsibility:State-level mattress recycling mandates are creating compliance-service revenue streams for producers who establish take-back infrastructure ahead of enforcement.
- Air-Chamber Smart Integration:Convergence of adjustable firmness technology with biometric sleep tracking is enabling subscription-based wellness positioning in direct-to-consumer channels.
Industry Challenges
- CertiPUR-US Testing Backlogs:Third-party laboratory capacity constraints for VOC emissions and durability certification are extending product launch timelines by 90-120 days for reformulated foam submissions.
- Legacy ERP Integration:Batch-oriented manufacturing execution systems at established foam pourers require capital-intensive retrofitting to support mass-customization workflows demanded by configurable hybrid platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mattresses and Accessories Market |
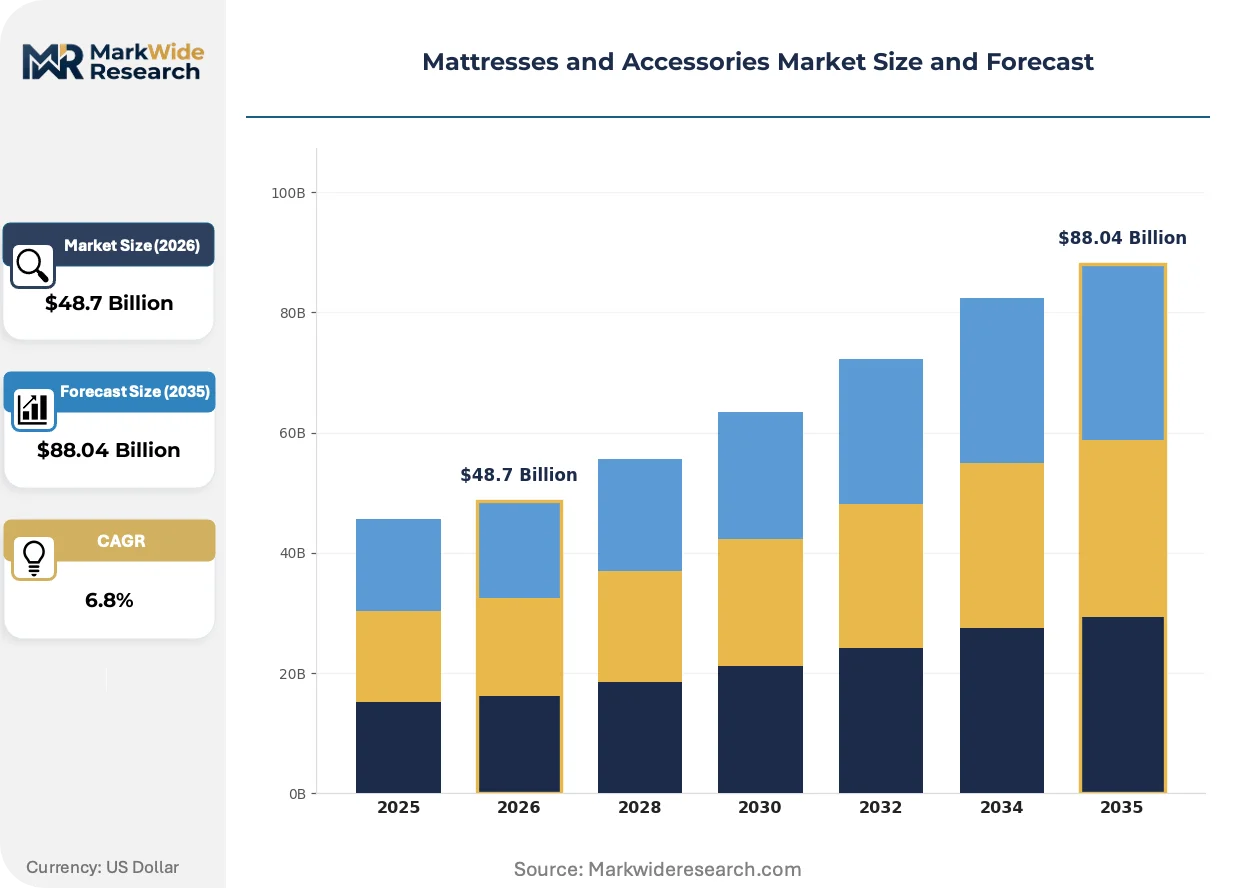
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid Accessory Type: Pillows, Mattress Protectors, Bed Frames, Mattress Toppers Size: Queen, King, Twin, Full Firmness Level: Soft, Medium, Firm, Extra Firm |
| Companies Covered | Tempur Sealy International, Serta Simmons Bedding, Sleep Number Corporation, Casper Sleep, Leggett & Platt, Kingsdown, Purple, Spring Air International, Paramount Bed Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mattresses and Accessories Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry mandates are converging to redefine competitive advantage around thermal performance, fire safety, and circular material flows rather than coil count or brand heritage.
Copper-infused and graphite-doped memory foam is rewriting thermal management expectations in premium sleep systems. Hospitality procurement teams specify these formulations for properties in warm-climate destinations where guest complaints about heat retention damage review scores. The technology is compressing differentiation timelines for legacy gel-infusion patents.
REACH restrictions on isocyanates and California's Bureau of Household Goods and Services upholstery standards are tightening permissible chemical inputs across transatlantic supply chains. Foam compounders serving both US and EU markets are consolidating formulations around lowest-common-denominator chemistries. Small-batch specialty producers without reformulation capacity are exiting cross-border trade.
Direct-to-consumer mattress-in-a-box fulfillment is disintermediating traditional furniture retail and regional bedding distributors. Urban millennial households in Germany and the United States are accepting compressed delivery tradeoffs against showroom trial periods. The channel shift is most visible in secondary metropolitan areas where legacy bedding retail footprints have contracted post-pandemic.
Mattresses and Accessories Market Segmentation
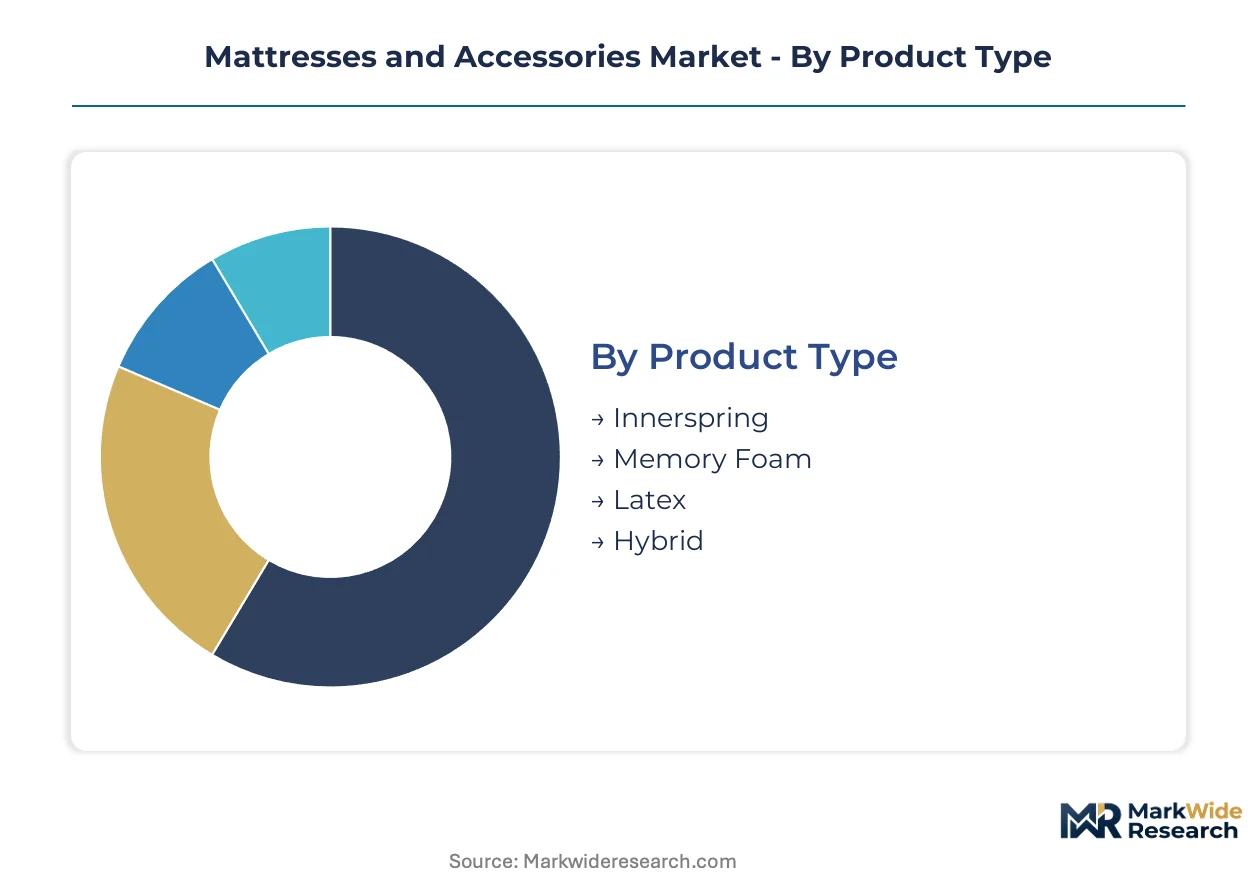
Segmentation in the Mattresses and Accessories Market reveals how certification requirements, thermal performance specifications, and procurement scale reshape competitive positioning across material categories and ancillary products. Understanding these divisions exposes where margin pools concentrate and which specifications filter market access.
Product Type:
CertiPUR-US certification applies selectively across foam-based constructions, with 16 CFR Part 1633 flammability compliance mandatory for all segments sold in the United States regardless of core material.
- Innerspring:Steel coil support systems with fabric-encased or Bonnell coil configurations dominate economy-tier retail below $400 price points. Demand concentrates in mass-market furniture chains and budget hospitality procurement where durability expectations span 5-7 years; coil count and gauge specifications function as primary quality signals despite limited correlation with pressure relief performance.
- Memory Foam:Viscous polyurethane formulations with open-cell structures and gel infusions require CertiPUR-US VOC emissions certification for US market access. Residential demand clusters in premium direct-to-consumer channels where thermal phase-change materials solve heat retention complaints; California Bureau of Household Goods and Services upholstery standards add compliance layers for products sold in that state.
- Latex:Natural rubber derived from Hevea brasiliensis sap or synthetic styrene-butadiene alternatives carries OEKO-TEX Standard 100 certification requirements for EU-bound shipments. Dunlop and Talalay processing methods create density and breathability differentiation.
- Hybrid:Coil support cores layered with foam comfort zones combine CertiPUR-US foam certification with 16 CFR Part 1633 barrier requirements. Hospitality chains in warm-climate destinations specify these constructions for balanced pressure relief and thermal management.
Innerspring sits at the top of the volume ranking, with Hybrid climbing the fastest.
Accessory Type:
Replacement cycles and margin structures diverge sharply across ancillary products, with protective layers and toppers generating recurring revenue streams absent from core mattress purchases.
- Pillows:Molded memory foam, shredded latex, and down-alternative fills carry shorter replacement intervals than mattresses. Hotel chains aggregate pillow procurement through linen service contracts rather than capital expenditure budgets.
- Mattress Protectors:Waterproof polyurethane laminates and breathable cotton-terry surfaces require OEKO-TEX certification for European hospitality procurement. Senior living operators specify egress-friendly low-profile protectors with antimicrobial treatments.
- Bed Frames:Metal platform bases, adjustable foundations, and upholstered headboards anchor sleep system aesthetics. Platform configurations eliminating box springs concentrate in urban millennial households where compressed delivery logistics matter.
- Mattress Toppers:Two-to-four-inch foam or featherbed overlays extend mattress lifecycles in rental property and student housing applications. Gel-infused and copper-doped formulations command premium positioning in warm-climate markets.
Mattress Protectors generate the steadiest replacement demand, with Toppers expanding most quickly in short-term rental furnishing.
Size:
Dimensional specifications align with residential square footage constraints and hospitality room configurations, with procurement scale advantages concentrating in standardized dimensions.
- Queen:Sixty-inch width accommodates dual occupancy in standard residential bedrooms and mid-scale hotel rooms. National hospitality chains specify queen-dominant sleep system contracts for inventory standardization across property portfolios.
- King:Seventy-six-inch width dominates master bedroom renovations and upscale hospitality suites. Split-king configurations with dual adjustable bases concentrate in senior living and wellness-focused residential applications.
- Twin:Thirty-eight-inch width serves children's bedrooms, dormitories, and budget hospitality. Bunk bed and trundle applications in vacation rental properties sustain volume.
- Full:Fifty-four-inch width occupies a narrowing niche between twin and queen, concentrated in adolescent bedroom upgrades and compact urban apartments where queen dimensions exceed available floor space.
Queen dominates absolute volume, with King gaining share fastest in renovation and replacement cycles.
Firmness Level:
Subjective comfort preferences and clinical positioning create divergent specification requirements, with medical and senior living applications driving standardization around measurable support metrics.
- Soft:Plush surface conformance with sinkage depths exceeding three inches targets side sleepers and lightweight users. Limited penetration in institutional procurement where durability concerns dominate.
- Medium:Balanced contouring and support satisfies the broadest residential preference distribution. Hospitality chains standardize on medium specifications to minimize guest complaint variance.
- Firm:Minimal surface give with enhanced edge support addresses back sleepers and heavier body mass indices. Assisted living facilities specify firm surfaces for egress safety and pressure redistribution.
- Extra Firm:Minimal compression resistance serves orthopedic positioning and bariatric applications. Medical equipment channels and workers' compensation replacement programs concentrate demand.
Medium holds the volume leadership position, with Firm advancing fastest in institutional and senior living procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospitality procurement standardization contrasts with China's manufacturing concentration, while the United States drives regulatory chemistry mandates that reshape material specifications across all export markets.
United States
Hotel chains and senior living operators aggregate sleep system purchases through national contracts, creating volume pull for certified hybrid constructions. The Consumer Product Safety Commission enforces 16 CFR Part 1633 open-flame flammability standards that mandate barrier technologies and fire-resistant foam formulations. Manufacturing clusters in North Carolina and Texas concentrate CertiPUR-US certified pour operations serving domestic hospitality and retail channels.
China
Urban millennial households in tier-1 and tier-2 cities accept compressed mattress-in-a-box delivery formats, displacing traditional furniture retail. The Ministry of Ecology and Environment monitors volatile organic compound emissions from polyurethane production under evolving GB standards. Shandong and Zhejiang provinces host bulk polyurethane slabstock production that supplies finished goods exporters facing tariff volatility and ocean freight rate spikes.
Germany
Direct-to-consumer channels disintermediate regional bedding distributors as compressed delivery logistics gain acceptance among urban apartment dwellers. REACH restrictions on isocyanates tighten permissible chemical inputs, forcing consolidation around lowest-common-denominator formulations for transatlantic supply chains. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate foam compounders serving both EU domestic demand and export markets.
Japan
Aging demographics drive demand for pressure-relief surfaces with egress-friendly heights in assisted living and memory care facilities. The Ministry of Economy, Trade and Industry oversees product safety standards through METI notification procedures that align with international flammability benchmarks. Manufacturing concentration in the Chubu region around Nagoya anchors production of high-density foam formulations for premium residential and institutional applications.
India
Organized retail expansion and e-commerce penetration expose price-sensitive consumers to branded mattress options previously concentrated in unorganized trade. The Bureau of Indian Standards maintains ISI certification requirements for furniture and bedding products that increasingly reference international flammability protocols. Industrial corridors in Gujarat and Maharashtra attract foam pour operations seeking to serve domestic hospitality growth and export markets in the Middle East and Africa.
Mattresses and Accessories Market Competitive Landscape
North American producers anchor the premium-tier and institutional procurement segments; Asian fabricators hold cost-advantaged positions in raw material supply and contract manufacturing. The vendor base stratifies across three tiers: multinational branded manufacturers with captive retail distribution, regional specialists serving hospitality and healthcare channels, and private-label compounders supplying compressed-mattress direct-to-consumer brands. Consolidation pressure concentrates among mid-scale foam pourers lacking CertiPUR-US certification capacity. Dominant competitive moves include backward integration into polyurethane chemistry and strategic partnerships with hospitality procurement consortia.
Within the multinational branded tier, Tempur Sealy International and Serta Simmons Bedding exemplify divergent channel strategies—one leveraging vertical manufacturing footprints for volume hospitality contracts, the other anchoring position through broad retail distribution networks. Sleep Number Corporation occupies a distinct position in the adjustable air-chamber segment, representing the convergence of sleep technology with direct-to-consumer wellness positioning. These three entities collectively illustrate how certification compliance, channel configuration, and material science differentiation separate market tiers.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Serta Simmons Bedding |
| Sleep Number Corporation |
| Casper Sleep |
| Leggett & Platt |
| Kingsdown |
| Purple |
| Spring Air International |
| Paramount Bed Holdings |
| Others |
Supply & Pricing Matrix
Polyether polyol feedstock costs trace a direct path from crude oil benchmarks through Shandong province slabstock producers to finished mattress price floors in North American retail channels. Tariff volatility on Chinese foam imports compresses margins for uncertified suppliers while rewarding domestic CertiPUR-US certified compounders with pricing power in hospitality procurement.
Pricing Analysis
Capacity additions in North Carolina and Texas are reshaping price floors for CertiPUR-US certified foam as domestic pour operations capture share from tariff-exposed imports. Three-tier pricing structure across premium gel-infused memory foam, standard hybrid constructions, and economy innerspring tiers segments buyer pools by thermal performance requirements and certification compliance. Price differentiation hinges on VOC emissions certification grade and volume scale in national hospitality contracts. Pricing pressure stems from polyol cost volatility that uncertified manufacturers cannot pass through to mass-market furniture chains. Budget hospitality procurement below $400 retail price points exhibits highest price sensitivity, while senior living operators prioritize pressure-relief specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Shandong and Zhejiang province polyurethane slabstock production that feeds finished goods exporters to North American and European markets. Raw material flows draw from crude oil derivatives, TDI/MDI isocyanates, and flame-retardant additive chemistries. Supply chain risk centers on tariff exposure and ocean freight rate spikes disrupting just-in-time inventory models for mattress-in-a-box fulfillment. Distribution runs through national hospitality procurement consortia, direct-to-consumer compressed delivery logistics, and legacy furniture retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Chinese manufacturing concentration and US regulatory compliance costs, with CertiPUR-US certification requirements creating a $40-80 per unit cost wedge that domestic compounders exploit.
For Market Incumbents: Deepen backward integration into polyurethane chemistry to secure captive polyol supply against feedstock volatility threatening margin structures. Anchor position through exclusive national hospitality contracts that lock in volume throughput and deter private-label entrants. CertiPUR-US certification capacity investments function as the primary defensive moat against tariff-advantaged imports. For New Entrants and Emerging Players: California SB 1015 extended producer responsibility opens a window for compliance-service revenue streams through mattress take-back infrastructure ahead of enforcement timelines. Target senior living sleep systems as the most penetrable institutional channel outside consolidated retail distribution. Pursue direct-to-consumer air-chamber smart integration with biometric sleep tracking as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale foam pourers lacking CertiPUR-US certification capacity because consolidation pressure concentrates among uncertified suppliers facing market access filters. Long-term viability favors vertically integrated compounders with captive chemistry and hospitality contract portfolios. Watch CertiPUR-US testing backlog resolution as the inflection indicator for product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| CertiPUR-US Certification Investment | 16 CFR Part 1633 compliance mandates barrier technologies that filter non-compliant imports from US market access. |
| Hospitality Procurement Partnership | National hotel chain contracts standardize hybrid specifications and create volume pull for certified manufacturers. |
| Backward Integration into Polyol Chemistry | Captive feedstock supply insulates margin structures from crude oil-linked volatility in polyurethane production. |
| Direct-to-Consumer Channel Expansion | Compressed mattress-in-a-box logistics disintermediate legacy furniture retail in urban millennial households. |
| Senior Living Sleep System Development | Assisted living facilities specify pressure-relief surfaces with egress-friendly heights outside conventional retail channels. |
Research Methodology
Multiple input streams — executive interviews with foam compounders and hospitality procurement directors, regulatory filing analysis, and trade flow databases — were reconciled to construct segment-level demand estimates. Primary fieldwork captured perspectives from CertiPUR-US certified pour operators, senior living facility specifiers, and compressed-mattress fulfillment logistics providers. Secondary validation drew from EPA emissions disclosures, CPSC flammability standard updates, and customs records of polyurethane slabstock trade. Bottom-up unit economics and top-down category spend estimates were triangulated to anchor volume projections.
Historical shipment patterns were cross-referenced against panel input from procurement consortia and retail channel partners to calibrate growth assumptions across the analysis window. Segmentation dimensions modeled include product architecture, certification tier, firmness specification, and end-use channel. CAGRs were derived from elasticity-adjusted demand curves incorporating replacement cycle dynamics and hospitality construction pipelines. Forecast inputs included polyol price trajectory scenarios and tariff regime sensitivity testing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended trade friction or accelerated state-level extended producer responsibility adoption. Projections reflect assumptions about certification testing capacity expansion and hospitality procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Digital Printed Wallpaper Market