
 Smart and Connected Offices Market | 2026-2036
Smart and Connected Offices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart and Connected Offices Market Analytics
Corporate office portfolios is pivoting toward hybrid-work-optimized infrastructure, diverting capital from pure density plays to experience-driven space design. Honeywell International Inc. leverages its building automation heritage to dominate North American retrofits. Siemens AG anchors European demand through its Desigo platform integration. Cisco Systems Inc. competes on network-edge convergence, merging IT infrastructure with operational technology stacks.
Smart and connected offices integrate sensor networks, actuators, and software platforms to monitor occupancy, air quality, energy consumption, and security status in real time, typically operating through IP-based building management systems with sub-second response latency for climate and lighting adjustments. The primary purpose is to reduce operational expenditure while enabling flexible, health-certified workspace configurations. Smart Lighting and HVAC Systems carry the largest installed base and replacement revenue pools, though Security Solutions is deepening its margin profile through AI-enabled video analytics subscriptions. IoT Platforms leads technology adoption by volume, while Edge Computing is capturing the fastest expansion as latency-sensitive applications multiply.
The EU AI Act, GDPR, and the F-Gas Regulation collectively constrain how facial recognition, predictive occupancy algorithms, and refrigerant-based climate systems deploy across European facilities. The FCC and OSHA shape US requirements for wireless spectrum allocation and indoor air quality monitoring in commercial buildings. Stakeholders must weigh interoperability certifications against regional compliance burdens when selecting platform architectures for multi-national footprints.
Market Dynamics
Hybrid work stabilization is forcing corporate real estate teams to reconfigure space utilization models, shifting capital from fixed seating density to dynamic occupancy-responsive infrastructure that adapts to fluctuating in-office headcounts.
Growth Catalysts
- EU AI Act compliance mandates:European facility managers must deploy privacy-preserving occupancy analytics, accelerating procurement of edge-processed sensor networks that anonymize data before cloud transmission.
- Workplace wellness certification:WELL Building Standard and Fitwel criteria are embedding air quality and circadian lighting requirements into lease agreements, pulling smart HVAC and tunable LED upgrades into base building specifications.
- India's commercial real estate expansion:Bangalore and Hyderabad office stock is adding Class A supply with native IoT infrastructure, bypassing retrofit constraints that slow adoption in mature markets.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication concentrates in Taiwan and South Korea, exposing building automation OEMs to allocation volatility for vision processing modules.
- GDPR enforcement friction:Cross-border data residency requirements complicate multi-tenant building platforms where sensor feeds must remain within national jurisdictions.
- Copper and rare earth input costs:Motor windings and permanent magnets for smart HVAC actuators face price volatility from concentrated Chilean and Chinese mining operations.
Strategic Opportunities
- Sub-Saharan Africa greenfield development:Kenya and Nigeria commercial hubs are leapfrogging legacy Building Management Systems, accepting full-stack IoT platforms as standard in new construction.
- F-Gas Regulation retrofit wave:European refrigerant phase-down mandates are compressing replacement cycles for climate systems, opening bundled upgrade paths that integrate predictive maintenance subscriptions.
- Digital twin convergence:Facility operators are merging BIM models with real-time sensor streams, creating new revenue pools for vendors offering simulation-based space optimization services.
Industry Challenges
- Cyber-physical security skill scarcity:Building IT teams lack OT network segmentation expertise, delaying deployment of converged IP-based management systems.
- Interoperability certification bottlenecks:BACnet/KNX/LON protocol validation timelines stretch 8-14 months, compressing product launch windows for multi-protocol gateways.
- Legacy pneumatic control inertia:1970s-era air handling infrastructure in US Northeast and Midwest Class B stock resists sensor retrofit without full mechanical replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart and Connected Offices Market |
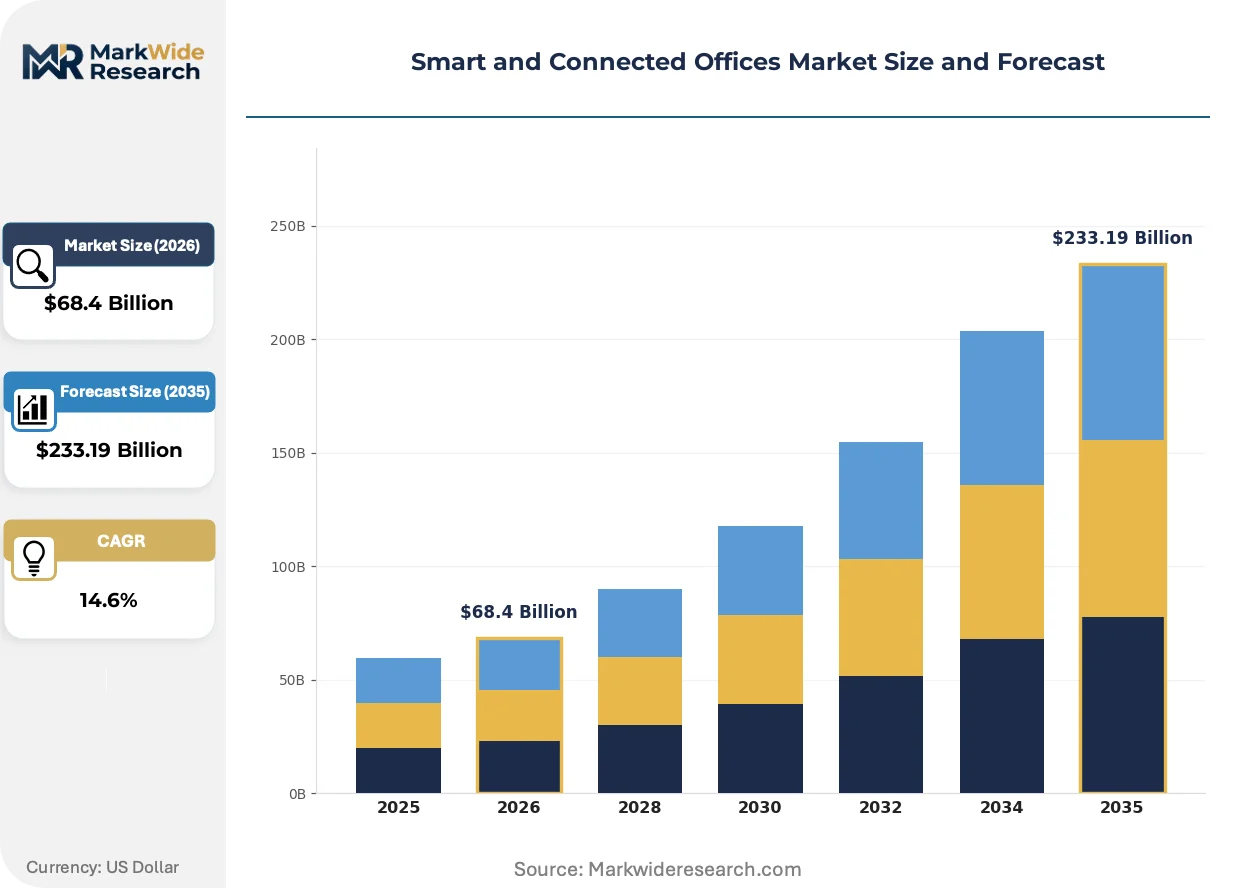
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $233.19 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, HVAC Systems, Security Solutions, Connected Furniture Technology: IoT Platforms, AI Analytics, Cloud Computing, Edge Computing End User: Corporate Offices, Co-Working Spaces, Educational Institutions, Government Buildings Deployment: On-Premise, Hybrid, Cloud-Based, Fully Managed |
| Companies Covered | Honeywell International Inc., ABB Ltd., Johnson Controls International PLC, Philips Lighting, Crestron Electronics Inc., Siemens AG, Schneider Electric SE, Google, Cisco Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart and Connected Offices Market Evolving Landscape
Building automation is pivoting from reactive climate control toward predictive environmental orchestration, with sensor fusion and machine inference collapsing response latencies from minutes to milliseconds.
Power over Ethernet lighting is electrifying ceiling grid infrastructure, consolidating data and electrical distribution into single-cable topologies. Large corporate tenants in Texas and Arizona are specifying PoE-native luminaires for new buildouts, eliminating separate 120V circuits and enabling granular zone control without proprietary DALI wiring. This convergence is compressing electrical contractor scope and accelerating post-occupancy reconfiguration cycles.
The EU AI Act's risk-based classification system is reshaping video analytics deployment across German and French commercial portfolios. Biometric identification functions now trigger conformity assessment obligations, pushing facility managers toward edge-processed occupancy counting that strips identifying features before data leaves the camera. Nordic markets are responding fastest, with Stockholm and Copenhagen landlords advertising GDPR-certified building systems as tenant acquisition tools.
Space-as-a-service procurement is fragmenting traditional landlord-tenant equipment ownership boundaries. WeWork competitors and flexible workplace operators in London and Singapore are demanding embedded smart infrastructure with usage-based service fees rather than capital expenditure transfers. This shift concentrates vendor selection power with platform operators who aggregate demand across multiple landlord relationships, compressing pricing leverage for single-building owners.
Smart and Connected Offices Market Segmentation
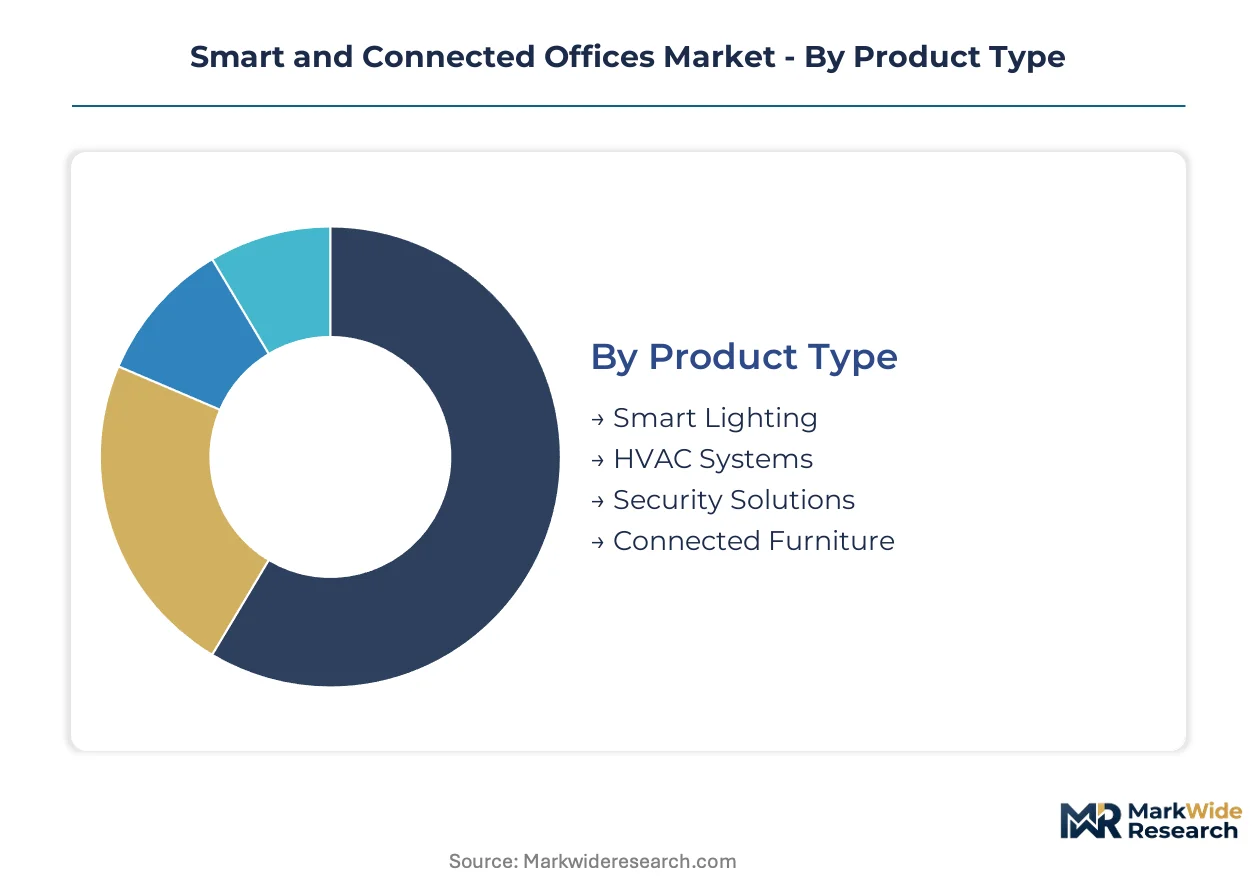
Smart office procurement varies sharply by segment, with certification requirements from FCC, GDPR, and EU AI Act filtering which technologies reach which building types. Vendors must align product architectures to distinct compliance burdens across lighting, climate, security, and furniture categories.
Product Type:
Smart Lighting and HVAC Systems carry CE marking and FCC Part 15 emissions approvals, while Security Solutions trigger EU AI Act conformity assessments for biometric functions. Connected Furniture faces lighter regulatory loads, concentrating compliance investment in the climate and surveillance segments.
- Smart Lighting:Power over Ethernet luminaires consolidate data and electrical distribution into single-cable ceiling grids. Texas and Arizona corporate tenants specify PoE-native systems for new buildouts, eliminating separate circuits and enabling granular zone control without proprietary DALI wiring.
- HVAC Systems:Sensor networks and actuators monitor occupancy, CO2, and temperature with sub-second response latency. European F-Gas Regulation mandates are compressing replacement cycles, opening bundled upgrade paths that integrate predictive maintenance subscriptions.
- Security Solutions:AI-enabled video analytics subscriptions deepen margin profiles through recurring revenue models. Edge-processed occupancy counting strips identifying features before cloud transmission to satisfy GDPR and EU AI Act requirements.
- Connected Furniture:Sensor-embedded workstations and meeting tables track utilization patterns. Demand concentrates in flexible workplace operators who aggregate demand across multiple landlord relationships.
Smart Lighting sits at the top of the volume ranking, with Security Solutions climbing the fastest.
Technology:
Technology selection splits between latency-tolerant cloud architectures and millisecond-response edge systems, with cost tiers determining which buildings deploy which stack.
- IoT Platforms:IP-based building management systems aggregate sensor feeds from lighting, climate, and security subsystems. Volume leadership stems from retrofit compatibility with 1990s-era BACnet infrastructure in US Northeast Class B stock.
- AI Analytics:Machine inference on occupancy patterns and energy consumption enables predictive environmental orchestration. GDPR data residency requirements complicate multi-tenant deployments where sensor feeds must remain within national jurisdictions.
- Cloud Computing:Centralized data lakes support long-term trend analysis and portfolio-level benchmarking. Latency constraints limit application to non-time-critical reporting functions.
- Edge Computing:Local processing eliminates round-trip delays for climate and lighting adjustments. Vision processing modules for biometric functions trigger EU AI Act risk classification and conformity obligations.
IoT Platforms commands the largest installed base, while Edge Computing expands most quickly as latency-sensitive applications multiply.
End User:
Customer type dictates procurement authority, with corporate real estate teams, flexible operators, and public institutions each running distinct vendor selection processes.
- Corporate Offices:Hybrid work stabilization forces real estate teams to reconfigure space utilization models, shifting capital from fixed seating density to dynamic occupancy-responsive infrastructure. WELL Building Standard and Fitwel criteria embed air quality requirements into lease agreements.
- Co-Working Spaces:Space-as-a-service procurement fragments traditional landlord-tenant equipment ownership boundaries. WeWork competitors demand embedded smart infrastructure with usage-based service fees rather than capital expenditure transfers.
- Educational Institutions:Campus-wide deployments prioritize interoperability certifications across multi-building footprints. Budget cycles stretch 18-24 months, compressing vendor cash conversion timelines.
- Government Buildings:Cyber-physical security mandates drive OT network segmentation requirements. Building IT teams lack expertise, delaying deployment of converged IP-based management systems.
Corporate Offices anchor procurement volume, with Co-Working Spaces gaining share fastest as flexible workplace models proliferate.
Deployment:
Deployment mode determines which party carries operational risk, with fully managed services transferring accountability to vendors.
- On-Premise:Local servers and dedicated networks satisfy data residency requirements for financial services and defense contractors. Capital intensity limits adoption to large portfolios with dedicated facilities teams.
- Hybrid:Edge processing for latency-critical functions pairs with cloud analytics for trend reporting. This architecture satisfies GDPR anonymization mandates while preserving responsiveness.
- Cloud-Based:Subscription pricing lowers entry barriers for mid-market tenants. Network dependency creates vulnerability to ISP outages.
- Fully Managed:Vendors assume uptime responsibility and performance guarantees. Service level agreements specify response times for climate and lighting faults.
Hybrid deployment leads on new project specifications, with Fully Managed climbing fastest as landlords seek to offload operational complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting smart office platform development toward jurisdictions with clearer AI governance frameworks, as vendors seek predictable compliance costs. The EU AI Act's risk-based classification system has concentrated European R&D investment in Germany and France, while US developers exploit OSHA's performance-based indoor air standards to accelerate deployment timelines. Facility operators in Singapore and the UAE are importing European privacy architectures to preempt GDPR-equivalent legislation.
United States
Corporate retrofit cycles in Texas and Arizona are specifying Power over Ethernet lighting for new buildouts, eliminating separate electrical circuits. OSHA's performance-based indoor air quality monitoring standards allow faster deployment than prescriptive European equivalents. Dallas-Fort Worth and Phoenix office clusters are consolidating procurement around hybrid cloud-edge architectures that satisfy financial services data residency requirements.
Germany
The EU AI Act's conformity assessment obligations for biometric functions are forcing facility managers toward edge-processed occupancy counting. F-Gas Regulation refrigerant phase-down mandates are compressing HVAC replacement cycles in Frankfurt and Munich commercial portfolios. Berlin landlords are advertising GDPR-certified building systems as tenant acquisition tools against London competitors.
Japan
METI's energy efficiency standards for commercial buildings are accelerating sensor network deployment in Tokyo and Osaka office towers. JIS interoperability certifications are filtering out non-compliant foreign platform vendors. Nagoya's automotive supplier headquarters are specifying predictive maintenance subscriptions for climate systems to align with just-in-time production cultures.
Singapore
The Building and Construction Authority's Green Mark certification is embedding IoT infrastructure requirements into new Class A supply. Data residency rules for financial services tenants are favoring hybrid deployment architectures with local edge processing. Marina Bay and Raffles Place developments are leapfrogging legacy Building Management Systems with full-stack native installations.
India
Bangalore and Hyderabad office stock additions are bypassing retrofit constraints that slow adoption in mature markets. The Bureau of Indian Standards is developing IoT interoperability frameworks that reduce vendor lock-in risks for corporate tenants. Mumbai's financial district landlords are importing European privacy-preserving sensor designs to attract multinational lease commitments.
Smart and Connected Offices Market Competitive Landscape
Strategic partnerships dominate the current landscape as building automation heritage players seek network-edge capabilities from IT infrastructure specialists. The vendor base clusters around three archetypes: industrial conglomerates with mechanical systems lineage, enterprise networking firms with OT convergence expertise, and pure-play IoT platform operators. Tiered competitive positioning separates full-stack solution providers from component specialists. M&A activity and technology licensing agreements are the primary vectors for capability expansion.
Within the industrial heritage tier, Honeywell International Inc., Siemens AG, and Johnson Controls International PLC exemplify the building automation-to-IT convergence strategy. These entities anchor North American and European retrofit demand through established mechanical systems relationships. Cisco Systems Inc. occupies the network infrastructure specialist position, competing on IT/OT stack integration rather than climate hardware. Google represents the cloud-native entrant archetype, leveraging data analytics capabilities against incumbent platform limitations.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd. |
| Johnson Controls International PLC |
| Philips Lighting |
| Crestron Electronics Inc. |
| Siemens AG |
| Schneider Electric SE |
| Cisco Systems Inc. |
| Others |
Value Network & Pricing Analysis
Edge AI engineering talent concentration in Taiwan and South Korea generates labor-cost differentials that widen pricing-tier spreads between premium vision-processing modules and standard sensor arrays.
Pricing Analysis
Distributor margin layers compress as building automation OEMs consolidate direct procurement relationships with semiconductor foundries. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified edge systems from uncertified alternatives and basic cloud-connected sensors. Pricing pressure stems from copper and rare earth input volatility in Chilean and Chinese mining operations. Flexible workplace operators exhibit highest price sensitivity due to usage-based service fee models, while financial services tenants prioritize data residency compliance over cost.
Supply Chain Analysis
Dual-sourcing requirements from European facility managers mandate multi-supplier qualification for edge AI chip vendors, fragmenting procurement across Taiwan, South Korea, and emerging US fabrication capacity. Motor windings draw from Chilean copper and Chinese rare earth permanent magnets. Single-source vulnerability concentrates in Taiwan-based vision processing module fabrication. Distribution runs through building automation OEMs with established mechanical systems relationships rather than IT channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart and Connected Offices Market functions as a stable compounder, with hybrid work stabilization driving steady infrastructure replacement cycles across corporate real estate portfolios.
For Market Incumbents: Anchor retrofit demand in North American and European Class B stock through BACnet-compatible gateway investments that bridge 1990s-era pneumatic infrastructure to IP-based sensor networks. Defend against cloud-native entrants by deepening predictive maintenance subscription attach rates. Prioritize F-Gas Regulation compliance bundling in European climate system replacements.
For New Entrants and Emerging Players: Capture greenfield specification authority in Bangalore and Hyderabad Class A developments where native IoT infrastructure bypasses retrofit constraints. Target sub-Saharan Africa commercial hubs in Kenya and Nigeria that leapfrog legacy Building Management Systems. Lead with full-stack platform offerings priced on usage-based service fees rather than capital expenditure transfers.
For Investors and Strategic Acquirers: Enterprise networking specialists with OT convergence expertise are the most active acquirer in this space, seeking building automation heritage capabilities. Five-to-ten year viability rests on edge computing IP and GDPR-certified sensor architectures. Monitor EU AI Act enforcement patterns as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Merges IT infrastructure with operational technology stacks for converged building management. |
| Acquisition of Specialist Firm | Adds edge AI vision processing capabilities to complement mechanical systems heritage. |
| Strategic Partnership | Links building automation OEMs with semiconductor foundries for allocation security. |
| Geographic Expansion | Targets India greenfield developments and sub-Saharan Africa leapfrog markets. |
| Product Launch | Introduces GDPR-certified sensor networks that anonymize data before cloud transmission. |
Research Methodology
Multiple input streams — facility manager interviews, building automation OEM technical consultations, and flexible workplace operator procurement reviews — were reconciled against regulatory filing analysis and commercial real estate transaction databases. Primary engagement spanned corporate real estate directors, OT network engineers, and smart infrastructure procurement leads. Secondary validation drew from FCC equipment authorization records, EU AI Act conformity assessment documentation, and SEC filings from publicly traded building technology vendors. Bottom-up sensor deployment estimates and top-down construction spending data were triangulated.
Data-stream reconciliation anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, technology stack, end-user category, and deployment architecture. CAGRs were derived from installed base replacement cycles and greenfield penetration curves. Forecast inputs incorporated hybrid work stabilization timelines and refrigerant phase-down mandates under the F-Gas Regulation.
Semiconductor allocation volatility, GDPR enforcement friction, and copper price instability are the dominant revision risks. Deviation in edge AI chip fabrication capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Voice Remote Control Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Document Management System Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Digital Pen Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
Construction Design App Market