
 Key Management As a Service (Kmaas) Market | 2026-2036
Key Management As a Service (Kmaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Key Management As a Service (Kmaas) Market Analysis
The EU AI Act is restructuring how European enterprises evaluate cloud encryption providers, mandating audit trails for cryptographic key provenance in high-risk AI systems. Microsoft Corporation leverages its Azure Dedicated HSM portfolio to anchor compliance-heavy workloads across German automotive and French healthcare verticals. Thales Group competes through hardware-backed key escrow architectures that sustain sovereign data residency requirements in regulated EU jurisdictions. Amazon Web Services differentiates via multi-cloud key federation APIs that extend customer control across hybrid environments without vendor lock-in.
Key Management as a Service delivers cloud-hosted cryptographic key lifecycle operations encompassing generation, storage, rotation, and destruction of symmetric and asymmetric keys through FIPS 140-2 Level 3 validated hardware security modules accessible via REST APIs. The primary industrial purpose centers on enabling organizations to encrypt data-at-rest and data-in-transit without maintaining on-premises HSM infrastructure or specialized cryptography personnel. Public cloud deployment leads in absolute volume due to hyperscaler integration economies, while hybrid cloud configurations capture the fastest expansion as regulated enterprises demand split-key architectures keeping root key material on-premises while offloading operational key management to cloud providers. Managed services dominate margin pools because recurring operational responsibilities for key rotation, policy enforcement, and compliance reporting command premium pricing over one-time professional services engagements.
The European Banking Authority, EMA, and GDPR supervisory authorities collectively shape Kmaas demand through mandatory encryption standards for personal data, clinical trial records, and payment transaction logs. France's CNIL and Germany's BSI enforce technical specifications that effectively restrict non-EU key custody arrangements for sensitive national data categories. Stakeholders must monitor evolving EU Cybersecurity Certification schemes for cloud services and assess whether their key management architectures satisfy emerging qualified trust service provider requirements before procurement cycles finalize.
Market Dynamics
The EU AI Act's audit-trail mandates for cryptographic key provenance in high-risk AI systems are forcing European enterprises to re-architect cloud encryption procurement around sovereign key custody and hardware-backed escrow architectures.
Growth Catalysts
- GDPR Cross-Border Data Rules:Germany's BSI and France's CNIL enforce technical specifications that restrict non-EU key custody, compelling enterprises to adopt Kmaas with local HSM infrastructure.
- Automotive OEM Requirements:Connected vehicle platforms in Germany mandate sovereign key control for over-the-air software updates and telematics encryption, driving vaultless tokenization adoption.
- Smart Factory Data Pipelines:Industrial conglomerates across Europe deploy split-key architectures to encrypt operational technology data streams while maintaining root key material on-premises.
Market Restraints
- Hardware Security Module Concentration:FIPS 140-2 Level 3 validated HSM supply concentrates among limited semiconductor foundries, creating procurement bottlenecks for cloud providers scaling European capacity.
- Qualified Trust Service Provider Certification:EU Cybersecurity Certification schemes impose 18-24 month compliance timelines that delay Kmaas vendor market entry in regulated jurisdictions.
- Legacy On-Premises Infrastructure:Enterprises with sunk investments in physical HSM estates face migration friction and hybrid integration costs that slow cloud-native key management adoption.
Strategic Opportunities
- Hybrid Cloud Configurations:Split-key architectures capturing fastest expansion as regulated enterprises demand operational key management offloading while retaining root key material on-premises.
- French Healthcare Vertical:CNIL enforcement of clinical trial record encryption creates procurement pull for Kmaas with hardware-backed key escrow and sovereign data residency guarantees.
- Multi-Cloud Key Federation:APIs extending customer control across heterogeneous environments without vendor lock-in address enterprise demand for cryptographic agility across AWS, Azure, and private infrastructure.
Industry Challenges
- Cryptographic Personnel Scarcity:Enterprises lack specialized talent for key lifecycle governance, forcing reliance on managed service providers for rotation scheduling and policy enforcement.
- Compliance Reporting Automation:EMA and European Banking Authority audit requirements demand continuous cryptographic provenance documentation that strains operational workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Key Management As a Service (Kmaas) Market |
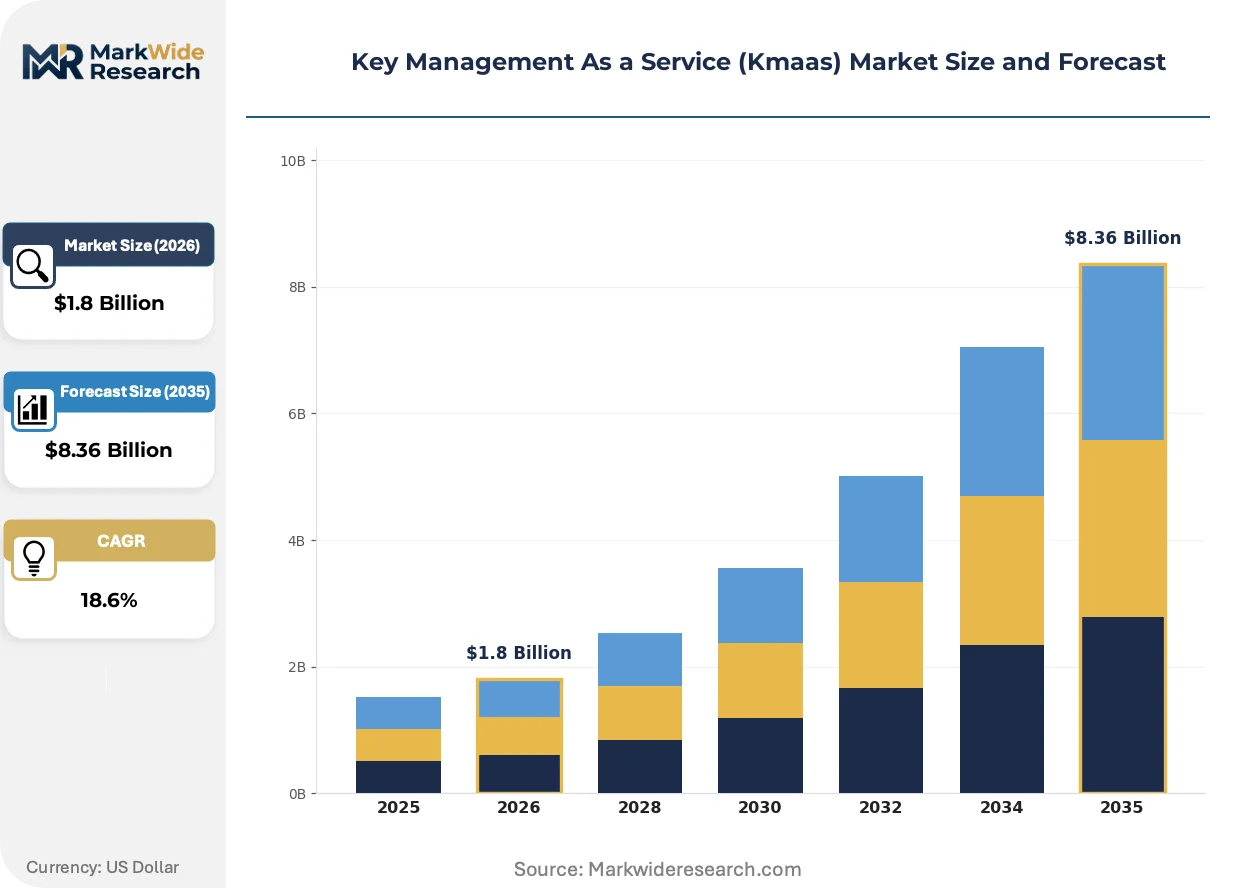
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Managed Services, Professional Services, Consulting, Support Services Client Type: Enterprise, Small Business, Government, Non-Profit Use Case: Data Encryption, Access Management, Compliance, Secure Communication |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google, IBM Corporation, Oracle Corporation, Thales Group, Hewlett Packard Enterprise Development, Egnyte, Fortanix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Key Management As a Service (Kmaas) Market Emerging Trajectories
Vaultless tokenization architectures are displacing traditional vault-based encryption in high-throughput environments, while regulatory pressure on AI system transparency accelerates investment in auditable key provenance infrastructure.
Confidential computing with hardware-based trusted execution environments is rewriting how automotive OEMs protect AI model weights and inference data in connected vehicle platforms. BMW and Volkswagen procurement teams now mandate memory encryption and attested key release mechanisms for supplier cloud workloads. This technology is rewriting competitive requirements for Kmaas providers serving German industrial verticals.
France's CNIL has issued binding technical specifications for health data encryption that effectively disqualify key custody arrangements outside EU jurisdiction. Hospital groups and clinical research organizations must demonstrate cryptographic key material never transits non-European infrastructure. Pharmaceutical sponsors running multi-site trials now specify Kmaas with dedicated French HSM estates to satisfy these constraints.
Subscription-based managed key services are displacing perpetual-license professional services engagements as the dominant commercial model. Recurring operational responsibilities for rotation, policy enforcement, and compliance reporting command premium pricing over one-time implementation projects. German automotive suppliers and French healthcare networks lead this shift, unbundling cryptographic operations from capital-intensive infrastructure ownership.
Key Management As a Service (Kmaas) Market Segmentation
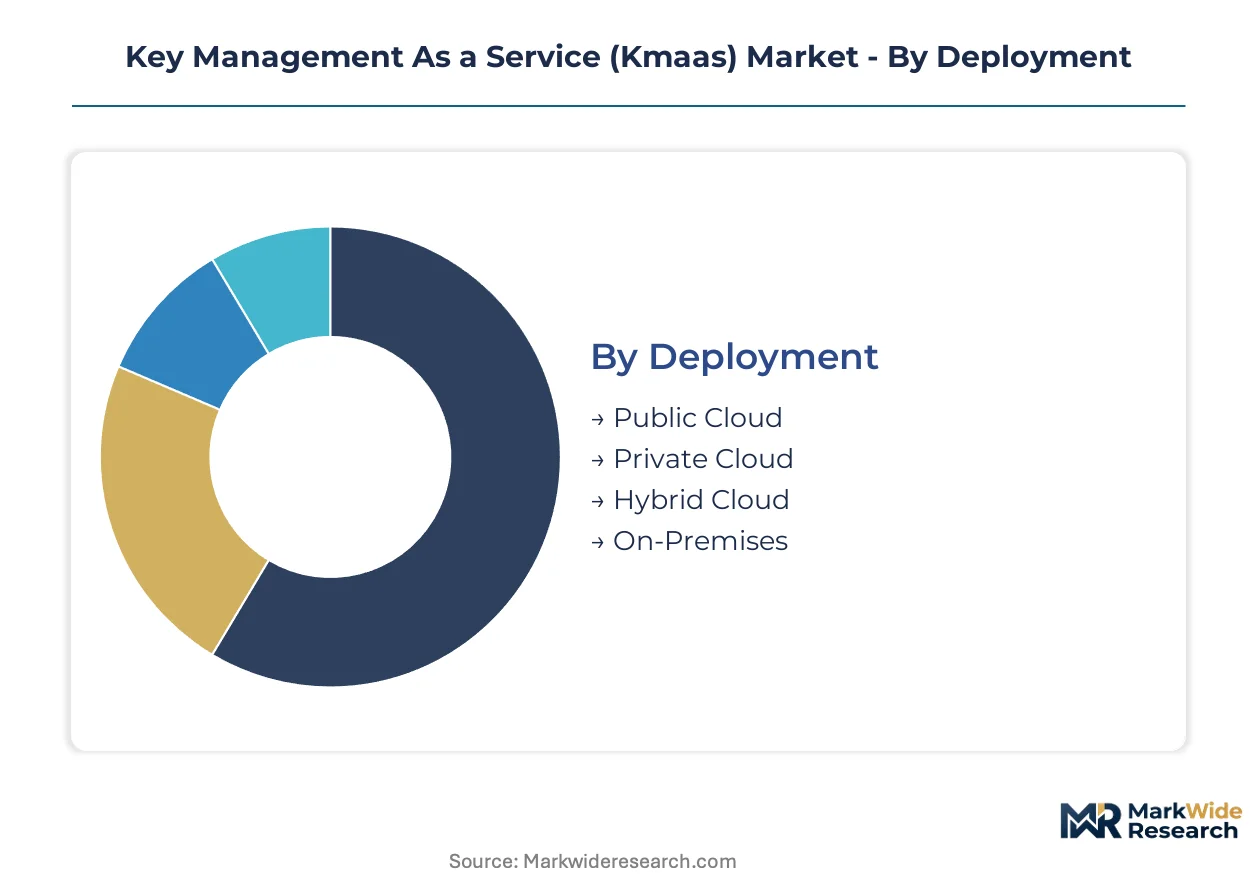
Segmentation in Kmaas procurement follows capital deployment patterns, with regulated enterprises prioritizing sovereignty-preserving architectures over cost-optimized configurations. Deployment mode and service packaging determine compliance eligibility and operational liability exposure.
Deployment:
Capital intensity varies sharply across deployment modes, with sovereign infrastructure requirements driving premium provisioning costs.
- Hybrid Cloud:Split-key architectures separate root key material on-premises from operational key management in cloud infrastructure. German automotive OEMs and French hospital networks mandate this configuration to satisfy BSI and CNIL data residency rules while offloading operational overhead.
- Public Cloud:Hyperscaler-integrated key lifecycle services deliver FIPS 140-2 Level 3 validated HSM access via REST APIs without customer-managed infrastructure. Absolute volume concentrates here due to integration economies and fastest provisioning timelines.
- Private Cloud:Dedicated single-tenant HSM estates within customer-controlled cloud environments. Deployed by defense contractors and critical infrastructure operators requiring complete cryptographic boundary control.
- On-Premises:Customer-owned HSM hardware with vendor-managed software layers. Legacy estates in European banking persist due to sunk infrastructure investments and migration friction.
Most installed capacity flows through Public Cloud. Expansion is steepest in Hybrid Cloud.
Service Type:
Margin pools concentrate where recurring operational responsibilities displace one-time implementation engagements.
- Managed Services:Continuous key rotation scheduling, policy enforcement, and compliance reporting delivered under subscription contracts. German automotive suppliers and French healthcare networks lead the shift from perpetual licenses to recurring operational models.
- Professional Services:One-time implementation projects encompassing architecture design, HSM provisioning, and initial policy configuration. Procurement cycles lengthen as enterprises bundle these into broader cloud transformation programs.
- Consulting:Cryptographic posture assessments and regulatory readiness evaluations. Demand spikes preceding EU Cybersecurity Certification audits and EMA clinical trial system inspections.
- Support Services:Technical assistance and incident response for key lifecycle exceptions. Required for all FIPS 140-2 Level 3 deployments to maintain validation status.
Revenue concentration sits with Managed Services. Consulting is climbing the fastest as regulatory complexity deepens.
Client Type:
Procurement authority and compliance burden vary by organizational scale and regulatory classification.
- Enterprise:Multi-national corporations with dedicated cryptography teams and complex multi-cloud estates. Demand multi-cloud key federation APIs and hardware-backed escrow architectures.
- Government:National agencies and military organizations mandating sovereign key custody with domestic HSM infrastructure. Subject to longest procurement cycles and strictest certification requirements.
- Small Business:Mid-market firms adopting Kmaas through managed service provider bundles. Price-sensitive segment prioritizing operational simplicity over architectural customization.
- Non-Profit:Research institutions and NGOs handling donor or beneficiary personal data. GDPR compliance requirements drive adoption despite constrained IT budgets.
Contract value peaks with Enterprise accounts. Government is gaining share fastest as sovereign cloud programs expand.
Use Case:
Functional requirements determine key lifecycle complexity and integration architecture.
- Data Encryption:Encryption-at-rest and encryption-in-transit for databases, object storage, and application workloads. Vaultless tokenization is displacing vault-based encryption in high-throughput automotive telematics pipelines.
- Compliance:Audit trail generation and cryptographic provenance documentation for regulatory examinations. EU AI Act mandates now require key provenance tracking for high-risk AI systems.
- Access Management:Key-based authentication and privileged access credential protection. Integrated with identity platforms for zero-trust architectures.
- Secure Communication:End-to-end encryption for messaging, voice, and video conferencing. Deployed by clinical research organizations for multi-site trial coordination.
Deployment breadth is widest in Data Encryption. Compliance is expanding most quickly as audit mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud cryptography specialists cluster in Germany, France, and the United States, with emerging talent pools forming in India and the United Kingdom. Sovereign data residency mandates are redrawing where key management infrastructure must physically reside.
Germany
Automotive OEMs and industrial conglomerates mandate sovereign key control for connected vehicle platforms and smart factory data pipelines. Germany's BSI enforces technical specifications that restrict non-EU key custody arrangements for sensitive national data categories. Munich and Stuttgart anchor procurement demand from BMW and Volkswagen supplier networks.
France
Hospital groups and clinical research organizations drive adoption for health data encryption and multi-site trial coordination. CNIL binding specifications disqualify key custody outside EU jurisdiction for clinical trial records. Paris-based pharmaceutical sponsors now specify dedicated French HSM estates for cryptographic compliance.
United States
Financial services firms expand vaultless tokenization for payment transaction logs and cross-border data flows. HIPAA and state-level privacy laws shape procurement criteria for healthcare cloud encryption. New York and San Francisco financial technology clusters lead managed services contracting.
United Kingdom
Enterprise demand concentrates on multi-cloud key federation for heterogeneous infrastructure estates. Post-Brexit data adequacy negotiations influence cross-border key custody architecture decisions. London financial services and Cambridge technology corridors sustain consulting and professional services demand.
India
IT services exporters and domestic fintech platforms adopt Kmaas through managed service provider bundles. RBI guidelines on data localization influence cloud encryption procurement for payment systems. Bangalore and Hyderabad technology hubs drive small business segment expansion.
Key Management As a Service (Kmaas) Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the Kmaas market structure. Hyperscale cloud providers with dedicated HSM infrastructure anchor the premium tier, while specialized cryptography vendors occupy sovereign compliance niches. The vendor base stratifies across three archetypes: integrated cloud platforms, hardware security module specialists, and managed security service providers. Dominant competitive moves include strategic partnerships for hybrid cloud certification and portfolio diversification into confidential computing.
Among integrated cloud platforms, Amazon Web Services, Microsoft Corporation, and Thales Group exemplify contrasting approaches to sovereign key custody. AWS anchors multi-cloud federation capabilities, Microsoft occupies compliance-heavy European verticals through dedicated HSM portfolios, and Thales represents hardware-backed escrow architectures sustaining data residency requirements. These three occupy positions across the spectrum from pure software abstraction to physical infrastructure control.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Thales Group |
| Hewlett Packard Enterprise Development |
| Egnyte |
| Fortanix |
| Others |
Supply Flow & Price Mechanics
German automotive OEM procurement teams anchor demand for sovereign key custody configurations, locking in subscription-based managed services as the dominant commercial model across European Kmaas procurement. Their mandate for split-key architectures with on-premises root key material sustains premium pricing tiers despite operational cost compression in standard cloud-native deployments.
Pricing Analysis
Subscription-based recurring contracts dominate Kmaas commercial structures, with three-tier pricing separating FIPS 140-2 Level 3 validated deployments from standard cloud HSM tiers and economy-grade shared infrastructure offerings. Price differentiation rests on certification grade and geographic HSM residency, with EU-sovereign instances commanding substantial premiums over standard hyperscaler configurations. Cost compression in economy tiers is intensifying because managed service providers compete aggressively for mid-market bundles. Small business segments exhibit highest price sensitivity, while government and automotive OEM buyers prioritize compliance eligibility over unit economics.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for sovereign HSM infrastructure, while managed security service providers distribute operational key management to mid-market segments. Hardware security module manufacturing concentrates in the United States, Germany, and Taiwan, with FIPS 140-2 Level 3 validated semiconductor foundries feeding cloud provider capacity expansion. Supply chains draw from specialized cryptographic processors, tamper-resistant enclosures, and certified firmware stacks. Single-source vulnerability around qualified trust service provider certification creates procurement bottlenecks, as EU Cybersecurity Certification schemes impose extended validation timelines that constrain vendor market entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kmaas margin expansion rests on operational leverage in managed services and premium-tier shift toward confidential computing integrations. Sovereign key custody requirements across German automotive and French healthcare verticals sustain pricing power despite input cost pressures.
For Market Incumbents: To counter emerging confidential computing specialists, hyperscale cloud providers should deepen hardware-backed key escrow capabilities through dedicated HSM portfolio expansion and pursue qualified trust service provider certification in priority EU jurisdictions. Channel control over managed service provider networks represents a secondary defensive lever against specialized cryptography vendors. For New Entrants and Emerging Players: Begin with hybrid cloud split-key architectures in underpenetrated French healthcare networks, where CNIL enforcement creates procurement urgency for dedicated HSM estates with sovereign data residency guarantees. A compliance-first go-to-market angle targeting clinical research organizations offers fastest path to referenceable enterprise accounts. For Investors and Strategic Acquirers: Hyperscale cloud platforms are the most active acquirer in this space, consolidating specialized HSM vendors and confidential computing startups to fill sovereign custody capability gaps. Long-term viability favors asset-light managed service providers with recurring revenue concentration above seventy percent. The signal to watch is EU Cybersecurity Certification scheme acceleration, which would compress vendor qualification timelines and reshape competitive entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | BMW and Volkswagen now mandate memory encryption for supplier cloud workloads. |
| Qualified Trust Service Provider Certification | EU Cybersecurity Certification schemes enable market access in regulated French and German jurisdictions. |
| Multi-Cloud Key Federation API Development | Pharmaceutical sponsors running multi-site trials require cryptographic agility across heterogeneous infrastructure estates. |
| Hybrid Cloud Split-Key Architecture Deployment | German automotive OEMs demand operational key management offloading while retaining root key material on-premises. |
| Vaultless Tokenization Platform Launch | High-throughput automotive telematics pipelines are displacing vault-based encryption for performance-critical applications. |
Methodological Framework
Direct dialogue with chief information security officers, cloud infrastructure architects, cryptography procurement leads, and managed service provider executives grounded this analysis, cross-referenced against hyperscaler capex disclosures, EU regulatory filings, FIPS 140-2 validation databases, and automotive OEM supplier requirement documents. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market trajectories.
Bottom-up modeling projected adoption curves across deployment mode, service type, and client type segments, while top-down analysis anchored aggregate market scale against cloud security spending patterns. CAGRs were derived from installation base expansion and average revenue per account trends across the projection horizon. Forecast inputs incorporated EU AI Act implementation timelines, GDPR supervisory authority enforcement patterns, and confidential computing hardware availability roadmaps.
Caveats apply where EU Cybersecurity Certification scheme delays, FIPS 140-2 Level 3 foundry capacity constraints, or qualified trust service provider qualification failures could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Game Engines Market
Digital Solutions
Spain Digital Twin Market
Digital Solutions
Construction Design App Market
Digital Solutions
Shipping Software Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
South Korea Cloud OSS BSS Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
US Transcription Market
Digital Solutions
Global Media (Video) Processing Solutions Market