
 Document Management System Market | 2026-2036
Document Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Document Management System Market Analysis
Mid-market enterprises is unwinding legacy paper-dependent workflows faster than Fortune 500 incumbents. OpenText Documentum anchors high-compliance verticals with deep records-management heritage. Microsoft SharePoint leverages existing Office 365 estates to dominate departmental collaboration deployments. M-Files competes through metadata-driven architecture that eliminates folder-hierarchy constraints.
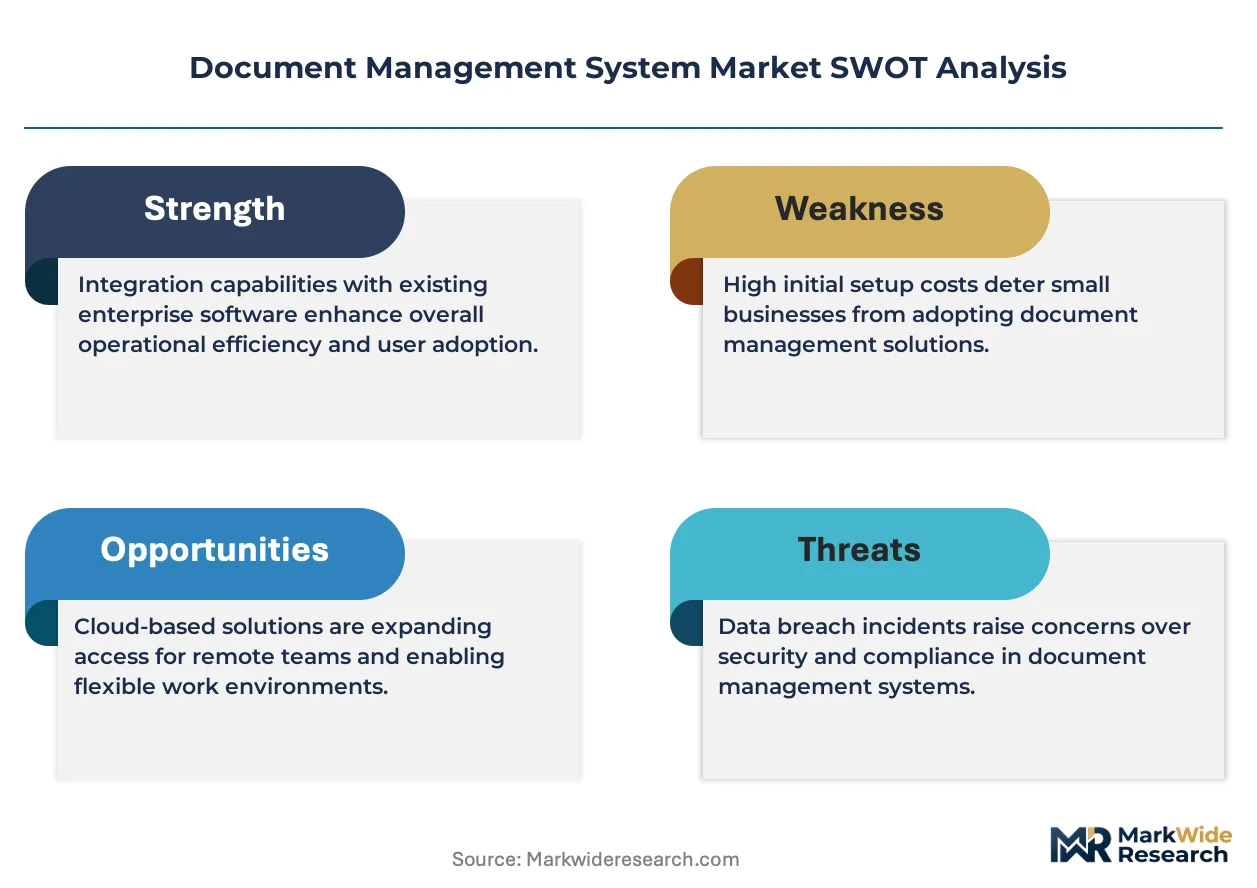
A Document Management System is a software platform that captures, indexes, stores, retrieves, and governs electronic documents through centralized repositories with audit trails, access controls, and retention policies. Its primary commercial purpose is to enforce information governance while accelerating document-centric business processes. Cloud-Based deployment leads in new customer acquisition as IT departments trade capital expenditure for subscription flexibility. Workflow Automation functionality captures the fastest expansion within the Functionality segment because enterprises prioritize straight-through processing over passive storage. API-Based integration sits at the margin pool center, since connectivity premiums compound across enterprise application stacks.
FDA 21 CFR Part 11 in the United States and EMA Annex 11 in Europe impose validation requirements on electronic records in life sciences, directly shaping vendor product roadmaps and buyer qualification checklists. India's BIS IT Act amendments and the EU AI Act's risk-classification framework are extending compliance scope into automated document classification. Stakeholders must monitor whether emerging sovereign-data regulations fragment cloud-deployment strategies or consolidate vendor selection around regional data-residency certifications.
Market Dynamics
Cloud migration mandates under GDPR and HIPAA are forcing enterprises to retire on-premise repositories and requalify vendors against data-residency certifications, compressing procurement cycles and consolidating supplier shortlists.
Growth Catalysts
- HIPAA digitization mandates:Healthcare providers in the United States must convert paper patient records to electronic formats, driving repository modernization and workflow automation procurement.
- AI-powered metadata extraction:Machine learning classification engines are eliminating manual indexing bottlenecks in legal and financial services document ingestion pipelines.
- Germany's Mittelstand modernization wave:Mid-market manufacturers are accelerating legacy paper-dependent workflow replacement ahead of EU CSRD reporting deadlines.
Market Restraints
- Cloud egress cost volatility:Data retrieval fees from hyperscale storage tiers create unpredictable operational expenditure spikes for high-volume archival users.
- Validation documentation burden:FDA 21 CFR Part 11 and EMA Annex 11 impose multi-quarter qualification timelines that delay production deployment in life sciences.
- Legacy system integration friction:Proprietary APIs from 1990s-era ECM platforms resist standard REST connectivity, forcing costly middleware development.
Strategic Opportunities
- India's BIS IT Act compliance surge:Data localization amendments are creating first-mover advantage for vendors with Mumbai and Hyderabad region certifications.
- Converged RPA-DMS platforms:Robotic process automation vendors are embedding document capture into straight-through processing workflows for insurance claims.
- API monetization models:Connectivity-first pricing is capturing premium margins from enterprise architects building composite application stacks.
Industry Challenges
- Information governance specialist scarcity:Certified records managers with cross-border retention expertise command salary premiums that strain implementation budgets.
- Multi-jurisdiction retention conflicts:Conflicting statutory periods between EU GDPR right-to-erasure and US SEC 17a-4 immutability rules complicate global deployment architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Document Management System Market |
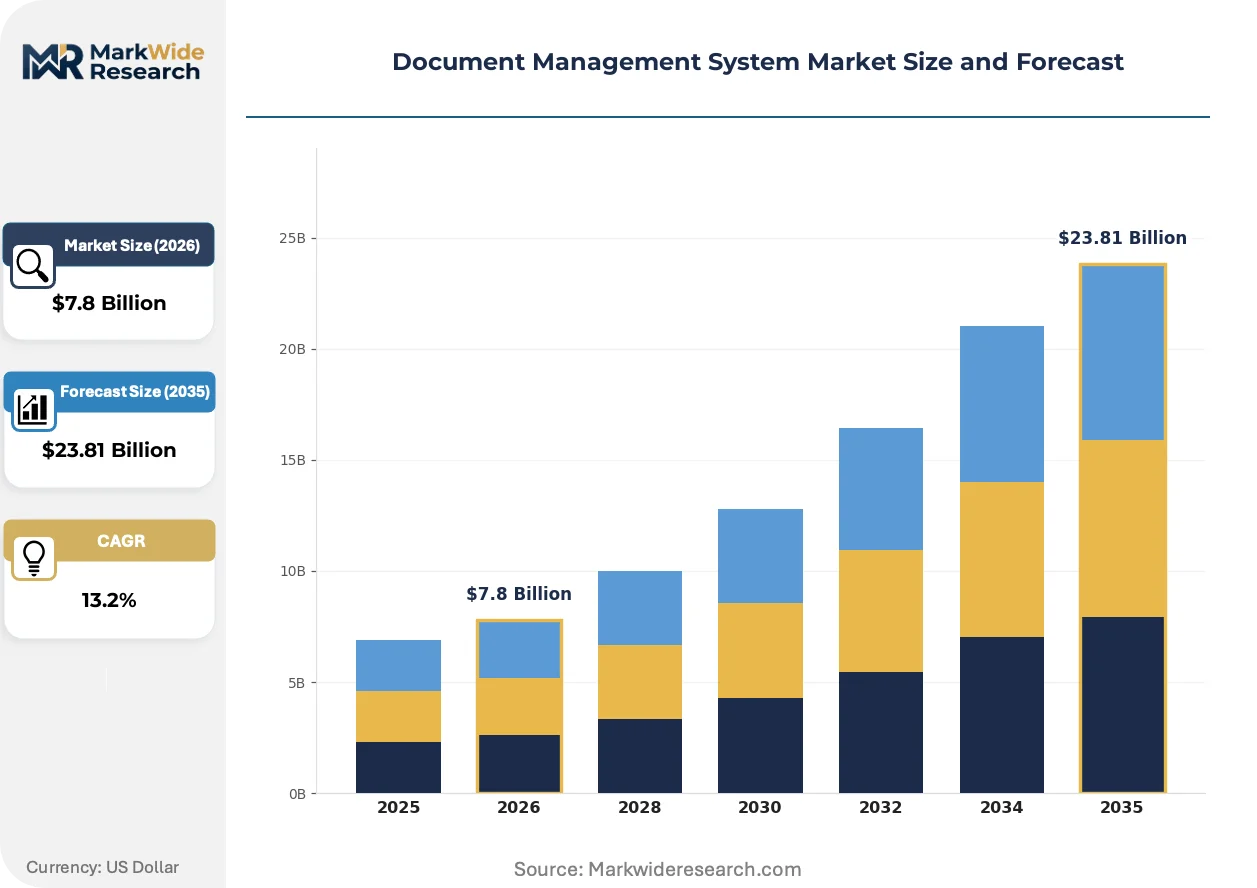
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $23.81 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Remote End User: Healthcare, Legal, Education, Finance Functionality: Version Control, Document Retrieval, Workflow Automation, Collaboration Tools Integration: API-Based, Third-Party Applications, Mobile Integration, Desktop Sync |
| Companies Covered | Box, OpenText Documentum, M-Files, eFileCabinet, NetDocuments, Microsoft SharePoint, Laserfiche, Adobe Document Cloud, DocuWare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Document Management System Market Emerging Trajectories
Metadata-driven architecture is displacing folder-hierarchy paradigms, while regulatory automation and consumption-based procurement models are redefining vendor-buyer relationships across compliance-intensive verticals.
Intelligent document processing engines are miniaturizing extraction workloads onto edge deployments. Manufacturing quality teams at automotive suppliers are adopting lightweight on-premise OCR nodes to avoid cloud latency in defect documentation. This architecture is miniaturizing the capture layer and decoupling ingestion from central repository dependencies.
EMA Annex 11 validation guideline updates are tightening electronic signature audit trail requirements. Pharmaceutical quality assurance departments must now demonstrate continuous monitoring of document system performance. Contract research organizations in Ireland and Switzerland are responding by pre-qualifying vendors with pre-validated infrastructure templates.
Subscription elasticity is compressing traditional perpetual-license renewal cycles. Enterprise buyers in financial services are unbundling storage from workflow functionality and sourcing each component through separate cloud marketplaces. This fragmentation is most visible in London and Singapore, where procurement teams maintain multiple concurrent vendor relationships to optimize unit economics.
Document Management System Market Segmentation
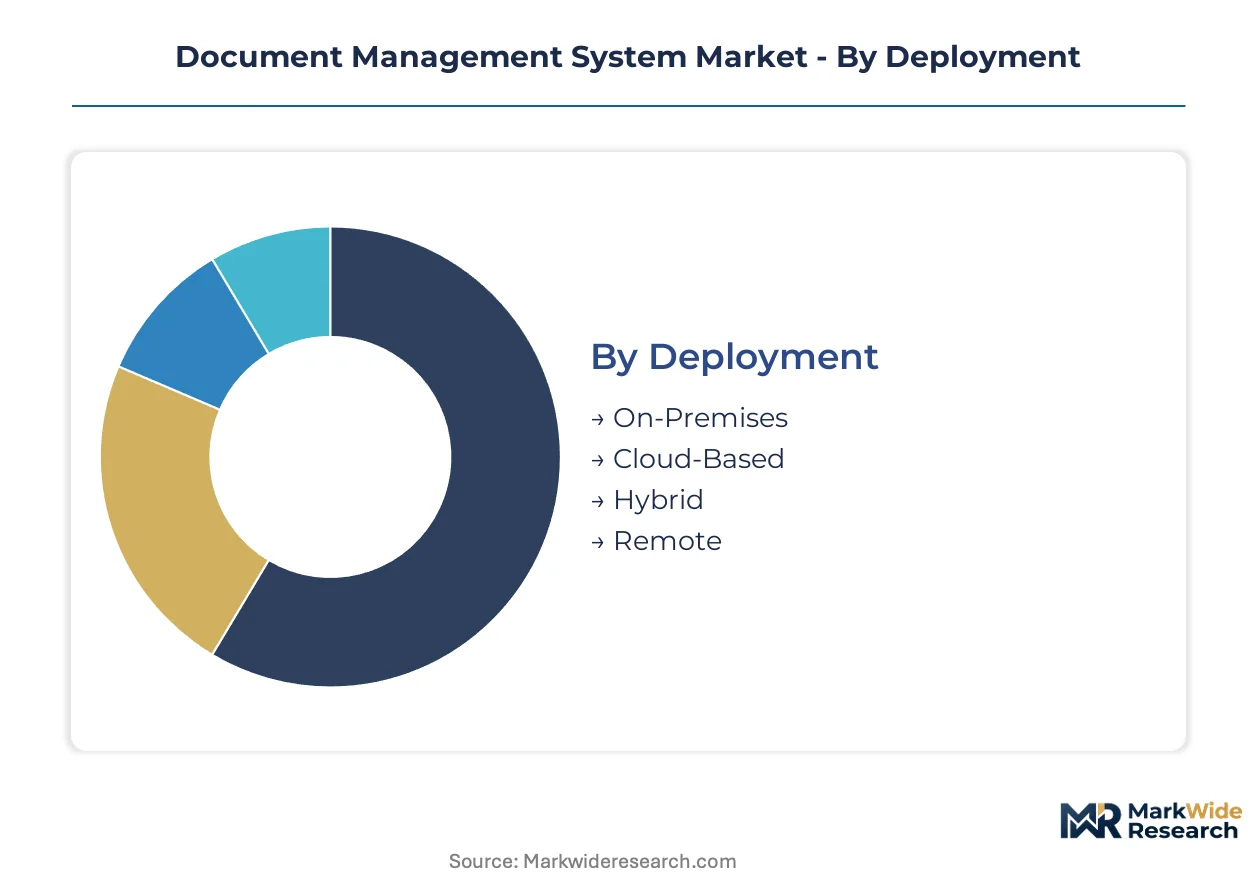
Deployment architecture determines capital structure and vendor selection criteria across compliance-intensive verticals. Functionality depth separates passive archival systems from process-automation platforms that command subscription premiums.
Deployment:
Margin pools concentrate in hybrid configurations that balance data-residency mandates with cloud elasticity.
- Cloud-Based:Multi-tenant SaaS architectures eliminate infrastructure ownership while embedding automatic compliance updates. Healthcare providers in the United States favor this model under HIPAA digitization mandates that require rapid scaling without capital commitment.
- Hybrid:Split-stack deployments retain sensitive records on-premise while pushing collaborative workflows to cloud tiers. Germany's Mittelstand manufacturers deploy this architecture to satisfy GDPR data-residency requirements without sacrificing remote access functionality.
- On-Premises:Self-managed infrastructure persists in defense and classified government environments where air-gapped security is non-negotiable.
- Remote:Edge-optimized deployments serve distributed field teams with intermittent connectivity, common in construction and utility inspection workflows.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
End User:
Application intensity varies sharply—healthcare and finance drive workflow automation depth, while legal and education prioritize search and retrieval.
- Healthcare:Patient record digitization mandates from HIPAA and parallel regulations in India and Europe are accelerating repository modernization. Diagnostic imaging integration and clinical trial documentation create the highest per-seat licensing values.
- Finance:Trade confirmation archiving, KYC document lifecycle management, and SEC 17a-4 immutability requirements dominate procurement specifications. API connectivity premiums compound across core banking system integrations.
- Legal:Matter-centric organization and privilege detection drive metadata extraction investments, though price sensitivity limits deployment scale relative to healthcare and finance.
- Education:Student record management and research data governance represent volume opportunity with compressed functionality requirements and elongated sales cycles.
Finance holds installed capacity. Healthcare is rotating up the share rankings.
Functionality:
Workflow automation commands the steepest expansion trajectory as enterprises prioritize straight-through processing over passive storage.
- Workflow Automation:Rules-based routing and approval chains eliminate manual handoffs in insurance claims and loan origination. Machine learning classification engines are embedding directly into these pipelines to accelerate ingestion throughput.
- Document Retrieval:Full-text search with semantic relevance ranking remains the baseline expectation, though differentiation has shifted toward federated discovery across multiple repositories.
- Version Control:Check-in/check-out mechanisms and audit trails satisfy FDA 21 CFR Part 11 and EMA Annex 11 requirements in life sciences quality management.
- Collaboration Tools:Real-time co-authoring and annotation layers integrate with Microsoft 365 and Google Workspace estates, often sourced as bundled rather than standalone functionality.
Document Retrieval holds installed capacity. Workflow Automation is rotating up the share rankings.
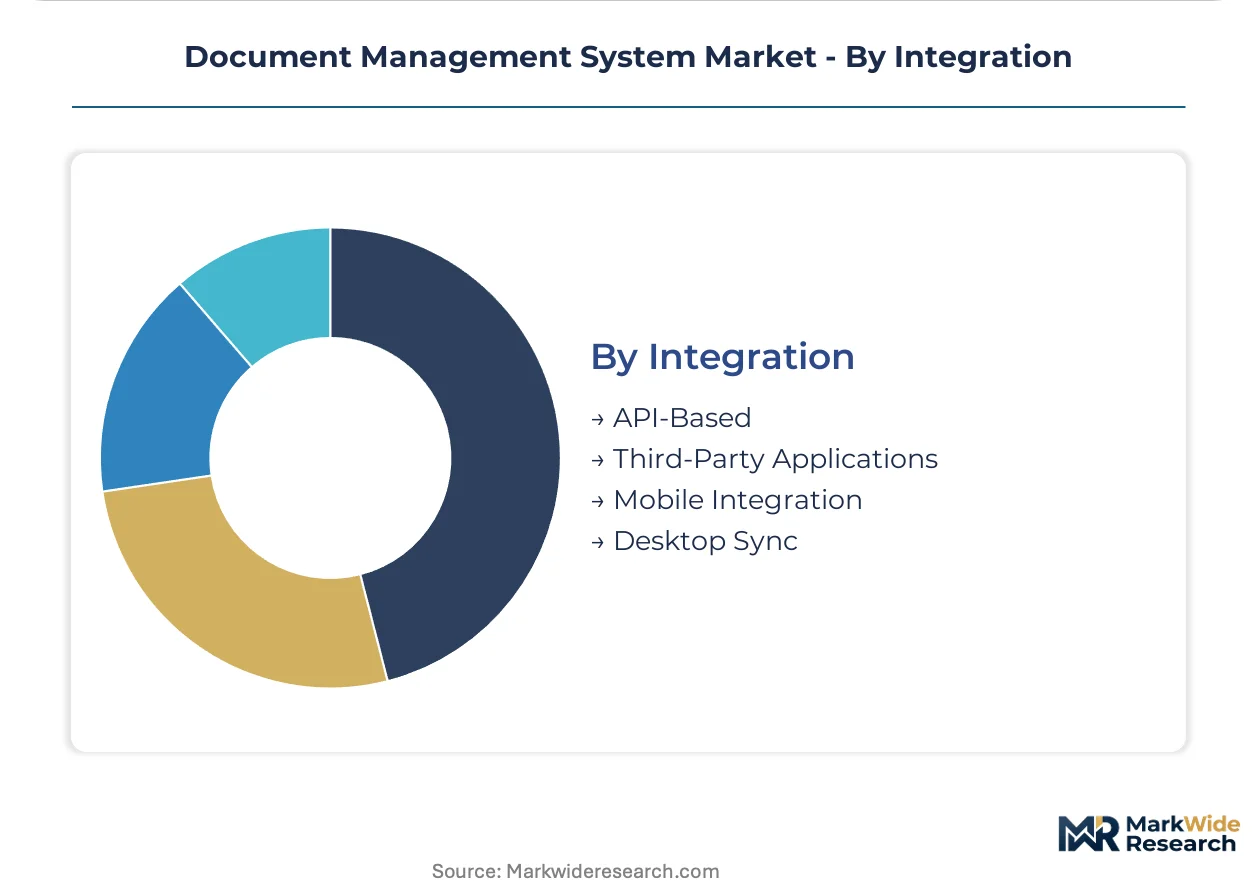
Integration:
API-Based connectivity sits at the margin pool center, capturing premium pricing from enterprise architects building composite application stacks.
- API-Based:REST and GraphQL endpoints enable headless document services that embed into custom applications. Vendors monetize through consumption-based pricing tiers tied to call volume.
- Third-Party Applications:Pre-built connectors for Salesforce, SAP, and Oracle ERP systems reduce implementation timelines and expand addressable user bases within existing accounts.
- Mobile Integration:Native iOS and Android SDKs support field capture scenarios in construction, logistics, and healthcare home visits where desktop access is impractical.
- Desktop Sync:Folder-mirroring clients bridge legacy user behaviors with cloud backends, common in legal and professional services transitions from on-premise file servers.
Third-Party Applications holds installed capacity. API-Based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software vendors in the United States export document management platforms to enterprise buyers across Germany, India, and the United Kingdom, with compliance certifications serving as the primary trade qualification mechanism.
United States
HIPAA digitization mandates and SEC 17a-4 immutability rules drive healthcare and financial services procurement. FDA 21 CFR Part 11 validation requirements shape vendor product roadmaps for pharmaceutical quality systems. Boston's life sciences corridor concentrates contract research organizations pre-qualifying electronic signature platforms.
Germany
Mittelstand manufacturers modernize paper-dependent workflows ahead of EU CSRD reporting deadlines. GDPR data-residency certifications compress procurement cycles toward regional cloud deployments. Stuttgart's automotive supplier ecosystem adopts hybrid architectures balancing on-premise sensitive records with cloud collaboration tiers.
India
BIS IT Act data localization amendments create first-mover advantage for vendors with Mumbai and Hyderabad region certifications. Healthcare providers accelerate patient record digitization parallel to United States HIPAA trajectories. Bangalore's enterprise software corridor hosts implementation specialists for metadata-driven repository migrations.
United Kingdom
Financial services firms unbundle storage from workflow functionality through separate cloud marketplaces. FCA operational resilience requirements extend to document system continuity planning. London's insurance market drives converged RPA-DMS procurement for claims straight-through processing.
Switzerland
Pharmaceutical quality assurance departments demand pre-validated infrastructure templates under tightened EMA Annex 11 guidelines. Contract research organizations in Basel and Zurich pre-qualify vendors for continuous monitoring capabilities. Swissmedic oversight reinforces multi-quarter validation timelines that delay production deployment.
Document Management System Market Vendor Landscape
Player mix skews toward established enterprise software incumbents with deep compliance heritage and cloud-native challengers with API-first architectures. The vendor base organizes around three strategic archetypes: legacy ECM platforms with records-management depth, hyperscale productivity suites with existing Office 365 estates, and metadata-driven specialists eliminating folder hierarchies. Consolidation pressures favor acquisition of vertical workflow automation capabilities, while partnership strategies dominate API ecosystem expansion.
Within the legacy ECM tier, OpenText Documentum anchors high-compliance verticals with validation-ready infrastructure templates. Microsoft SharePoint occupies a position leveraging existing enterprise productivity estates for departmental collaboration deployments. M-Files exemplifies the metadata-driven challenger archetype through architecture that displaces traditional folder constraints.
| Leading Market Players |
|---|
| Box |
| OpenText Documentum |
| M-Files |
| eFileCabinet |
| NetDocuments |
| Microsoft SharePoint |
| Laserfiche |
| Adobe Document Cloud |
| DocuWare |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day implementation timelines for hybrid cloud deployments concentrate pricing power with vendors holding pre-validated infrastructure templates, while subscription elasticity compresses traditional perpetual-license renewal cycles across enterprise procurement teams.
Pricing Analysis
Next-generation API-first architectures command 40-60% subscription premiums over legacy ECM perpetual licenses, while current-generation SaaS tiers stratify across enterprise, mid-market, and departmental entry points. Price differentiation hinges on FDA 21 CFR Part 11 validation tier and cross-border data-residency certification depth. Pricing pressure stems from hyperscale productivity suites bundling document functionality into existing Office 365 estates. Mid-market manufacturers in Germany exhibit highest price sensitivity; contract research organizations in Switzerland show lowest.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native deployments, while strategic stockpiling of validation documentation persists among life sciences buyers facing multi-quarter EMA Annex 11 qualification timelines. Software development concentrates in the United States, India, and Ireland. Intellectual property feeds from machine learning classification engines, REST API frameworks, and pre-built ERP connectors. Single-source vulnerability sits with hyperscale infrastructure dependencies. Distribution runs through direct enterprise sales, cloud marketplaces, and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates formidable switching costs—validated infrastructure templates and multi-jurisdiction compliance certifications embed vendors deeply into buyer procurement cycles.
For Market Incumbents: Secure pre-validated infrastructure template expansion across EMA Annex 11 and FDA 21 CFR Part 11 requirements to defend against metadata-driven challengers. Anchor in vertical workflow automation capabilities through targeted acquisition of insurance claims and clinical trial documentation specialists. Certification investment in India's BIS IT Act data localization represents the priority lever.
For New Entrants and Emerging Players: Anchor in India's BIS IT Act compliance surge where first-mover advantage awaits vendors with Mumbai and Hyderabad region certifications. Target converged RPA-DMS platforms for London insurance market claims straight-through processing. API monetization models offer the most penetrable go-to-market angle through consumption-based pricing tiers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because compliance certification depth compounds customer lifetime value through renewal stickiness and expansion revenue. Acquisition target archetype: metadata-driven specialists with vertical workflow automation depth. Watch FDA 21 CFR Part 11 guideline revision timing as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Infrastructure Expansion | EMA Annex 11 compliance templates compress pharmaceutical procurement cycles in Basel and Zurich. |
| API-First Architecture Development | REST and GraphQL endpoints capture premium margins from enterprise architects building composite stacks. |
| Vertical Workflow Automation Acquisition | Insurance claims straight-through processing expertise deepens London market penetration. |
| Regional Data Residency Certification | Mumbai and Hyderabad certifications create first-mover advantage under India's BIS IT Act amendments. |
| Metadata-Driven Platform Migration | Folder-hierarchy elimination accelerates mid-market German Mittelstand modernization ahead of EU CSRD deadlines. |
Methodological Framework
A standing panel of chief information officers, compliance officers, procurement directors, and systems integration specialists provided ongoing calibration against vendor product roadmaps and buyer qualification checklists. Primary interviews with healthcare IT directors, pharmaceutical quality assurance leads, and financial services records managers combined with secondary validation from FDA 510(k) filings, EMA submission databases, SEC 10-K software segment disclosures, and hyperscaler capex reports. Bottom-up deployment counts triangulated with top-down subscription revenue estimates.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to annualized subscription bookings. Forecast inputs incorporated HIPAA digitization mandate compliance deadlines and EU CSRD reporting timeline acceleration.
Decision-makers should treat outputs as directional under sustained cloud migration preference and regulatory harmonization assumptions; material deviation would warrant model refresh. Revision becomes warranted when sovereign data localization requirements fragment cloud-deployment strategies or consolidate vendor selection around regional certifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Search Market
Digital Solutions
IPTV Market
Digital Solutions
Utility App Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Business Information Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market