
 Smart Agriculture Technology Market | 2026-2036
Smart Agriculture Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Agriculture Technology Market Insights
Subscription-based agronomic software is repositioning equipment sales toward recurring revenue models. Deere & Company leverages its Operations Center platform to lock in multi-year data contracts. Trimble Inc. anchors its precision-ag portfolio through NAV-900 guidance controllers and cloud-connected correction services. AGCO Corporation competes via Fuse Smart Farming, an open-architecture system that integrates third-party IoT devices without proprietary lock-in.
Smart agriculture technology encompasses sensor networks, autonomous machinery, and data analytics platforms that collect field-level environmental and biological data to optimize input application and harvest timing. Systems typically integrate GPS-corrected positioning to sub-inch accuracy with variable-rate controllers for seed, fertilizer, and crop protection. Precision Farming generates the dominant revenue stream through yield monitors and auto-steer systems, while AI Analytics expands fastest as computer-vision models classify weed species and predict grain protein content. Livestock Monitoring remains comparatively mature, with margin pools concentrating in herd-health diagnostics rather than basic activity tracking collars.
The EPA governs drone-based pesticide application through Part 137 agricultural aircraft certifications, while the USDA channels conservation-tech adoption via Environmental Quality Incentives Program cost-share agreements. EU F-Gas Regulation phases out hydrofluorocarbon refrigerants in controlled-environment agriculture, redirecting greenhouse automation investment toward CO2-based climate systems. Stakeholders must weigh compliance-driven hardware upgrades against software-centric platform strategies as regulatory granularity tightens across multiple jurisdictions.
Market Dynamics
Subscription-based agronomic software is repositioning equipment sales toward recurring revenue models, forcing hardware manufacturers to build platform ecosystems that capture multi-year data contracts rather than one-time machinery transactions.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Chemical-use reporting requirements tighten across member states, pushing farms toward sensor-based compliance systems that automate documentation.
- Automated Irrigation:Brazil's Mato Grosso soy belt concentrates demand for precision water management as drought cycles intensify and input costs escalate.
- Drone-Based Field Mapping:Large-scale row-crop operations across the US Corn Belt deploy aerial imaging to optimize variable-rate input application and reduce overlap waste.
Market Restraints
- Connectivity Infrastructure Gaps:Rural broadband deficits in agricultural regions delay real-time data transmission for cloud-dependent platforms.
- Proprietary Data Lock-In:Equipment manufacturers restrict interoperability, forcing farms to maintain fragmented technology stacks across brands.
- Sensor Hardware Costs:Soil moisture and weather station networks require substantial upfront capital that mid-sized operations struggle to justify.
Strategic Opportunities
- Carbon Credit Verification:USDA Environmental Quality Incentives Program cost-share agreements channel conservation-tech adoption, creating revenue streams from soil carbon sequestration data.
- AI-Computer Vision Convergence:Machine learning models classify weed species and predict grain protein content, opening premium pricing for quality-assured harvests.
- Controlled-Environment Agriculture:EU F-Gas Regulation phases out hydrofluorocarbon refrigerants, redirecting greenhouse automation investment toward CO2-based climate systems.
Industry Challenges
- Agronomic Data Science Talent:Farms lack personnel capable of interpreting complex yield maps and prescription algorithms, creating adoption bottlenecks.
- Legacy Equipment Integration:Older tractors and implements require aftermarket retrofit kits that introduce calibration errors and warranty conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Agriculture Technology Market |
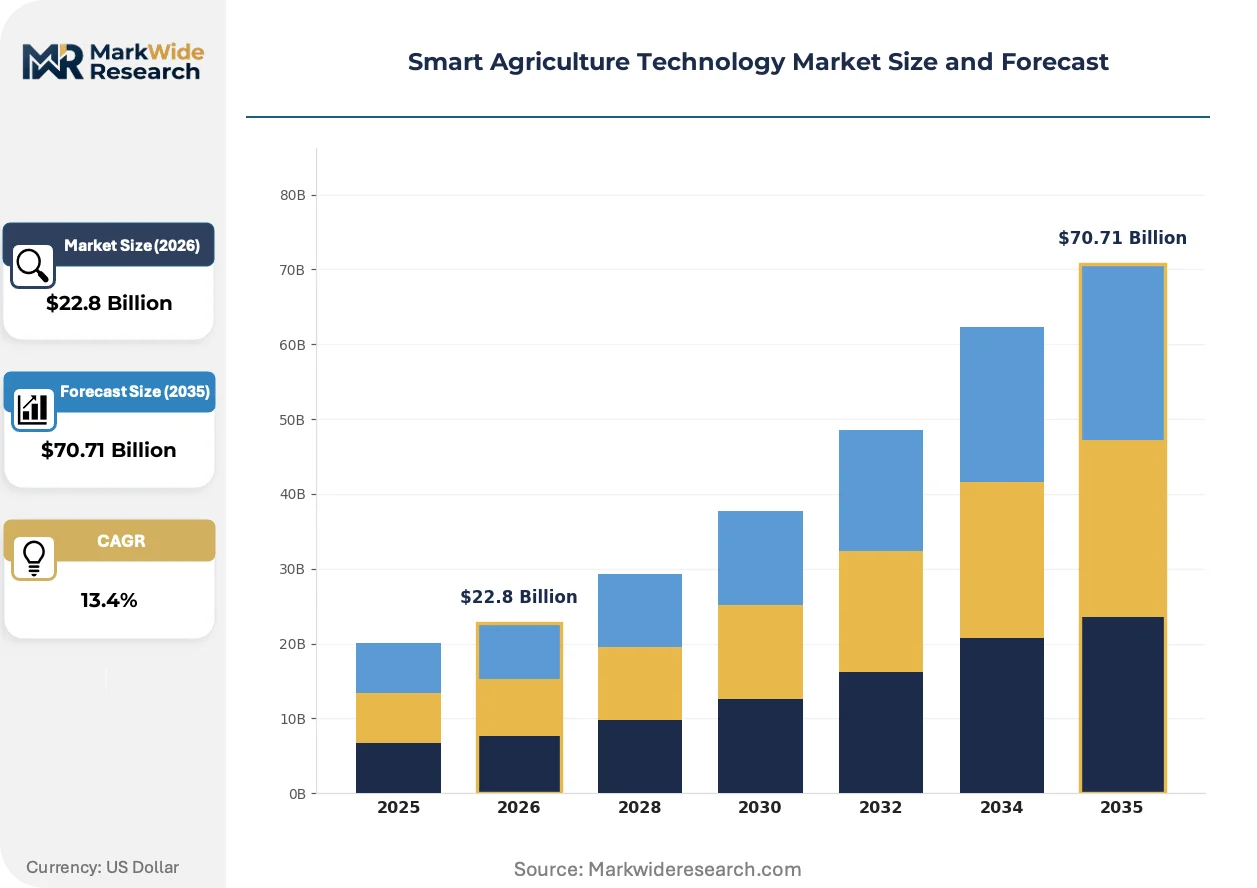
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $70.71 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precision Farming, Livestock Monitoring, Greenhouse Automation, Crop Management Technology: IoT Sensors, Drones, AI Analytics, Soil Monitoring Application: Irrigation Management, Pest Control, Yield Prediction, Field Mapping End User: Farmers, Agricultural Cooperatives, Research Institutions, Agribusinesses |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial, Bayer, Kubota Corporation, Topcon, CLAAS Group, Farmers Edge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Agriculture Technology Market Trends and Innovations
Precision agriculture is fragmenting into specialized component ecosystems where farms assemble best-of-breed solutions rather than accepting bundled proprietary stacks from single manufacturers.
Edge computing hardware is modularizing field-level data processing, enabling real-time decision-making without cloud dependency. Mid-sized grain operations in the US Corn Belt adopt these ruggedized units fastest, cutting latency for auto-steer corrections and variable-rate triggers. This architecture is modularizing supplier relationships as farms mix sensor brands with independent guidance controllers.
EU F-Gas Regulation mandates refrigerant phase-outs in controlled-environment agriculture, forcing greenhouse operators toward CO2 heat pump systems. Dutch and Spanish vegetable producers face retrofit deadlines that compress capital planning cycles. Protected-crop segments respond by clustering near industrial CO2 sources to secure supply contracts.
Service unbundling disrupts traditional dealer networks as farms purchase precision-ag subscriptions directly from software platforms. Equipment distributors lose attachment revenue for agronomic advisory, while independent crop consultants capture recurring fees for prescription optimization. This channel shift concentrates in regions with mature broadband infrastructure and large consolidated acreage.
Smart Agriculture Technology Market Segmentation
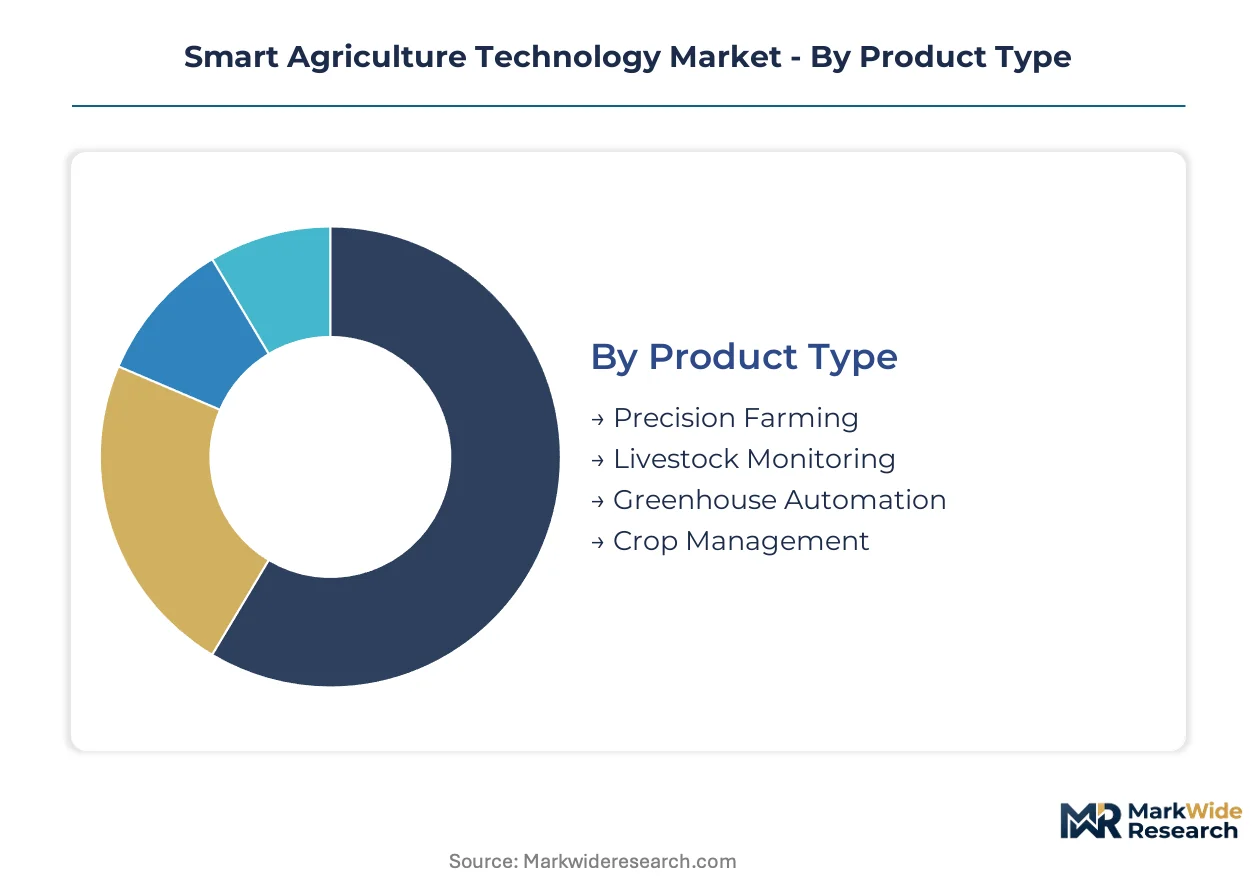
Smart agriculture technology segments reflect divergent buyer priorities across capital intensity, data maturity, and operational scale. Equipment manufacturers and software platforms configure pricing architectures around these divisions to capture recurring revenue versus one-time hardware sales.
Product Type:
Investment scale and payback horizon drive purchasing decisions across these categories, with large row-crop operations favoring capital-intensive systems while smaller holdings prioritize modular entry points.
- Precision Farming:GPS-corrected auto-steer systems and variable-rate controllers dominate capital allocation in the US Corn Belt and Brazil's Mato Grosso soy belt. Deere & Company and Trimble Inc. anchor subscription revenue through cloud-connected guidance platforms that lock in multi-year data contracts.
- Livestock Monitoring:Herd-health diagnostics and activity tracking collars command premium pricing in concentrated dairy regions. Margin pools concentrate in predictive health analytics rather than basic collar hardware as veterinary integration deepens.
- Greenhouse Automation:Climate control systems and CO2-based heat pumps redirect investment under EU F-Gas Regulation refrigerant phase-outs. Dutch and Spanish vegetable producers cluster near industrial CO2 sources to secure supply contracts.
- Crop Management:Field-level prescription software and harvest logistics platforms serve mid-sized grain operations seeking yield optimization without full precision hardware suites.
Volume sits with Precision Farming; growth tilts toward Greenhouse Automation as regulatory deadlines compress capital planning cycles.
Technology:
Interoperability requirements and connectivity infrastructure shape deployment patterns, with farms mixing sensor brands against independent guidance controllers to avoid proprietary lock-in.
- IoT Sensors:Soil moisture probes and weather station networks require substantial upfront capital that mid-sized operations struggle to justify where rural broadband deficits delay real-time data transmission.
- Drones:Aerial imaging platforms optimize variable-rate input application across large-scale operations. EPA Part 137 agricultural aircraft certifications govern pesticide application, constraining service provider expansion.
- AI Analytics:Computer-vision models classify weed species and predict grain protein content, opening premium pricing for quality-assured harvests. Machine learning platforms expand most quickly as farms seek decision automation.
- Soil Monitoring:Subsurface sensor arrays and nutrient mapping tools support compliance-driven documentation under EU Green Deal Farm to Fork chemical-use reporting requirements.
Hardware concentration favors IoT Sensors; software margins concentrate in AI Analytics as prescription algorithms displace manual agronomic judgment.
Application:
Water stress and input cost inflation elevate irrigation and pest control priorities, while yield prediction attracts data-forward early adopters seeking harvest timing optimization.
- Irrigation Management:Automated valve controllers and deficit-scheduling algorithms concentrate demand in drought-exposed regions. Brazil's Mato Grosso soy belt deploys precision water management as input costs escalate and rainfall variability intensifies.
- Pest Control:Drone-based pesticide application and targeted spraying systems reduce chemical volumes while satisfying tightening documentation requirements.
- Yield Prediction:Grain protein forecasting and harvest logistics modeling attract large-scale operations with sufficient historical data to train predictive algorithms.
- Field Mapping:Sub-inch accuracy elevation models and prescription zone delineation underpin variable-rate application programs across consolidated acreage.
Deployment scale favors Irrigation Management; technology advancement concentrates in Yield Prediction as satellite and ground-truth data fusion improves.
End User:
Organizational scale and data science capability determine platform complexity, with cooperatives aggregating member data for collective bargaining while individual farmers prioritize plug-and-play simplicity.
- Farmers:Owner-operators select modular systems with minimal calibration requirements, constrained by agronomic data science talent shortages that create adoption bottlenecks.
- Agricultural Cooperatives:Member-owned enterprises aggregate field-level data to secure input discounts and carbon credit verification revenue through USDA Environmental Quality Incentives Program cost-share agreements.
- Research Institutions:University and government experimental stations deploy full-stack sensor networks for variety trials and climate adaptation studies.
- Agribusinesses:Integrated grain handlers and input suppliers capture farm-level data to optimize procurement logistics and product placement.
Transaction volume concentrates with Farmers; platform sophistication concentrates with Agricultural Cooperatives as data aggregation unlocks collective value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of precision agriculture hardware concentrates in Germany and the United States, while consumption scales fastest in Brazil and India where large-scale mechanization meets data-driven input optimization.
United States
Large-scale row-crop operations across the US Corn Belt deploy GPS-corrected auto-steer systems and variable-rate controllers at scale. The USDA channels conservation-tech adoption through Environmental Quality Incentives Program cost-share agreements. Iowa and Illinois concentrate demand for yield monitors and cloud-connected guidance platforms that lock in multi-year data contracts.
Brazil
The Mato Grosso soy belt drives automated irrigation and drone-based field mapping as drought cycles intensify and input costs escalate. ANVISA governs pesticide registration and application standards, constraining service provider expansion. Precision water management clusters around Sorriso and Lucas do Rio Verde where consolidated acreage justifies capital-intensive sensor networks.
Germany
EU Green Deal Farm to Fork chemical-use reporting requirements push farms toward sensor-based compliance systems that automate documentation. The F-Gas Regulation phases out hydrofluorocarbon refrigerants in controlled-environment agriculture. Bavaria and Lower Saxony concentrate greenhouse automation investment toward CO2-based climate systems.
China
Dual carbon goals redirect agricultural automation investment toward energy-efficient precision systems and soil carbon monitoring. MIIT sets IoT device certification standards for rural deployment. Shandong and Heilongjiang provinces concentrate demand for autonomous machinery and subsurface sensor arrays in grain production zones.
India
PLI scheme incentives for agricultural mechanization accelerate precision equipment adoption in water-stressed regions. The CEA regulates rural electrification infrastructure that powers automated irrigation networks. Punjab and Haryana concentrate demand for drip automation and soil moisture monitoring as groundwater depletion tightens water access.
Smart Agriculture Technology Market Competitive Landscape
Top-tier vendors anchor platform ecosystems, while mid-tier specialists compete on modular interoperability and regional service density. The vendor base stratifies across bundled proprietary stacks and open-architecture alternatives. Three archetypes dominate: equipment manufacturers pivoting to recurring software revenue, independent guidance specialists, and data analytics platforms. M&A activity concentrates on sensor technology acquisitions and cloud infrastructure partnerships.
Within the equipment manufacturer tier, Deere & Company, Trimble Inc., and AGCO Corporation exemplify divergent platform strategies. Deere leverages its Operations Center to capture multi-year data contracts through cloud-connected guidance. Trimble anchors precision-ag portfolios through NAV-900 controllers and correction services. AGCO competes via open-architecture systems that integrate third-party IoT devices without proprietary lock-in.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial |
| Bayer |
| Kubota Corporation |
| Topcon |
| CLAAS Group |
| Farmers Edge |
| Others |
Pricing and Supply Chain Analysis
Backward integration into sensor fabrication and cloud infrastructure anchors pricing power for equipment manufacturers pivoting toward recurring software revenue. Deere & Company, Trimble Inc., and AGCO Corporation leverage captive production of guidance controllers and correction services to defend margin structures against modular competitors sourcing from independent suppliers.
Pricing Analysis
Margin tightening in precision hardware reflects subscription-model conversion costs and cloud infrastructure investment. Three-tier pricing structure across premium, standard, and economy levels separates bundled platform ecosystems from modular entry points and aftermarket retrofit kits. Certification grade under EU Green Deal Farm to Fork chemical-use reporting requirements commands premium positioning for sensor-based compliance systems. Mid-sized grain operations exhibit highest price sensitivity, constrained by upfront capital requirements for soil moisture networks and connectivity infrastructure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for GPS chipset fabrication and China for lithium-ion battery cells powering autonomous machinery. German and US production clusters anchor precision agriculture hardware assembly, drawing from Japanese MEMS sensor suppliers and South Korean display panel manufacturers. Tariff exposure on Chinese-sourced IoT components elevates landed costs for North American and European equipment manufacturers. Distribution runs through authorized dealer networks transitioning toward direct platform subscriptions in broadband-mature regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where equipment manufacturers capture recurring revenue through captive cloud infrastructure and proprietary data architectures. Incumbents and challengers compete on control of the sensor-to-software stack.
For Market Incumbents: Deepen backward integration into edge computing hardware to reduce dependency on Taiwanese GPS chipsets and Chinese battery suppliers. Expand certification investment for EU F-Gas Regulation compliance in controlled-environment agriculture. Defend platform ecosystems against AGCO Corporation's open-architecture alternative by locking multi-year data contracts through Operations Center-style cloud anchoring.
For New Entrants and Emerging Players: The price-point gap between Deere's premium subscription tier and economy retrofit kits creates white-space for modular interoperability solutions. Target mid-sized grain operations in Brazil's Mato Grosso soy belt with sensor-agnostic guidance controllers. Pursue direct-to-farm software subscriptions bypassing traditional dealer networks in Iowa and Illinois broadband corridors.
For Investors and Strategic Acquirers: Exit pathways concentrate in sensor technology acquisitions and cloud infrastructure partnerships rather than standalone hardware plays. Long-term viability hinges on data aggregation scale and regulatory compliance automation capability. Watch USDA Environmental Quality Incentives Program funding allocation shifts as inflection indicator for conservation-tech adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-connected guidance platforms lock in multi-year data contracts across US Corn Belt operations. |
| Backward Integration | In-house production of NAV-900 controllers reduces dependency on Taiwanese GPS chipset suppliers. |
| Regulatory Certification | EU F-Gas Regulation compliance opens greenhouse automation retrofit cycles in Dutch vegetable production. |
| Geographic Expansion | Automated irrigation networks capture drought-intensified demand in Brazil's Mato Grosso soy belt. |
| Acquisition of Specialist Firm | Computer-vision weed classification startups accelerate AI Analytics segment growth for protein prediction. |
Research Methodology
Multi-period observation of equipment shipment volumes, subscription renewal rates, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with precision agriculture platform engineers, farm operations managers at large-scale row-crop enterprises, USDA conservation program administrators, and agronomic data science consultants. Secondary validation drew from SEC 10-K filings of Deere & Company, Trimble Inc., and AGCO Corporation; EU Farm to Fork strategy implementation reports; ANVISA pesticide registration databases; and Brazil agricultural machinery import statistics. Bottom-up triangulation across farmer purchasing surveys and top-down reconciliation against equipment manufacturer revenue disclosures ensured cross-validation.
Input-output matrices modeled relationships between hardware unit sales, software subscription attach rates, and recurring revenue conversion across product type, technology, application, and end user segmentation dimensions. CAGRs were derived from slope analysis of historical shipment trajectories projected against regulatory deadline compression and input cost inflation assumptions. Irrigation management adoption curves in drought-exposed regions and AI Analytics penetration in protein prediction applications served as industry-specific forecast inputs throughout the projection horizon.
Inputs from equipment manufacturer financial disclosures and government conservation program databases were available through the study window; gaps in real-time farm-level profitability data and proprietary prescription algorithm performance metrics introduce uncertainty bands around adoption rate assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Irrigation Controllers Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
US Smart Agriculture Market