
 Connected Agriculture Market | 2026-2036
Connected Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Agriculture Market Intelligence
The substitution of intuition-based field management with sensor-derived data is decoupling farm profitability from unpredictable weather patterns. Deere & Company leverages its integrated hardware and software ecosystem to capture this value. Trimble specializes in precision GPS and guidance systems for autonomous farm equipment, while AGCO Corporation competes through its FendtONE platform offering open-architecture data solutions.
Connected agriculture involves the network integration of digital technologies into farming operations to enhance productivity and sustainability. It utilizes a suite of IoT devices, including soil sensors and aerial drones, to collect real-time data on crop health and soil conditions. Precision Farming applications currently dominate investment, driven by large agribusinesses. Cloud-based deployment models represent the fastest-growing segment due to scalability and lower upfront costs.
Government policies, including USDA grant programs in the United States and the EU's Common Agricultural Policy, directly influence technology adoption rates. Data governance frameworks like GDPR in Europe and new privacy laws in nations like Brazil shape how farm data is collected and shared. Decisions around data interoperability standards and cybersecurity protocols will determine long-term platform leadership and farmer trust.
Market Dynamics
The fundamental shift from intuition-based farming to data-driven agronomy is the central force shaping the market. This transition is propelled by economic pressures on large-scale farms and reinforced by sustainability mandates like the EU Green Deal.
Growth Catalysts
- Sustainable Farming Policies:The EU's Farm to Fork Strategy and associated eco-schemes directly incentivize the adoption of precision technologies to meet targets for reduced fertilizer and pesticide use, creating a strong regulatory pull for connected solutions.
- IoT Sensor Proliferation:Advances in low-power, wide-area networks and the decreasing cost of soil, weather, and crop sensors make large-scale data collection economically viable for agribusinesses in core markets like the United States.
- Operational Efficiency Demand:In agricultural powerhouses such as Brazil and Australia, large farm operators are investing in connected systems to optimize resource use, manage labor shortages, and mitigate the financial impact of climate volatility.
Market Restraints
- Rural Connectivity Gaps:The absence of reliable, high-speed broadband infrastructure in many agricultural regions remains a primary barrier, limiting the functionality of cloud-dependent platforms and real-time data analytics tools.
- High Capital Outlay:The significant upfront investment required for precision hardware, including GPS-enabled tractors and drone fleets, is prohibitive for many small and medium-sized farming enterprises globally.
- Data Interoperability Issues:A lack of industry-wide standards for data formats and APIs across different equipment and software vendors creates data silos, hindering the creation of a unified farm management dashboard.
Strategic Opportunities
- Emerging Market Expansion:Government initiatives to boost food security and agricultural productivity in nations across Southeast Asia and sub-Saharan Africa present a significant opportunity for deploying entry-level connected farming solutions.
- High-Value Crop Specialization:Developing tailored IoT and analytics platforms for specialty segments like viticulture, aquaculture, and indoor vertical farming allows for premium pricing and addresses specific, high-stakes operational needs.
- Supply Chain Traceability:Integrating blockchain with farm-level data provides immutable proof of origin and production practices, meeting rising consumer and regulatory demand for food transparency and safety verification.
Industry Challenges
- Agronomic Talent Scarcity:A persistent shortage of professionals with dual expertise in agronomy and data science limits the ability of farms to translate raw sensor data into effective, actionable field-level decisions.
- Data Governance and Security:Establishing trust with farmers regarding data ownership, privacy, and cybersecurity is critical, especially as farm data becomes an increasingly valuable asset governed by regulations like GDPR.
- Legacy System Integration:The operational complexity of integrating modern digital tools with existing, non-standardized farm machinery and decades-old management practices slows down technology adoption and return on investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Agriculture Market |
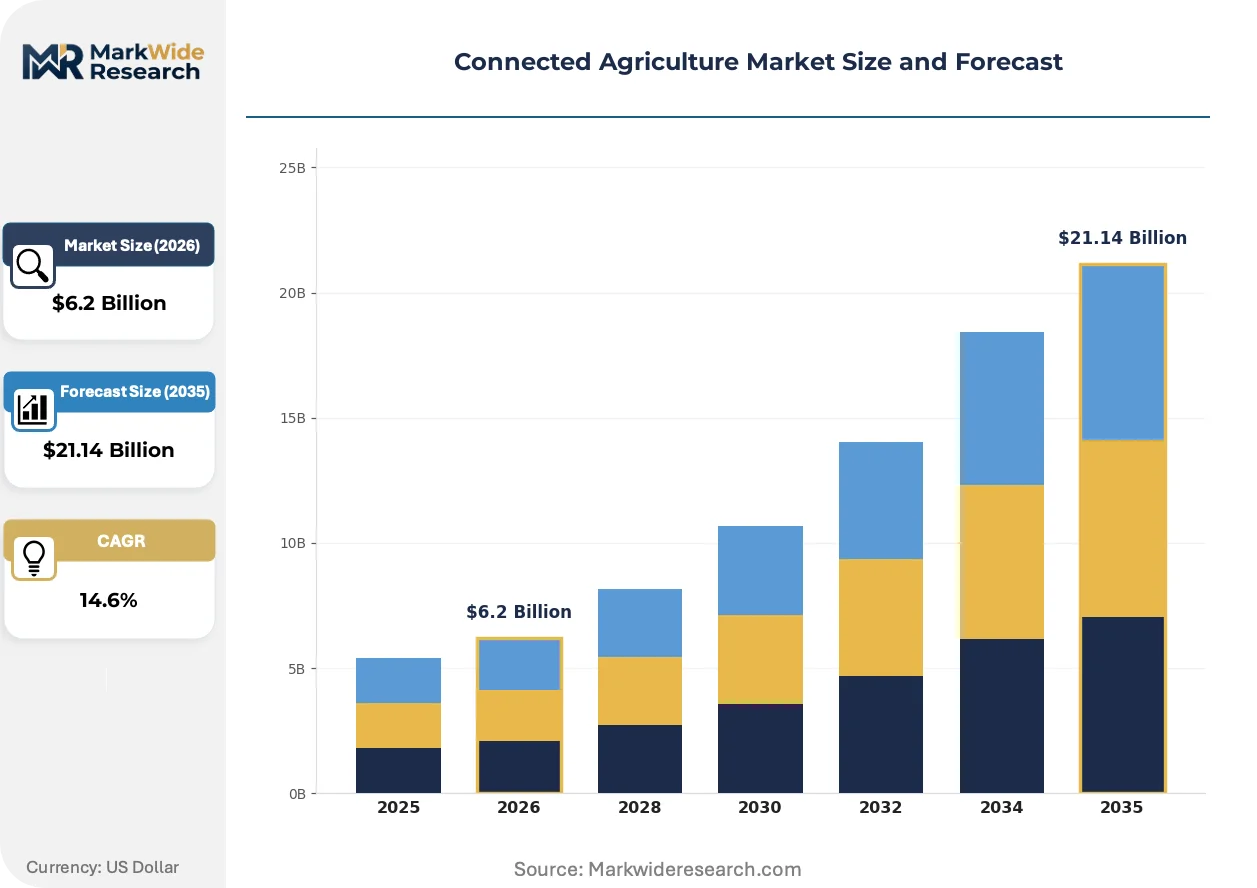
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $21.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, Drones, Sensors, GPS Technology End User: Farmers, Cooperatives, Agribusinesses, Research Institutions Application: Crop Monitoring, Soil Management, Livestock Tracking, Precision Farming Deployment: On-Premise, Cloud-Based, Edge Computing, Hybrid Solutions |
| Companies Covered | Deere & Company, AGCO Corporation, Raven Industries, Trimble, CNH Industrial, IBM Corporation, Microsoft Corporation, Cisco Systems, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Agriculture Market Strategic Shifts & Innovations
Automation and data autonomy are redefining field-level operations. The market is moving beyond simple monitoring toward systems that enable automated decision-making and robotic execution, driven by advancements in artificial intelligence and machine learning algorithms.
Autonomous Machinery: Autonomous farm equipment, guided by precision GPS and AI-powered computer vision, automates tasks like planting, spraying, and harvesting. Large-scale agribusinesses in North America and Australia are the primary adopters, seeking to reduce labor costs and improve operational uptime. This level of automation is overtaking manual operator control for repetitive, high-precision field tasks, fundamentally changing farm labor dynamics.
Policy-Driven Technology Adoption: The EU's Common Agricultural Policy (CAP) now incorporates "eco-schemes" that financially reward farmers for adopting sustainable practices, including precision agriculture. This policy creates direct financial incentives for investing in sensor networks and variable rate application technology to reduce input waste. Farmers in member states like France and Germany are most affected, re-evaluating technology investments to align with CAP funding requirements.
Subscription-Based Service Models: A shift from one-time hardware sales towards subscription-based "Farming-as-a-Service" (FaaS) models is gaining traction. This approach bundles hardware, software, and agronomic support into a recurring fee, lowering the upfront cost barrier and creating predictable revenue for vendors. This trend is most visible in the North American market, where equipment dealers and ag-tech startups are pioneering these service-oriented offerings.
Connected Agriculture Market Segmentation
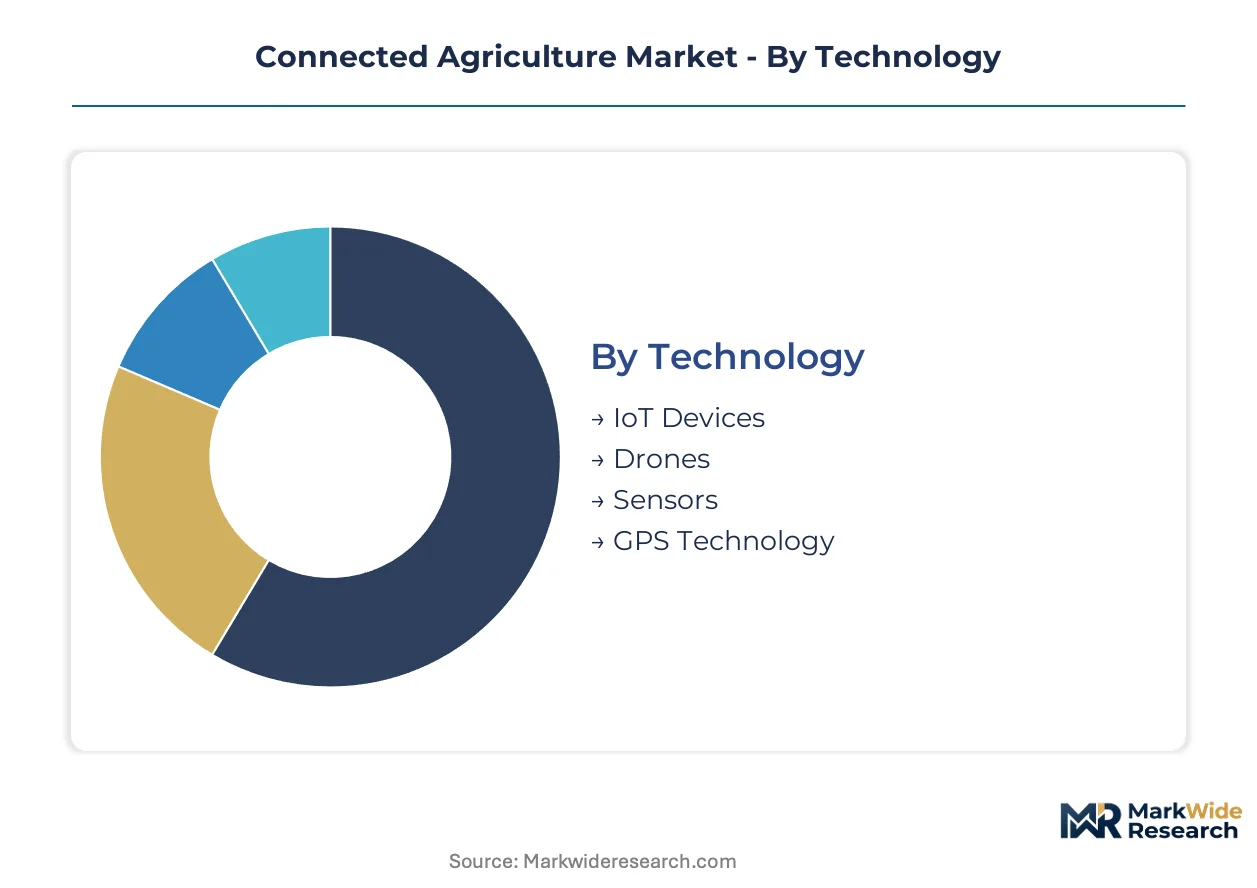
Connected agriculture segmentation provides a granular view of technology adoption and operational impact across diverse farming environments. Understanding these distinct categories helps stakeholders identify specific needs, allocate resources effectively, and tailor solutions for optimal agricultural productivity and sustainability. Each segment reflects unique drivers and constraints influencing market penetration.
Technology:
Technology choices in connected agriculture differentiate buyers based on their operational scale and data acquisition needs.
- IoT Devices:These integrated hardware and software units collect diverse environmental and operational data, enabling real-time monitoring and automated control across large-scale farm operations. Demand concentrates in agribusinesses in the United States, driven by the need for comprehensive data integration across vast land areas.
- Sensors:Specialized sensors measure specific parameters like soil moisture, nutrient levels, and crop health, providing localized, actionable data for precision input application. Investments in Brazil are strong, as farmers seek to optimize fertilizer and water use to manage high input costs.
- Drones:Unmanned aerial vehicles equipped with cameras and sensors capture high-resolution imagery for crop scouting, field mapping, and targeted spraying, offering efficient data collection over expansive fields.
- GPS Technology:Global Positioning System solutions provide precise location data for autonomous farm equipment and variable rate application, enhancing accuracy and reducing overlap in field operations.
Volume sits with Sensors; growth tilts toward IoT Devices.
End User:
Customer type segmentation reflects varying scales of operation and financial resources within the agricultural sector.
- Agribusinesses:Large-scale corporate farming entities with extensive landholdings and complex supply chains, demanding integrated solutions for efficiency, compliance, and large-volume output. Investment patterns concentrate in Agribusinesses across Australia, where economies of scale drive technology adoption.
- Farmers:Individual or family-owned farming operations, often characterized by smaller land sizes and a greater focus on cost-effective, easy-to-implement connected solutions. Farmers in France demonstrate significant expansion, driven by EU Common Agricultural Policy incentives for sustainable practices.
- Cooperatives:Groups of farmers pooling resources for shared services, equipment, and market access, often adopting connected technologies collectively to benefit all members.
- Research Institutions:Academic and private organizations utilizing connected agriculture technologies for data collection, experimentation, and development of new farming practices and crop varieties.
Investment patterns concentrate in Agribusinesses, with Farmers showing significant expansion.
Application:
Application scope defines how connected agriculture solutions address specific operational challenges on the farm.
- Precision Farming:This holistic approach uses data-driven insights to optimize resource allocation, including water, fertilizer, and pesticides, across specific field areas for maximum yield and sustainability. The largest revenue contribution stems from Precision Farming, particularly in the United States, due to its direct impact on profitability and resource conservation.
- Crop Monitoring:Technologies used to track crop health, growth stages, and potential stressors like pests or diseases, enabling timely interventions to protect yields. Crop Monitoring is a primary entry point for technology adoption among farmers in Germany, driven by environmental regulations.
- Soil Management:Solutions focused on analyzing soil composition, moisture content, and nutrient levels to inform irrigation schedules and fertilization strategies.
- Livestock Tracking:Systems that monitor the health, location, and behavior of individual animals or herds, improving animal welfare and operational efficiency in ranching.
The largest revenue contribution stems from Precision Farming, while Livestock Tracking demonstrates the steepest expansion trajectory.
Deployment:
Infrastructure requirements dictate the deployment models, influencing scalability and upfront capital expenditure for farm operations.
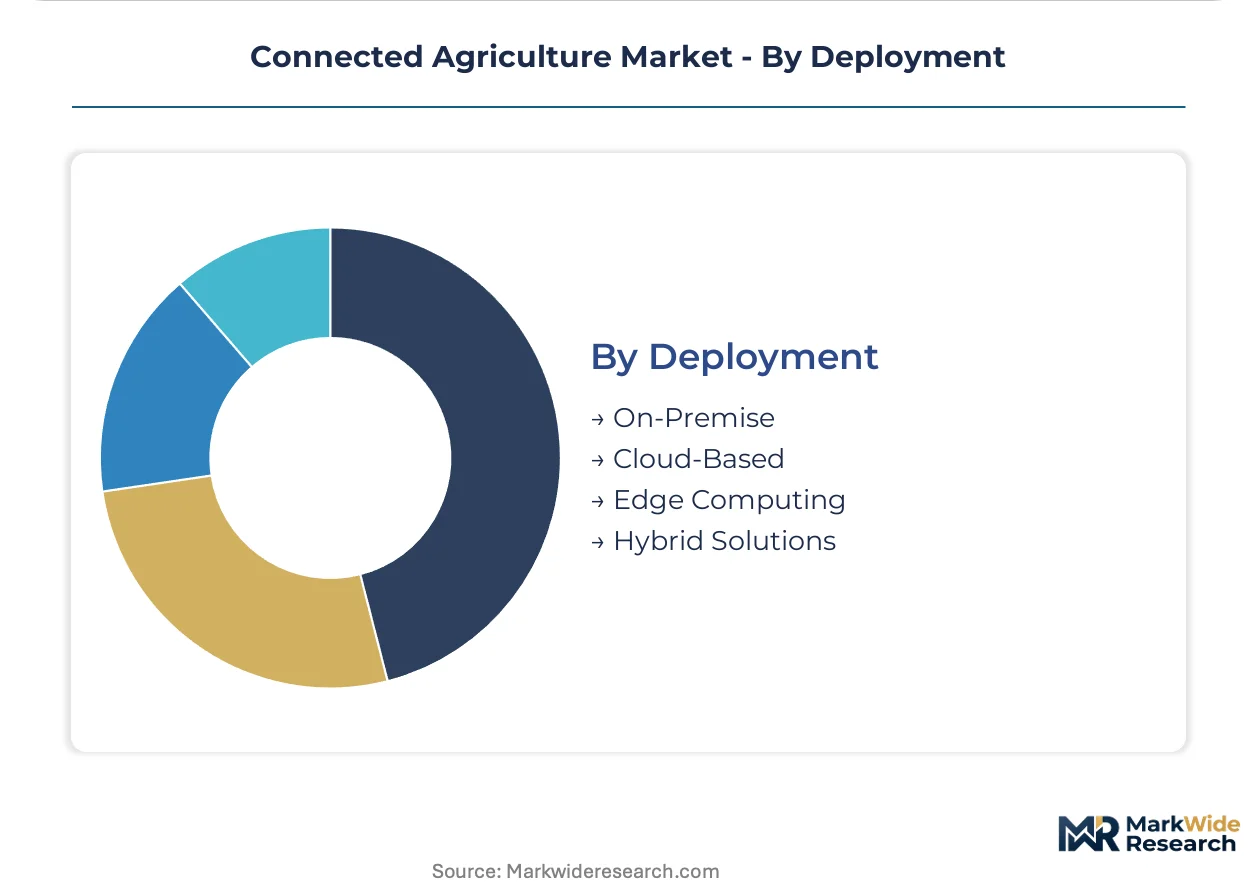
- Cloud-Based:Solutions hosted on remote servers, offering high scalability, accessibility from anywhere, and reduced upfront hardware costs for the end-user, often requiring reliable internet connectivity. Cloud-Based deployment represents the fastest-growing segment due to scalability and lower upfront costs.
- Hybrid Solutions:A combination of on-premise and cloud-based components, balancing data control and security with the flexibility and scalability of cloud services. These solutions appeal to large agribusinesses in Canada, seeking optimized performance and data management.
- On-Premise:Software and hardware installed directly on the farm, providing maximum data control and security but requiring significant upfront investment and local IT management.
- Edge Computing:Processing data closer to the source (e.g., on the farm equipment itself) to enable real-time decision-making and reduce reliance on constant cloud connectivity, crucial for rural areas with limited broadband.
Initial deployments favor On-Premise, but market penetration for Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for connected agriculture solutions concentrates in the agricultural heartlands of the United States and Brazil. Large farms in these regions actively seek operational efficiencies through technology integration. This focus on efficiency drives significant investment and technology adoption.
United States
Agribusinesses in the United States drive demand for precision farming applications to enhance operational efficiencies. USDA grant programs directly influence technology adoption rates across various farm sizes. The Midwest agricultural belt sees concentrated investment in IoT devices for comprehensive data integration.
Brazil
Brazilian farmers seek to optimize fertilizer and water use to manage high input costs effectively. New privacy laws in Brazil shape how farm data is collected and shared, impacting technology providers. Mato Grosso, a major agricultural state, shows strong investment in specialized sensors for localized data.
Australia
Large farm operators in Australia invest in connected systems to manage labor shortages and mitigate climate volatility. National agricultural policies support technology adoption to boost productivity and sustainability across vast landholdings. New South Wales agribusinesses lead the adoption of autonomous farm equipment for repetitive field tasks.
France
Farmers in France demonstrate significant expansion in connected agriculture, driven by EU Common Agricultural Policy incentives. The CAP's eco-schemes financially reward farmers for adopting precision technologies and sustainable practices. The Brittany region sees increased investment in sensor networks for reduced input waste.
Germany
German farmers adopt connected technologies primarily for crop monitoring, driven by stringent environmental regulations. The EU's Farm to Fork Strategy influences technology investments to meet targets for reduced pesticide use. Bavaria, a key agricultural state, focuses on variable rate application technology to optimize resource deployment.
Connected Agriculture Market Key Industry Players
Strategic partnerships and technology integration dominate the current landscape, as companies seek to expand their ecosystem offerings and consolidate market presence. The market structure exhibits a tiered approach, with integrated solution providers alongside specialized technology vendors. Key archetypes include hardware-centric integrators, precision GPS specialists, and open-platform developers. Portfolio diversification through software and service offerings represents a significant competitive move, aimed at capturing recurring revenue streams.
Within the integrated solution provider archetype, Deere & Company exemplifies a strategy centered on a comprehensive hardware and software ecosystem for end-to-end farm management. Precision technology specialists like Trimble occupy a position focused on advanced GPS and guidance systems for autonomous farm equipment, enhancing field accuracy. AGCO Corporation represents an open-architecture approach, offering data solutions through its FendtONE platform to farmers seeking flexible integration with existing machinery. These companies, among others, anchor the market across different segments of connected agriculture, influencing technology standards and adoption patterns for future growth.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| Raven Industries |
| Trimble |
| CNH Industrial |
| IBM Corporation |
| Microsoft Corporation |
| Cisco Systems |
| SAP |
| Others |
Cost & Logistics Intelligence
Large agribusinesses, concentrated in the United States and Brazil, increasingly favor subscription-based "Farming-as-a-Service" models. This shift reduces upfront capital outlay while securing predictable revenue streams for vendors.
Pricing Analysis
Volume-based sales of IoT devices generate lower per-unit margins, while specialized analytics platforms command premium pricing. Subscription-based "Farming-as-a-Service" (FaaS) models offer predictable revenue streams, differentiated by customization level for specific crop types and robust after-sales service bundles. Pricing softness in entry-level sensors stems from increasing competition among hardware providers. Small and medium-sized farming enterprises exhibit higher price sensitivity compared to large agribusinesses, which prioritize value-based outcomes and integrated solutions.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate the delivery of connected agriculture hardware, particularly in agricultural heartlands like the United States and Brazil. Component manufacturing for sensors and IoT devices largely concentrates in China and Germany. The sector relies on semiconductor components and specialized sensor materials, creating a structural risk from geopolitical tensions impacting supply. Distribution runs through a combination of direct sales channels from equipment OEMs and specialized ag-tech distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected agriculture market is poised for consolidation, driven by the increasing capital outlay required for advanced R&D and platform integration. This pressure forces smaller, less capitalized players to seek strategic partnerships or acquisition.
For Market Incumbents: Anchor existing customer bases through deepening hardware-software integration and expanding subscription-based service offerings. Invest heavily in R&D for AI/ML algorithms to enhance autonomous decision-making capabilities, countering the threat from emerging specialized ag-tech startups. Control the customer experience through proprietary data ecosystems, ensuring farmer loyalty against new platform entrants.
For New Entrants and Emerging Players: A price-point gap exists between premium integrated solutions and basic entry-level monitoring tools for small and medium-sized farming enterprises. Target high-value crop specialization, such as viticulture, or emerging markets in Southeast Asia with tailored, cost-effective solutions. Partner with local agricultural cooperatives to leverage existing trust and distribution networks for market penetration.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to build out comprehensive platform capabilities over the next decade. Focus on vertically integrated mid-cap specialists with strong intellectual property in AI/ML algorithms or advanced sensor technology. A critical signal to watch is the consolidation of data interoperability standards, which will unlock significant platform leadership opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unify disparate hardware and software components for seamless farm management. |
| AI/ML Algorithm Development | Enhance autonomous decision-making for precision farming applications. |
| Subscription Service Expansion | Shift revenue models towards recurring "Farming-as-a-Service" offerings. |
| Rural Connectivity Partnerships | Address infrastructure gaps in agricultural regions for broader adoption. |
| Data Interoperability Advocacy | Promote industry-wide standards to foster unified farm data dashboards. |
Research Approach
Multi-period observation of technology adoption rates and investment patterns anchored the trend analysis, supplemented by interviews with agribusiness executives, farm managers, ag-tech engineers, and government policy advisors. Secondary validation drew from USDA grant program reports, EU Common Agricultural Policy documents, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
An input-output matrix modeled market dynamics across the analysis window, integrating segmented data for technology, end-user, application, and deployment model. Compound Annual Growth Rates were derived from historical growth trends and projected market drivers. Key forecast inputs included rural broadband infrastructure development and global agricultural commodity prices.
Inputs from public financial disclosures and government agricultural surveys were available through the study window; gaps in real-time private farm-level operational data introduce uncertainty bands. Forecasts reflect assumptions regarding geopolitical stability and technology evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Qatar Agriculture Market