
 Bulgaria Facility Management Market | 2026-2036
Bulgaria Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Facility Management Market Analysis
Skilled technical labor availability is reorganizing competitive dynamics across Bulgaria's facility management sector. Mundus Services AD leverages its Sofia-centric workforce base to dominate corporate cleaning and maintenance contracts. ISS Facility Services Bulgaria sustains cross-border service protocols by aligning with multinational client standards. OKIN Facility differentiates through specialized security and access control deployments for industrial zones.
Facility management encompasses the integration of hard services such as HVAC maintenance, electrical systems upkeep, and structural repairs alongside soft services including cleaning, catering, and security operations. The discipline relies on computerized maintenance management systems to schedule preventive interventions and track asset lifecycle performance across building portfolios. Cleaning and maintenance services anchor revenue stability given their non-discretionary nature and recurring contract structures. Smart building technology represents the fastest-expanding segment as Bulgarian property owners pursue EU-funded energy efficiency upgrades. Performance-based contracts are gaining traction because they align provider incentives with measurable uptime and cost reduction outcomes.
Bulgaria's Ministry of Regional Development and Public Works enforces building energy certification requirements derived from EU directives, compelling facility operators to document consumption metrics and retrofit timelines. The country's national construction regulator mandates safety inspections and technical passport updates that directly shape maintenance scheduling and contractor qualification thresholds. Stakeholders must monitor how EU cohesion fund allocations for municipal building modernization will reshape procurement patterns and vendor selection criteria across secondary cities.
Market Dynamics
EU Energy Performance of Buildings Directive transposition is forcing Bulgarian property owners into accelerated retrofit cycles, converting compliance deadlines into sustained service demand for integrated facility management providers across Sofia, Plovdiv, and secondary industrial corridors.
Growth Catalysts
- Smart building retrofits:EU-funded energy efficiency programs are driving building automation system deployments across municipal and commercial portfolios in Bulgaria's major urban centers.
- REACH chemical compliance:Industrial cleaning and maintenance protocols must align with EU chemical safety standards, expanding specialized service contracts for hazardous material handling.
- Automotive FDI concentration:Plovdiv's electronics and vehicle assembly corridors generate recurring integrated facility services demand from multinational manufacturing tenants.
Market Restraints
- Skilled technician scarcity:Bulgaria's emigration patterns have depleted HVAC and electrical specialist pools, inflating wage costs for certified maintenance personnel.
- Equipment import dependency:Building automation hardware and smart sensor networks rely predominantly on German and Austrian supply chains, exposing operators to euro-denominated cost volatility.
- Secondary city infrastructure gaps:Municipal building stock outside Sofia and Plovdiv lacks baseline digital connectivity for IoT-enabled facility management platforms.
Strategic Opportunities
- Burgas-Varna corridor penetration:Black Sea port modernization and logistics hub development create underexploited demand for industrial security and integrated maintenance services.
- CSRD reporting alignment:Corporate sustainability disclosure requirements position facility management providers as data collection partners for Scope 1 and Scope 2 emissions verification.
- AI-driven predictive maintenance:Machine learning algorithms converging with existing CMMS platforms enable Bulgarian operators to offer uptime guarantees previously available only from Western European competitors.
Industry Challenges
- Certification timeline compression:Bulgaria's national construction regulator mandates accelerated technical passport updates, forcing contractors to absorb compliance documentation costs without proportional contract adjustments.
- Legacy system integration friction:Soviet-era building infrastructure in industrial zones requires bespoke sensor deployment and protocol bridging, complicating standardized service offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Facility Management Market |
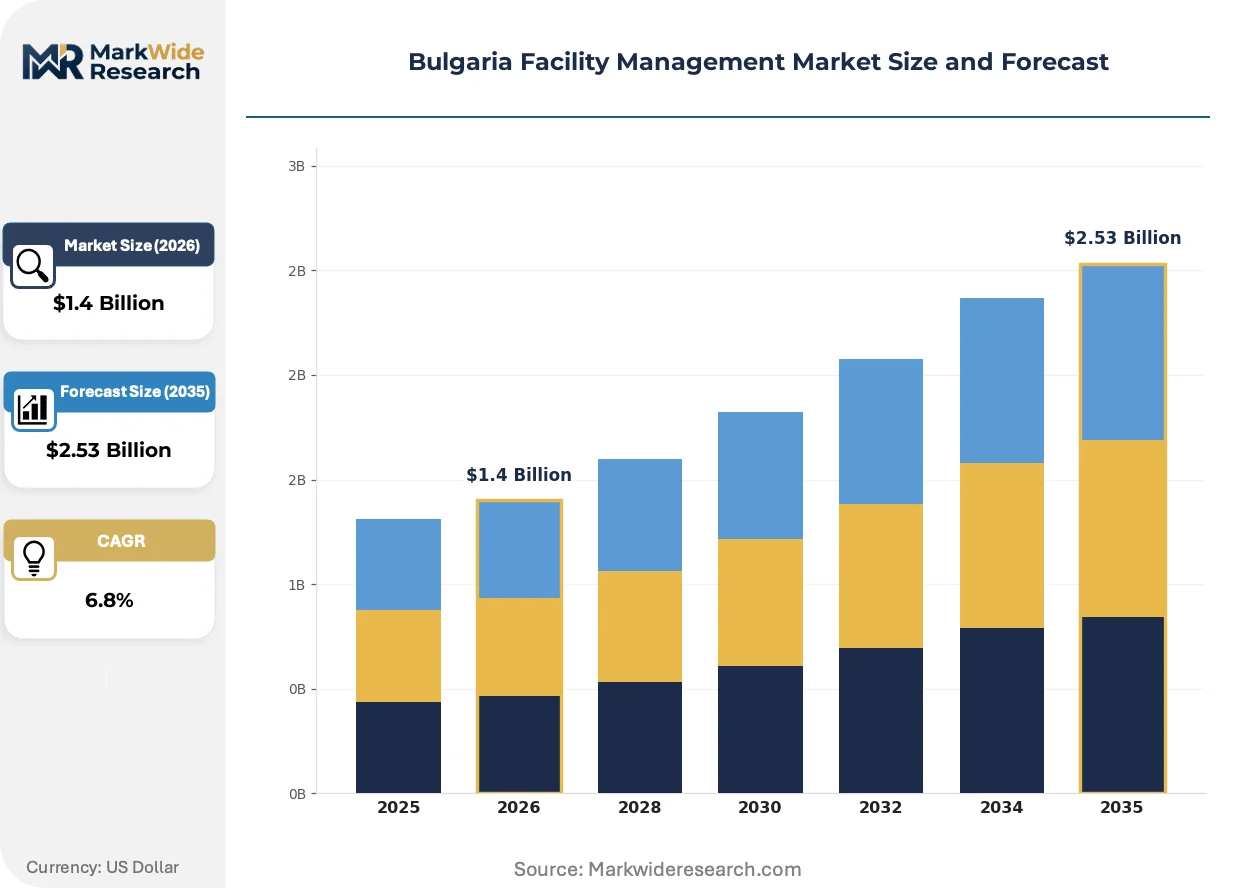
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Catering End User: Commercial, Residential, Industrial, Educational Technology: Integrated Systems, IoT Solutions, Automation, Smart Building Contract Type: Fixed-Term, Time and Materials, Performance-Based, Outsourced |
| Companies Covered | Mundus Services AD, OKIN Facility, GI Enterprise Ltd., ISS Facility Services Bulgaria, Global Facility Services Ltd., KEY Facilities Management, Landmark Property Management Jsc, Sodexo Bulgaria, First Facility Bulgaria EOOD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Facility Management Market Emerging Trajectories
Digital instrumentation of building systems is compressing reactive maintenance models across Bulgarian commercial and industrial portfolios. Facility operators are repositioning around data-centric service architectures that convert energy and occupancy metrics into recurring advisory revenue streams.
Internet of Things sensor networks are displacing scheduled inspection routines in Bulgarian manufacturing facilities. Automotive and electronics assembly plants in Plovdiv industrial zones deploy vibration analysis and thermal imaging arrays that feed real-time diagnostics to centralized maintenance dashboards. This displacement of calendar-based interventions is compressing equipment downtime windows and enabling performance-based contract structures previously uncommon in Southeastern European markets.
Bulgaria's transposition of EU Energy Performance of Buildings Directive standards mandates consumption benchmarking and retrofit roadmaps for structures exceeding specified floor area thresholds. Commercial landlords in Sofia must now document energy certificates and renovation timelines, compelling outsourced facility partnerships that bundle compliance reporting with operational maintenance. Industrial manufacturing tenants face the most aggressive certification deadlines and are consolidating vendor relationships to streamline audit documentation.
Integrated service bundling is consolidating previously fragmented procurement patterns among Bulgarian multinational tenants. Automotive and electronics assemblers increasingly specify single-contractor accountability for hard services, soft services, and energy management rather than maintaining discrete vendor relationships for cleaning, security, and HVAC maintenance. This consolidation is most visible in Plovdiv's foreign-investment manufacturing zones where global parent companies impose standardized vendor rationalization protocols on Bulgarian facility operations.
Bulgaria Facility Management Market Segmentation
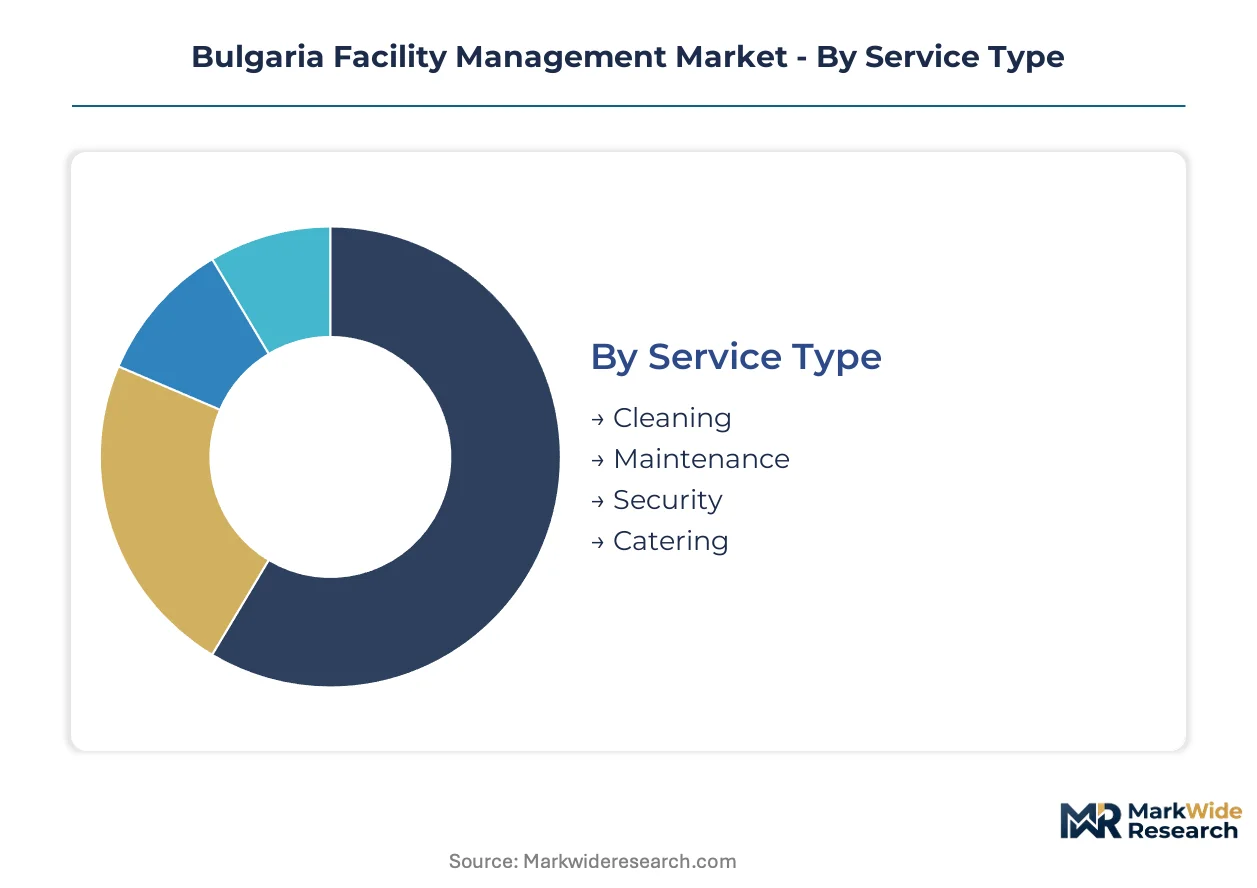
Segmentation reveals how facility management value pools fragment across service delivery models and client risk appetites in Bulgaria. Understanding these divisions exposes where contract profitability concentrates and which technology investments yield competitive separation.
Service Type:
Margin pools concentrate in specialized technical services where certification barriers limit competition, while commoditized offerings face price compression from labor cost pressures.
- Cleaning:Corporate and healthcare cleaning contracts anchor recurring revenue through standardized scope definitions and unionized workforce structures. Sofia office towers and Plovdiv manufacturing plants drive volume concentration as multinational tenants mandate ISSA certification and green chemical protocols.
- Maintenance:HVAC and electrical systems maintenance commands premium pricing due to Bulgaria's depleted technician pools and mandatory safety inspection requirements. Industrial zones around Plovdiv generate sustained demand as automotive assemblers require uptime guarantees tied to production schedules.
- Security:Access control and manned guarding services scale through industrial corridor penetration. OKIN Facility and similar operators differentiate via perimeter surveillance integration for logistics hubs.
- Catering:On-site food service contracts cluster in educational institutions and manufacturing facilities with shift-based workforce structures. EU hygiene standards and HACCP compliance create vendor qualification barriers.
The dominant share belongs to Maintenance, while Cleaning is closing the gap fastest through bundled integrated service contracts.
End User:
Volume distribution tracks foreign direct investment corridors and EU-funded public building modernization cycles.
- Commercial:Sofia office portfolios and retail centers generate standardized service demand with predictable contract renewal patterns. EU Energy Performance of Buildings Directive compliance timelines accelerate outsourced facility partnerships.
- Residential:High-rise developments in Sofia and Burgas create property management outsourcing opportunities. Smart building retrofits remain limited by homeowner association governance fragmentation.
- Industrial:Plovdiv's automotive and electronics assembly corridors concentrate demand for integrated hard and soft services. Multinational tenants impose vendor rationalization protocols that consolidate previously fragmented procurement.
- Educational:Municipal school and university facilities represent stable public sector revenue. EU cohesion fund allocations for building modernization reshape procurement patterns across secondary cities.
Industrial contracts capture the steepest expansion trajectory as manufacturing FDI deepens, though Commercial retains the largest installed base.
Technology:
Adoption velocity varies sharply between greenfield industrial deployments and legacy municipal infrastructure constraints.
- Integrated Systems:Computerized maintenance management platforms unify work order dispatch, asset tracking, and vendor coordination. Plovdiv manufacturing zones lead deployment as global parent companies mandate standardized reporting architectures.
- IoT Solutions:Sensor networks for predictive maintenance gain traction in automotive assembly plants. Vibration analysis and thermal imaging arrays feed real-time diagnostics that compress equipment downtime windows.
- Automation:Robotic cleaning and security patrol systems penetrate high-value commercial portfolios. Implementation remains constrained by Soviet-era building infrastructure requiring bespoke retrofitting.
- Smart Building:Building automation systems and energy management platforms expand through EU-funded efficiency programs. Sofia commercial landlords pursue certification compliance through bundled advisory and operational contracts.
Smart Building solutions are gaining share fastest from a low base, while Integrated Systems commands the dominant revenue position through CMMS penetration.
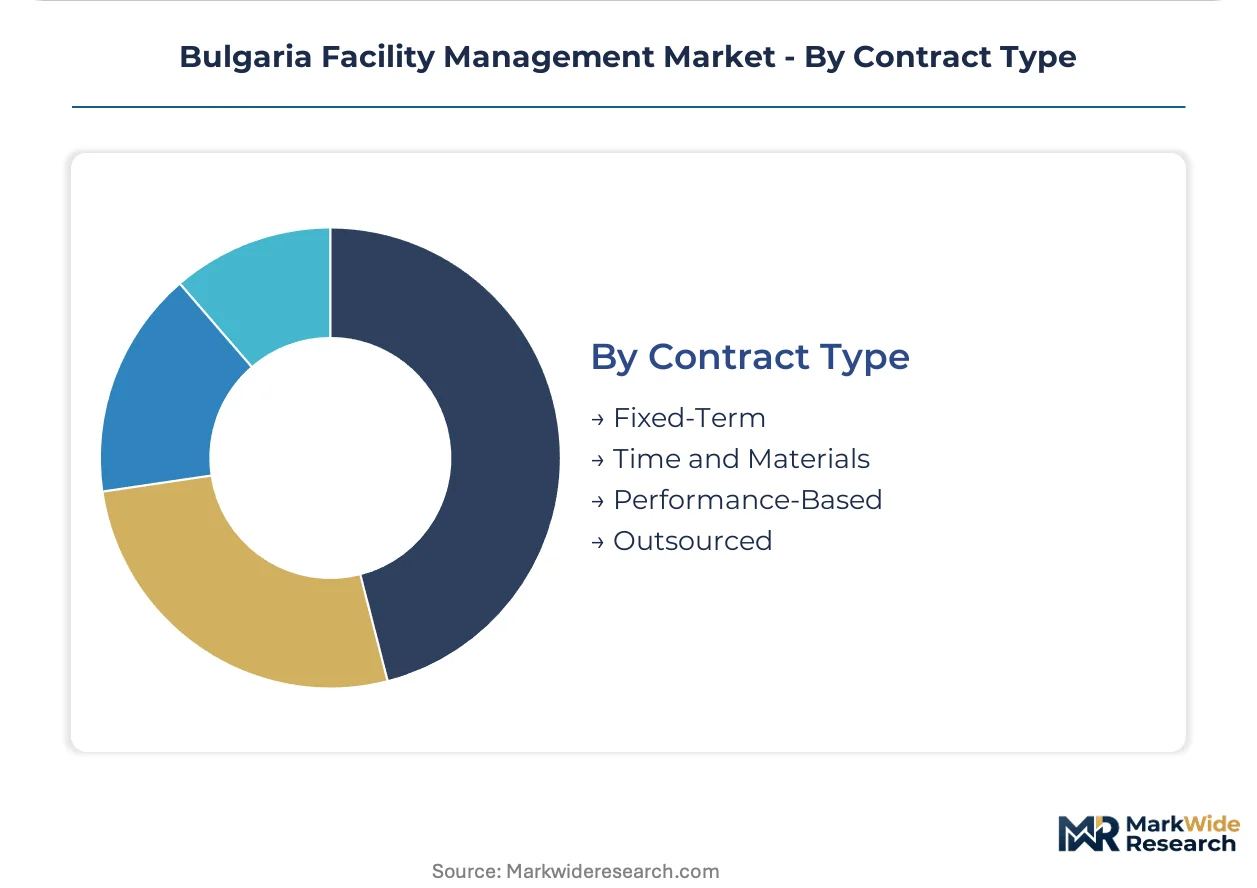
Contract Type:
Structural shift toward outcome-based pricing reconfigures provider risk exposure and client retention economics.
- Fixed-Term:Multi-year agreements with defined scope and pricing anchor revenue predictability for established operators. Municipal and educational clients favor this structure for budget certainty.
- Time and Materials:Reactive maintenance engagements persist for legacy equipment and emergency interventions. Margin volatility limits strategic priority for major facility management groups.
- Performance-Based:Uptime guarantees and cost reduction targets align provider incentives with measurable outcomes. Plovdiv industrial tenants increasingly specify KPI-linked compensation structures.
- Outsourced:Single-contractor accountability for integrated hard services, soft services, and energy management consolidates previously fragmented vendor relationships. Multinational manufacturing parents impose this structure on Bulgarian operations.
Outsourced contracts hold the dominant position, while Performance-Based structures are climbing fastest as industrial clients demand measurable accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sofia commands pricing premiums 40% above Plovdiv for equivalent integrated facility contracts, while secondary cities operate at discount structures that compress provider margins. Bulgaria's facility management market fragments across three distinct economic corridors, each shaped by foreign investment patterns and EU fund absorption capacity.
Sofia Capital Region
Corporate office towers and retail portfolios generate standardized demand for bundled hard and soft services. Bulgaria's Ministry of Regional Development enforces building energy certification deadlines that compel landlords into outsourced compliance partnerships. Business Park Sofia and Lozenets district concentrate multinational tenant clusters requiring ISSA-certified cleaning protocols and smart building retrofits.
Plovdiv Industrial Zone
Automotive and electronics assembly plants drive integrated facility services demand with uptime-linked contract structures. EU cohesion fund allocations for municipal infrastructure modernization reshape procurement patterns across the city's manufacturing corridors. Trakia Economic Zone anchors foreign direct investment concentration from German and Turkish vehicle component suppliers.
Burgas-Varna Black Sea Corridor
Port modernization and logistics hub development create underexploited demand for industrial security and predictive maintenance services. Bulgaria's national construction regulator mandates safety inspections that elevate contractor qualification thresholds for maritime-adjacent facilities. Burgas Free Trade Zone and Varna West Industrial Park attract cold storage and distribution operators requiring specialized HVAC maintenance.
Ruse-Danube North
Cross-border trade infrastructure with Romania generates demand for bilingual facility crews and EU-standard compliance documentation. REACH chemical safety protocols govern industrial cleaning contracts at river port chemical handling facilities. Ruse Free Trade Zone concentrates Bulgarian-Romanian logistics joint ventures requiring harmonized service standards.
Bulgaria Facility Management Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium providers capture compliance-heavy contracts while regional operators compete on labor arbitrage. The vendor base organizes around three strategic archetypes: integrated multinationals leveraging cross-border protocols, domestic specialists dominating geographic clusters, and diversified property groups capturing captive demand. M&A activity concentrates among mid-scale domestic operators seeking scale to meet multinational qualification thresholds. Strategic partnerships with German and Austrian equipment suppliers represent the dominant competitive move for technology access.
Among Sofia-centric operators, Mundus Services AD and ISS Facility Services Bulgaria exemplify contrasting archetypes—domestic workforce concentration versus multinational protocol alignment. OKIN Facility occupies a position within the security-specialist tier, anchoring industrial zone penetration around Plovdiv. These three patterns illustrate how competitive positioning fragments across service bundling strategies and geographic focus rather than consolidating around scale alone.
| Leading Market Players |
|---|
| Mundus Services AD |
| OKIN Facility |
| GI Enterprise Ltd. |
| ISS Facility Services Bulgaria |
| Global Facility Services Ltd. |
| KEY Facilities Management |
| Landmark Property Management Jsc |
| Sodexo Bulgaria |
| First Facility Bulgaria EOOD |
| Others |
Supply Flow & Price Mechanics
IoT sensor substitution for manual inspection routines simultaneously relocates value capture toward software-integrated service providers and compresses margin pools for labor-dependent operators across Sofia and Plovdiv contract markets. This displacement dynamic concentrates pricing power with vendors controlling German and Austrian equipment supply relationships while eroding returns for undifferentiated maintenance contractors.
Pricing Analysis
Customization-premium spreads separate performance-guaranteed industrial contracts from standardized commercial cleaning engagements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in the standard tier intensifies because Romanian and Serbian labor arbitrage exerts downward pressure on cross-border service bids. Multinational manufacturing tenants in Trakia Economic Zone exhibit lowest price sensitivity, while municipal educational clients face strict budget ceilings that amplify procurement friction.
Supply Chain Analysis
Danube River transit chokepoints through Ruse elevate logistics costs for HVAC components and building automation hardware sourced from German industrial clusters. Equipment procurement draws from Austria, Germany, and Czech Republic manufacturing bases for smart sensors and CMMS platforms. Single-source vulnerability concentrates in Siemens and Honeywell distribution networks serving Bulgarian industrial zones. Distribution runs through Sofia-based integrators who bundle hardware installation with recurring software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against in-house facility management substitution as multinational tenants consolidate vendor relationships and develop captive technical capabilities. The substitution threat intensifies where global parent companies impose standardized protocols that reduce outsourcing dependency.
For Market Incumbents: Secure technician certification pipelines through Bulgarian-German vocational partnerships to counter emigration-driven skill scarcity. Anchor long-term contracts with performance-based KPI structures that embed switching costs. Vertical integration into energy advisory services creates defensive moats against pure-play maintenance competitors.
For New Entrants and Emerging Players: Differentiate on AI-driven predictive maintenance capabilities that compress downtime windows below incumbent benchmarks. Target Burgas-Varna corridor logistics hubs where industrial security and cold storage maintenance demand outpaces qualified supply. Lead with CSRD compliance data partnerships that position facility operators as Scope 1 and Scope 2 verification allies.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scale-oriented acquirers with cross-border protocol capabilities. Long-term viability hinges on EU fund absorption capacity and technician training infrastructure deployment. Acquisition target archetype: mid-scale domestic operators with Sofia-Plovdiv geographic coverage and pending multinational qualification thresholds. Watch EU cohesion fund allocation velocity as inflection indicator for municipal contract pipeline expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | German-Bulgarian vocational partnerships address HVAC specialist scarcity constraining contract scalability. |
| Performance-Based Contract Structuring | KPI-linked compensation aligns provider incentives with uptime guarantees demanded by Plovdiv automotive assemblers. |
| Smart Building Retrofit Bundling | EU Energy Performance of Buildings Directive compliance creates recurring advisory revenue alongside operational maintenance. |
| CSRD Reporting Alignment | Corporate sustainability disclosure requirements position facility operators as emissions verification data partners. |
| Burgas-Varna Corridor Expansion | Black Sea port modernization generates underexploited demand for industrial security and predictive maintenance services. |
Methodological Framework
The analysis maps hard services, soft services, smart building technology, and contract type segments, each validated through facility directors, procurement officers at multinational manufacturing tenants, municipal building managers, and CMMS platform vendors. Primary interviews with maintenance directors and industrial zone operators combined with secondary validation against EU cohesion fund disbursement records, national construction regulator technical passport databases, and trade data from German-Austrian equipment exporters. Bottom-up contract value aggregation and top-down EU fund allocation modeling enabled triangulation across independent estimation approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, end-user industry, technology adoption tier, and contract structure complexity. CAGRs derived from historical fund absorption patterns and FDI inflow trajectories, with specific inputs from automotive sector facility expansion timelines and building certification deadline schedules.
Material uncertainties — EU fund reallocation, technician emigration acceleration, and multinational captive facility management decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and FDI corridor stability. Practitioners should keep alternative scenarios live as EU Green Deal implementation intensity and German industrial investment patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Nigeria Facility Management Services Market
Facility Management
Facility Management Services Market
Facility Management
Singapore Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
GCC Facility Management Market
Facility Management
Soft Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Italy Facility Management Services Market
Facility Management
Poland Facility Management Market