
 Colostrum Chewable Tablets Market | 2026-2036
Colostrum Chewable Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
Colostrum Chewable Tablets Market Insights
Athletes and fitness enthusiasts is realigning demand profiles within the colostrum chewable tablets space, pulling formulation standards toward higher immunoglobulin concentrations. Glanbia plc leverages its dairy-derived ingredient heritage to anchor premium supply positions across North American sports nutrition channels. Biotaris B.V. specializes in cold-processed colostrum extraction, sustaining bioactive protein integrity through its Dutch manufacturing footprint. Xiuzheng competes aggressively on volume scale, dominating pharmacy shelf presence across multiple Chinese provinces.
Colostrum chewable tablets deliver concentrated bovine first-milk immunoglobulins, lactoferrin, and growth factors in a stabilized oral-delivery format, typically standardized to minimum IgG thresholds between 15% and 30% by weight. The manufacturing process demands low-temperature spray drying or freeze-drying to preserve peptide bioactivity, followed by direct compression or wet granulation into chewable matrices with binders and flavor masking agents. Among end user segments, athletes command premium pricing due to performance-recovery positioning, while children represents the fastest-growing consumption pool as parental preference shifts toward natural immune support alternatives. Natural product type currently occupies the largest volume share, though fortified variants are gaining shelf space as brands differentiate through added vitamin D or zinc complexes.
FDA CGMP rules for dietary supplements govern manufacturing quality and adverse event reporting for US-bound products, while EFSA novel food assessments constrain entry pathways for innovative colostrum derivatives across European Union markets. China's SAMR and NMPA jointly oversee health food blue-hat registration, creating a dual-track compliance burden for brands seeking pharmacy and direct-sales channels simultaneously. India's FSSAI has tightened bovine-source documentation requirements following broader food safety audits, extending clearance timelines for imported colostrum inputs. Stakeholders must monitor evolving immunoglobulin potency labeling standards and country-of-origin disclosure mandates as these determine competitive access and consumer trust architecture across priority markets.
Market Dynamics
FDA CGMP enforcement on raw material traceability is compressing supplier qualification timelines and forcing manufacturers toward captive colostrum sourcing or vertically integrated dairy partnerships.
Growth Catalysts
- Sports nutrition protocol adoption:Collegiate athletic programs now standardize colostrum chewables for post-training immune recovery, creating institutional procurement pipelines that bypass retail channel volatility.
- EFSA novel food pathways:Streamlined assessments for bovine-derived ingredients accelerate European market entry for standardized IgG formulations above 20% concentration thresholds.
- Cold-processed extraction methods:Low-temperature spray drying preserves lactoferrin bioactivity, enabling premium positioning against heat-degraded commodity alternatives.
Market Restraints
- Bovine source documentation burden:India's FSSAI now mandates three-year herd health records for imported colostrum inputs, extending clearance timelines by 4-6 months.
- Freeze-drying capex concentration:Capital equipment for bioactive preservation concentrates production among dairy cooperatives with existing lyophilization infrastructure.
- Plant-based protein substitution:Fermented immunoglobulin analogs from precision fermentation startups threaten premium positioning in vegan-aligned consumer segments.
Strategic Opportunities
- Pediatric immune support white space:Parental preference for natural alternatives to pediatric OTC antihistamines drives pharmacy channel expansion for flavored, low-dose formats.
- China health food blue-hat registration:Dual-track SAMR-NMPA compliance creates defensive moats for first movers securing pharmacy shelf presence across Jiangsu and Zhejiang provinces.
- Vitamin D fortification convergence:Combining colostrum immunoglobulins with cholecalciferol addresses seasonal deficiency patterns in Northern European markets.
Industry Challenges
- Peptide stability validation talent gap:Analytical chemists capable of IgG degradation kinetics modeling command premium compensation, constraining mid-tier manufacturer QC expansion.
- Flavor masking formulation complexity:Bovine colostrum's native lipid profile requires multi-layer coating technologies to achieve palatability thresholds in children's formats without sugar alcohol overloading.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colostrum Chewable Tablets Market |
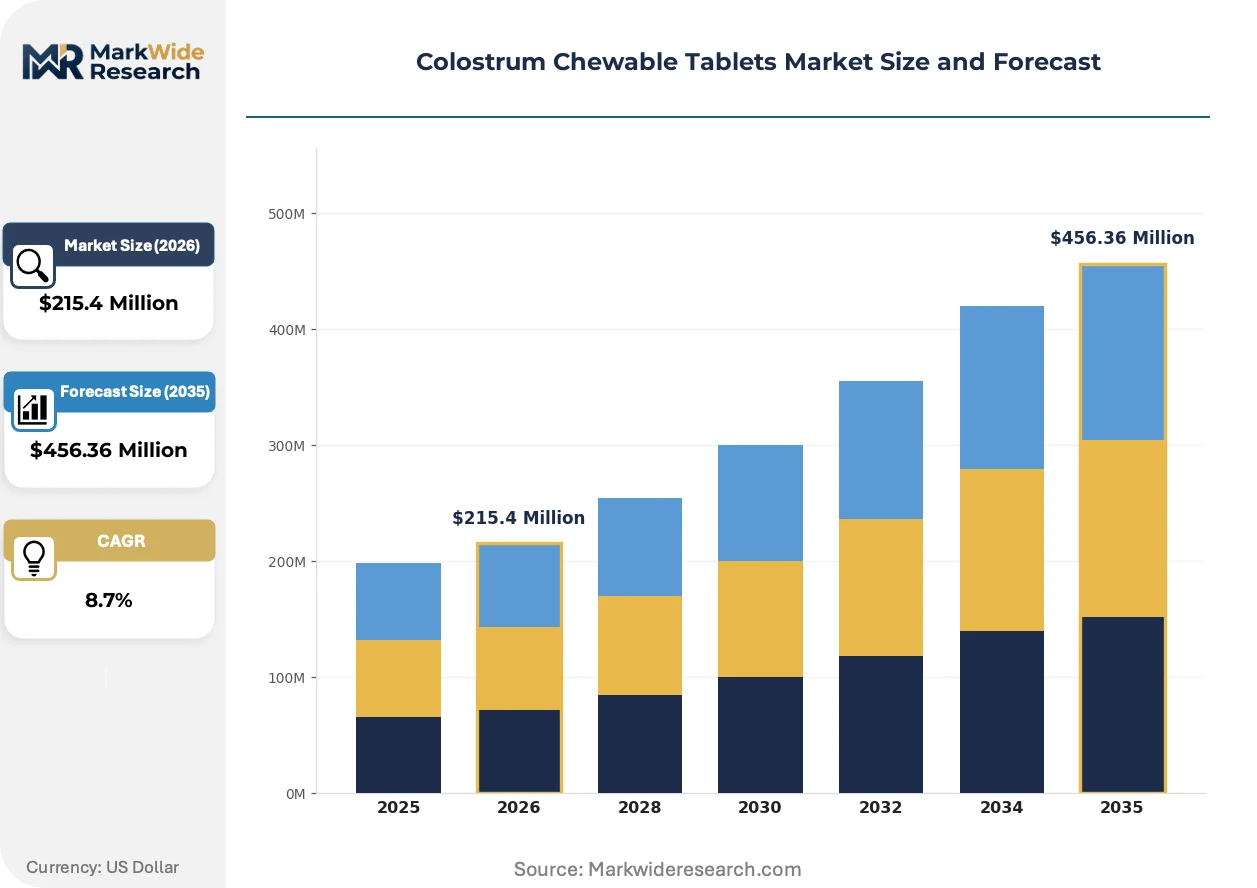
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $456.36 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Organic, Fortified, Flavored End User: Children, Adults, Seniors, Athletes Distribution Channel: Online, Pharmacies, Health Stores, Supermarkets Formulation: Tablet, Powder, Liquid, Granule |
| Companies Covered | BYHEALTH, HealthBank, Xiuzheng, Renhe, GOOD HEALTH, K-MAX, Glanbia plc, Agati Healthcare, Biotaris B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colostrum Chewable Tablets Market Trends and Innovations
Manufacturing technology and regulatory transparency requirements are compressing traditional supply relationships while opening premium tier positions for verified bioactive preservation.
Freeze-drying is overtaking conventional spray drying for immunoglobulin retention above 25% IgG thresholds. Sports nutrition contract manufacturers in the United States now specify lyophilized colostrum for elite athlete protocols. This preservation technology is overtaking heat-based methods in premium segment procurement specifications, compressing commodity supplier margins.
China's SAMR has tightened health food label claims verification for immunoglobulin content declarations. Manufacturers must now submit third-party HPLC potency certificates prior to blue-hat registration approval. Pediatric-focused brands targeting Shanghai and Beijing pharmacy chains are responding by building in-house analytical laboratories rather than relying on supplier certificates.
Direct-to-athlete subscription models are displacing traditional sports nutrition retail distribution. Collegiate programs and professional training facilities now procure through institutional purchasing cooperatives that aggregate volume across multiple teams. This channel consolidation is most visible in Germany, where pharmacy chains simultaneously merchandise colostrum alongside conventional probiotics, creating dual-track access points.
Colostrum Chewable Tablets Market Segmentation
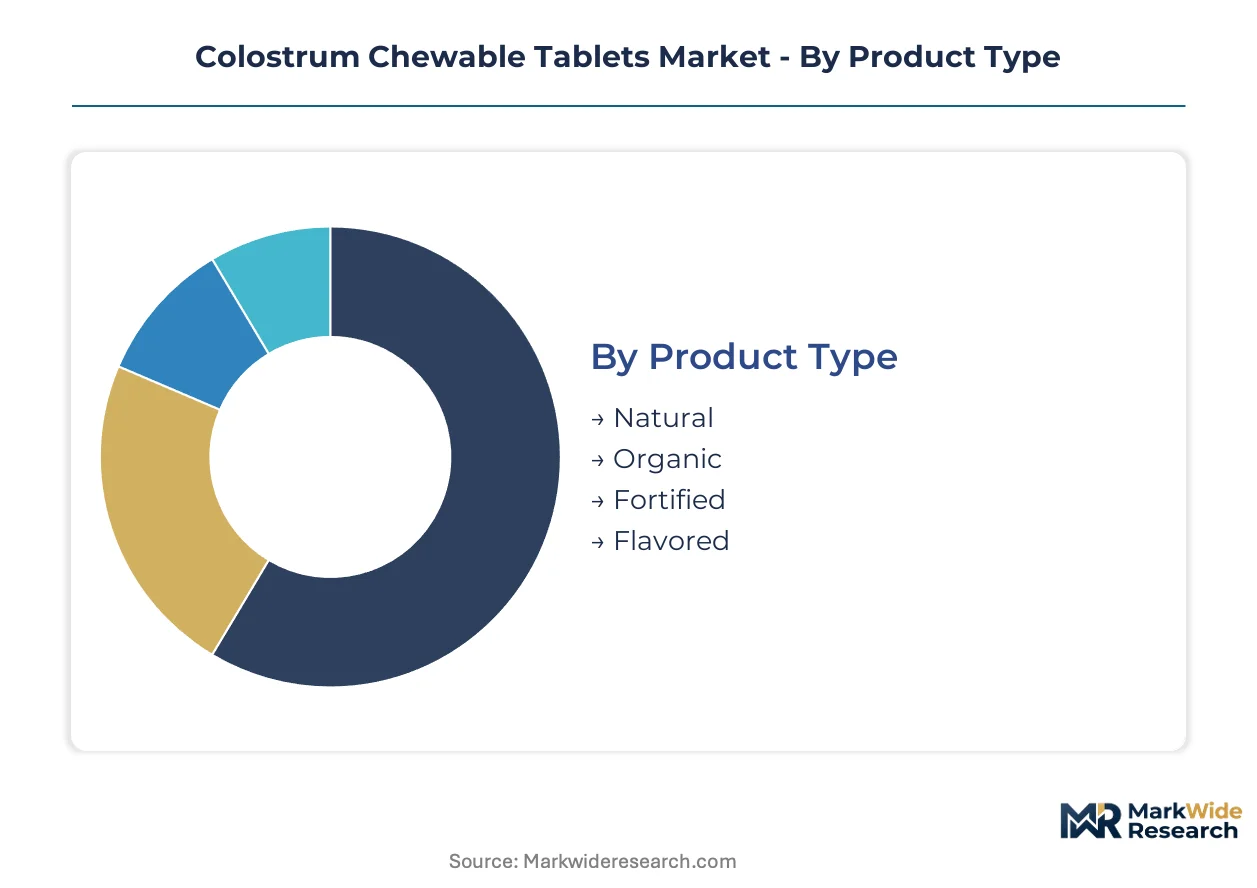
Colostrum chewable tablets fragment across four distinct category axes, each shaping procurement patterns and margin structures differently. Product type and end user concentration determine formulation investment priorities, while distribution channel dynamics govern geographic expansion sequencing for new entrants.
Product Type:
Supply concentration around cold-processed extraction infrastructure favors producers with captive dairy partnerships or lyophilization capabilities.
- Natural:Unmodified bovine colostrum standardized to 15-30% IgG content without synthetic additives. Demand concentrates in Germany's pharmacy chains where consumers prioritize ingredient minimalism alongside proven immunoglobulin thresholds.
- Fortified:Base colostrum matrix enhanced with cholecalciferol, zinc complexes, or additional lactoferrin isolates. Sports nutrition departments at US collegiate athletic programs drive procurement for post-training immune recovery protocols requiring stacked bioactive delivery.
- Organic:Sourced from certified grass-fed herds with full veterinary traceability documentation. Appeals to parental segments seeking pediatric immune alternatives with verified hormone-free credentials.
- Flavored:Incorporates natural masking agents to offset native lipid bitterness in children's formats. Requires multi-layer coating technologies to achieve palatability without excessive sugar alcohol loading.
Today's leader: Natural. Tomorrow's challenger: Fortified.
End User:
Premium pricing power clusters around performance-recovery positioning, while volume scale concentrates in household purchasing decisions for developmental immune support.
- Athletes:Elite competitors and collegiate programs command premium formulations with IgG thresholds above 25%, validated through third-party HPLC potency certificates. Institutional procurement pipelines now bypass retail channel volatility through direct purchasing cooperatives.
- Children:Parental preference shifts toward natural immune support alternatives drive pharmacy channel expansion across Chinese provinces. SAMR blue-hat registration requirements create defensive moats for first movers in Jiangsu and Zhejiang.
- Adults:General wellness consumers seeking preventive immune maintenance represent stable baseline demand with moderate price elasticity.
- Seniors:Age-related immune function concerns propel interest in lactoferrin-rich formulations, though flavor masking challenges complicate adherence in this segment.
Athletes extract maximum margin per unit. Children are climbing the fastest.
Distribution Channel:
Channel consolidation is compressing traditional retail relationships while opening premium tier positions for verified bioactive preservation through institutional procurement.
- Pharmacies:German pharmacy chains actively merchandise colostrum alongside conventional probiotics, creating dual-track access points for discerning consumers. China's health food blue-hat registration mandates determine shelf presence eligibility.
- Online:Direct-to-athlete subscription models displace traditional sports nutrition retail distribution, aggregating volume across collegiate programs and professional training facilities through institutional purchasing cooperatives.
- Health Stores:Natural product retailers serve educated consumers prioritizing cold-processed extraction credentials and transparent IgG labeling.
- Supermarkets:Mass-market penetration remains limited due to temperature-controlled storage requirements and premium positioning constraints.
Pharmacies anchor current revenue. Online is gaining share fastest.
Formulation:
Manufacturing technology requirements fragment competitive access based on capital equipment for bioactive preservation.
- Tablet:Direct compression or wet granulation into chewable matrices with binders and flavor masking agents. Freeze-drying capex concentration limits viable producers to dairy cooperatives with existing lyophilization infrastructure.
- Powder:Loose colostrum for flexible dosing in smoothie or beverage applications, appealing to adult wellness segments comfortable with self-measurement.
- Liquid:Ready-to-consume formats with shorter shelf stability, requiring cold chain logistics that constrain geographic reach.
- Granule:Dissolvable particles offering faster absorption kinetics, positioned in Asian markets accustomed to traditional medicine delivery formats.
Tablets dominate current manufacturing investment. Granule shows steepest expansion trajectory in Asia-Pacific adoption patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined dairy-derived ingredient approvals and lower compliance-cost burdens. Cost-of-compliance gaps between established pharmaceutical markets and emerging health-food corridors now determine where cold-processing capacity concentrates.
United States
FDA CGMP enforcement on raw material traceability is compressing supplier qualification timelines for bovine-sourced inputs. Collegiate athletic programs in Texas and California now standardize colostrum chewables for post-training immune recovery, creating institutional procurement pipelines. Sports nutrition contract manufacturers in the Denver-Boulder corridor specify lyophilized colostrum for elite athlete protocols.
Germany
EFSA novel food assessments for standardized IgG formulations above 20% concentration thresholds are accelerating European market entry pathways. Pharmacy chains in Munich and Hamburg actively merchandise colostrum products alongside conventional probiotics, creating dual-track consumer access points. Bavarian dairy cooperatives with existing freeze-drying infrastructure dominate premium-tier supply positions.
China
SAMR and NMPA joint oversight of health food blue-hat registration creates dual-track compliance burdens for pharmacy and direct-sales channels. Parental preference for natural pediatric immune alternatives drives pharmacy expansion across Jiangsu and Zhejiang provinces. Shanghai-based manufacturers are building in-house analytical laboratories to meet tightened label claims verification requirements.
India
FSSAI mandates for three-year herd health records on imported colostrum inputs extend clearance timelines by 4-6 months, constraining supply velocity. Demand for developmental immune support concentrates in Maharashtra and Gujarat pharmacy networks. Mumbai-based distributors are qualifying domestic dairy partnerships to bypass documentation burdens on foreign-sourced material.
Netherlands
Cold-processed extraction specialists leverage Dutch dairy heritage and lyophilization infrastructure to sustain bioactive protein integrity. EFSA regulatory clarity on bovine-derived ingredients positions Rotterdam-Amsterdam corridor manufacturers as preferred suppliers for EU-bound premium formulations. Biotech clusters in Leiden and Wageningen are developing peptide stability validation capabilities for third-party potency certification.
Colostrum Chewable Tablets Market Competitive Landscape
Backward integration into captive colostrum sourcing dominates the current landscape as manufacturers seek to compress supplier qualification timelines and secure immunoglobulin supply continuity. The vendor base stratifies across three tiers: dairy-derived ingredient heritage players with lyophilization assets, regional pharmacy-channel specialists with health-food registration expertise, and volume-scale contract manufacturers serving mass-market shelf presence. Two strategic archetypes now command disproportionate positioning: cold-processing technology specialists and regulatory-first movers with dual-track SAMR-NMPA compliance capabilities. Competitive intensity concentrates on M&A activity targeting freeze-drying infrastructure and strategic partnerships with collegiate athletic procurement cooperatives.
Among dairy-ingredient heritage players, Glanbia plc anchors premium supply positions across North American sports nutrition channels through its established bovine-derived ingredient footprint. Biotaris B.V. exemplifies the cold-processing technology archetype, sustaining bioactive protein integrity through Dutch manufacturing infrastructure with low-temperature extraction capabilities. Xiuzheng occupies the volume-scale end, dominating pharmacy shelf presence across multiple Chinese provinces through aggressive health-food registration strategies and manufacturing scale. These three represent distinct competitive vectors: heritage supply relationships, processing technology differentiation, and regulatory-first market penetration.
| Leading Market Players |
|---|
| BYHEALTH |
| HealthBank |
| Xiuzheng |
| Renhe |
| GOOD HEALTH |
| K-MAX |
| Glanbia plc |
| Agati Healthcare |
| Biotaris B.V. |
| Others |
Pricing and Supply Chain Analysis
Captive colostrum sourcing through vertically integrated dairy partnerships anchors both supply security and premium pricing power for manufacturers navigating FDA CGMP traceability mandates. This integration choice compresses supplier qualification timelines while insulating first movers from raw material volatility that erodes margin positions in commodity-dependent tiers.
Pricing Analysis
Pharmacy retail markup layers stratify end-user pricing across three distinct tiers tied to immunoglobulin certification thresholds. Premium formulations commanding athlete segment loyalty carry 25-30% IgG validation premiums against standard 15-20% pharmacy-grade alternatives, while economy-positioned natural products compete on volume scale with minimal potency disclosure. Pricing pressure intensifies in children's formats where flavor masking R&D costs compound with SAMR blue-hat registration fees, squeezing mid-tier brand margins. Institutional procurement cooperatives for collegiate athletic programs exhibit lowest price sensitivity, prioritizing batch-certified bioactivity over per-unit cost.
Supply Chain Analysis
Raw colostrum feedstock rests on dairy cooperative networks concentrated across the Netherlands, Germany, and New Zealand, with Bavarian and Dutch producers dominating cold-processing infrastructure for premium IgG retention. Bovine first-milk collection, low-temperature lyophilization equipment, and HPLC potency validation laboratories constitute the three critical input dependencies. Single-source vulnerability concentrates around freeze-drying capex, where existing dairy cooperative assets create entry barriers for new processing capacity. Distribution runs through dual pharmacy-direct channels in Germany, online subscription platforms for US athletic programs, and SAMR-registered pharmacy chains across Chinese provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA CGMP enforcement on raw material traceability simultaneously elevates compliance costs and consolidates pricing power among verified suppliers.
For Market Incumbents: Deepen captive dairy partnerships in the Netherlands and Bavaria to secure lyophilization capacity ahead of competitor qualification timelines. Fortify in-house analytical laboratories for IgG degradation kinetics validation, addressing the peptide stability talent gap that constrains mid-tier QC expansion. Prioritize SAMR-NMPA dual-track registration completion in Jiangsu and Zhejiang provinces before secondary entrants secure pharmacy shelf moats. For New Entrants and Emerging Players: Launch via direct-to-athlete subscription models aggregating collegiate procurement cooperatives, bypassing entrenched retail relationships that incumbent brands dominate. Target pediatric immune support white space in Chinese pharmacy channels where parental preference shifts create penetrable demand pools. Pursue precision fermentation partnerships to develop immunoglobulin analogs threatening vegan-aligned consumer segments. For Investors and Strategic Acquirers: Roll-up economics work for cold-processing technology specialists because freeze-drying capex concentration limits viable independent producers to dairy cooperatives with existing infrastructure. Over the projection horizon, vertically integrated manufacturers with captive sourcing and analytical validation capabilities present durable margin structures. Monitor EFSA novel food pathway acceleration for standardized IgG formulations above 20% thresholds as the inflection signal for European premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Bavarian dairy cooperatives with lyophilization assets capture premium IgG retention contracts from US sports nutrition manufacturers. |
| SAMR Blue-Hat Registration Completion | First movers securing pharmacy shelf presence across Jiangsu and Zhejiang provinces build defensive moats against delayed entrants. |
| Direct-to-Athlete Subscription Launch | Institutional procurement cooperatives for collegiate programs bypass retail channel volatility and aggregate volume across multiple teams. |
| In-House Analytical Laboratory Buildout | Shanghai-based manufacturers meet tightened SAMR label claims verification without supplier certificate dependency. |
| Pediatric Flavor Masking R&D Investment | Multi-layer coating technologies achieve palatability thresholds without sugar alcohol overloading in children's formats. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with sports nutrition procurement directors, pharmacy chain category managers, dairy cooperative operations heads, and SAMR registration consultants combined with secondary validation from FDA CGMP enforcement records, EFSA novel food assessment databases, and Chinese health food blue-hat registration filings. Trade data from customs authorities and pharmaceutical distribution audits provided supply-side triangulation against demand estimates from institutional purchasing cooperatives and direct-to-consumer channel analytics.
Input-output matrices mapped colostrum raw material flows through lyophilization capacity, potency validation stages, and channel-specific markup layers across the projection horizon. Segmentation dimensions included product type tiers, end-user archetypes, distribution channel structures, and geographic regulatory clusters. CAGRs derived from historical volume trajectories adjusted for enforcement-driven supplier consolidation and cold-processing technology adoption curves. Forecast inputs incorporated collegiate athletic program procurement standardization timelines and parental preference shift velocities in pediatric immune support categories.
Several conditions sit outside the modeled scope, including precision fermentation immunoglobulin analog commercialization timelines and potential FSSAI herd health record requirement extensions beyond current three-year mandates. Forecasts reflect documented assumptions about regulatory enforcement continuity and bioactive preservation technology cost curves. A small set of named triggers warrants ongoing watch: EFSA novel food pathway streamlining velocity, SAMR label claims verification tightening scope, and freeze-drying equipment manufacturer order backlogs as capacity expansion indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Medicated Confectionery Market