
 Nootropic Products Market | 2026-2036
Nootropic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Nootropic Products Market Outlook
Precision fermentation and biosynthetic manufacturing is fragmenting traditional supply chains for cholinergic and racetam compounds, enabling smaller batch producers to compete on purity and customization. Onnit Labs leverages vertically integrated content-to-commerce ecosystems that anchor brand loyalty in subscription models. Nootropics Depot competes on third-party Certificate of Analysis transparency for synthetic compounds. Reckitt Benckiser Group PLC sustains mass-market shelf presence through pharmacy and big-box retail channel control.
Nootropic products encompass dietary supplements and functional compounds formulated to modulate neurotransmitter activity, enhance cerebral blood flow, or support neuroplasticity through mechanisms involving acetylcholine, dopamine, or glutamate receptor pathways; these formulations typically specify active ingredient concentrations measured in milligram doses and are manufactured via either extraction from botanical sources or chemical synthesis in GMP-certified facilities. Natural Supplements leads volume due to consumer preference for plant-derived ingredients with established safety profiles, while Synthetic Compounds captures premium pricing from biohackers seeking precise dose-to-response calibration. Memory Enhancement applications dominate clinical positioning, though Focus Improvement segments among technology professionals are expanding fastest in direct-to-consumer channels.
The US FDA exercises oversight through DSHEA enforcement and Good Manufacturing Practice inspections, while the FTC monitors cognitive health advertising claims for substantiation. The EU EFSA maintains stricter novel food and health claim assessments that limit product positioning in European markets. Stakeholders must monitor how evolving pharmacovigilance frameworks distinguish between dietary supplement and drug classifications, as this boundary determination will reshape market access requirements and reformulation investments.
Market Dynamics
Precision fermentation and biosynthetic manufacturing are fragmenting traditional supply chains for cholinergic and racetam compounds, enabling smaller batch producers to compete on purity and customization while compressing legacy extraction economics.
Growth Catalysts
- DSHEA Enforcement Modernization:The FDA's tightening Good Manufacturing Practice inspections are forcing quality verification investments that elevate compliant manufacturers above gray-market competitors in the United States.
- Tech-Sector Biohacker Demand:Silicon Valley engineers and quantified-self practitioners are driving direct-to-consumer volume for synthetic racetams with precise dose-to-response calibration requirements.
- Neuroplasticity Research:Academic validation of acetylcholine receptor modulation mechanisms is legitimizing clinical positioning for memory enhancement formulations among aging demographics.
Market Restraints
- Botanical Input Volatility:Bacopa monnieri and Ginkgo biloba extract prices fluctuate with monsoon-dependent Indian and Chinese agricultural yields, squeezing margin stability for natural supplement lines.
- Synthetic Precursor Concentration:Pharmaceutical-grade aniracetam and oxiracetam precursor synthesis concentrates in Zhejiang and Jiangsu province facilities, creating single-geography supply vulnerability.
- EU Novel Food Assessment Friction:EFSA's stringent health claim substantiation requirements block rapid product launches that succeed in less regulated jurisdictions, capping European addressable market expansion.
Strategic Opportunities
- Subscription Commerce Penetration:Vertically integrated content-to-commerce ecosystems that anchor brand loyalty through personalized dosing protocols and community education platforms remain underdeveloped outside the United States.
- Professional Sports Neuroprotection:Esports organizations and traditional athletics programs are exploring cognitive recovery formulations as distinct from acute performance enhancers, opening B2B institutional channels.
- Precision Fermentation Scale Economics:Biosynthetic production of citicoline and alpha-GPC is virtualizing batch economics previously gated by botanical extraction minimums, enabling regional micro-facility deployment.
Industry Challenges
- Certificate of Analysis Talent Scarcity:Third-party analytical chemistry verification capacity for synthetic nootropic purity testing latches behind formulation innovation velocity, creating quality assurance bottlenecks.
- Regulatory Classification Ambiguity:Evolving pharmacovigilance frameworks that distinguish dietary supplement from drug boundaries force parallel compliance pathway investments without certainty on final classification outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nootropic Products Market |
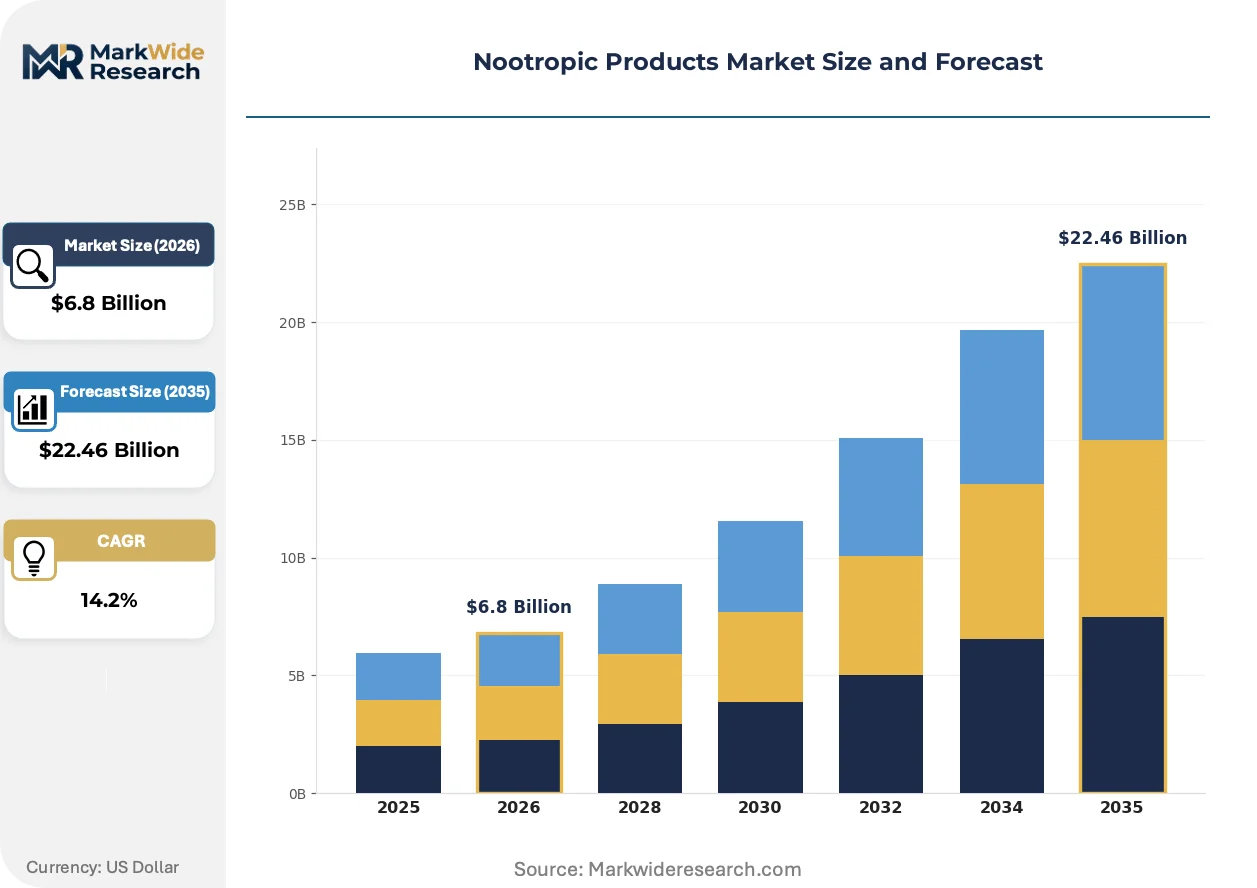
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Racetams, Cholinergics, Natural Supplements, Synthetic Compounds Application: Memory Enhancement, Cognitive Function, Focus Improvement, Mood Enhancement End User: Students, Professionals, Athletes, Seniors Distribution Channel: Online Retailers, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | Onnit Labs, Reckitt Benckiser Group PLC, Nootropics Depot, Amway, TruBrain, Natural Stacks, Mind Lab Pro, GNC Holdings, Qualia Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nootropic Products Market Strategic Shifts
Biosynthetic manufacturing and personalized dosing protocols are compressing traditional extraction economics while regulatory scrutiny intensifies on cognitive health substantiation claims across major jurisdictions.
Precision fermentation for cholinergic compound production is virtualizing the capital requirements that previously gated entry into synthetic nootropic manufacturing. Biohackers and tech-sector professionals are adopting biosynthetically derived citicoline and alpha-GPC at accelerating rates through direct-to-consumer channels. This technology is virtualizing geographic production constraints by enabling distributed micro-facility deployment outside traditional Chinese and Indian extraction hubs.
The FDA's evolving dietary supplement enforcement posture under DSHEA is tightening substantiation requirements for cognitive health advertising claims. FTC monitoring of memory enhancement and focus improvement positioning is forcing reformulation investments toward mechanistically defensible ingredient combinations. Synthetic compound specialists are responding with increased third-party Certificate of Analysis transparency to preempt regulatory action and differentiate from gray-market competitors.
Direct-to-consumer subscription models are displacing pharmacy and big-box retail as the dominant channel for premium synthetic formulations among quantified-self practitioners. Tech-sector workers in Seattle, Austin, and San Francisco are consolidating purchasing through vertically integrated content-to-commerce ecosystems that bundle personalized dosing protocols with community education. This channel rotation is most visible in the United States where regulatory arbitrage between supplement and drug classifications enables faster product iteration than European or Asian markets permit.
Nootropic Products Market Segmentation
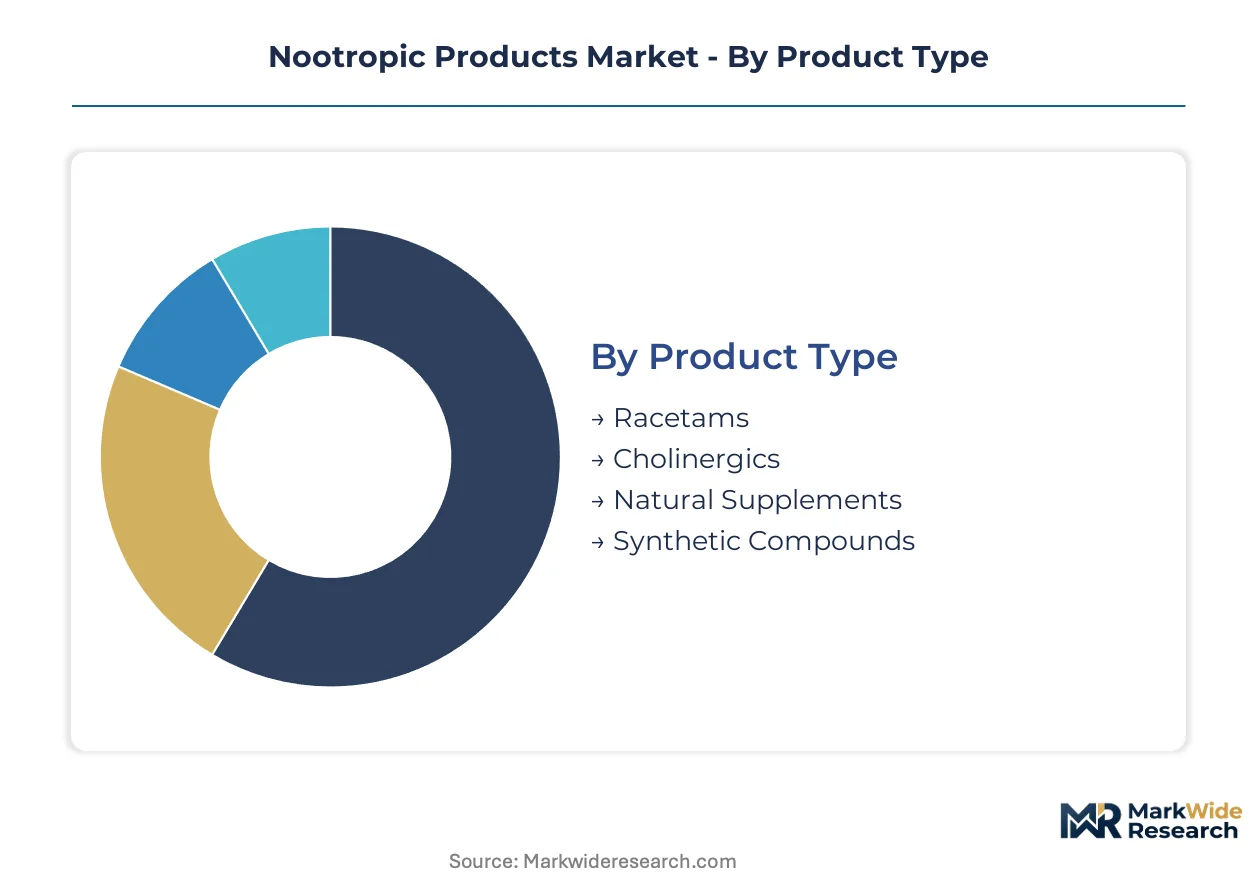
Nootropic market segmentation reveals divergent velocity profiles across product categories, with synthetic formulations iterating faster than botanical extracts due to regulatory arbitrage and biohacker demand for precise dose calibration. Understanding these cycle-time differentials enables stakeholders to align inventory, R&D, and channel investments with segment-specific turnover rhythms.
Product Type:
Cycle times vary dramatically across product categories, with biosynthetically manufactured compounds turning inventory fastest while botanical extracts face agricultural harvest constraints and extraction batch minimums.
- Natural Supplements:Formulations derived from Bacopa monnieri, Ginkgo biloba, and Panax ginseng extracts carry 12-18 month agricultural lead times from Indian and Chinese cultivation through GMP-certified processing. Demand concentrates among aging demographics in Germany and Japan seeking established safety profiles with EFSA and PMDA documentation. Monsoon-dependent harvest volatility compresses margin stability for suppliers locked into long-term retail pharmacy contracts.
- Synthetic Compounds:Laboratory-synthesized aniracetam, oxiracetam, and noopept enable precise milligram dosing with batch-to-batch consistency unattainable from botanical sources. Tech-sector professionals in Seattle and Austin drive direct-to-consumer velocity through subscription platforms demanding Certificate of Analysis transparency. The FDA's evolving DSHEA enforcement posture accelerates quality verification investments that elevate compliant manufacturers above gray-market competitors.
- Racetams:Piracetam-class compounds modulate glutamate receptor activity with established mechanistic profiles in European pharmacovigilance frameworks.
- Cholinergics:Citicoline and alpha-GPC formulations support acetylcholine synthesis with precision fermentation now enabling distributed micro-facility production outside traditional extraction hubs.
Natural Supplements anchors the volume base while Synthetic Compounds gains share at the steepest rate.
Application:
Commercial maturity stratifies sharply across use cases, with memory enhancement carrying decades of clinical positioning while mood modulation remains nascent with limited mechanistic substantiation.
- Memory Enhancement:Acetylcholine receptor modulation for age-related cognitive support commands the longest commercial history and broadest demographic penetration. Positioning concentrates among seniors in Japan and Germany where PMDA and EFSA frameworks respectively permit specific health claim substantiation. Academic validation of neuroplasticity mechanisms legitimizes clinical positioning that withstands FTC scrutiny of cognitive advertising claims.
- Focus Improvement:Dopaminergic and noradrenergic pathway targeting for sustained attention tasks captures the steepest trajectory among quantified-self practitioners and Silicon Valley engineers. Technology professionals in San Francisco and Austin consolidate purchasing through vertically integrated content-to-commerce ecosystems bundling personalized dosing protocols with community education platforms.
- Cognitive Function:General neuroprotection claims span multiple mechanisms with broader positioning flexibility across regulatory jurisdictions.
- Mood Enhancement:Serotonergic and GABAergic modulation for anxiolytic effects faces stricter pharmacovigilance classification scrutiny that constrains market access in European markets.
Memory Enhancement commands the established revenue base while Focus Improvement climbs the fastest among application segments.
End User:
Procurement authority and price sensitivity diverge substantially across user categories, with institutional purchasing from athletics programs contrasting sharply with individual biohacker experimentation.
- Professionals:Tech-sector workers, financial analysts, and consultants prioritize precise dose-to-response calibration and third-party purity verification with premium price tolerance. Demand clusters in United States metropolitan corridors where regulatory arbitrage enables faster product iteration than European markets permit. Subscription commerce penetration remains underdeveloped outside North America, creating geographic expansion opportunity.
- Students:Academic performance pressure drives volume in competitive higher education markets with acute price sensitivity and channel preference for online retailers over pharmacy distribution.
- Athletes:Esports organizations and traditional sports programs are exploring cognitive recovery formulations distinct from acute performance enhancers, opening B2B institutional channels with procurement scale.
- Seniors:Aging demographics in Japan and Germany seek clinically substantiated memory support with established safety documentation for long-term use.
Professionals generate the premium pricing tier while Athletes represents the emerging institutional channel with steepest expansion potential.
Distribution Channel:
Channel economics fragment along purity verification and community education dimensions, with direct-to-consumer platforms capturing premium synthetic formulations while mass retail dominates commoditized botanical extracts.
- Online Retailers:Amazon, specialized nootropic marketplaces, and brand-owned direct-to-consumer sites aggregate quantified-self practitioners seeking batch-specific Certificate of Analysis documentation. Tech-sector workers in Austin and Seattle consolidate purchasing through vertically integrated ecosystems that bundle personalized dosing protocols with community education. This channel rotation displaces pharmacy and big-box retail for premium synthetic formulations.
- Pharmacies:CVS, Walgreens, and independent drugstores sustain mass-market shelf presence for established natural supplement brands with GMP certification and decades of consumer familiarity.
- Health Stores:GNC and Vitamin Shoppe serve enthusiast consumers seeking in-person consultation with moderate price tolerance and brand discovery orientation.
- Direct Sales:Practitioner-sourced and multi-level marketing channels persist in Asian markets with relationship-based purchasing customs and limited e-commerce penetration.
Pharmacies retain the volume foundation while Online Retailers expands most quickly as channel share migrates toward verification-transparent platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese precision fermentation facilities export biosynthetic cholinergic compounds to United States direct-to-consumer brands, compressing traditional Indian botanical extraction economics across trans-Pacific supply corridors.
United States
Tech-sector professionals in Seattle and Austin drive premium synthetic nootropic demand through subscription platforms requiring Certificate of Analysis transparency. FDA DSHEA enforcement modernization elevates compliant manufacturers above gray-market competitors through tightened Good Manufacturing Practice inspections. San Francisco Bay Area biohackers consolidate purchasing through vertically integrated content-to-commerce ecosystems bundling personalized dosing with community education.
Germany
Aging demographics seek clinically substantiated memory enhancement formulations with established EFSA safety documentation for long-term use. EFSA novel food assessment friction blocks rapid product launches that succeed in less regulated jurisdictions, capping addressable market expansion. Frankfurt and Munich pharmacy channels sustain mass-market shelf presence for natural supplement brands with decades of consumer familiarity.
China
Pharmaceutical-grade aniracetam and oxiracetam precursor synthesis concentrates in Zhejiang and Jiangsu province facilities, creating single-geography supply vulnerability. NMPA oversight of dietary supplement versus drug classification boundaries forces parallel compliance pathway investments without certainty on final outcomes. Shanghai and Hangzhou precision fermentation startups are virtualizing batch economics previously gated by botanical extraction minimums.
Japan
Senior populations prioritize PMDA-documented neuroplasticity support with mechanistically defensible acetylcholine receptor modulation claims. PMDA pharmacovigilance frameworks maintain stricter health claim substantiation requirements than United States DSHEA enforcement, limiting product positioning flexibility. Tokyo and Osaka direct-to-consumer penetration remains underdeveloped relative to North America, creating geographic expansion opportunity for subscription commerce models.
India
Bacopa monnieri and Ginkgo biloba extract production faces monsoon-dependent agricultural yield volatility from Madhya Pradesh and Maharashtra cultivation regions. FSSAI regulatory evolution is tightening quality verification requirements for botanical supplement exports to European and North American markets. Bangalore and Hyderabad formulation facilities serve as regional processing hubs for standardized extract production destined for United States and German buyers.
Nootropic Products Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market pharmacy and big-box retail presence concentrates among legacy consumer health conglomerates with decades of shelf space negotiation leverage. Direct-to-consumer specialists and biosynthetic manufacturers represent distinct strategic archetypes competing on purity verification and customization velocity. Dominant competitive moves include subscription model deployment for recurring revenue capture and precision fermentation capacity expansion for supply chain virtualization.
Within the content-to-commerce archetype, Onnit Labs exemplifies vertically integrated ecosystem construction anchoring brand loyalty through community education platforms. Among mass-market channel controllers, Reckitt Benckiser Group PLC occupies a position sustained through pharmacy and retail network dominance. On the specialist verification tier, Nootropics Depot represents Certificate of Analysis transparency differentiation for synthetic compound purity.
| Leading Market Players |
|---|
| Onnit Labs |
| Reckitt Benckiser Group PLC |
| Nootropics Depot |
| Amway |
| TruBrain |
| Natural Stacks |
| Mind Lab Pro |
| GNC Holdings |
| Qualia Life Sciences |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu province facilities concentrate pharmaceutical-grade aniracetam and oxiracetam precursor synthesis, anchoring margin pools with downstream direct-to-consumer brands in Seattle and Austin that command premium subscription pricing through Certificate of Analysis transparency.
Pricing Analysis
Biosynthetic citicoline and alpha-GPC from precision fermentation facilities commands 40-60% premiums over botanical-extracted equivalents, while legacy racetam compounds face cost compression from Chinese manufacturing scale. Three-tier pricing structure across premium synthetic formulations, standard natural supplements, and economy bulk powders separates tech-sector biohackers from aging demographic natural supplement users from student price-sensitive segments. Pricing pressure stems from DSHEA enforcement modernization forcing quality verification investments that elevate compliant manufacturers above gray-market competitors. Tech-sector professionals in San Francisco demonstrate lowest price sensitivity due to quantified-self calibration demands, while students exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for synthetic nootropic precursors, with pharmaceutical-grade synthesis concentrated in Zhejiang and Jiangsu provinces. Bacopa monnieri and Ginkgo biloba extraction draws from Madhya Pradesh and Maharashtra cultivation regions in India, creating monsoon-dependent agricultural volatility. Single-geography concentration for racetam precursors creates supply vulnerability amplified by NMPA dietary supplement versus drug classification uncertainty. Distribution runs through vertically integrated content-to-commerce ecosystems for premium synthetic formulations, while mass-market botanical extracts sustain pharmacy and big-box retail channel presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation is disrupting traditional extraction economics, with FDA DSHEA enforcement modernization creating regulatory arbitrage windows that favor quality-verified manufacturers over gray-market competitors.
For Market Incumbents: Insulate market position by deepening backward integration into precision fermentation capacity for citicoline and alpha-GPC production, preempting supply disruption from Chinese precursor concentration. Acquire Certificate of Analysis transparency capabilities to differentiate from emerging biosynthetic competitors facing talent scarcity in analytical chemistry verification.
For New Entrants and Emerging Players: Subscription commerce penetration in Japan and Germany represents the most penetrable entry point, with Tokyo and Osaka direct-to-consumer channels underdeveloped relative to North American saturation. Esports organization B2B institutional procurement for cognitive recovery formulations offers white-space access with procurement scale and lower competitive density than consumer markets.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated content-to-commerce specialists with established community education platforms and personalized dosing protocol capabilities. The signal to monitor is EFSA novel food assessment friction resolution, which would unlock European market expansion and validate premium pricing sustainability for mechanistically substantiated formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Biosynthetic citicoline production virtualizes batch economics previously gated by Indian botanical extraction minimums. |
| Certificate of Analysis Transparency Investment | Third-party verification capabilities differentiate compliant manufacturers from gray-market competitors under tightening FDA DSHEA enforcement. |
| Subscription Commerce Platform Development | Recurring revenue capture through personalized dosing protocols anchors brand loyalty among quantified-self practitioners in Austin and Seattle. |
| Esports B2B Institutional Channel Entry | Cognitive recovery formulation procurement from athletics programs opens institutional purchasing with scale advantages over fragmented consumer markets. |
| EFSA Novel Food Assessment Preparation | Mechanistic substantiation investments preempt European market access barriers and validate premium positioning against natural supplement commoditization. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA warning letters, EFSA novel food assessments, and customs trade data for racetam precursor flows. Conversations with formulation chemists at GMP-certified facilities, procurement leads at direct-to-consumer brands, regulatory affairs specialists navigating DSHEA enforcement, and esports organization nutrition directors informed demand segmentation. Secondary validation drew from ClinicalTrials.gov neuroplasticity research, SEC 10-K filings for consumer health conglomerates, and PMDA pharmacovigilance documentation. Bottom-up demand modeling across product type, application, and end user segments triangulated against top-down market sizing from trade flow analysis.
Forecast inputs include precision fermentation capacity buildout trajectories, DSHEA enforcement modernization pace, and tech-sector employment concentration in target metropolitan corridors. Segmentation dimensions encompass natural versus synthetic product origin, memory enhancement versus focus improvement applications, and professional versus student versus athlete end users. CAGRs derive from regression analysis of historical volume patterns against regulatory inflection points and technology adoption curves. Biosynthetic manufacturing cost curves and EFSA assessment pipeline velocity serve as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in tech-sector employment levels, Chinese pharmaceutical export policy, or Indian monsoon patterns would shift the trajectory. Forecasts reflect documented assumptions on regulatory classification stability and precision fermentation yield improvements. Macroeconomic contraction, accelerated pharmacovigilance reclassification, or breakthrough neurotechnology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Glucosamine Supplements Market