
 Glucosamine Supplements Market | 2026-2036
Glucosamine Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Glucosamine Supplements Market Analysis
Pharmaceutical-grade formulation expertise is bifurcating the competitive landscape into science-backed brands and commodity private-label suppliers. Nutramax Laboratories Consumer Care sustains its position through veterinary and human joint health specialization. TSI Group Ltd. leverages vertically integrated glucosamine salt production from shellfish biomass. Pfizer Inc. competes through pharmacy-centric distribution networks and clinician endorsement programs.
Glucosamine supplements are amino-monosaccharide compounds, primarily glucosamine sulfate and glucosamine hydrochloride, manufactured through chitin hydrolysis from crustacean shells or via microbial fermentation for plant-based variants, functionally intended to support articular cartilage integrity and reduce osteoarthritic discomfort. Capsules dominate volume due to dosing precision and consumer familiarity, while plant-based ingredient sources represent the fastest-expanding margin pool as shellfish allergen concerns and vegan preferences reshape formulation R&D. The senior end-user segment anchors value generation, though pet applications are emerging as a structurally distinct growth corridor.
The FDA's Current Good Manufacturing Practices and the EFSA's health claims assessment framework govern product quality substantiation and label permissibility across the United States and European markets. Japan's Ministry of Health, Labour and Welfare regulates glucosamine-containing products through Foods with Function Claims standards, creating a tripartite compliance architecture that shapes market access costs. Stakeholders must monitor evolving substantiation requirements for structure-function claims, as regulatory divergence between jurisdictions threatens to fragment product development roadmaps and force geography-specific formulation investments.
Market Dynamics
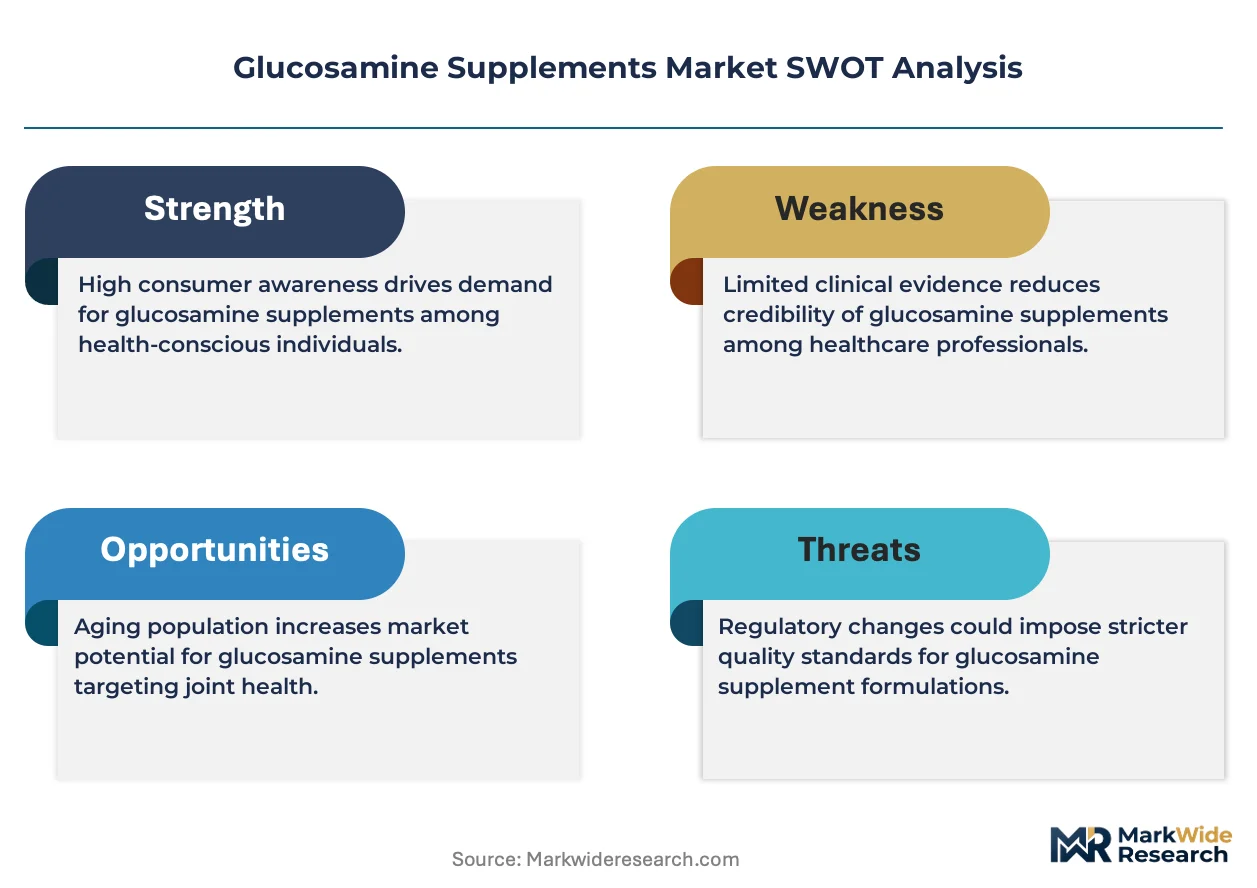
FDA's Current Good Manufacturing Practices enforcement is compressing formulation margins for non-compliant suppliers while elevating entry barriers for science-backed brands that can substantiate structure-function claims through clinical documentation.
Growth Catalysts
- Aging Demographics in Japan and Germany:Expanding senior populations in these countries are amplifying demand for joint health formulations targeting osteoarthritic discomfort management.
- EFSA Health Claims Assessment Framework:This regulatory architecture rewards substantiated products with label permissibility, creating competitive separation between clinically validated and commodity formulations.
- Direct-to-Consumer Online Channels:E-commerce platforms in the United States are capturing disproportionate volume by bypassing traditional pharmacy intermediaries and reducing customer acquisition costs.
Market Restraints
- Shellfish Supply Concentration:Chitin hydrolysis feedstock dependence on crustacean shell biomass creates input cost volatility tied to fishery yields and seasonal harvesting patterns.
- Regulatory Divergence Between Jurisdictions:FDA, EFSA, and Japan's Foods with Function Claims standards impose non-harmonized substantiation requirements that fragment product development roadmaps.
- Plant-Based Fermentation Cost Premium:Microbial production methods for vegan glucosamine variants carry higher unit economics that constrain mass-market penetration.
Strategic Opportunities
- Pet Application Expansion:Veterinary joint health formulations represent a structurally distinct growth corridor with lower regulatory friction and premium pricing tolerance.
- Japan's Foods with Function Claims Channel:This regulatory pathway offers faster market entry for substantiated products compared to pharmaceutical registration routes.
- Capsule-to-Gummy Format Migration:Confectionery delivery formats are capturing younger demographic segments previously alienated by pill fatigue.
Industry Challenges
- Clinical Trial Talent Scarcity:Structure-function claim substantiation requires specialized biostatisticians and regulatory affairs expertise that command premium compensation.
- Multi-Jurisdiction Label Harmonization:Geography-specific formulation investments strain working capital for mid-scale manufacturers attempting cross-border expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucosamine Supplements Market |
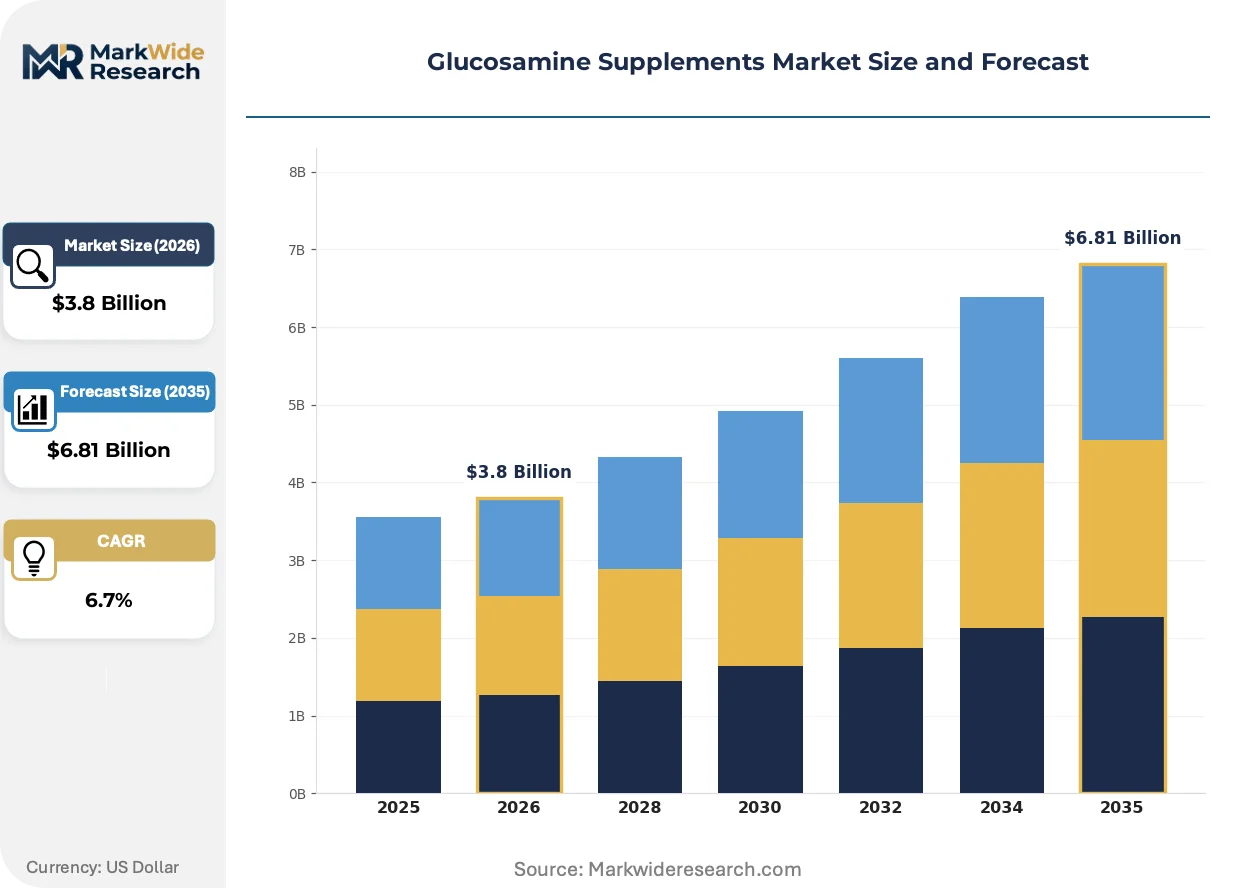
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquids Ingredient Source: Shellfish, Plant-Based, Synthetic, Mixed End User: Adults, Athletes, Seniors, Pets Distribution Channel: Online, Pharmacies, Health Stores, Supermarkets |
| Companies Covered | GlaxoSmithKline, Pfizer Inc., Merck & Co. Inc., Sanofi, Novartis AG, Cargill, Inc., Koyo Chemical Co., Ltd., TSI Group Ltd., Nutramax Laboratories Consumer Care, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucosamine Supplements Market Emerging Trajectories
Formulation science and distribution architecture are undergoing parallel transformation as microbial fermentation, regulatory digitization, and channel disintermediation reshape competitive economics.
Microbial fermentation pathways for glucosamine hydrochloride production are displacing traditional chitin hydrolysis methods among premium-positioned brands. Vegan-certified manufacturers in Germany and California are adopting this biotechnology to eliminate shellfish allergen liabilities and capture ethical-consumer segments. The shift is compressing cost differentials between plant-based and crustacean-derived supply chains.
Japan's PMDA has streamlined Foods with Function Claims notification procedures, reducing time-to-market for substantiated joint health products. This regulatory efficiency is attracting multinational formulation investments into Japanese distribution partnerships. Domestic brands with established clinical dossiers are leveraging the accelerated pathway to defend shelf position against imported competitors.
Subscription-based replenishment models are capturing recurring revenue from chronic-condition consumers who prioritize adherence convenience over episodic pharmacy purchasing. Direct-to-consumer platforms in the United States are bundling glucosamine with complementary nutraceuticals to increase average order value and reduce churn. This behavioral shift concentrates customer lifetime value with digitally native brands that own the full data relationship.
Glucosamine Supplements Market Segmentation
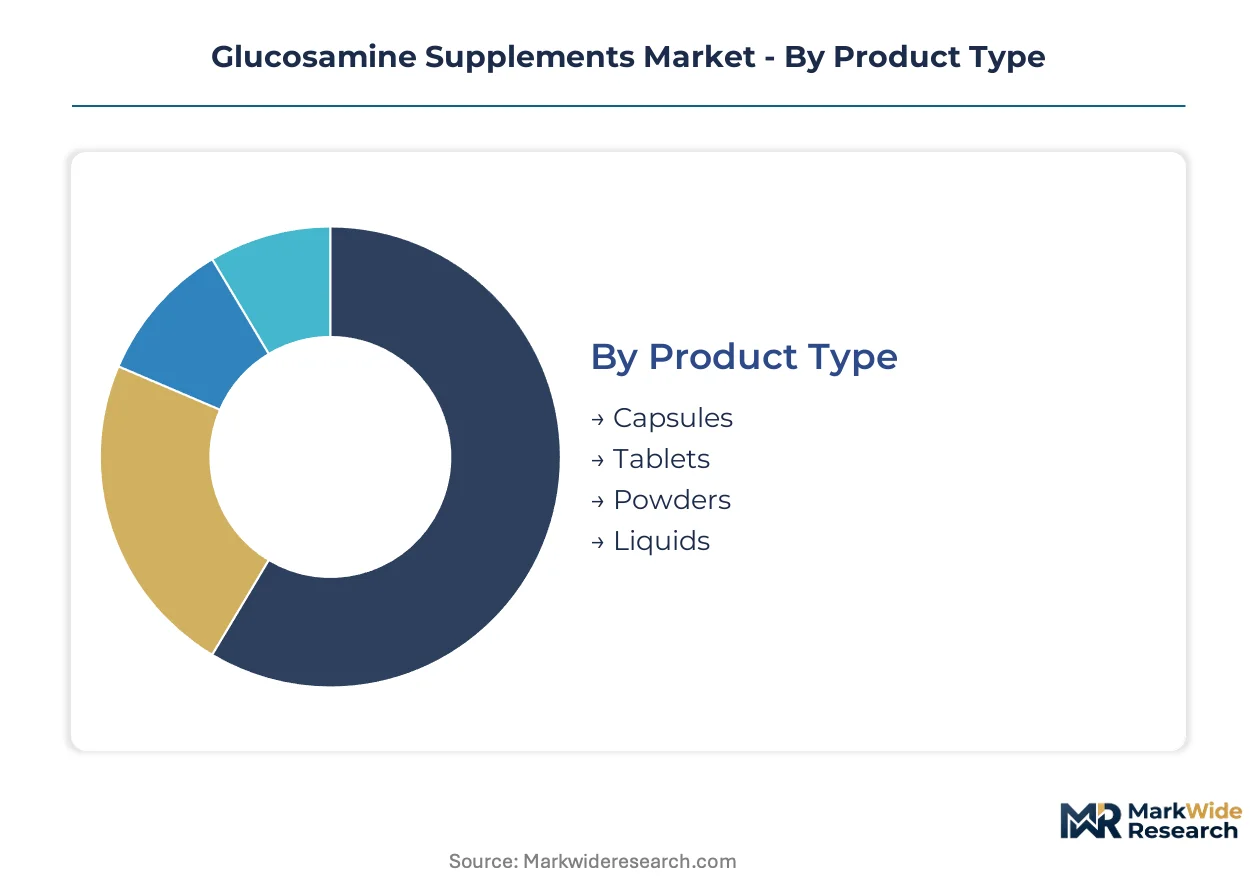
Glucosamine supplement segmentation reveals how formulation choices, sourcing decisions, and channel strategies create distinct margin profiles. Manufacturers must align product architecture with specific end-user compliance requirements and regulatory substantiation thresholds.
Product Type:
Capsule and tablet formats dominate domestic consumption in the United States and Japan, while powder and liquid variants capture disproportionate export volume to European markets with stronger preference for dosage flexibility.
- Capsules:Hard-shell gelatin and vegetable cellulose encapsulation delivers precise milligram dosing for chronic-condition consumers. Demand concentrates among seniors in Japan and Germany where pill familiarity reduces adherence friction.
- Tablets:Compressed glucosamine sulfate with excipient binders enables cost-efficient mass production. United States pharmacy channels favor this format for insurance-adjacent reimbursement workflows.
- Powders:Bulk glucosamine hydrochloride with flavor masking targets athletic end-users requiring customizable dosing protocols.
- Liquids:Suspension formulations with preservative systems serve pediatric and geriatric populations with swallowing difficulties.
Capsules command the established base. The steepest expansion runs through powders.
Ingredient Source:
Cost tiers separate crustacean-derived feedstocks from fermentation-based alternatives, with synthetic and mixed formulations occupying intermediate price positioning.
- Shellfish:Chitin hydrolysis from crab and shrimp shell biomass yields glucosamine sulfate with established clinical dossiers. Japanese and United States brands rely on this cost-efficient pathway despite seasonal supply volatility.
- Plant-Based:Microbial fermentation of Aspergillus niger or genetically modified yeast strains produces vegan-certified glucosamine hydrochloride. German and California manufacturers adopt this biotechnology to eliminate allergen liabilities and capture ethical-consumer segments.
- Synthetic:Chemical synthesis from glucose and ammonia precursors offers batch consistency independent of biological feedstocks.
- Mixed:Blended shellfish and plant-derived glucosamine enables partial vegan positioning at moderate cost premiums.
Shellfish-derived material anchors volume economics. Plant-based sourcing gains share fastest among premium-positioned entrants.
End User:
Application maturity varies sharply: senior and adult segments represent saturated chronic-condition management, while athletic and pet applications offer greenfield expansion with distinct regulatory pathways.
- Adults:Preventive joint health consumption among 35-55 year-olds in the United States drives steady replenishment demand through direct-to-consumer subscriptions.
- Seniors:Osteoarthritic symptom management in Japan and Germany generates the highest per-capita consumption intensity. PMDA Foods with Function Claims and EFSA substantiation requirements shape product positioning.
- Athletes:Cartilage stress recovery formulations target gym-based and endurance sports participants with performance-oriented marketing.
- Pets:Veterinary joint health applications for canine and feline osteoarthritis represent structurally distinct growth with lower regulatory friction and premium pricing tolerance.
Seniors command the established base. The steepest expansion runs through pets.
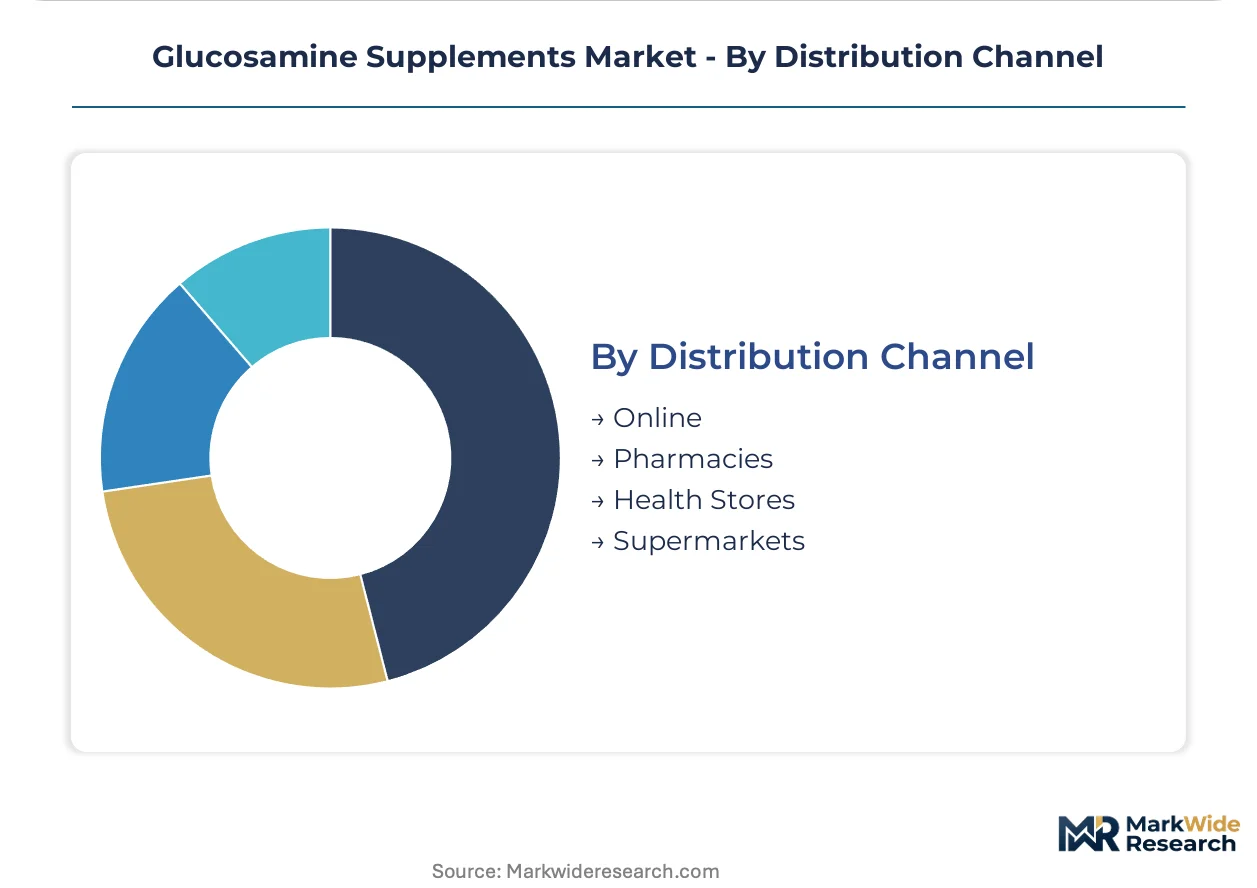
Distribution Channel:
Channel economics bifurcate between high-touch pharmacy consultation and low-friction digital self-service, with health stores and supermarkets occupying intermediate customer acquisition cost positions.
- Online:Direct-to-consumer platforms and marketplace aggregators capture disproportionate United States volume by bypassing pharmacy intermediaries. Subscription replenishment models concentrate customer lifetime value with digitally native brands.
- Pharmacies:Clinician endorsement and insurance-adjacent positioning sustain premium pricing in Japan and German retail pharmacy networks. Pharmacist consultation drives trial among first-time users.
- Health Stores:Specialty retailers with trained staff serve educated consumers seeking combination formulations with chondroitin and MSM.
- Supermarkets:Mass-market shelf placement targets impulse purchasers with private-label and economy-tier pricing.
Pharmacies command the established base. The steepest expansion runs through online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Japan and Germany prioritize senior-targeted osteoarthritis formulations with regulatory substantiation, while the United States channels volume through direct-to-consumer subscriptions that bundle glucosamine with complementary nutraceuticals.
United States
Direct-to-consumer online platforms capture disproportionate volume by bypassing pharmacy intermediaries and reducing customer acquisition costs. FDA's Current Good Manufacturing Practices enforcement elevates entry barriers for brands lacking clinical documentation. Subscription-based replenishment models concentrate in California and New York metro areas where digitally native brands own full customer data relationships.
Japan
Expanding senior populations amplify demand for joint health formulations targeting osteoarthritic discomfort management. PMDA's streamlined Foods with Function Claims notification procedures reduce time-to-market for substantiated products. Domestic manufacturers in Kanto and Kansai regions leverage accelerated pathways to defend shelf position against imported competitors.
Germany
Aging demographics drive per-capita consumption intensity for clinically validated joint health products. EFSA's health claims assessment framework rewards substantiated formulations with label permissibility. Bavaria-based manufacturers adopt microbial fermentation biotechnology to eliminate shellfish allergen liabilities and capture ethical-consumer segments.
China
Preventive joint health consumption among middle-aged urban populations generates steady replenishment demand through e-commerce platforms. NMPA oversight of dietary supplement quality thresholds reshapes product entry requirements. Manufacturing clusters in Yangtze River Delta and Pearl River Delta regions specialize in chitin hydrolysis from crustacean shell biomass.
Australia
TGA regulation of complementary medicines creates a compliance architecture that favors clinically documented formulations over commodity private-label alternatives. Pharmacy-centric distribution networks sustain premium pricing through clinician endorsement. Sydney and Melbourne serve as headquarters for brands targeting Asia-Pacific export markets with substantiated joint health products.
Glucosamine Supplements Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical-grade formulation expertise bifurcating the landscape into science-backed brands and commodity private-label suppliers. The competitive structure rewards vertical control over glucosamine salt production and clinical dossier development. Three archetypes dominate: crustacean-derived bulk suppliers, fermentation-based vegan specialists, and veterinary-human dual-application formulators. Capacity expansion in microbial production and strategic partnerships for Japanese regulatory pathway access represent the dominant competitive moves.
Within the integrated manufacturing tier, TSI Group Ltd. exemplifies upstream control over shellfish biomass supply chains, while Nutramax Laboratories Consumer Care, Inc. occupies a position bridging veterinary and human joint health applications. Pfizer Inc. anchors the pharmacy-centric distribution archetype through clinician endorsement programs. These three entities represent distinct strategic vectors: captive feedstock security, cross-species formulation specialization, and retail pharmacy channel dominance.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Sanofi |
| Novartis AG |
| Cargill, Inc. |
| Koyo Chemical Co., Ltd. |
| TSI Group Ltd. |
| Nutramax Laboratories Consumer Care, Inc. |
| Others |
Supply Flow & Price Mechanics
Microbial fermentation displacement of crustacean-derived chitin hydrolysis simultaneously redistributes production geography toward Germany and California biotechnology clusters while compressing cost premiums that previously separated vegan-certified formulations from commodity shellfish-sourced alternatives.
Pricing Analysis
Long-term offtake contracts between Japanese pharmaceutical distributors and domestic manufacturers dominate premium-tier transactions, while spot purchasing governs commodity-grade shellfish-derived volumes in United States mass-market channels. Price differentiation hinges on FDA Current Good Manufacturing Practices certification tier and volume scale commitments, with clinic-endorsed brands commanding substantial premiums over private-label alternatives. Cost compression in the standard tier intensifies as Chinese chitin hydrolysis capacity expands and raw material volatility from seasonal fishery yields feeds into margin pressure. Subscription-based direct-to-consumer buyers exhibit lowest price sensitivity due to adherence convenience premiums, while supermarket impulse purchasers drive aggressive economy-tier competition.
Supply Chain Analysis
Crustacean shell biomass concentration in Chinese Yangtze River Delta and Pearl River Delta manufacturing clusters creates single-source vulnerability for conventional glucosamine sulfate production, with Japanese coastal processing facilities providing secondary but higher-cost feedstock security. Raw material dependencies encompass crab and shrimp shell harvests, Aspergillus niger fermentation substrates for plant-based variants, and pharmaceutical-grade excipient binders for tablet compression. Tariff exposure on United States-bound Chinese chitin derivatives threatens input cost stability for non-vertically integrated formulators. Distribution runs through direct-to-consumer platforms for replenishment-heavy United States consumption, while pharmacy-centric networks dominate Japanese and German clinically validated product channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glucosamine supplements represent early-cycle expansion as veterinary applications and microbial fermentation unlock penetration gains in previously underserved pet owner and ethical-consumer segments.
For Market Incumbents: Secure captive supply of crustacean shell biomass through backward integration into Chinese and Southeast Asian fishery processing partnerships, insulating margin structures from seasonal harvest volatility. Invest in PMDA Foods with Function Claims dossier development to defend Japanese shelf position against imported competitors leveraging streamlined notification pathways. Prioritize certification maintenance under FDA Current Good Manufacturing Practices as enforcement actions elevate compliance costs for non-compliant suppliers. For New Entrants and Emerging Players: Anchor in pet veterinary formulations as the structurally most penetrable corridor, where lower regulatory friction and premium pricing tolerance create favorable entry economics. Target direct-to-consumer subscription models in United States coastal metro areas, bundling glucosamine with complementary nutraceuticals to increase average order value and reduce customer acquisition costs. Pursue microbial fermentation partnerships with established German or California biotechnology facilities to bypass shellfish allergen liabilities and capture vegan-certified positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed veterinary-human dual-application formulators possessing established clinical dossiers but limited geographic expansion capital. Long-term viability across the projection horizon rests on regulatory pathway expertise and fermentation technology access rather than commodity chitin hydrolysis scale. Watch PMDA notification volume trends as the inflection signal for Japanese market entry acceleration and corresponding valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Fermentation Scale-Up | Biotechnology investment in Aspergillus niger production lines eliminates shellfish allergen exposure for vegan-certified positioning. |
| PMDA Foods with Function Claims Notification | Accelerated Japanese regulatory pathway reduces time-to-market for substantiated joint health formulations against imported competition. |
| Veterinary Formulation Development | Canine and feline osteoarthritis applications unlock premium pricing tolerance with lower compliance burden than human pharmaceutical routes. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models in United States metro areas concentrate customer lifetime value through owned data relationships. |
| Backward Integration into Shellfish Processing | Captive chitin hydrolysis feedstock security insulates margin structures from seasonal fishery yield volatility and tariff exposure. |
Methodological Framework
The analysis maps glucosamine salt production pathways, finished formulation manufacturing, and distribution channel economics, each validated through primary interviews with regulatory affairs directors at supplement manufacturers, veterinary product development leads, pharmacy chain procurement managers, and direct-to-consumer platform operators. Secondary validation drew from FDA dietary supplement enforcement actions, PMDA Foods with Function Claims notification databases, EFSA health claim assessment records, and customs trade data on chitin derivative flows. Bottom-up volume estimates from ingredient sourcing and formulation capacity were triangulated against top-down demand projections from end-user demographic modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation encompassing product format, ingredient source, end-user application, and distribution channel. Analytical framework approach tracked adoption curves for microbial fermentation technology, regulatory pathway efficiency differentials, and channel shift dynamics. CAGRs were derived from regression analysis on historical penetration rates adjusted for demographic tailwinds and compliance cost trajectories. Forecast inputs included aging population projections in Japan and Germany, pet ownership growth rates, and e-commerce penetration in United States nutraceutical categories.
Underlying assumptions cover stable FDA enforcement intensity, sustained PMDA notification streamlining, and gradual microbial fermentation cost convergence with chitin hydrolysis, with deviation risk concentrated in fishery yield shocks, tariff regime changes, and regulatory substantiation requirement tightening. Practitioners should keep alternative scenarios live as biotechnology scale economics and jurisdictional compliance architectures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Canine Weight Loss Drugs Market