
 Medicated Confectionery Market | 2026-2036
Medicated Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Medicated Confectionery Market Outlook
Sugar alcohols and natural sweeteners are consolidating their position in medicated confectionery formulations as brands reformulate to reduce glycemic impact and clean-label dependency. Ricola Group AG leverages its Swiss herb supply chain to sustain premium positioning in botanical lozenges. Haleon plc anchors pharmacy and retail shelf presence across multiple continents with its consumer health portfolio. Mondelez International, Inc. competes through scale manufacturing and cross-category distribution infrastructure.
Medicated confectionery comprises dosage-form candies incorporating pharmacologically active ingredients for therapeutic or prophylactic delivery, typically manufactured through cold-compression or deposit-molding processes at controlled temperatures to preserve volatile actives like menthol or dextromethorphan. These products serve primarily as palatable, self-administered alternatives to conventional tablets for cough, cold, and minor pain indications. Lozenges dominate volume due to established efficacy in localized throat delivery and broad pharmacy availability. Gummies represent the fastest-expanding format as adult consumers prioritize chewable vitamin and antihistamine regimens. Tablets retain margin concentration in clinical and pediatric segments where precise dosing commands premium positioning.
The FDA regulates active ingredient claims and manufacturing standards in the United States, while the EMA and national bodies like Germany's BfArM govern pharmaceutical-candy hybrids under OTC or borderline classifications in Europe. REACH and evolving EU packaging waste directives further constrain excipient selection and single-dose wrapping formats. Stakeholders must monitor regulatory divergence between pharmaceutical and food frameworks as classification ambiguity creates compliance risk and market access friction.
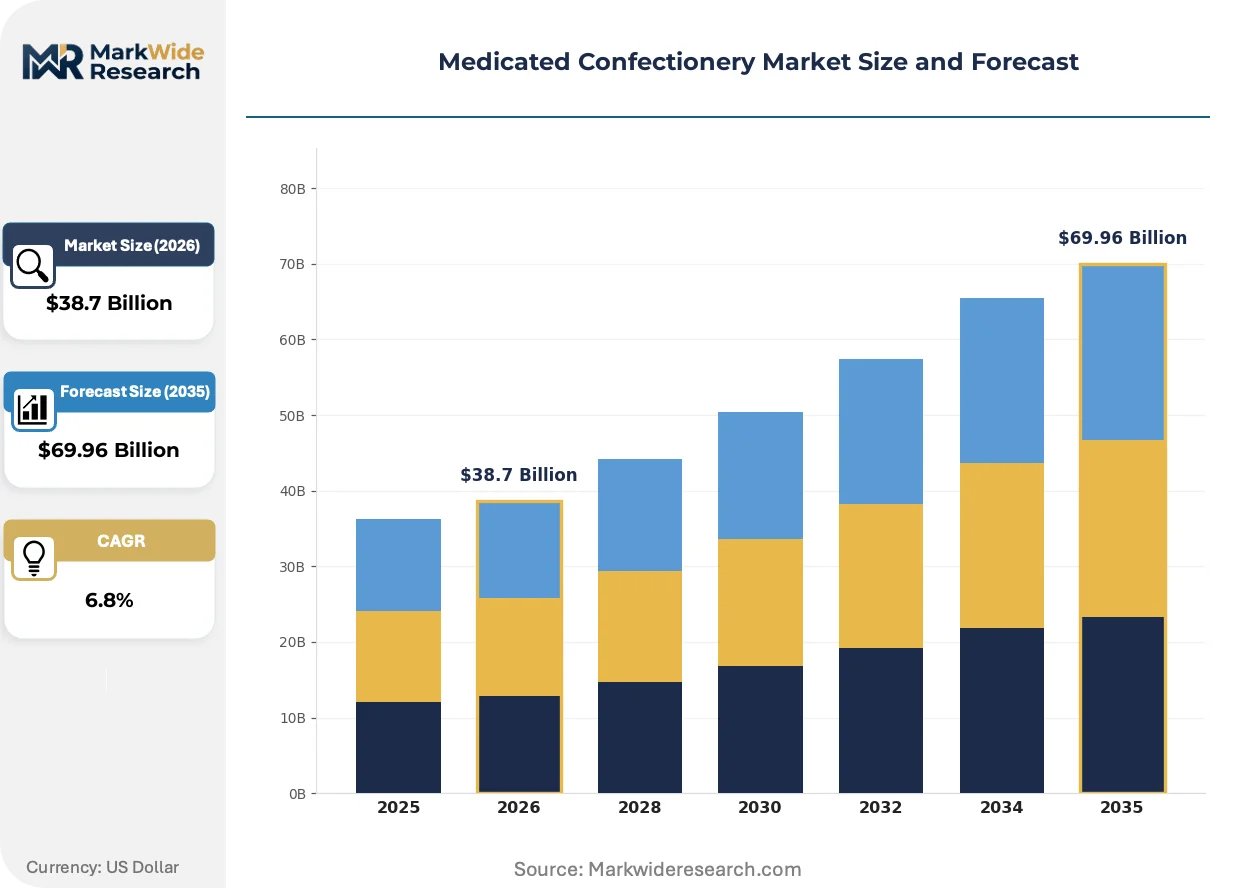
Market Dynamics
Reformulation pressure is compressing traditional sucrose-based supply chains as pharmacy buyers and wellness consumers demand glycemic-friendly alternatives with clean-label positioning.
Growth Catalysts
- REACH-compliant excipient sourcing:European manufacturers accelerate plant-based active adoption to satisfy ECHA substance restrictions and differentiate from synthetic competitors.
- Adult wellness regimens:Vitamin-enriched gummies capture self-directed health management demand among working-age populations seeking palatable supplement formats.
- Japan's pharmacy-channel density:METI-supported retail health infrastructure expansion creates accessible distribution nodes for OTC symptom-relief products.
Market Restraints
- Volatile erythritol supply:Sugar alcohol feedstock costs fluctuate with corn and wheat starch commodity markets, squeezing margin on reformulated lines.
- FDA-EMA classification divergence:Borderline product status creates dual-track compliance burdens for manufacturers distributing across Atlantic markets.
- Hard candy substitution:Functional beverages and dissolvable oral strips compete for throat-soothing and rapid-onset delivery occasions.
Strategic Opportunities
- Pediatric precision dosing:Micro-tablet formats with verified child-resistant packaging address unmet needs in family cough-cold segments.
- US IRA preventive health alignment:Medicare Advantage plan incentives for OTC wellness purchases expand reimbursable access channels.
- Direct-to-clinic distribution:Physician office dispensing of probiotic lozenges bypasses retail markup and builds prescriber loyalty.
Industry Challenges
- Volatile actives handling expertise:Cold-compression process engineering talent scarcity constrains expansion of menthol and dextromethorphan product lines.
- EU packaging waste directive compliance:Single-dose wrapping redesign demands capital-intensive equipment retooling ahead of 2030 reduction targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicated Confectionery Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lozenges, Gummies, Tablets, Chews Active Ingredient: Cough Suppressants, Pain Relievers, Vitamins, Antihistamines Distribution Channel: Pharmacies, Supermarkets, Online, Convenience Stores Target Demographic: Adults, Children, Seniors, Pregnant Women |
| Companies Covered | Mondelez International, Inc., Cloetta AB, Ricola Group AG, Mastix Medica, LLC, Ernest Jackson Ltd., Haleon plc, Reckitt Benckiser Group PLC, Perrigo Company PLC, The Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicated Confectionery Market Strategic Shifts
Cold-compression manufacturing systems are automating quality consistency while regulatory frameworks on both sides of the Atlantic tighten ingredient transparency requirements.
Continuous manufacturing platforms are automating temperature-controlled deposit-molding processes that preserve volatile actives like eucalyptus oil and dextromethorphan. Mid-size contract manufacturers in Germany and the United States deploy these systems to reduce batch-to-batch variation and accelerate scale-up for seasonal demand surges. Automation is compressing lead times from formulation to pharmacy shelf placement.
REACH substance evaluation and evolving EU packaging waste directives are forcing excipient portfolio reviews and single-dose format redesigns. Manufacturers serving European markets now pre-validate biodegradable film wrappers and reduced-plastic blister alternatives. Lozenge producers with German and Swiss manufacturing footprints face the steepest compliance cost curves.
Adult consumers now treat medicated confectionery as a planned wellness purchase rather than impulse symptom response. Pharmacy loyalty programs and subscription replenishment models displace convenience-store grab-and-go patterns. This behavioral pivot is most visible in US and Japanese urban markets where pharmacy-chain mobile apps integrate cough-cold inventory with household prescription management.
Medicated Confectionery Market Segmentation
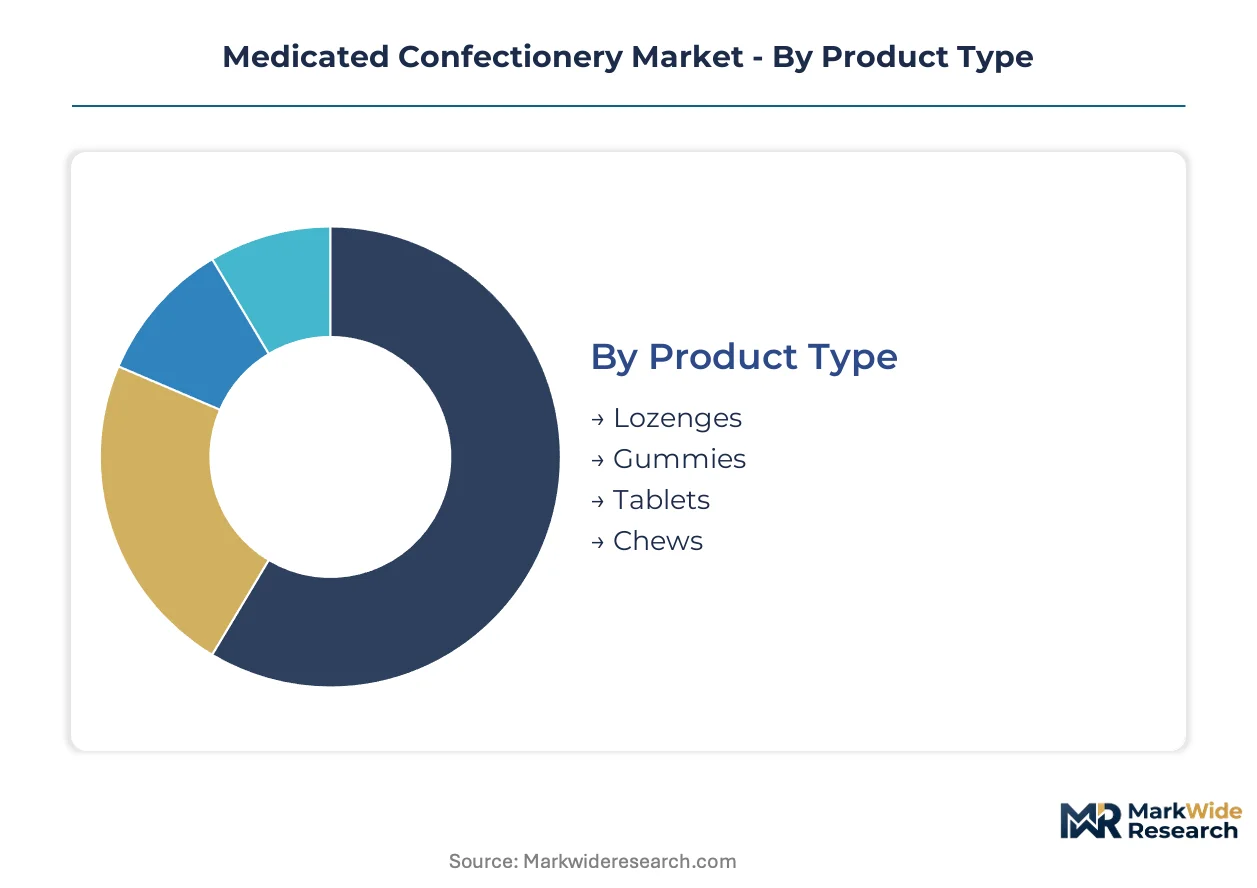
Medicated confectionery segmentation reveals how regulatory pathways, dosage precision requirements, and consumer self-selection behaviors fragment commercial opportunities across distinct product architectures and channel strategies.
Product Type:
FDA and EMA classification divergence creates tiered approval burdens: lozenges and gummies navigate food-drug borderline frameworks, while tablets trigger pharmaceutical dossier requirements.
- Lozenges:Cold-compressed or deposit-molded dosage forms delivering menthol, benzocaine, or dextromethorphan through sustained oral dissolution. Demand concentrates in Germany and Japan where pharmacy-channel density supports premium botanical and synthetic formulations. EMA borderline classification creates compliance friction versus US FDA OTC monograph pathways.
- Gummies:Gelatin or pectin-based matrices suspending vitamins, antihistamines, or zinc salts for chewable delivery. Adult wellness consumers in US urban markets drive subscription replenishment through pharmacy loyalty apps. METI-supported retail health infrastructure in Japan accelerates comparable adoption curves.
- Tablets:Direct-compression formats with precise active loading for clinical and pediatric dosing segments.
- Chews:Softer matrices than gummies, often positioned for rapid onset or pediatric palatability.
Leading the category by volume: Lozenges. Growing fastest: Gummies.
Active Ingredient:
Ingredient selection determines manufacturing temperature controls, stability testing protocols, and whether products qualify for OTC monograph or require new drug applications.
- Cough Suppressants:Dextromethorphan and menthol formulations requiring cold-compression process engineering to preserve volatile actives. Supply chain talent scarcity in Germany and the United States constrains capacity expansion for seasonal demand surges.
- Pain Relievers:Benzocaine and phenol-based localized analgesia for throat indications. Pharmacy buyers in Japan prioritize METI-compliant manufacturing documentation for import clearance.
- Vitamins:Ascorbic acid, D3, and zinc complexes for prophylactic wellness regimens.
- Antihistamines:Diphenhydramine and loratadine incorporation into chewable formats for allergy symptom management.
Highest margin concentration: Pain Relievers. Steepest volume climb: Vitamins.
Distribution Channel:
Channel selection dictates packaging format, unit economics, and whether products integrate with pharmacy prescription management systems or compete on convenience-store impulse fixtures.
- Pharmacies:Primary node for clinically positioned products with pharmacist consultation potential. US Medicare Advantage plan incentives for OTC wellness purchases expand reimbursable access through this channel. Cold-chain and verified child-resistant packaging requirements elevate operational complexity.
- Supermarkets:Mass-market penetration for wellness-positioned gummies and seasonal cough-cold lozenges. German and Swiss retail consolidation demands centralized distribution compliance with EU packaging waste directives.
- Online:Direct-to-consumer subscription models displacing grab-and-go purchase patterns in US and Japanese urban markets.
- Convenience Stores:Impulse-driven single-unit sales for acute symptom relief occasions.
Dominant by revenue: Pharmacies. Expanding most quickly: Online.
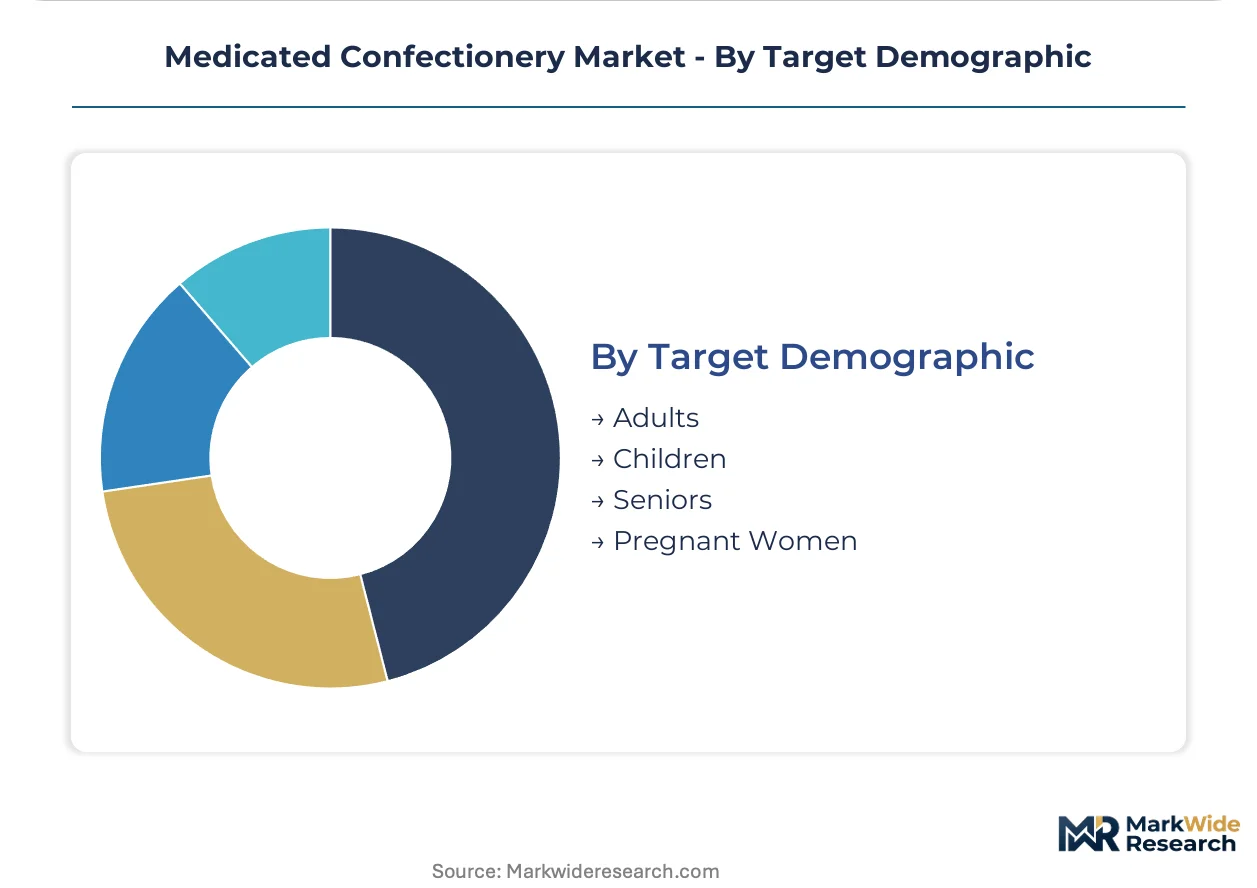
Target Demographic:
Demographic targeting determines dosing precision requirements, palatability engineering, and whether products require pediatric-specific safety testing or geriatric-friendly packaging adaptations.
- Adults:Working-age populations self-directing wellness regimens through chewable vitamin and antihistamine formats. Pharmacy mobile app integration in US and Japanese markets enables planned replenishment rather than impulse purchase behavior.
- Children:Micro-tablet and reduced-dose formats with verified child-resistant packaging addressing family cough-cold segments. FDA pediatric labeling requirements and EU safety standards create dual-track compliance burdens.
- Seniors:Formulations addressing polypharmacy interactions and swallowing difficulty through soft-chew alternatives.
- Pregnant Women:Ingredient-restricted formulations excluding teratogenic actives like high-dose vitamin A or certain herbal extracts.
Largest addressable base: Adults. Fastest-emerging opportunity: Children.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy-channel density and aging demographics concentrate demand in the United States, Germany, and Japan, with each market presenting distinct regulatory and distribution architectures for OTC confectionery formats.
United States
Medicare Advantage plan incentives for OTC wellness purchases expand reimbursable access through pharmacy chains, while FDA OTC monograph pathways enable faster product launches than new drug applications. Cold-compression manufacturing clusters in New Jersey and Pennsylvania support seasonal capacity surges for menthol-based lozenges.
Germany
EMA borderline classification creates compliance friction for food-drug hybrid products, yet pharmacy-channel loyalty sustains premium positioning for botanical formulations. REACH substance restrictions accelerate plant-based active adoption among Baden-Württemberg and Bavaria contract manufacturers serving EU markets.
Japan
METI-supported retail health infrastructure expansion creates accessible distribution nodes for throat-soothing lozenges and vitamin-enriched gummies. PMDA documentation requirements for import clearance elevate operational complexity for foreign entrants targeting Tokyo-Osaka pharmacy corridors.
Switzerland
Swissmedic oversight of pharmaceutical-candy hybrids maintains stringent quality benchmarks that reinforce premium export positioning. Ricola Group AG leverages its central Swiss herb supply chain to sustain botanical lozenge differentiation across European and Asian markets.
United Kingdom
MHRA post-Brexit regulatory divergence from EMA frameworks creates dual-track compliance burdens for manufacturers distributing across UK-EU borders. London and Southeast England pharmacy chains integrate cough-cold inventory with digital prescription management systems.
Medicated Confectionery Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers reformulate sucrose-based lines toward glycemic-friendly alternatives and clean-label positioning. The vendor base spans multinational consumer health conglomerates, Swiss and German botanical specialists, and mid-size contract manufacturers with cold-compression expertise. Three strategic archetypes emerge: scale-driven cross-category distributors, herb-integrated premium positioning specialists, and pharmacy-channel-anchored OTC health platforms. M&A activity and REACH-compliant excipient sourcing represent the dominant competitive vectors reshaping supply relationships.
Within the botanical specialist tier, Ricola Group AG exemplifies herb-integrated supply chain control, while Haleon plc occupies a position bridging pharmaceutical credibility with mass-market distribution reach. Mondelez International, Inc. anchors the scale-driven archetype through manufacturing infrastructure that spans multiple confectionery categories.
| Leading Market Players |
|---|
| Mondelez International, Inc. |
| Cloetta AB |
| Ricola Group AG |
| Mastix Medica, LLC |
| Ernest Jackson Ltd. |
| Haleon plc |
| Reckitt Benckiser Group PLC |
| Perrigo Company PLC |
| The Procter & Gamble Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned Swiss and German botanical specialists anchor supply discipline through captive herb cultivation and cold-compression expertise, translating upstream control into premium pricing power that commodity-grade competitors cannot replicate. Their integrated ownership structures resist margin erosion from volatile erythritol feedstock markets while sustaining pharmacy-channel premiums.
Pricing Analysis
Volume concentrates in standard-tier lozenges sold through supermarket and convenience channels, while margin pools in premium botanical formulations commanding pharmacy shelf placement. Three-tier pricing structure across premium, standard, and economy levels separates Swiss herb-integrated products from synthetic-active competitors and private-label alternatives. Cost compression in standard-tier gummies is intensifying because corn-derived sugar alcohol feedstock costs fluctuate with commodity grain markets. Pharmacy buyers exhibit lowest price sensitivity for clinically positioned cough suppressants, whereas convenience-store consumers of seasonal throat lozenges demonstrate highest elasticity.
Supply Chain Analysis
REACH-compliant excipient qualification gates European market access, forcing manufacturers to pre-validate plant-based actives and biodegradable packaging formats before commercialization. Supply concentrates in Switzerland, Germany, and the United States, where cold-compression engineering talent and FDA-EMA dual-track compliance infrastructure cluster. Raw material dependencies include Swiss alpine herb supplies, corn-derived erythritol feedstocks, and pharmaceutical-grade gelatin or pectin matrices. Single-source vulnerability runs through Swiss herb supply chains controlled by vertically integrated specialists. Distribution runs through pharmacy chains in Japan and the United States, supermarket consolidation networks in Germany, and direct-to-clinic physician dispensing models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs and cold-compression talent scarcity are forcing consolidation as sub-scale manufacturers exit rather than absorb capital-intensive equipment retooling.
For Market Incumbents: Deepen backward integration into Swiss and Bavarian herb cultivation to lock in premium raw material access that synthetic competitors cannot replicate. Acquire cold-compression engineering talent in New Jersey and Pennsylvania manufacturing clusters to secure seasonal capacity surge capability. Defend pharmacy-channel positioning by accelerating biodegradable wrapper validation ahead of EU packaging waste directive deadlines. For New Entrants and Emerging Players: Enter via direct-to-clinic physician dispensing of probiotic lozenges, bypassing retail markup concentration and building prescriber loyalty before scaling to pharmacy distribution. Target pediatric precision dosing segments where micro-tablet formats with verified child-resistant packaging address unmet family cough-cold needs. Pursue white-label contract manufacturing partnerships with mid-size German producers seeking REACH-compliant excipient sourcing allies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size contract manufacturers with validated cold-compression capabilities in Baden-Württemberg and Bavaria, where REACH compliance burdens exceed standalone capital access. Long-term viability hinges on five-to-ten year pharmacy-channel density expansion in METI-supported Japanese markets and Medicare Advantage-aligned US access channels. Watch for inflection signals in erythritol feedstock cost stabilization that would restore margin expansion to reformulated product lines.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Excipient Sourcing | ECHA substance restrictions accelerate plant-based active adoption among European contract manufacturers. |
| Cold-Compression Capacity Expansion | Automation investment in Pennsylvania and New Jersey clusters reduces batch-to-batch variation for seasonal demand surges. |
| Biodegradable Packaging Transition | EU packaging waste directive compliance demands capital-intensive single-dose wrapper redesign ahead of reduction targets. |
| Direct-to-Clinic Distribution Buildout | Physician office dispensing bypasses retail markup and builds prescriber loyalty for probiotic lozenge lines. |
| Pediatric Precision Dosing Development | Micro-tablet formats with verified child-resistant packaging capture unmet family cough-cold segment demand. |
Study Parameters
Regulatory filings from FDA, EMA, and PMDA, trade customs data from Germany and Japan, and pharmacy-channel procurement databases formed the secondary backbone of this analysis. Primary interviews with cold-compression process engineers, pharmacy category buyers, contract manufacturing executives, and herb supply chain managers validated demand assumptions and pricing dynamics. Bottom-up product-line volume estimates triangulated against top-down category spending data from Medicare Advantage plan disclosures and METI retail health infrastructure reports.
Historical trendline analysis of lozenge, gummy, and tablet shipment volumes informed base-case trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, active ingredient class, distribution channel, and target demographic dimensions with regional regulatory cluster overlays. CAGRs derived from weighted-average growth assumptions applied to each segment, with cross-validation against pharmacy-channel expansion rates and sugar alcohol feedstock cost indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained erythritol commodity volatility or accelerated EU packaging waste directive enforcement. Forecasts reflect assumptions about REACH substance evaluation timelines, METI-supported pharmacy density expansion curves, and Medicare Advantage OTC wellness incentive continuity. A model refresh is warranted upon material change in FDA-EMA classification convergence negotiations or breakthrough adoption of dissolvable oral strip substitutes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Postpartum Health Supplements Market