
 Pet Herbal Supplements Market | 2026-2036
Pet Herbal Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Herbal Supplements Market Analytics
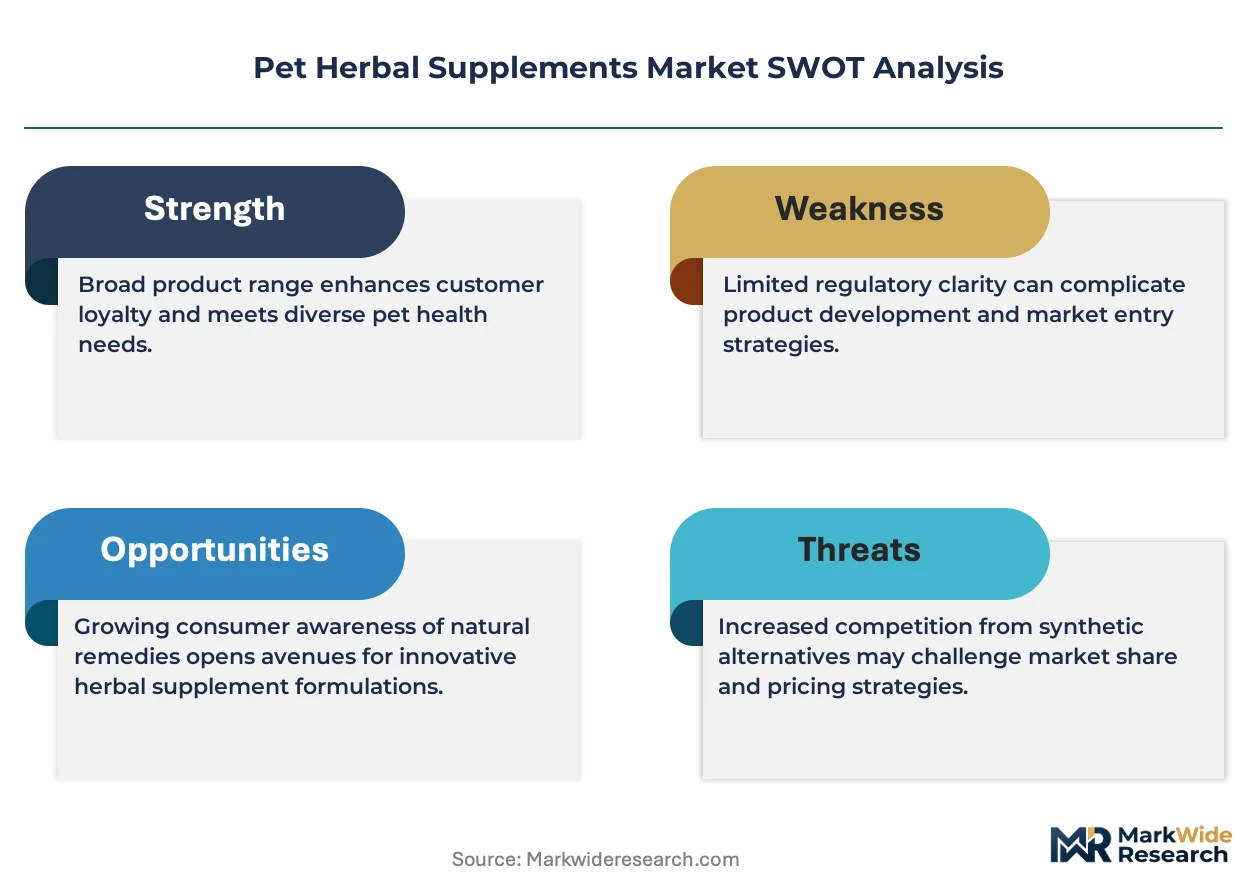
Capital-intensity divergence between large-scale extract processors and small-batch herbal formulators is reorganizing competitive tiers in pet supplements. Only Natural Pet LLC leverages vertical integration across organic sourcing and direct-to-consumer channels to sustain margin control. NaturVet anchors its position through pharmacy-grade manufacturing standards that dominate veterinary clinic distribution. Dorwest Herbs Ltd. specializes in British-grown botanical supply chains that differentiate its product line from commodity competitors.
Pet herbal supplements comprise phytochemical preparations derived from plant materials such as turmeric rhizomes containing standardized curcuminoid concentrations, formulated for oral administration to companion animals to support physiological functions including joint mobility, digestive balance, and behavioral calmness. Oil extracts lead product-type revenue due to superior bioavailability and dosing precision for canine applications. Chewables represent the fastest-expanding format as palatability engineering improves acceptance rates among cats and small mammals. Powders retain strong positioning in the avian segment where precise titration of chamomile-based calming blends remains essential for exotic veterinary protocols.
The FDA Center for Veterinary Medicine shapes U.S. market access through enforcement discretion policies distinguishing supplements from unapproved animal drugs. The National Animal Supplement Council operates a quality seal program that filters non-compliant manufacturers from premium retail placement. The EU Feed Additives Regulation, enforced by EFSA member-state authorities, mandates novel botanical safety dossiers that constrain European formulation innovation. Stakeholders must monitor evolving pharmacovigilance requirements for herbal actives as regulators tighten evidentiary standards for structure-function claims across major pet-care economies.
Market Dynamics
Millennial pet ownership patterns are compressing product development cycles as calming formulations for anxious companion animals command disproportionate shelf space and veterinary recommendation protocols.
Growth Catalysts
- EU Feed Additives Regulation:EFSA-mandated safety dossiers for novel botanicals are filtering out commodity competitors and elevating pharmacy-grade manufacturers into premium distribution channels.
- Direct-to-consumer channel expansion:Digital-native pet owners in Germany and the United States are bypassing traditional retail intermediaries, accelerating margin capture for vertically integrated formulators.
- Chamomile and valerian extraction technologies:Supercritical CO2 methods are improving standardization of active compound concentrations, enabling precise dosing protocols for feline stress management applications.
Market Restraints
- FDA enforcement discretion volatility:The Center for Veterinary Medicine's evolving distinction between supplements and unapproved animal drugs creates approval timeline uncertainty for structure-function claim submissions.
- Organic botanical supply concentration:British-grown chamomile and turmeric rhizome sourcing clusters in limited certified organic acreage, exposing formulators to harvest yield variability and input cost spikes.
- Bioavailability limitations of powder formats:Poor intestinal absorption of unencapsulated curcuminoid preparations restricts efficacy demonstration in avian and small mammal applications.
Strategic Opportunities
- Veterinary clinic channel underpenetration:German veterinary practices currently stock limited herbal SKUs, creating white space for pharmacy-grade manufacturers with EFSA-compliant dossiers.
- Chewable palatability engineering convergence:Flavor masking technologies combined with cold-pressed oil infusion are opening feline acceptance rates previously blocked by bitter phytochemical profiles.
- National Animal Supplement Council quality seal:The NASC certification program offers a regulatory tailwind for compliant U.S. manufacturers seeking premium retail placement separation from unverified competitors.
Industry Challenges
- Pharmacovigilance reporting infrastructure:Veterinary clinics lack standardized adverse event documentation systems for herbal actives, complicating post-market surveillance obligations under tightening EFSA requirements.
- Structure-function claim substantiation:The FDA's demand for clinical evidence supporting physiological function claims requires capital-intensive study designs that strain small-batch formulator R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Herbal Supplements Market |
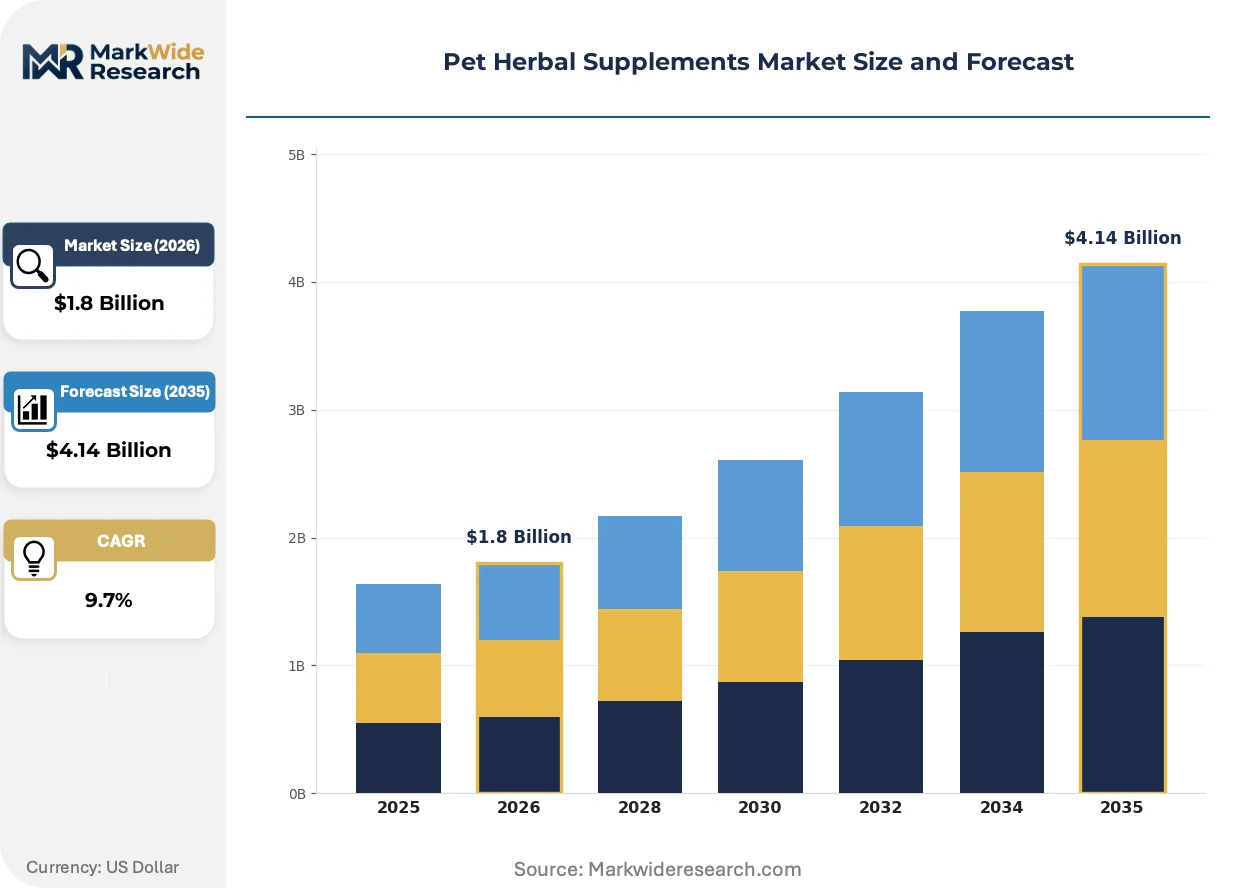
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Extracts, Chewables, Powders, Capsules Active Ingredient: Turmeric, Ginger, Chamomile, Valerian Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Online Retail, Veterinary Clinics, Pet Stores, Health Food Stores |
| Companies Covered | Only Natural Pet LLC, NaturVet, Blackmores, AMORVET, Dorwest Herbs Ltd., Pet Natural Remedies, AdvaCare Pharma, Natural Dog Company Inc., Rockwell Pets Pro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Herbal Supplements Market Evolving Landscape
Formulation science and distribution architecture are undergoing parallel transformation as bioavailability engineering and channel disintermediation reshape competitive advantage sources.
Liposomal encapsulation technology is supplanting conventional oil-based delivery systems by shielding curcuminoid and valerian actives from gastric degradation. Veterinary formulators in Germany and the United States are adopting these delivery platforms at accelerating pace for joint mobility and behavioral calmness applications. This technology compression is enabling structure-function claims with stronger pharmacokinetic backing, separating premium tier manufacturers from commodity extract suppliers.
REACH-compliant botanical sourcing standards are extending from human nutraceuticals into companion animal applications, forcing European manufacturers to document full supply chain substance safety. The European Chemicals Agency's expanded registration requirements are increasing formulation costs for non-compliant processors. German and British formulators with pre-existing REACH dossiers are capturing market access advantages as retailers demand certified clean label credentials.
Subscription-based replenishment models are displacing episodic retail purchasing among digitally engaged millennial pet owners in the United States. Direct-to-consumer platforms with automated dosing reminders and veterinary telehealth integration are capturing recurring revenue streams previously fragmented across pet specialty stores. This channel shift concentrates most visibly in urban coastal markets where veterinary clinic density supports hybrid online-offline service models.
Pet Herbal Supplements Market Segmentation
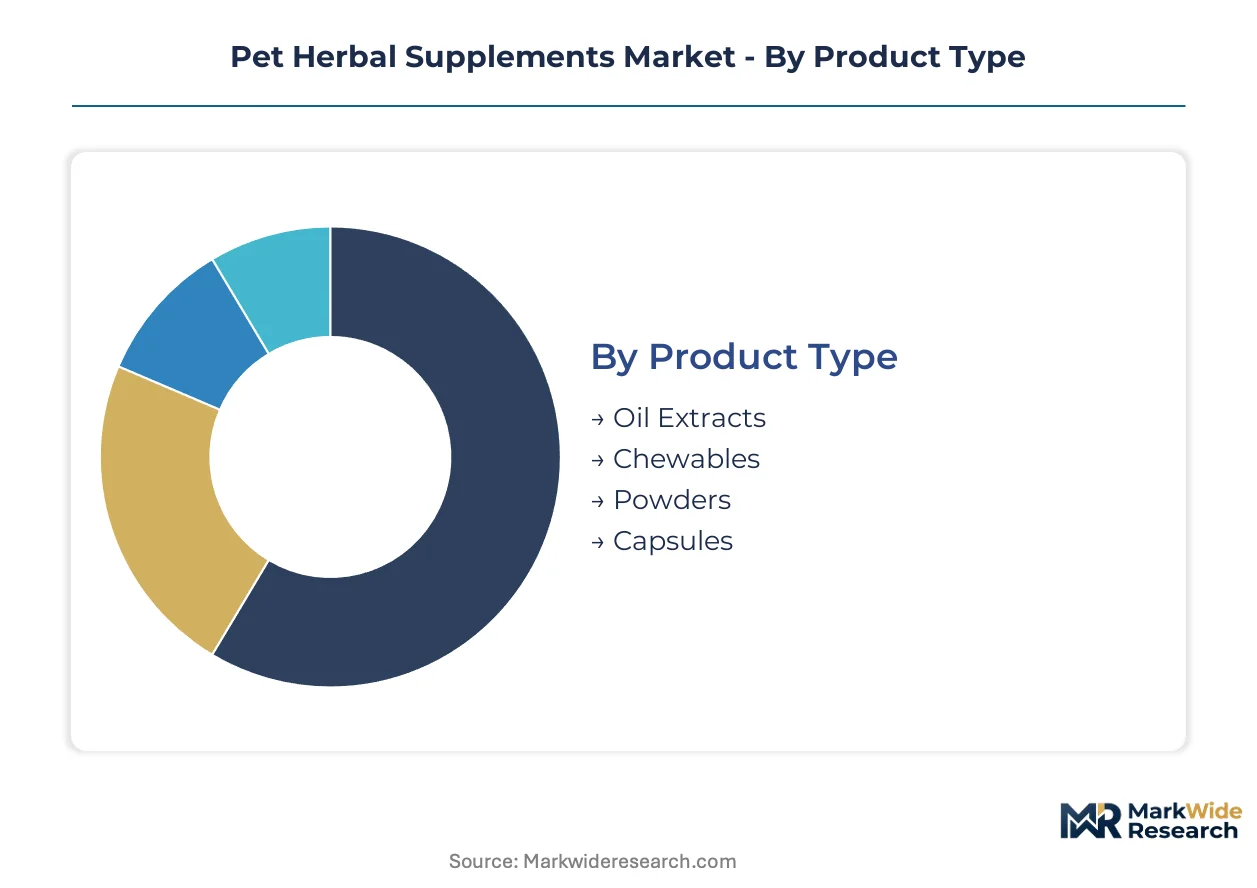
Pet herbal supplement manufacturers navigate divergent regulatory pathways depending on formulation format and active compound classification. Segmentation strategy determines channel access, manufacturing investment, and claim substantiation requirements across veterinary and consumer markets.
Product Type:
FDA enforcement discretion applies unevenly across delivery formats, with oil extracts facing lighter scrutiny than encapsulated actives making implied drug claims.
- Oil Extracts:Lipophilic phytochemical suspensions in carrier oils enable superior intestinal absorption of curcuminoids and valerian acids. Demand concentrates in canine applications across the United States, driven by veterinary endorsement of measurable serum concentration thresholds.
- Chewables:Palatable matrix formulations incorporate cold-pressed oil infusions with flavor masking systems to overcome bitter alkaloid profiles. German pet owners are accelerating purchases for feline stress management as palatability engineering improves acceptance rates previously blocked by taste aversion.
- Powders:Standardized botanical granules allow precise titration for exotic veterinary protocols.
- Capsules:Enteric-coated gelatin shells protect gastric-sensitive actives but trigger stricter regulatory review.
Established volume favors Oil Extracts; emerging adoption favors Chewables.
Active Ingredient:
EFSA novel botanical dossier requirements have restructured competitive access, with legacy ingredients grandfathered under feed additive precedents while new entrants face safety study burdens.
- Turmeric:Rhizome-derived curcuminoid preparations target joint mobility support through cyclooxygenase pathway modulation. British organic acreage constraints concentrate supply risk among processors dependent on certified harvests.
- Chamomile:Flavonoid-rich flower heads deliver anxiolytic effects via GABA receptor modulation. United States millennial pet owners are compressing development cycles for canine calming formulations commanding disproportionate shelf space.
- Ginger:Gingerol concentrates address digestive motility disorders in companion animals.
- Valerian:Sesquiterpene extracts require supercritical CO2 standardization to achieve reproducible dosing.
Chamomile anchors current revenue; turmeric carries supply-side vulnerability.
Animal Type:
Species-specific metabolism and dosing precision requirements fragment manufacturing scale economies across veterinary and consumer segments.
- Dogs:Large body mass enables cost-effective oil-based delivery with measurable pharmacokinetic endpoints. German veterinary clinics increasingly stock chamomile formulations for behavioral protocols.
- Cats:Obligate carnivore metabolism and finicky consumption patterns demand specialized palatability engineering. United States direct-to-consumer channels are capturing recurring revenue through subscription models targeting urban millennial ownership clusters.
- Birds:Avian metabolic sensitivity requires precise powder titration for exotic veterinary applications.
- Small Mammals:Rodent and rabbit formulations face bioavailability constraints with unencapsulated actives.
Canine applications dominate manufacturing scale; feline segments are climbing the fastest.
Distribution Channel:
Channel selection determines margin capture, regulatory exposure, and customer acquisition cost structures for formulators at varying scale.
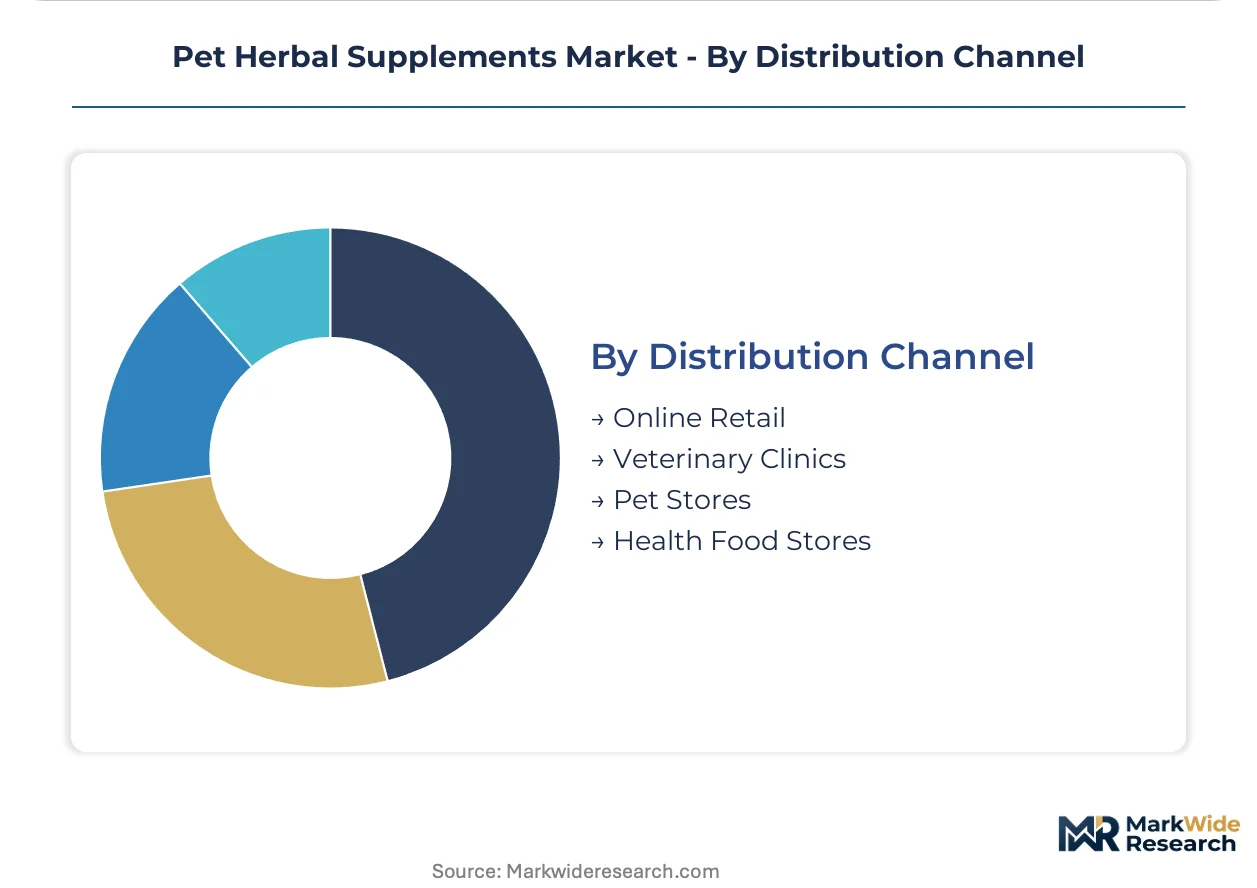
- Online Retail:Direct-to-consumer platforms with automated replenishment and telehealth integration bypass traditional retail intermediaries. United States coastal urban markets show highest subscription penetration among digitally native pet owners.
- Veterinary Clinics:Pharmacy-grade manufacturing standards and EFSA-compliant dossiers unlock premium placement. German practices currently stock limited herbal SKUs, creating white space for compliant manufacturers.
- Pet Stores:NASC quality seal programs filter non-compliant suppliers from premium shelf placement.
- Health Food Stores:Human nutraceutical crossover demand extends into companion animal adjacencies.
Veterinary channels command price premiums; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States consumers absorb premium pricing for pharmacy-grade formulations, while German buyers demand EFSA-compliant certification at moderate price points. Emerging markets prioritize cost-accessible oil extracts over advanced delivery technologies.
United States
Millennial pet owners in coastal urban markets drive subscription-based replenishment for canine calming formulations. FDA Center for Veterinary Medicine enforcement discretion policies create approval uncertainty for structure-function claims. Los Angeles and New York Metro clusters concentrate direct-to-consumer platforms with veterinary telehealth integration.
Germany
Veterinary clinics in Bavaria and North Rhine-Westphalia accelerate chamomile and valerian stocking for feline stress protocols. EFSA novel botanical dossier requirements filter non-compliant suppliers from premium channels. Munich-based formulators with REACH-compliant sourcing capture retailer preference for certified clean label credentials.
United Kingdom
British-grown botanical supply chains concentrate in limited certified organic acreage, exposing processors to harvest variability. Dorwest Herbs anchors regional production through captive chamomile cultivation in Somerset and Wiltshire. London veterinary practices increasingly recommend standardized extracts over commodity powders.
China
Domestic pet ownership expansion in Shanghai and Beijing generates demand for imported turmeric and ginger formulations. SAMR and NMPA oversight of animal health products creates registration bottlenecks for foreign entrants. Yangtze River Delta distributors build cold-chain infrastructure for temperature-sensitive oil extracts.
Canada
Health Canada PMRA guidelines on veterinary health products shape market access for U.S.-origin supplements. Ontario and British Columbia veterinary networks prefer NASC-equivalent quality assurance seals. Toronto-area retailers stock hybrid human-pet nutraceutical lines from crossover manufacturers.
Pet Herbal Supplements Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmacy-grade manufacturers commanding veterinary clinic placement while commodity extractors serve price-sensitive retail. Three archetypes dominate: vertically integrated formulators controlling organic sourcing, pharmacy-standard manufacturers with EFSA dossiers, and direct-to-consumer platforms with subscription infrastructure. Capacity expansion in supercritical CO2 extraction and strategic partnerships with veterinary telehealth providers represent the dominant competitive moves.
Among North American integrated players, Only Natural Pet LLC exemplifies the vertically controlled archetype through captive organic supply chains. NaturVet occupies the pharmacy-grade tier with manufacturing standards aligned to veterinary distribution requirements. Dorwest Herbs Ltd. anchors the British-grown botanical specialist position, representing regional supply chain differentiation against commodity competitors. These three entities illustrate how certification depth and channel control separate premium positioning from volume-driven alternatives.
| Leading Market Players |
|---|
| Only Natural Pet LLC |
| NaturVet |
| Blackmores |
| AMORVET |
| Dorwest Herbs Ltd. |
| Pet Natural Remedies |
| AdvaCare Pharma |
| Natural Dog Company Inc. |
| Rockwell Pets Pro |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction technology replacing conventional solvent-based methods simultaneously redraws procurement geography around German and British processing clusters and compresses unit economics for standardized actives. Millennial pet owners absorbing subscription premiums for veterinary-grade formulations now fund capital equipment amortization that commodity extractors cannot match.
Pricing Analysis
Recurring replenishment revenue from automated subscription platforms now exceeds one-time transactional margins as the dominant lifetime value driver. Three-tier pricing structure across pharmacy-grade, NASC-certified, and unverified economy levels separates EFSA-compliant manufacturers commanding veterinary clinic premiums from direct-to-consumer challengers. Cost compression in economy-tier oil extracts is intensifying because British organic acreage constraints limit certified turmeric and chamomile supply. Small-batch formulators exhibit highest price sensitivity due to R&D study burdens for FDA structure-function claims, while vertically integrated incumbents absorb input volatility through captive sourcing.
Supply Chain Analysis
Somerset and Wiltshire organic cultivation zones in the United Kingdom constitute the primary chokepoint for EFSA-preferred chamomile supply. British certified acreage, German supercritical processing capacity, and United States direct-to-consumer fulfillment infrastructure anchor the tripartite supply architecture. Raw material dependencies center on turmeric rhizomes, valerian rootstock, and gelatin capsule shells. Single-source vulnerability runs through limited British organic harvests exposed to climate yield variability. Distribution runs through veterinary clinic networks in Germany, subscription platforms in United States coastal markets, and pet specialty retail intermediaries elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services now expand faster than hardware margins, transforming pet herbal supplements into a service-attach business where automated dosing reminders and telehealth integration capture recurring revenue previously lost to episodic retail.
For Market Incumbents: Secure EFSA-compliant dossiers for novel botanicals before regulatory tightening closes the grandfathering window for legacy ingredients. Deepen backward integration into British certified organic acreage to defend margin position against harvest volatility that commodity competitors cannot hedge. Lock in supercritical CO2 extraction capacity in Bavaria and North Rhine-Westphalia to preempt capacity scarcity as veterinary clinic demand accelerates. For New Entrants and Emerging Players: Telehealth integration gaps in United States direct-to-consumer channels offer white-space entry where incumbents under-serve urban millennial clusters seeking hybrid online-offline veterinary guidance. Target German veterinary practices currently stocking limited herbal SKUs with pharmacy-grade formulations and EFSA dossiers ready for clinic adoption. Pursue cold-pressed oil infusion partnerships with feline palatability engineering specialists to overcome taste aversion barriers blocking incumbent penetration. For Investors and Strategic Acquirers: FDA enforcement discretion evolution reshapes the acquisition landscape by elevating manufacturers with substantiated structure-function claims above commodity extractors facing approval timeline risk. Five-to-ten year viability favors vertically integrated formulators controlling organic sourcing and subscription infrastructure over single-channel distributors. Watch NASC quality seal penetration rates in United States premium retail as the inflection signal separating compliant acquisition targets from stranded commodity assets.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | German processors achieve EFSA-mandated standardization thresholds that solvent-based competitors cannot replicate. |
| Subscription Platform Integration | United States direct-to-consumer channels capture recurring revenue through automated replenishment and dosing reminders. |
| EFSA Dossier Investment | Pharmacy-grade manufacturers unlock veterinary clinic placement as novel botanical safety requirements filter commodity suppliers. |
| British Organic Acreage Acquisition | Captive chamomile cultivation in Somerset and Wiltshire insulates margin against certified supply concentration. |
| Veterinary Telehealth Partnership | Hybrid online-offline service models in Los Angeles and New York Metro clusters reduce customer acquisition costs. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary formulators, regulatory affairs specialists at animal health companies, procurement managers at German clinic networks, and direct-to-consumer platform operators and refined through secondary validation. Sources included FDA Center for Veterinary Medicine enforcement discretion policy documents, EFSA novel botanical safety dossier filings, National Animal Supplement Council quality seal program records, and trade data on British organic herb exports. Bottom-up demand modeling across product formats and animal types triangulated against top-down market sizing from channel revenue analysis.
Variance decomposition across the projection horizon isolates volume drivers by product type, active ingredient classification, animal species metabolism requirements, and distribution channel regulatory exposure. CAGRs derive from segment-level growth rate reconciliation with macro pet ownership trends and veterinary recommendation pattern shifts. Forecast inputs incorporate EFSA dossier approval timelines, FDA structure-function claim substantiation study costs, and supercritical CO2 extraction capacity expansion pipelines.
Forecasts assume regulatory continuity in FDA enforcement discretion policies and EFSA novel botanical requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as pharmacovigilance reporting infrastructure standardization and REACH-compliant sourcing mandate expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Cold Remedies Market