
 Robotic Desktop Automation (RDA) Market | 2026-2036
Robotic Desktop Automation (RDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Desktop Automation (RDA) Market Outlook
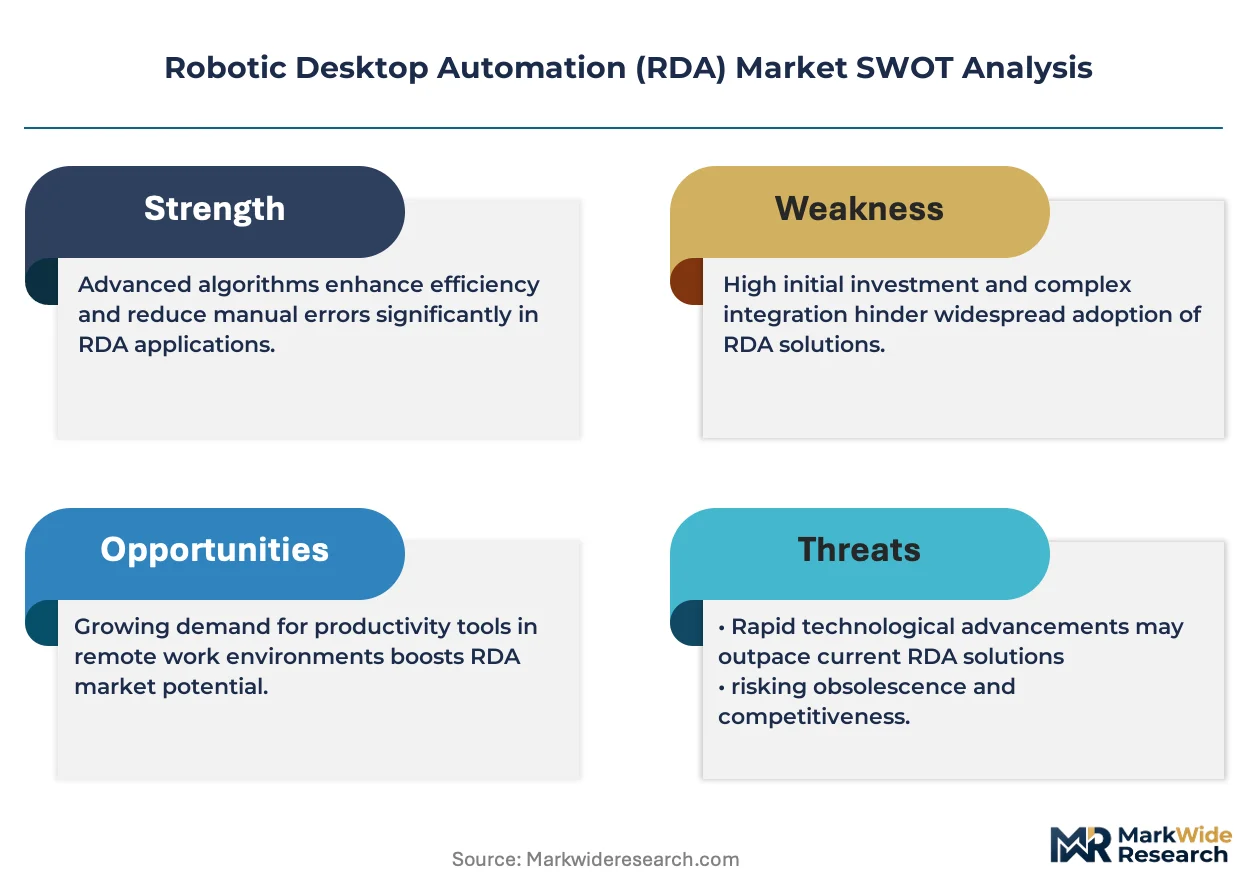
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring subscription and usage-based models. UiPath leverages its extensive partner ecosystem to sustain deployment velocity across mid-market accounts. Automation Anywhere anchors its competitive position through cloud-native architecture that reduces infrastructure overhead for distributed workforces. SS&C Blue Prism specializes in regulated industries where audit trails and governance controls carry premium pricing power.
Robotic Desktop Automation comprises software agents that execute repetitive tasks through user interface interactions, API calls, and data layer manipulations, typically operating at keystroke-level granularity with response latencies under 200 milliseconds for attended workflows. Its primary commercial purpose is to augment human workers by automating data entry, form population, and cross-application synchronization without requiring full-scale enterprise platform overhauls. Cloud-based deployment now captures the fastest expansion as IT departments prioritize elastic scaling and reduced on-premises maintenance burdens, while legacy system integration commands premium pricing due to scarce technical expertise in mainframe and AS/400 connectivity. Full automation solutions dominate large corporation budgets, though assisted automation is gaining traction among government agencies seeking human-in-the-loop controls for sensitive citizen data processing.
The EU AI Act and GDPR compliance frameworks are reshaping vendor product roadmaps toward explainable automation logs and explicit consent mechanisms for data handling. The US SEC and FINRA examination priorities are driving financial services adopters toward RDA tools with embedded surveillance and exception reporting capabilities. Enterprises must evaluate whether their current desktop automation stacks satisfy emerging algorithmic accountability requirements before regulatory examination cycles intensify.
Market Dynamics
The EU AI Act's transparency mandates are forcing European enterprises to retire opaque scripting methods in favor of auditable automation logs, compressing vendor evaluation cycles and reshaping procurement criteria toward governance-first platforms.
Growth Catalysts
- EU AI Act compliance deadlines:German automotive suppliers and French insurers are accelerating RDA deployments to satisfy algorithmic accountability requirements before examination cycles intensify.
- Legacy ERP modernization:Industrial conglomerates in Germany are bridging SAP R/3 and AS/400 systems with cloud applications through attended automation workflows.
- Cloud-native architecture preference:Distributed financial services workforces are prioritizing elastic scaling over on-premises maintenance burdens, expanding subscription revenue pools.
Market Restraints
- Scarce mainframe connectivity expertise:AS/400 and IBM z/OS integration skills concentrate among aging specialist workforces in Stuttgart and Munich, creating supply bottlenecks.
- GDPR consent mechanism complexity:Explicit data handling permissions add 15-20% to implementation timelines for citizen-facing government workflows.
- Attended automation labor substitution limits:Human-in-the-loop requirements for sensitive data processing cap unattended deployment ratios in public sector contracts.
Strategic Opportunities
- Underpenetrated Mittelstand segment:Mid-sized German manufacturers with fragmented application landscapes represent a white space for standardized attended automation packages.
- SEC examination tailwinds:US broker-dealers are embedding surveillance capabilities into RDA stacks ahead of FINRA priority cycles, creating premium pricing for exception-reporting features.
- API-overlay convergence:Hybrid agents combining UI scraping with direct system integration are collapsing deployment friction for cloud-migration projects.
Industry Challenges
- Cobol and RPG skill scarcity:Integration projects requiring mainframe data layer manipulation face 6-9 month talent acquisition timelines in Düsseldorf and Frankfurt.
- Cross-border data residency conflicts:German enterprises operating GDPR-governed workflows across EU member states encounter fragmented supervisory authority interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Desktop Automation (RDA) Market |
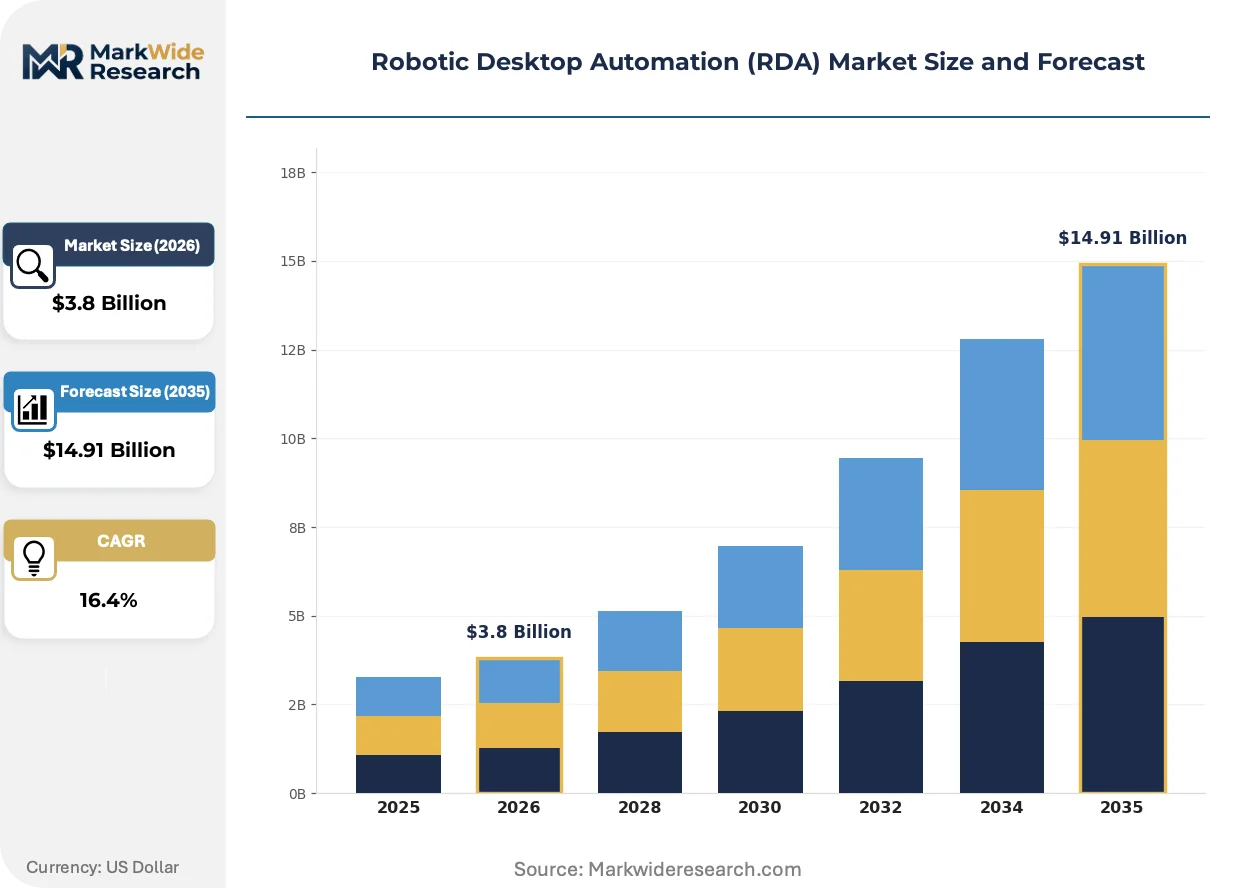
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote End User: Small Enterprises, Mid-size Organizations, Large Corporations, Government Agencies Solution Type: Full Automation, Assisted Automation, Workflow Automation, Task Automation Integration Level: API Integration, UI Integration, Data Integration, Legacy System Integration |
| Companies Covered | Microsoft Power Automate, Pega Platform, UiPath, Tungsten RPA, IBM RPA, Automation Anywhere, WorkFusion, Appian, SS&C Blue Prism, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Desktop Automation (RDA) Market Strategic Shifts
Automation architecture is bifurcating between lightweight attended agents for knowledge workers and heavy-duty unattended orchestration for back-office operations, with hybrid deployment models capturing the fastest expansion as IT departments reconcile elasticity with auditability.
Low-code process discovery tools are collapsing the traditional six-month assessment phase into weeks. Banking operations teams in Frankfurt are deploying these platforms to map customer onboarding workflows without external consultancy. The compression is reallocating budget toward actual bot development rather than diagnostic services.
The EU AI Act's risk classification framework is forcing vendors to reengineer logging architectures. Financial institutions in Paris and Amsterdam are demanding explainable decision trails for credit decision automation. The mandate is accelerating differentiation between governance-native platforms and retrofitted legacy tools.
Subscription pricing for attended seats is displacing perpetual licensing in mid-market procurement. German automotive suppliers are negotiating consumption-based contracts tied to monthly active user counts. The shift is visible most acutely among firms with seasonal workforce fluctuations.
Robotic Desktop Automation (RDA) Market Segmentation
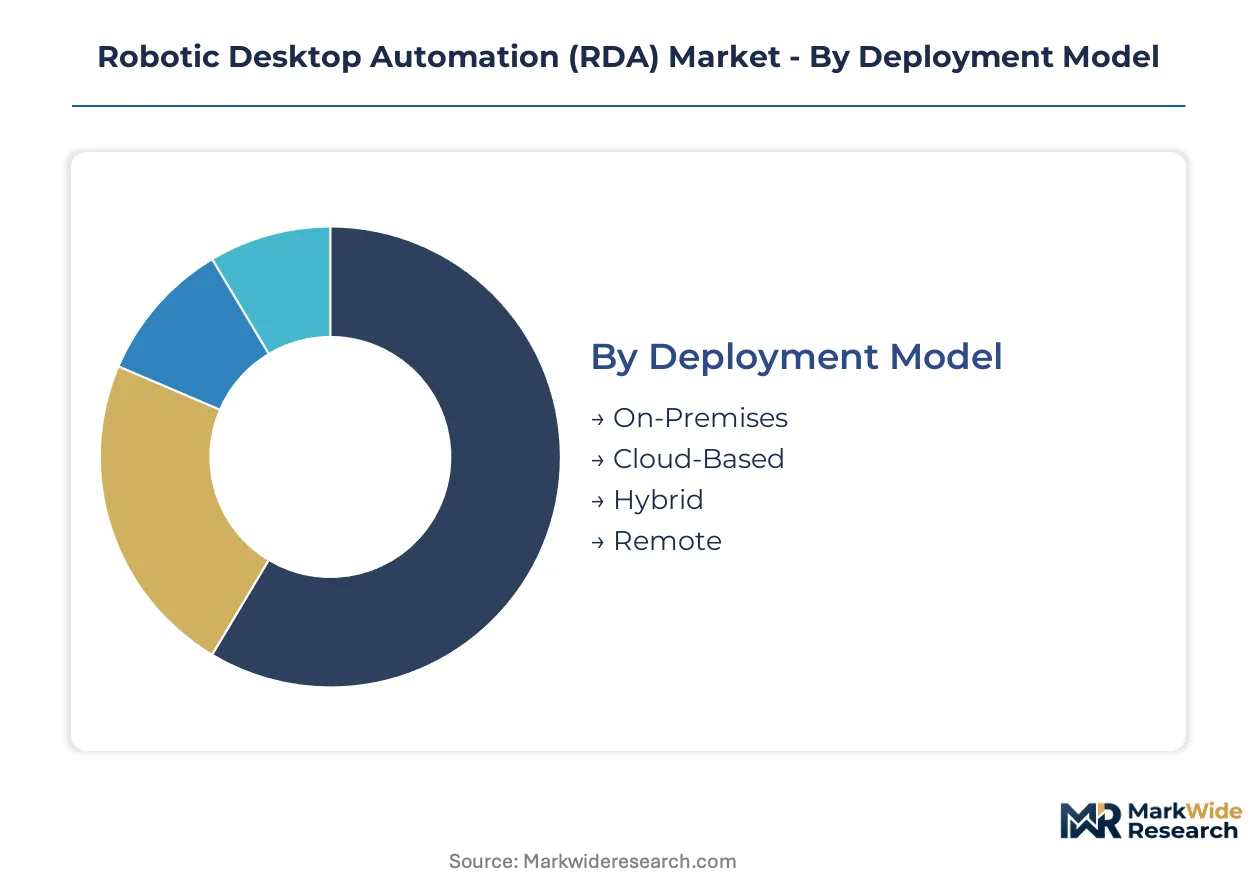
Segmentation in the RDA market reveals divergent procurement patterns between legacy-heavy industrial adopters and cloud-native service enterprises. Deployment architecture, organizational scale, and integration depth collectively determine pricing power and vendor selection criteria across buyer categories.
Deployment Model:
Mature on-premises installations anchor established manufacturing workflows, while emerging cloud-native configurations capture fastest expansion among distributed financial services teams.
- On-Premises:Local server installations with sub-200ms response latency for attended workflows. German automotive suppliers in Stuttgart and Wolfsburg maintain these deployments for air-gapped production environments where data sovereignty overrides elasticity requirements.
- Cloud-Based:Elastic scaling architectures reducing infrastructure overhead for distributed workforces. French insurers and Dutch banks are migrating here to satisfy EU AI Act auditability mandates without capital-intensive hardware refresh cycles.
- Hybrid:Split orchestration combining on-premises control planes with cloud execution nodes. Mid-market manufacturers in Düsseldorf favor this for seasonal workforce fluctuations.
- Remote:Edge-deployed agents serving home-based knowledge workers. German Mittelstand firms accelerated adoption post-pandemic for customer service teams.
On-Premises handles the majority of throughput; Cloud-Based is expanding most quickly on share.
End User:
Cost tier stratification separates premium governance controls for regulated institutions from standardized attended packages for mid-market manufacturers.
- Small Enterprises:Low-code attended automation with pre-built connectors for SaaS applications. Fragmented application landscapes in German family-owned manufacturers drive demand for rapid deployment without dedicated IT staff.
- Mid-size Organizations:Consumption-based contracts tied to monthly active user counts. Seasonal workforce patterns in automotive suppliers favor this pricing model.
- Large Corporations:Heavy-duty unattended orchestration with embedded surveillance capabilities. US broker-dealers embed these ahead of FINRA examination cycles.
- Government Agencies:Human-in-the-loop controls for sensitive citizen data processing. GDPR consent mechanisms add implementation complexity for German federal and state workflows.
Large Corporations dominate current vendor revenue; Government Agencies are climbing the fastest as public sector digitization accelerates.
Solution Type:
Application intensity varies from keystroke-level task execution to comprehensive workflow orchestration across enterprise systems.
- Full Automation:End-to-end unattended execution eliminating human touchpoints. Back-office operations in Frankfurt banking centers deploy these for high-volume transaction processing.
- Assended Automation:Human-in-the-loop configurations with real-time exception handling. French insurers prioritize these for credit decision workflows requiring explainable audit trails under EU AI Act.
- Workflow Automation:Cross-application process orchestration spanning multiple systems. Legacy ERP modernization projects in Munich industrial conglomerates leverage this capability.
- Task Automation:Single-action agents for data entry and form population. Knowledge workers in Amsterdam financial services use these for repetitive interface interactions.
Full Automation commands the largest project budgets; Assisted Automation is gaining share fastest on regulatory tailwinds.
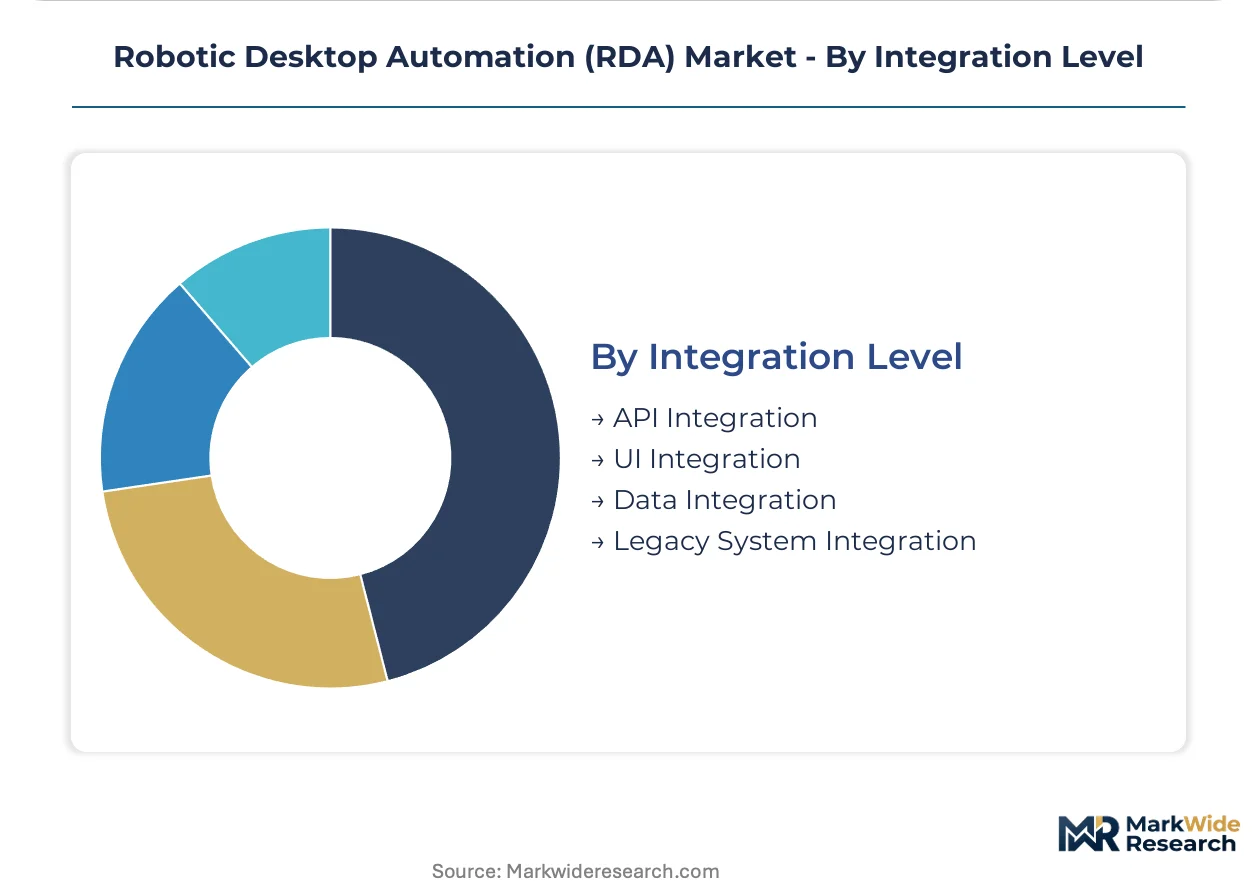
Integration Level:
Supply concentration in scarce technical expertise creates premium pricing for mainframe connectivity versus commoditized API overlay solutions.
- API Integration:Direct system-to-system calls eliminating UI dependency. Cloud-migration projects in Paris financial services favor this for reduced brittleness.
- UI Integration:Keystroke-level screen scraping and form interaction. Legacy applications without exposed APIs require this approach in older manufacturing environments.
- Data Integration:Direct database layer manipulation for batch processing. Stuttgart specialists command premium rates for AS/400 and IBM z/OS connectivity skills.
- Legacy System Integration:Bridging mainframe, AS/400, and SAP R/3 with modern cloud applications. Six-to-nine month talent acquisition timelines in Frankfurt constrain deployment velocity.
Legacy System Integration captures the steepest pricing premiums; API Integration is the fastest-expanding configuration as cloud-native architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial conglomerates deploy RDA for legacy ERP bridging, while US financial services prioritize embedded surveillance capabilities. French insurers and Dutch banks favor cloud-native architectures to satisfy EU AI Act mandates. This consumption-mix differential reflects divergent regulatory pressures and legacy system burdens across major markets.
United States
SEC examination priorities and FINRA enforcement cycles drive broker-dealers toward RDA stacks with exception-reporting features. The Dodd-Frank Act's operational risk requirements reinforce demand for auditable automation logs. New York and Chicago financial centers anchor deployment velocity for surveillance-embedded solutions.
Germany
Industrial conglomerates in Stuttgart and Munich bridge SAP R/3 and AS/400 systems with cloud applications through attended automation. The EU AI Act's algorithmic accountability mandates compress vendor evaluation cycles toward governance-first platforms. Mittelstand manufacturers in Baden-Württemberg represent underpenetrated demand for standardized attended packages.
France
Insurers in Paris deploy assisted automation for credit decision workflows requiring explainable audit trails. CNIL guidance on automated decision-making reinforces explicit consent mechanisms for data handling. The Île-de-France banking cluster drives premium pricing for human-in-the-loop configurations.
United Kingdom
Financial services firms in London prioritize hybrid deployment models reconciling elasticity with FCA operational resilience requirements. The UK GDPR framework maintains data protection standards post-Brexit. The City of London's back-office operations command heavy-duty unattended orchestration for high-volume transaction processing.
Netherlands
Dutch banks migrate to cloud-native RDA architectures to reduce infrastructure overhead for distributed workforces. The Dutch Central Bank's operational risk guidelines emphasize auditability in automation deployments. Amsterdam's financial services sector favors API-overlay solutions for cloud-migration projects.
Robotic Desktop Automation (RDA) Market Competitive Environment
Capability concentration sits with specialized governance-native platforms; scale advantage sits with ecosystem-leveraged generalists. The vendor landscape organizes around three strategic archetypes: cloud-native architects reducing infrastructure burdens, legacy integration specialists commanding premium pricing for scarce mainframe skills, and governance-first platforms embedding compliance controls. Dominant competitive moves include partner ecosystem expansion to sustain deployment velocity and reengineering of logging architectures to satisfy emerging regulatory mandates.
Within the ecosystem-leveraged tier, UiPath and Microsoft Power Automate occupy positions reflecting distinct scale advantages. Automation Anywhere exemplifies cloud-native architecture specialization. SS&C Blue Prism anchors the governance-first segment where audit trails and compliance controls carry premium pricing power. These three company representations illustrate how vendor selection criteria increasingly prioritize regulatory readiness over pure automation throughput.
| Leading Market Players |
|---|
| Microsoft Power Automate |
| Pega Platform |
| UiPath |
| Tungsten RPA |
| IBM RPA |
| Automation Anywhere |
| WorkFusion |
| Appian |
| SS&C Blue Prism |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's concentration of mainframe integration specialists commands premium billing rates for AS/400 and IBM z/OS connectivity, directly inflating project costs for German automotive suppliers bridging legacy ERP systems with cloud applications. This geographic skill scarcity creates pricing power for legacy integration vendors while compressing margins for standardized attended automation packages.
Pricing Analysis
Long-term enterprise licensing contracts dominate procurement among large financial institutions, though consumption-based SaaS subscriptions tied to monthly active user counts are displacing perpetual sales in the Mittelstand segment. Price differentiation rests on governance certification tiers and integration complexity depth, with EU AI Act-compliant audit trail features carrying substantial premiums. Cost compression in the mid-market intensifies as low-code platforms reduce deployment friction. Government agencies exhibit highest price sensitivity due to budget approval cycles, while regulated financial services show lowest sensitivity where surveillance-embedded capabilities satisfy SEC examination priorities.
Supply Chain Analysis
Contract manufacturing concentration for RDA platform components sits with specialized software development houses in India, Poland, and Romania, where engineering talent pools support cloud-native architecture development. Core technology inputs draw from open-source automation frameworks, proprietary AI/ML inference engines, and legacy system connectivity libraries. Single-source vulnerability concentrates in mainframe middleware expertise concentrated among aging specialist workforces in southern Germany. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for complex legacy modernization deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as regulatory mandates splinter procurement criteria between governance-first platforms and cost-optimized attended automation, enabling specialist vendors to capture premium segments without challenging scale leaders head-on.
For Market Incumbents: Harden competitive moats by acquiring boutique mainframe connectivity specialists in Stuttgart and Munich before talent scarcity escalates integration project costs. Deepen vertical integration into explainable AI logging architectures to satisfy EU AI Act algorithmic accountability requirements ahead of examination cycle intensification. Prioritize partner ecosystem expansion to sustain deployment velocity across mid-market accounts where low-code competitors erode traditional consulting attach rates. For New Entrants and Emerging Players: Mid-sized German manufacturers with fragmented SAP landscapes and no dedicated IT staff represent the most penetrable entry point for standardized attended automation packages delivered through channel partners. French insurers navigating CNIL guidance on automated credit decisions offer a secondary white space for human-in-the-loop workflow tools with embedded consent mechanisms. A vertical-specific go-to-market angle targeting automotive supplier compliance documentation workflows bypasses direct competition with generalist platforms. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwind play because algorithmic accountability mandates across EU and US financial services create durable demand for audit-native automation platforms regardless of macroeconomic cycles. Acquisition targets should display governance-first architecture with pre-built connectors to legacy ERP systems. The signal to watch is FINRA examination priority shifts toward real-time surveillance capabilities, which would accelerate premium pricing for exception-reporting features.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | UiPath's partner ecosystem sustains deployment velocity across mid-market manufacturing accounts. |
| Acquisition of Specialist Firm | SS&C Blue Prism's governance controls capture premium pricing in SEC-regulated broker-dealer segments. |
| Product Launch | Automation Anywhere's cloud-native architecture reduces infrastructure overhead for distributed French banking teams. |
| Strategic Partnership | Microsoft Power Automate's SaaS bundling penetrates government agencies through existing enterprise agreements. |
| Geographic Expansion | WorkFusion's Frankfurt presence targets Mittelstand ERP bridging demand with localized implementation support. |
Study Parameters
Initial hypotheses were tested against primary input from RDA platform engineers, enterprise IT procurement officers, systems integration specialists, and regulatory compliance leads at financial institutions, then refined through secondary validation against SEC examination priority disclosures, EU AI Act implementation guidance, FINRA enforcement bulletins, and vendor SEC 10-K filings. Bottom-up deployment volume estimates triangulated with top-down addressable market calculations across the analysis window.
Demand-supply balance modeling segmented projections by deployment architecture, organizational scale, solution type, and integration complexity depth, with CAGRs derived from elasticity-adjusted adoption curves and replacement cycle analysis. Cloud-migration velocity, legacy system obsolescence timelines, and regulatory examination cycle phasing served as industry-specific forecast inputs throughout the projection horizon.
Practitioners should monitor EU AI Act enforcement consistency across member state supervisory authorities and FINRA examination priority shifts for early signals requiring forecast revision. Cross-checking against hyperscaler automation capex disclosures and enterprise software spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Servo Gripper Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Inspection Robots Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Smart Exoskeleton Market