
 Hand Care Market | 2026-2036
Hand Care Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Care Market Outlook
Plant-derived surfactants is rebalancing cost structures away from petroleum-based alternatives across hand wash and sanitizer formulations. Procter & Gamble Company leverages its captive supply of renewable feedstocks to secure margin stability in volatile input markets. Unilever PLC anchors its portfolio through concentrated formulations that reduce water content and shipping weight. Henkel AG & Co. KGaA specializes in professional-grade dispensers and refills that dominate European hospital procurement channels.
Hand care encompasses topical preparations designed to cleanse, protect, or restore skin barrier function, typically formulated with emollients, humectants, and antimicrobial agents at pH levels between 4.5 and 6.5 to maintain acid mantle integrity. These products serve industrial, clinical, and consumer settings where repeated washing or chemical exposure elevates dermatitis risk. Moisturizers command the largest revenue pool due to daily-use frequency across household and professional segments, while antiseptics capture premium pricing in healthcare and foodservice compliance environments. Organic formulations are gaining shelf space fastest in North American and Western European retail, though synthetic bases still dominate institutional contracts where cost-per-use metrics govern procurement.
The EPA regulates antimicrobial claims on hand sanitizers and washes in the United States, requiring efficacy data that shapes product development timelines and label positioning. REACH and the EU Green Deal constrain preservative selections and mandate biodegradability thresholds that reformulation pipelines must address. FDA oversight of healthcare antiseptics continues to evolve around emerging resistance concerns and clinical outcome requirements. Stakeholders must track how tightening state-level ingredient disclosure laws in California and New York will cascade into national formulation standards and supplier qualification protocols.
Market Dynamics
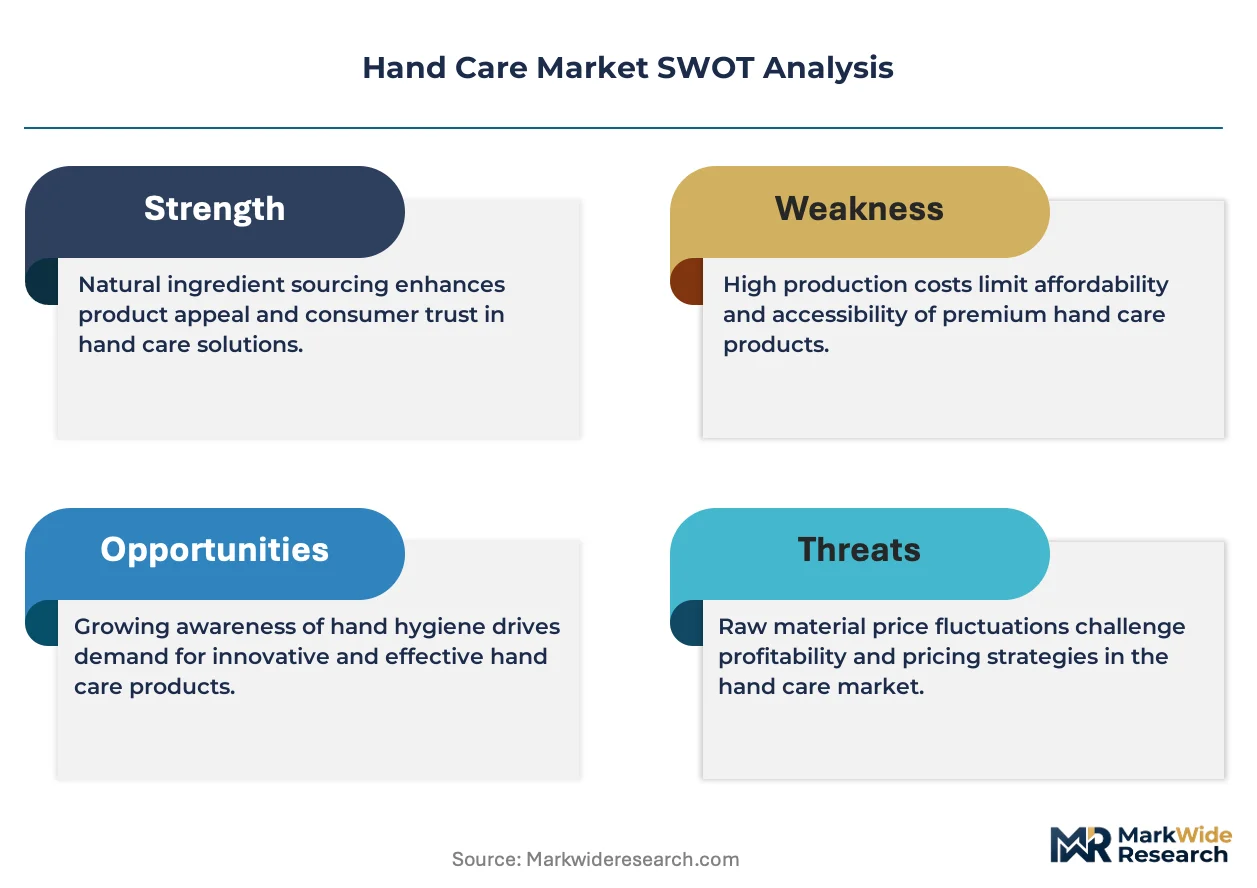
Hospital hygiene protocols are tightening procurement standards for clinical-grade hand care, forcing reformulation pipelines to reconcile efficacy claims with REACH-mandated biodegradability thresholds and EPA antimicrobial registration timelines.
Growth Catalysts
- REACH compliance deadlines:European formulators accelerating plant-derived surfactant adoption to meet EU Green Deal biodegradability mandates ahead of 2030 enforcement windows.
- Foodservice sector:Commercial kitchens in the United States expanding antiseptic dispenser deployments to satisfy FDA Food Code handwashing frequency requirements.
- Coconut-derived feedstocks:Southeast Asian oleochemical supply chains stabilizing input costs for manufacturers pivoting from petroleum-based emollients.
Market Restraints
- Palm oil price volatility:La Niña weather patterns disrupting Malaysian and Indonesian harvests, compressing margins on mass-market moisturizer lines.
- Isopropyl alcohol concentration:US Gulf Coast petrochemical capacity constraints limiting sanitizer production scale-up during demand spikes.
- Preservative approval bottlenecks:ECHA's stricter hazard classification for MIT/CMIT blends forcing emergency reformulation of legacy hospital hand rubs.
Strategic Opportunities
- Indian institutional procurement:CDSCO streamlining antiseptic registration pathways for domestic manufacturers supplying government hospital networks.
- Refill dispenser ecosystems:Concentrated formulation chemistry enabling subscription-based restocking models in European office and hospitality verticals.
- Biometric compliance tracking:Integration of hand hygiene monitoring sensors with enterprise IoT platforms creating bundled service revenue pools.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in acid mantle-compatible antimicrobial systems concentrated among retiring European laboratory directors.
- EPA registration timelines:New active ingredient approvals stretching 36-48 months, delaying pipeline commercialization for emerging biocidal technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Care Market |
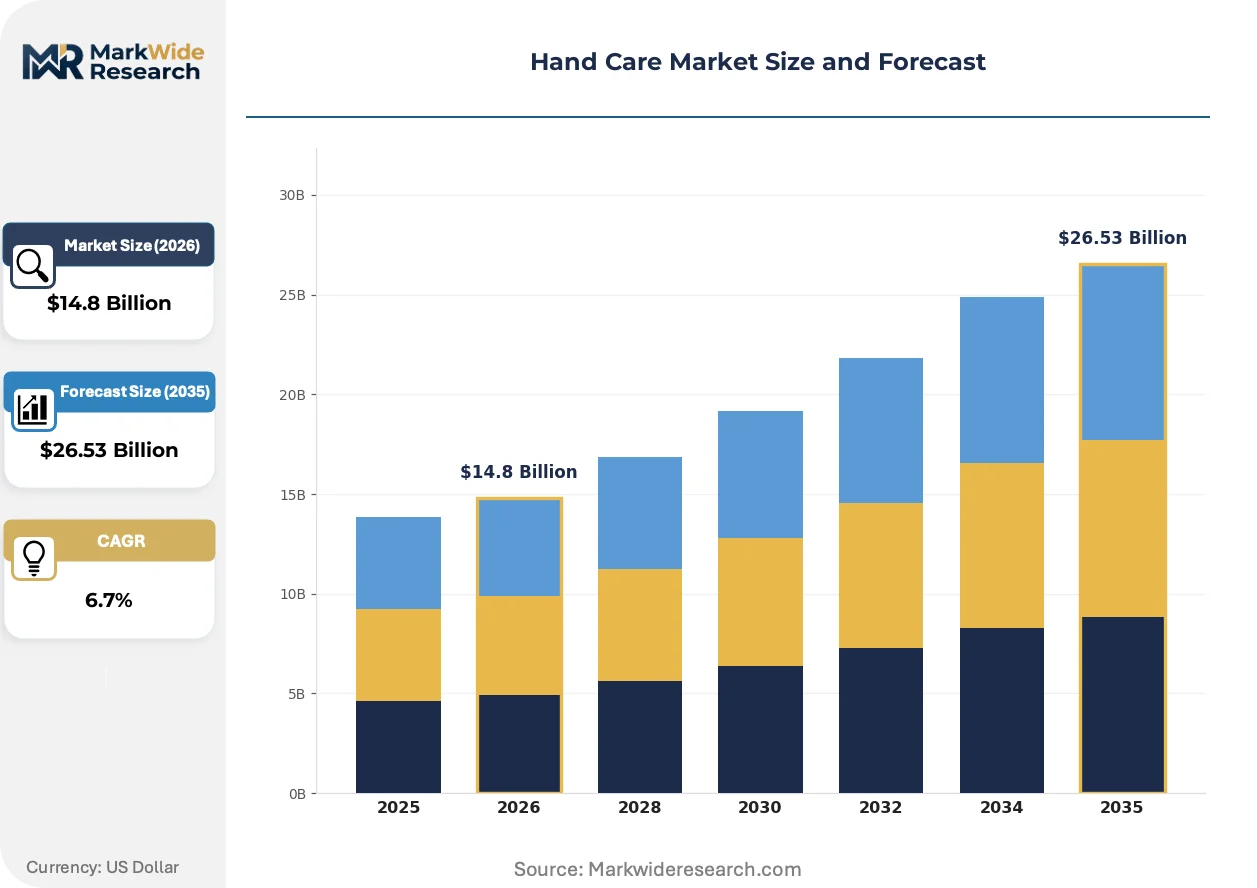
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Exfoliators, Antiseptics, Treatments End User: Household, Healthcare Professionals, Salons, Businesses Formulation: Organic, Synthetic, Natural, Hypoallergenic Packaging Type: Tubes, Bottles, Jars, Pouches |
| Companies Covered | Procter & Gamble Company, Unilever PLC, Reckitt Benckiser Group plc, Colgate-Palmolive Company, The Clorox Company, Johnson & Johnson, Kimberly-Clark Corporation, Henkel AG & Co. KGaA, GOJO Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Care Market Strategic Shifts
Active ingredient transparency is reshaping competitive positioning as institutional buyers demand chain-of-custody documentation and retail consumers scan ingredient databases before purchase decisions.
Alkyl polyglucoside surfactants synthesized from corn and potato starch deliver comparable foaming performance to sodium lauryl sulfate while satisfying OECD 301 biodegradability standards. Hospital procurement committees in Germany and France are overtaking retail channels as the primary volume adopters, compressing the premium pricing window for legacy petroleum-derived formulations.
California's Cleaning Product Right to Know Act and New York's ingredient disclosure mandates are cascading into de facto national standards, compelling formulators to restructure supply chain documentation systems. Manufacturers serving multi-state distribution networks now face fragmented compliance architectures that favor centralized reformulation over SKU proliferation.
Healthcare system consolidation is compressing vendor qualification cycles as integrated delivery networks centralize purchasing decisions across dozens of affiliated facilities. Group purchasing organizations now dictate antimicrobial efficacy thresholds that exceed FDA baseline requirements, squeezing mid-tier suppliers unable to fund expanded clinical testing programs. This concentration is most visible in Texas and Florida hospital systems, where three buyers control antiseptic procurement for over forty percent of licensed beds.
Hand Care Market Segmentation
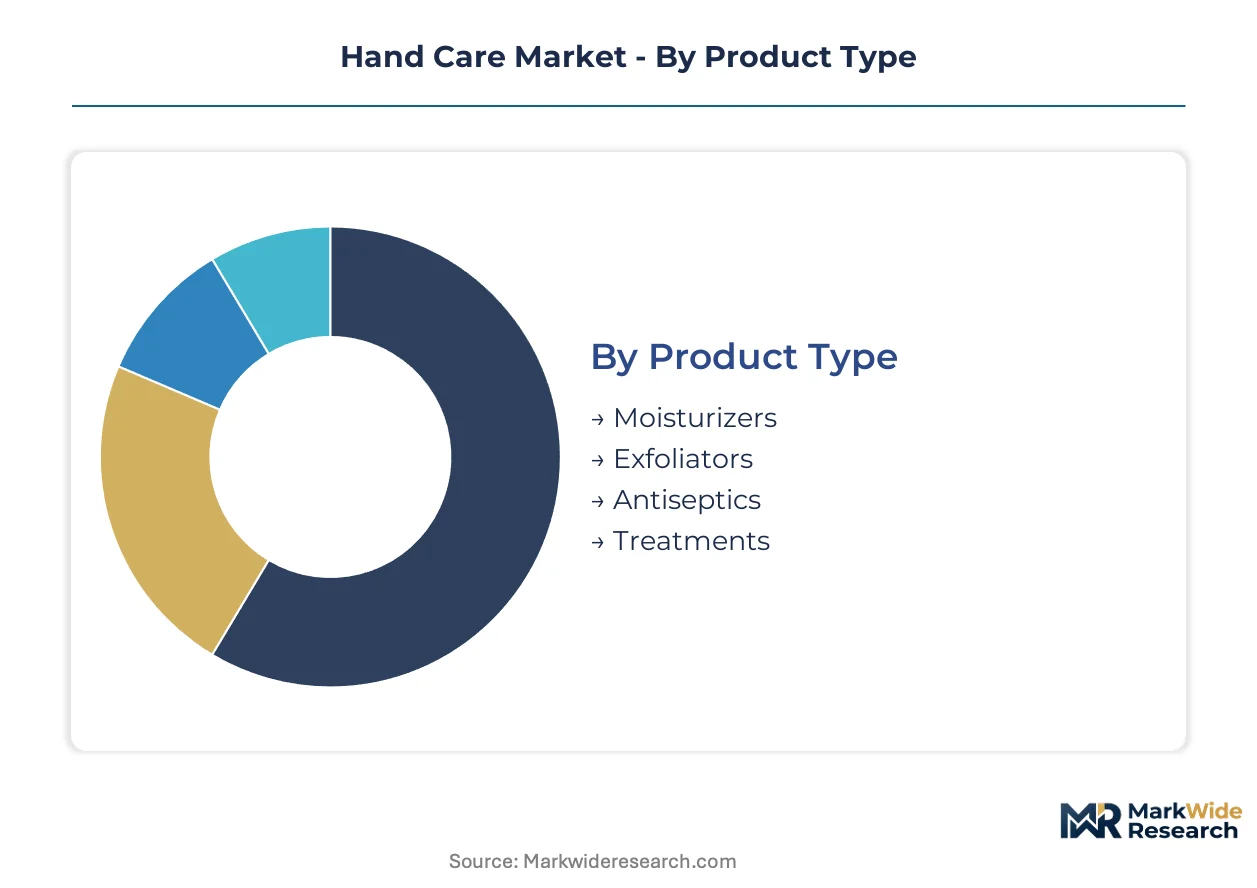
Segmentation in hand care reflects divergent performance requirements across clinical compliance, aesthetic outcomes, and daily maintenance routines. Formulators must balance acid mantle compatibility with antimicrobial efficacy while navigating packaging sustainability mandates and procurement cost thresholds.
Product Type:
Customization intensity varies sharply across this category, from commodity moisturizers with minimal SKU variation to antiseptics requiring site-specific efficacy documentation.
- Moisturizers:Emollient-rich formulations incorporating humectants and occlusive agents at pH 4.5-6.5 to restore barrier function after repeated washing. Demand concentrates in United States household and healthcare procurement channels where daily-use frequency drives volume economics. EPA and FDA registration requirements for antimicrobial variants compress margin structures on clinical-grade lines.
- Antiseptics:Alcohol-based or chlorhexidine formulations delivering log-reduction efficacy against nosocomial pathogens. Hospital procurement committees in Germany and France dominate volume uptake as EU Green Deal biodegradability mandates force reformulation away from legacy petroleum-derived bases.
- Exfoliators:Mechanical or chemical agents removing keratinized skin layers, primarily serving salon and premium retail segments.
- Treatments:Targeted therapies for dermatitis, eczema, or occupational skin damage, requiring dermatological validation.
Leading the category by volume: Moisturizers. Expanding most quickly: Antiseptics.
End User:
Cost tier stratification separates mass-market household consumption from premium-priced professional compliance environments.
- Healthcare Professionals:Clinical-grade hand rubs and surgical scrubs subject to FDA antiseptic monograph and EPA registration timelines. United States hospital systems and European NHS trusts drive procurement centralization, with three buyers controlling antiseptic sourcing for over forty percent of licensed beds in Texas and Florida networks.
- Household:Daily-use cleansers and moisturizers purchased through retail channels, with organic formulations gaining shelf space fastest in North American and Western European markets.
- Salons:Service-oriented consumption requiring aesthetic performance and fragrance differentiation.
- Businesses:Corporate and hospitality procurement of dispenser systems and bulk refills.
Dominant by procurement scale: Healthcare Professionals. Steepest expansion trajectory: Household organic lines.
Formulation:
Supply concentration in Southeast Asian oleochemical feedstocks is rebalancing cost structures between synthetic and plant-derived alternatives.
- Organic:Plant-derived surfactants and emollients certified to USDA Organic or ECOCERT standards, commanding premium pricing in United States and Western European retail. REACH-mandated biodegradability thresholds and California's Cleaning Product Right to Know Act accelerate adoption.
- Synthetic:Petroleum-derived bases still dominating institutional contracts where cost-per-use metrics govern procurement, though margin pressure from palm oil volatility and Gulf Coast petrochemical capacity constraints is mounting.
- Natural:Botanically sourced ingredients without full organic certification, occupying mid-tier pricing.
- Hypoallergenic:Fragrance-free, preservative-minimized formulations for sensitive skin populations.
Widest volume base: Synthetic. Gaining share fastest: Organic.
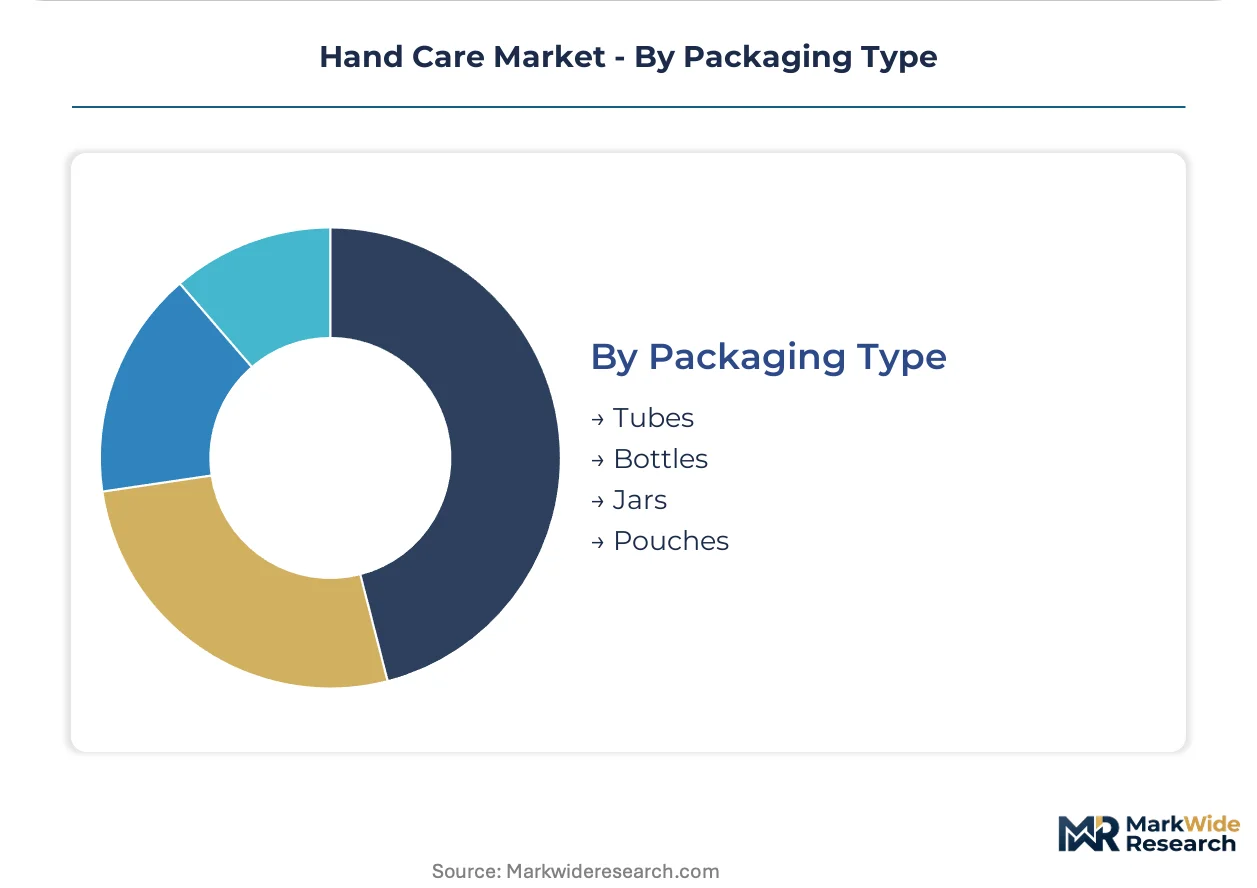
Packaging Type:
Customer type differentiation separates single-use convenience formats from institutional refill systems.
- Tubes:Portable, hygienic dispensing for household and travel segments, with aluminum laminate structures replacing plastic in premium European lines.
- Bottles:Standard retail format with pump or flip-cap dispensing, dominating mass-market moisturizer distribution.
- Jars:Wide-mouth containers for thick cream formulations, primarily serving salon and spa channels.
- Pouches:Concentrated refill formats enabling dispenser ecosystem models in European office and hospitality verticals, reducing shipping weight and plastic intensity.
Highest shipment volume: Bottles. Climbing the fastest: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States institutional buyers and premium retail channels concentrate demand for clinical-grade moisturizers and antiseptics. Healthcare system consolidation in Texas and Florida has compressed vendor qualification cycles. REACH-mandated biodegradability thresholds and EPA registration timelines are reshaping cross-border formulation strategies.
United States
Hospital procurement centralization dominates antiseptic volume, with three buyers controlling sourcing for over forty percent of licensed beds in Texas and Florida networks. FDA antiseptic monograph requirements and EPA registration timelines govern clinical-grade product development. Cleveland Clinic and Mayo Clinic procurement committees are setting efficacy thresholds exceeding baseline regulatory requirements.
Germany
Hospital procurement committees in Germany and France are overtaking retail channels as primary volume adopters of plant-derived surfactants. EU Green Deal biodegradability mandates and ECHA hazard classifications are accelerating reformulation away from legacy petroleum bases. The Rhine-Ruhr industrial corridor hosts concentrated dispenser manufacturing and professional-grade refill production.
China
Domestic manufacturers are scaling alkyl polyglucoside surfactant production from corn and potato starch feedstocks. NMPA registration pathways and GB standards for antimicrobial efficacy are tightening documentation requirements. The Yangtze River Delta clusters surfactant synthesis capacity serving both domestic hospital networks and export markets.
India
CDSCO is streamlining antiseptic registration pathways for domestic manufacturers supplying government hospital networks. Institutional procurement expansion targets tier-two and tier-three city healthcare infrastructure. Maharashtra and Gujarat host concentrated oleochemical processing capacity for coconut-derived emollient feedstocks.
France
ANSM oversight of healthcare antiseptics is converging with ECHA preservative hazard reclassifications. Paris-based procurement consortiums are mandating chain-of-custody documentation for active ingredient transparency. The Île-de-France region concentrates formulation R&D and dermatological validation laboratories.
Hand Care Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring established registrants and retail channels fragmenting toward niche organic entrants. The market exhibits tiered concentration: multinational FMCG conglomerates dominate mass-market moisturizers, European specialists capture professional dispenser ecosystems, and regional formulators serve price-sensitive institutional contracts. Two strategic archetypes predominate: captive renewable feedstock integrators securing margin stability, and concentrated formulation chemists reducing logistics intensity. Competitive moves center on EPA registration acceleration and Southeast Asian oleochemical supply chain anchoring.
Within the multinational FMCG tier, Procter & Gamble Company and Unilever PLC exemplify divergent feedstock strategies. P&G leverages captive renewable supply chains to buffer volatile input markets. Unilever anchors portfolio positioning through water-reduction chemistry that compresses shipping weight. Henkel AG & Co. KGaA occupies the professional-grade specialization vector, with its GmbH structure signaling European corporate governance aligned to hospital procurement channel dominance.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Unilever PLC |
| Reckitt Benckiser Group plc |
| Colgate-Palmolive Company |
| The Clorox Company |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Henkel AG & Co. KGaA |
| GOJO Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal biodegradability mandates gate qualified supply and premium-tier pricing access, forcing formulators to absorb reformulation costs or cede institutional contracts to competitors with REACH-certified plant-derived surfactant pipelines. Hospital procurement committees now require chain-of-custody documentation that synthetic-base suppliers cannot furnish, compressing margins on legacy petroleum-derived lines while elevating pricing power for certified organic entrants.
Pricing Analysis
Volume concentrates in synthetic-base moisturizers serving mass-market retail, while margins accrue to clinical-grade antiseptics with EPA registration and organic certification. Price differentiation hinges on biodegradability compliance tier and antimicrobial efficacy documentation depth. Cost compression in mass-market tiers intensifies because palm oil volatility disrupts emollient input costs. Household consumers exhibit highest price sensitivity, whereas hospital procurement committees prioritize total-cost-of-ownership metrics over unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian palm oil harvests exposed to La Niña weather pattern disruption. Manufacturing gravity centers on Germany, the United States, and China for dispenser systems and formulation finishing. Feedstock dependencies encompass coconut-derived oleochemicals, corn and potato starch for alkyl polyglucoside synthesis, and Gulf Coast petrochemical outputs. Tariff exposure on Southeast Asian oleochemical imports poses structural risk. Distribution runs through hospital group purchasing organizations in Texas and Florida, European NHS trusts, and North American retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-derived surfactant chemistry is displacing petroleum-based emollient systems, creating asymmetric exposure for incumbents with captive renewable feedstock pipelines versus legacy synthetic-base dependent competitors.
For Market Incumbents: Anchor margin stability through backward integration into Southeast Asian oleochemical processing capacity, securing coconut-derived feedstock supply before CDSCO registration pathways flood Indian institutional procurement with domestic competitors. Prioritize EPA registration acceleration for emerging biocidal actives to outpace 36-48 month approval bottlenecks that delay pipeline commercialization. For New Entrants and Emerging Players: Tier-two and tier-three Indian city hospital networks present the most penetrable procurement channel, with CDSCO streamlining antiseptic registration for domestic manufacturers supplying government infrastructure. Target refill dispenser ecosystem contracts in European office and hospitality verticals where concentrated formulations enable subscription-based restocking models with lower capital intensity than retail shelf-space competition. For Investors and Strategic Acquirers: ECHA hazard reclassifications forcing emergency MIT/CMIT preservative reformulation is the leading indicator that formulation chemist expertise scarcity will consolidate among acquirers with European laboratory director networks. Long-term viability over a multi-year horizon favors targets with REACH-compliant plant-derived surfactant pipelines and established hospital procurement committee relationships. Watch for EPA registration timeline compression signals as inflection catalysts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Supply | Captive coconut-derived feedstock procurement buffers Malaysian palm oil price volatility. |
| EPA Registration Acceleration | Expedited antimicrobial active ingredient approval compresses 36-48 month commercialization delays. |
| Refill Dispenser Ecosystem Deployment | Concentrated formulation chemistry enables European office and hospitality subscription revenue pools. |
| Biometric Compliance Tracking Integration | Hand hygiene monitoring sensors bundled with enterprise IoT platforms create service revenue attachment. |
| REACH-Compliant Reformulation Pipeline | Plant-derived surfactant adoption satisfies EU Green Deal biodegradability mandates ahead of enforcement windows. |
Study Parameters
Independent corroboration across procurement directors at Texas and Florida hospital systems, formulation chemists at European laboratory facilities, and category buyers at North American retail chains underwrites the qualitative findings. Primary interviews with GPO contracts managers, dermatological validation specialists, and Southeast Asian oleochemical processors combined with secondary validation from EPA registration databases, ECHA hazard classification filings, and customs trade data. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions.
Rate-of-change decomposition across the analysis window segments volume and value by product type, end user archetype, formulation chemistry, and packaging format, with additional granularity on regulatory compliance tier. CAGRs derive from elasticity-adjusted demand curves incorporating hospital procurement centralization trends and REACH-mandated reformulation timelines. Forecast inputs include oleochemical feedstock price indices and EPA registration pipeline status.
Revisions become necessary when ECHA preservative hazard reclassifications accelerate, La Niña patterns extend beyond historical cycles, or Gulf Coast petrochemical capacity constraints deepen. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Skin Care Emulsion Market
Skincare
Sun-Care Wipes Market
Skincare
Skincare Ingredients Market
Skincare
Global Anti-Aging Market
Skincare
Organic Skincare Products Market
Skincare
Facial Mask Market
Skincare
Dermal Regeneration Market
Skincare
Skin Resurfacing Market
Skincare
Germany Skincare Product Market
Skincare
Dermocosmetics Market
Skincare
Global Healthcare Wipes Market
Skincare
Incontinence Skin Care Products Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Skin Barrier Market
Skincare
Africa Cosmeceutical Market