
 Africa Cosmeceutical Market | 2026-2036
Africa Cosmeceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Cosmeceutical Market Outlook
Young urban professionals across Africa's major cities is unwinding the historical dominance of traditional mass-market cosmetic buyers. L'Oréal SA leverages its dermatological research infrastructure to serve clinic-grade skin care through pharmacy channels in Morocco and Senegal. Unilever PLC anchors its competitive position with localized manufacturing that reduces import dependency for hair care formulations. Ascendis Health Ltd specializes in therapeutic segments where clinician endorsement drives repeat purchase behavior.
Cosmeceuticals constitute topical formulations containing biologically active ingredients at concentrations sufficient to exert physiological effects on skin structure or function, typically manufactured through cold-process emulsification to preserve peptide and antioxidant integrity. These products serve the dermatological, aesthetic, and therapeutic application segments where clinical validation separates premium positioning from commodity cosmetics. Skin care and anti-aging product types command the deepest margin pools due to ingredient complexity and consumer willingness to pay for proven efficacy. The therapeutic application segment is expanding fastest as pharmacy chains across Africa upgrade staff training to recommend condition-specific regimens.
South Africa's National Regulator for Compulsory Specifications enforces ingredient safety thresholds that elevate compliance costs for imported formulations. The ECOWAS harmonization framework for cosmetics standards is reducing cross-border registration friction but demanding unified toxicology documentation across member states. Kenya's Pharmacy and Poisons Board increasingly inspects cosmeceutical claims at port of entry, reshaping how distributors validate product positioning. Stakeholders must monitor which regulatory pathway—national registration versus regional harmonization—delivers faster market access for new active ingredients.
Market Dynamics
ECOWAS harmonization standards are compressing registration timelines while elevating toxicology documentation requirements, forcing reformulators to consolidate multi-country dossiers into unified compliance packages.
Growth Catalysts
- Urban millennial demand:Lagos, Nairobi, and Johannesburg professionals seek science-backed skin care, expanding pharmacy channel throughput for clinically validated products.
- Nigeria's mass-market retail expansion:Supermarket chains upgrade beauty aisles with dedicated cosmeceutical sections, reducing import dependency through localized distribution hubs.
- Cold-process emulsification:This manufacturing technology preserves peptide integrity in anti-aging formulations, enabling longer shelf stability for temperature-vulnerable supply chains.
Market Restraints
- South Africa's NRCS compliance costs:Ingredient safety thresholds force imported brands to reformulate or absorb elevated testing expenses, squeezing margin structures.
- Active ingredient concentration limits:Retinol and hydroquinone caps vary across member states, complicating single-SKU strategies for regional distributors.
- Port-of-entry inspection delays:Kenya's Pharmacy and Poisons Board holds shipments for claim validation, extending working capital cycles for pharmacy-led networks.
Strategic Opportunities
- Morocco's pharmacy channel upgrade:Clinic-grade positioning through trained dermatological staff creates premium pricing power for validated formulations.
- Senegal's underpenetrated therapeutic segment:Condition-specific regimens for hyperpigmentation and eczema remain underserved relative to basic moisturizers.
- Biometric skin analysis integration:AI-driven diagnostic tools in retail settings enable personalized regimen recommendations, lifting conversion rates and basket sizes.
Industry Challenges
- Formulation chemist scarcity:Peptide stability expertise concentrates in South Africa and Egypt, forcing competitors to import technical talent or outsource R&D.
- Multi-jurisdiction dossier management:Divergent ECOWAS implementation timelines create registration lag, requiring parallel track strategies that strain regulatory affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Cosmeceutical Market |
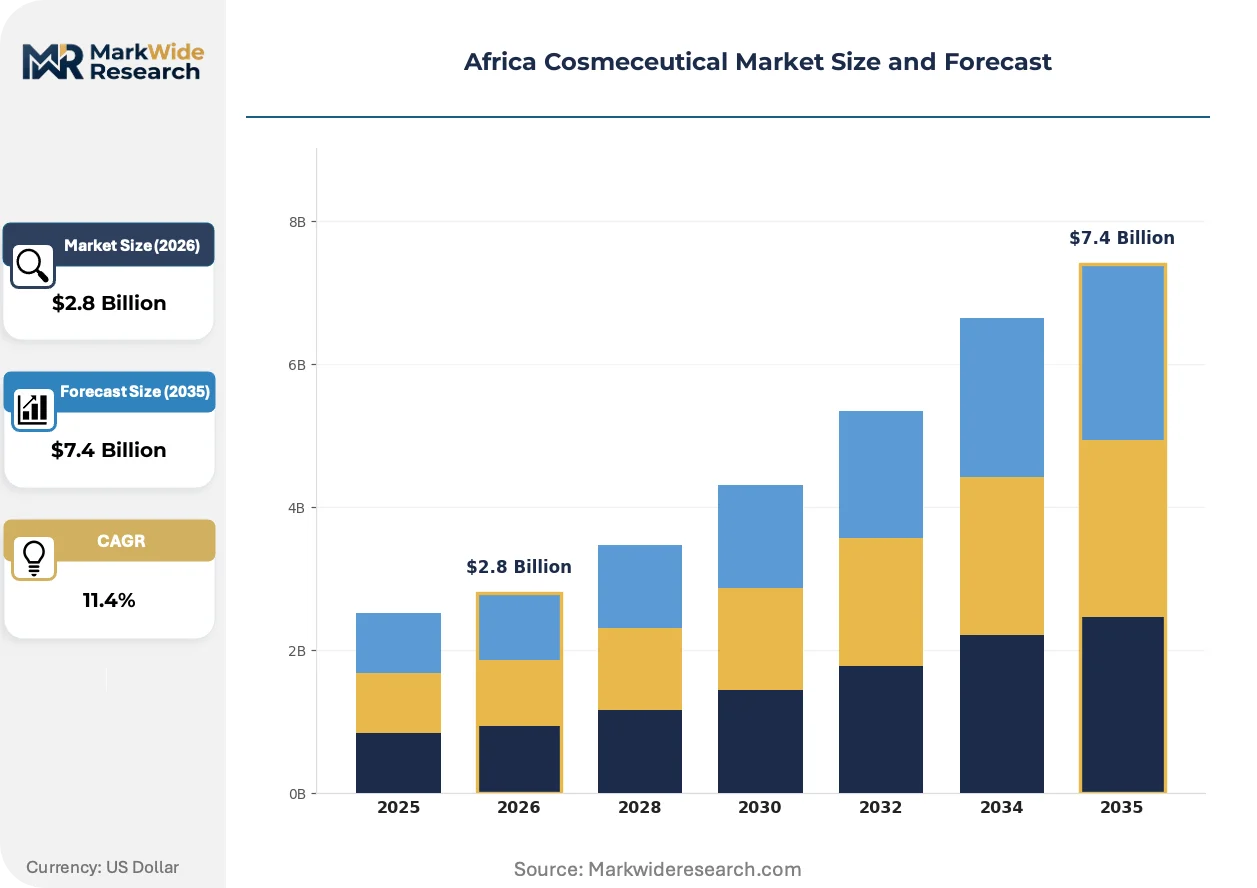
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Anti-Aging, Sun Care Application: Dermatological, Aesthetic, Therapeutic, Preventive End User: Consumers, Salons, Spa Centers, Retailers Distribution Channel: Direct Sales, E-Commerce, Specialty Stores, Pharmacy |
| Companies Covered | L'Oréal SA, Unilever PLC, Procter & Gamble Co., Beiersdorf AG, Johnson & Johnson Inc., Groupe Clarins SA, Ascendis Health Ltd, Amka Products (Pty) Ltd, Godrej Consumer Africa, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Cosmeceutical Market Strategic Shifts
Biotechnology-derived actives and digital diagnostic tools are restructuring how African consumers access personalized skin care, compressing the gap between clinical consultation and over-the-counter purchase.
Peptide-based collagen stimulators are displacing traditional retinoid dominance in premium anti-aging segments. Urban professionals in Johannesburg and Lagos adopt these formulations at accelerating rates through pharmacy channels. This technology shift is compressing the addressable market for established vitamin A derivatives while expanding margin pools for biotech-enabled suppliers.
South Africa's National Regulator for Compulsory Specifications tightened preservative disclosure mandates in 2024. Imported brands must now submit full supply chain documentation for paraben alternatives. The therapeutic application segment faces the steepest compliance burden, with several European suppliers withdrawing SKUs rather than reformulating for sub-scale markets.
Pharmacy staff training programs now incorporate skin condition diagnostics, transforming counter staff into recommendation agents. This channel evolution displaces traditional beauty advisor roles in department stores. Kenya's pharmacy chains lead this behavioral shift, with Nairobi outlets reporting higher attachment rates for regimen bundles than standalone product sales.
Africa Cosmeceutical Market Segmentation
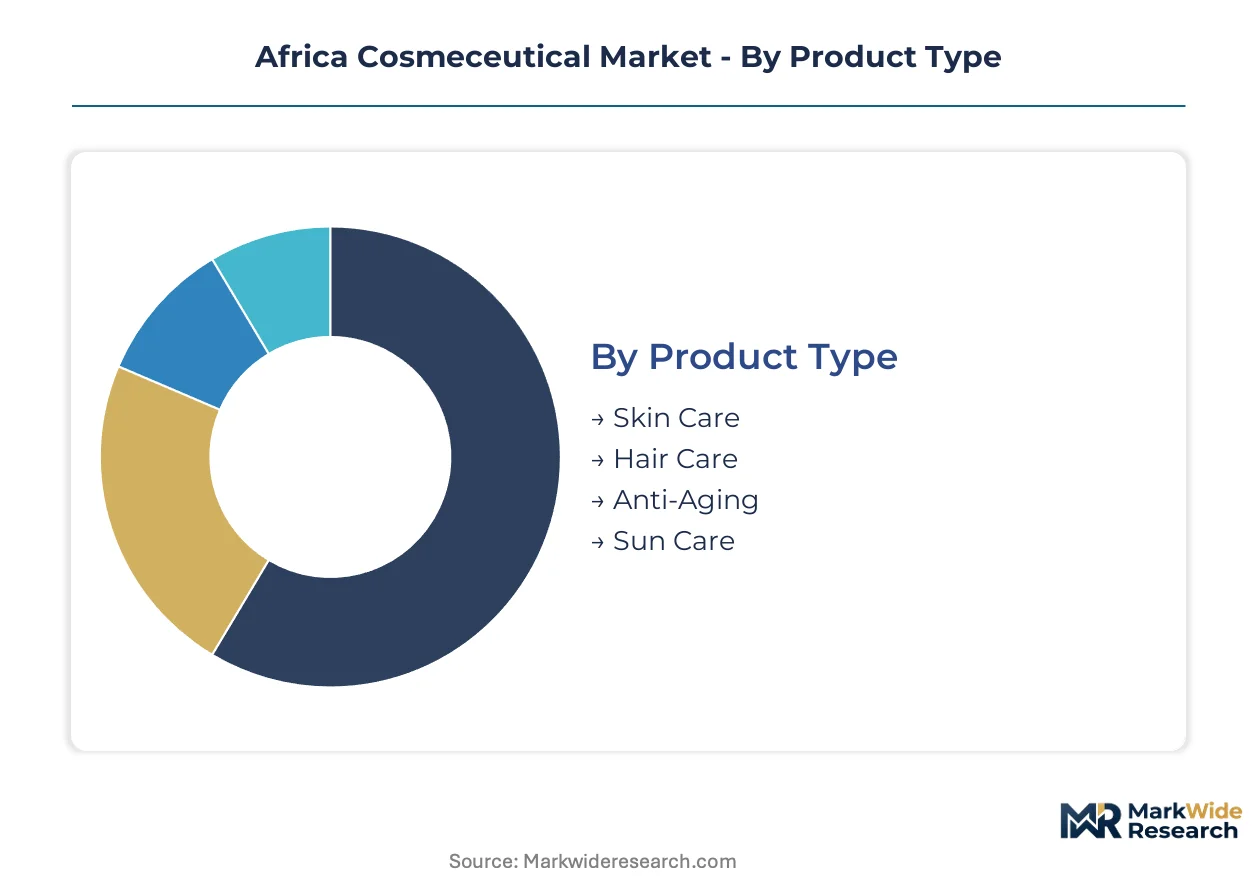
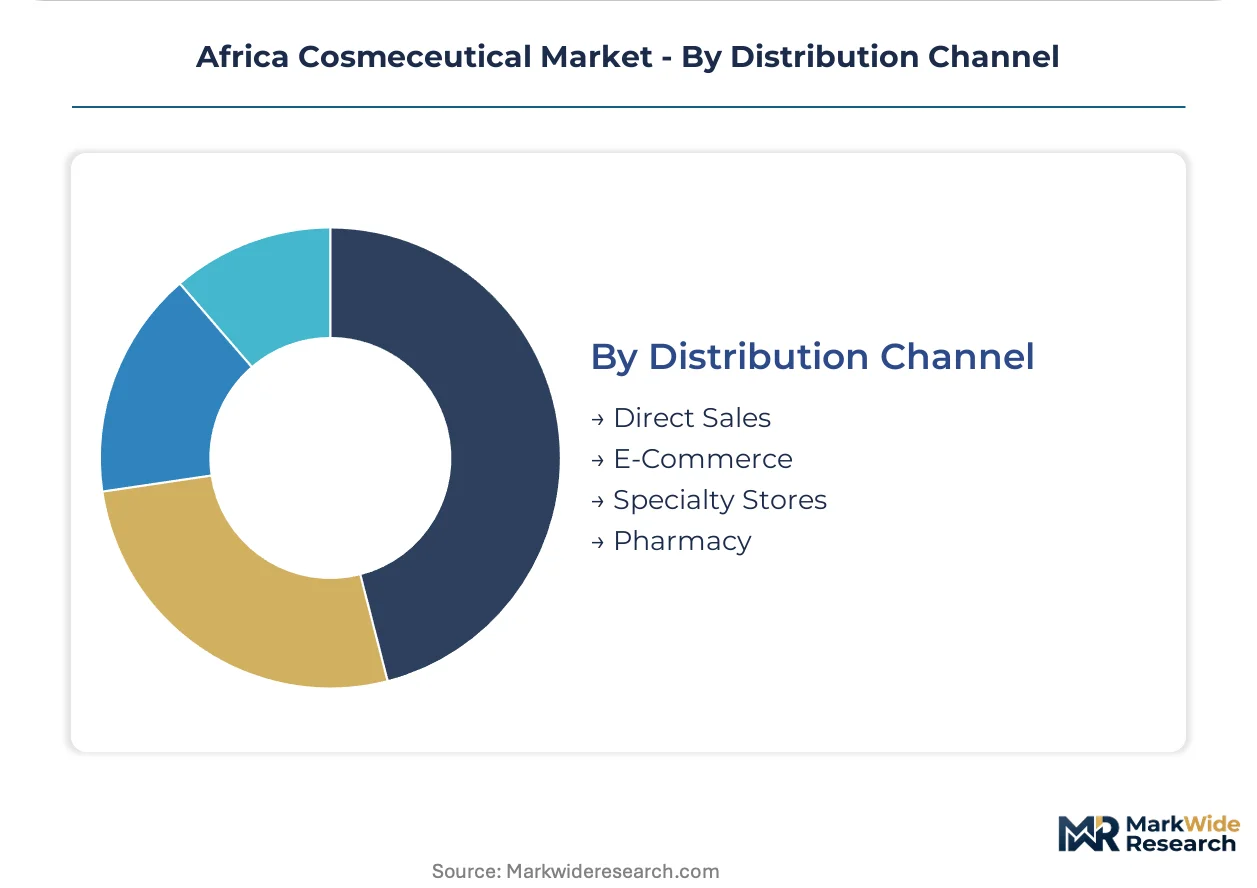
Channel dynamics across Africa's cosmeceutical landscape demand precise segmentation alignment. Pharmacy-led distribution in Kenya and Nigeria rewards therapeutic positioning, while e-commerce acceleration in Lagos and Johannesburg reshapes how product types reach urban millennials.
Product Type:
Pharmacy channels in Morocco and Senegal prioritize skin care and anti-aging formulations with clinical validation, while mass-market retail in Nigeria drives hair care volume through localized manufacturing.
- Skin Care:Topical formulations with biologically active ingredients at therapeutic concentrations, manufactured through cold-process emulsification to preserve peptide integrity. Demand concentrates in Lagos and Nairobi pharmacy networks where urban professionals seek science-backed solutions for hyperpigmentation and barrier repair. Kenya's Pharmacy and Poisons Board inspection protocols favor these clinically positioned products at port of entry.
- Anti-Aging:Peptide-based collagen stimulators and retinoid alternatives targeting cellular renewal. Johannesburg's pharmacy chains report accelerating adoption rates among millennial professionals. South Africa's NRCS preservative disclosure mandates tightened compliance burdens for imported formulations in this premium segment.
- Hair Care:Localized manufacturing in Nigeria reduces import dependency for conditioning and treatment formulations. Unilever PLC anchors competitive position through regional production hubs serving mass-market retail expansion.
- Sun Care:UV protection formulations with antioxidant co-actives, distributed primarily through specialty stores and pharmacy channels in high-altitude markets.
By volume, hair care leads through Nigeria's supermarket chain expansion. By growth pace, anti-aging is climbing the fastest as peptide technology displaces traditional retinoid dominance.
Application:
Cost tiers separate clinic-grade positioning from commodity cosmetics, with therapeutic applications commanding premium pricing through pharmacist endorsement.
- Therapeutic:Condition-specific regimens for eczema, hyperpigmentation, and acne require clinician endorsement and pharmacy staff training. Kenya's pharmacy chains lead this behavioral shift with higher attachment rates for regimen bundles. ECOWAS harmonization standards compress registration timelines while elevating toxicology documentation requirements.
- Dermatological:Physician-directed protocols for diagnosed skin conditions, concentrated in Morocco's upgraded pharmacy channels with trained dermatological staff.
- Aesthetic:Elective enhancement formulations bridging cosmetic and clinical positioning, distributed through spa centers and specialty retailers in Johannesburg and Lagos.
- Preventive:Daily-use formulations targeting environmental damage and premature aging, gaining traction among urban professionals through e-commerce platforms.
Therapeutic applications generate the deepest margin pools due to ingredient complexity and validation requirements. Preventive positioning is expanding most quickly as consumer education shifts from treatment to maintenance.
End User:
Customer type determines channel strategy, with institutional buyers demanding bulk pricing and consumers driving single-unit premium purchases.
- Consumers:Individual purchasers seeking personalized regimens, increasingly reached through biometric skin analysis integration in retail settings. AI-driven diagnostic tools in Nairobi and Lagos outlets lift conversion rates and basket sizes.
- Salons:Professional service providers requiring professional-size formats and staff training support, concentrated in urban centers across Nigeria and South Africa.
- Spa Centers:Premium positioning outlets in Johannesburg and Lagos adopting aesthetic application protocols for elective enhancement services.
- Retailers:Supermarket chains and pharmacy networks upgrading beauty aisle configurations with dedicated cosmeceutical sections.
Consumers dominate absolute transaction volume. Salon procurement is gaining share fastest as professional recommendation influence strengthens.
Distribution Channel:
Supply concentration in South Africa and Egypt shapes how channels access formulation expertise, with port-of-entry inspection protocols favoring established pharmacy networks.
- Pharmacy:Clinician-endorsed distribution with trained staff capable of condition-specific recommendations. Kenya's pharmacy chains report higher attachment rates for regimen bundles than standalone product sales. South Africa's NRCS compliance costs squeeze margin structures for imported brands.
- E-Commerce:Digital platforms serving Lagos and Johannesburg urban millennials with science-backed skin care solutions, bypassing traditional import dependency.
- Specialty Stores:Premium positioning outlets with dedicated beauty advisors, facing displacement as pharmacy staff training programs expand diagnostic capabilities.
- Direct Sales:Consultant-driven distribution remaining relevant in underpenetrated markets where retail infrastructure is limited.
Pharmacy channels lead by revenue per transaction. E-commerce is expanding most quickly as urban professionals prioritize convenience and access to international formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial professionals in Lagos, Nairobi, and Johannesburg concentrate purchasing power for science-backed skin care, with pharmacy-led networks and mass-market retail channels capturing divergent demand profiles across the continent.
Nigeria
Mass-market retail expansion drives volume throughput as supermarket chains upgrade beauty aisles with dedicated cosmeceutical sections. The National Agency for Food and Drug Administration and Control enforces ingredient disclosure thresholds that elevate compliance costs for imported formulations. Lagos anchors distribution hub activity, with localized manufacturing reducing import dependency for hair care formulations.
South Africa
Pharmacy chains report accelerating adoption of peptide-based anti-aging formulations among Johannesburg's professional demographic. The National Regulator for Compulsory Specifications tightened preservative disclosure mandates, forcing reformulation or withdrawal of several European supplier SKUs. Cape Town and Johannesburg concentrate formulation chemist expertise, creating regional R&D gravity.
Kenya
Pharmacy-led distribution networks reward therapeutic positioning with higher attachment rates for regimen bundles than standalone sales. The Pharmacy and Poisons Board inspects cosmeceutical claims at port of entry, extending working capital cycles for distributors. Nairobi outlets lead staff training integration of skin condition diagnostics, transforming counter staff into recommendation agents.
Morocco
Clinic-grade positioning through trained dermatological staff creates premium pricing power for validated formulations. The national pharmaceutical regulator harmonizes documentation requirements with ECOWAS frameworks, compressing cross-border registration timelines. Casablanca pharmacy channels upgrade diagnostic capabilities, displacing traditional beauty advisor roles in department stores.
Senegal
Underpenetrated therapeutic segments for hyperpigmentation and eczema remain underserved relative to basic moisturizers. ECOWAS harmonization standards demand unified toxicology documentation, forcing reformulators to consolidate multi-country dossiers. Dakar pharmacy networks expand condition-specific regimen recommendations, capturing unmet demand through clinician endorsement.
Africa Cosmeceutical Market Competitive Environment
Player mix skews toward multinational consumer goods conglomerates with dermatological research infrastructure and localized manufacturing capabilities. Market structure concentrates around three strategic archetypes: science-backed premium formulators with pharmacy channel dominance, mass-market manufacturers leveraging regional production hubs, and therapeutic specialists dependent on clinician endorsement. Dominant competitive moves include portfolio diversification into biotech-derived actives and geographic expansion through ECOWAS harmonization pathways.
Among the multinational tier, L'Oréal SA and Unilever PLC exemplify divergent positioning strategies, with the former anchoring clinic-grade skin care through pharmacy channels and the latter capturing mass-market volume through localized manufacturing. Ascendis Health Ltd occupies a position within the therapeutic specialist archetype, where clinician endorsement drives repeat purchase behavior in condition-specific segments.
| Leading Market Players |
|---|
| L'Oréal SA |
| Unilever PLC |
| Procter & Gamble Co. |
| Beiersdorf AG |
| Johnson & Johnson Inc. |
| Groupe Clarins SA |
| Ascendis Health Ltd |
| Amka Products (Pty) Ltd |
| Godrej Consumer Africa |
| Others |
Value Chain & Pricing Dynamics
Peptide-based collagen stimulators replacing traditional retinoid formulations in premium anti-aging segments simultaneously concentrates supply geography around South Africa and Egypt's formulation chemist expertise while compressing pricing economics for established vitamin A derivative suppliers. This substitution dynamic elevates margin pools for biotechnology-enabled suppliers while forcing legacy retinoid manufacturers into defensive repositioning across Africa's pharmacy-led distribution networks.
Pricing Analysis
Current-generation peptide formulations command substantial premiums over prior-generation retinoid alternatives, while next-generation biometric-personalized regimens are emerging at the apex. Three-tier pricing structure across clinic-grade therapeutic, standard dermatological, and economy cosmetic tiers separates products by clinical validation depth and pharmacist endorsement intensity. Price differentiation hinges on ECOWAS harmonization compliance status and cold-process manufacturing certification. Cost compression in mass-market hair care intensifies because Unilever's localized Nigerian production eliminates import tariff layers. Mass-market retail buyers exhibit highest price sensitivity, while therapeutic segment purchasers prioritize efficacy validation over unit cost.
Supply Chain Analysis
Strategic stockpiling of temperature-sensitive peptide inventories dominates over just-in-time preferences given Africa's cold-chain infrastructure gaps. Supply concentrates in South Africa, Egypt, and Nigeria, with formulation chemist expertise anchoring regional R&D gravity. Manufacturing draws from imported biotech-derived actives, paraben-alternative preservatives, and specialized emulsification equipment. Single-source vulnerability around European preservative suppliers intensified after South Africa's NRCS tightened disclosure mandates. Distribution runs through pharmacy-led networks in Kenya and Morocco, mass-market retail chains in Nigeria, and accelerating e-commerce platforms in Lagos and Johannesburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through ECOWAS harmonization compliance creates durable defensive moats, as unified toxicology documentation requirements raise fixed-cost barriers that favor incumbents with established multi-country dossier management capabilities.
For Market Incumbents: Compound pharmacy channel control through exclusive staff training partnerships with Kenya's pharmacy chains and Morocco's dermatological networks. Deepen backward integration into peptide manufacturing by acquiring South African cold-process emulsification specialists. Biometric skin analysis entrants threaten recommendation-agent positioning, making AI-diagnostic platform partnerships essential for defending regimen-bundle attachment rates.
For New Entrants and Emerging Players: ECOWAS fast-track certification for condition-specific therapeutic regimens opens immediate access to Senegal's underpenetrated hyperpigmentation and eczema segments. White-space concentration in biometric-personalized preventive formulations for Lagos and Johannesburg urban millennials offers lowest competitive density. Go-to-market execution should anchor in Nairobi pharmacy chain partnerships with diagnostic tool integration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors therapeutic specialists with clinician endorsement networks over commodity cosmetic manufacturers. Long-term viability over the coming decade rests on biotechnology-derived active pipelines and ECOWAS regulatory affairs capabilities. Acquisition target archetype: mid-cap formulators with validated peptide stability expertise and existing pharmacy channel relationships. Signal to watch is biometric diagnostic tool adoption rates in retail settings as inflection indicator for personalized regimen market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Staff Training Partnership | Kenya's Pharmacy and Poisons Board inspection protocols favor clinically positioned products with trained recommendation agents. |
| Backward Integration into Peptide Manufacturing | South Africa's NRCS preservative disclosure mandates favor in-house cold-process emulsification capabilities over imported formulations. |
| ECOWAS Harmonization Dossier Consolidation | Unified toxicology documentation across member states compresses registration timelines for multi-country market access. |
| Biometric Skin Analysis Platform Launch | AI-driven diagnostic tools in Lagos and Nairobi retail settings lift conversion rates and basket sizes for personalized regimens. |
| Therapeutic Segment Certification Investment | Clinician endorsement for condition-specific regimens generates deepest margin pools in Senegal's underpenetrated eczema and hyperpigmentation markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association reports. Primary interviews engaged formulation chemists, pharmacy chain procurement directors, regulatory affairs specialists at ECOWAS national agencies, and dermatology clinic operators. Secondary validation drew from South Africa's NRCS disclosure mandates, Kenya's Pharmacy and Poisons Board inspection protocols, ECOWAS harmonization framework documentation, and customs records of cosmeceutical imports. Bottom-up demand modeling across product types and applications triangulated against top-down market sizing through distribution channel throughput analysis.
Segmentation dimensions modeled include product type hierarchy, application tier positioning, end-user archetype, and distribution channel structure across the analysis window. CAGRs derived from regression analysis of historical throughput data and forward projection of urban millennial demand saturation. Industry-specific forecast inputs incorporated pharmacy staff training program rollout schedules and biometric diagnostic tool adoption curves in key metropolitan markets.
The analysis sits within stated boundaries; outcomes outside sustained ECOWAS harmonization implementation or cold-chain infrastructure investment trajectories would require recalibration. Forecasts reflect assumptions around peptide stability technology maturation and regulatory enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Facial Skincare Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Skin Care Supplements Market
Skincare
Exfoliators and Scrubs Market
Skincare
Preoperative Skin Preparation Market
Skincare
Biocellulose Mask Market
Skincare
Global Anti-Aging Market
Skincare
Skin Grafting System Market
Skincare
Pseudo Collagen Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
CBD Skincare Products Market
Skincare
Self-Tanning Care Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Skincare Cdmo and Cmo Market